
 Carbolic Oil Market | 2026-2036
Carbolic Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Carbolic Oil Market Analysis
Refined phenolic grade specifications is redrawing procurement priorities across downstream sectors. NalonChem leverages captive coking operations to sustain feedstock cost advantages in European phenol derivatives. Koppers dominates North American tar distillation capacity, while Rain Industries Limited anchors South Asian carbon chemicals supply through integrated refinery links.
Carbolic oil is a coal-tar distillate fraction rich in phenol, cresol, and xylenol isomers, typically recovered between 180°C and 230°C during high-temperature carbonization of bituminous coal; it serves as the primary feedstock for synthetic phenol extraction and wood preservative formulations. The disinfectants application segment leads volume absorption as healthcare sanitation protocols harden, whereas phenolic compounds command the widest margin pool due to pharmaceutical-grade certification requirements. Hydrocarbon solvents face slower expansion as water-based adhesive formulations gain share in coatings manufacturing.
EPA registration mandates govern biocidal phenol derivatives in the United States, while REACH Annex XVII restrictions limit cresol concentrations in consumer-grade disinfectants across Europe. India's BIS certification for industrial phenol purity and China's GB standards for coal-chemical emissions collectively raise compliance costs for non-integrated producers. Stakeholders must track regulatory divergence between pharmaceutical-grade and industrial-grade specification thresholds to align capacity investments with enforceable demand tiers.
Market Dynamics
REACH Annex XVII restrictions on cresol concentrations and EPA registration mandates for biocidal phenol derivatives are forcing integrated producers to bifurcate capacity between pharmaceutical-grade and industrial-grade output streams, reshaping capital allocation across coal-tar distillation networks.
Growth Catalysts
- Healthcare sanitation protocols:Hospital-grade disinfectant formulations are absorbing higher volumes of refined phenolic fractions as infection control standards tighten in tertiary care facilities across India and China.
- REACH compliance tiering:European phenolic compound exports face purity specification escalations that favor integrated refiners with captive coking operations, concentrating procurement among certified suppliers.
- Specialty chemical manufacturing clusters:Gujarat and Shandong provinces are anchoring downstream phenol derivative capacity, creating localized feedstock pull for high-purity carbolic oil fractions.
Market Restraints
- Bituminous coal feedstock volatility:Coking coal price swings directly compress margins for non-integrated tar distillers lacking captive mine-to-oven supply chains.
- European supply concentration:Tar distillation capacity clusters in Germany and Poland create geographic vulnerability to energy cost shocks and carbon border adjustment mechanisms.
- Bio-based phenol substitution:Lignin-derived phenolic platforms are displacing coal-tar feedstocks in selected wood preservative applications where performance specifications permit.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO certification requirements for active pharmaceutical ingredient precursors create demand for GMP-grade phenol derivatives from domestic tar distillation investments.
- Water-based adhesive formulation convergence:Coatings manufacturers combining phenolic tackifiers with low-VOC resin systems are opening specification windows for modified cresol fractions.
- China GB standard alignment:MEE emissions enforcement for coal-chemical complexes is accelerating consolidation toward integrated refiners with flue-gas treatment capabilities.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA validation protocols for phenol derivative excipients extend qualification cycles to 18-24 months, freezing capacity decisions.
- Legacy distillation asset retrofit costs:Continuous versus batch processing upgrades for REACH-compliant fractionation demand capital commitments that mid-scale operators cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbolic Oil Market |
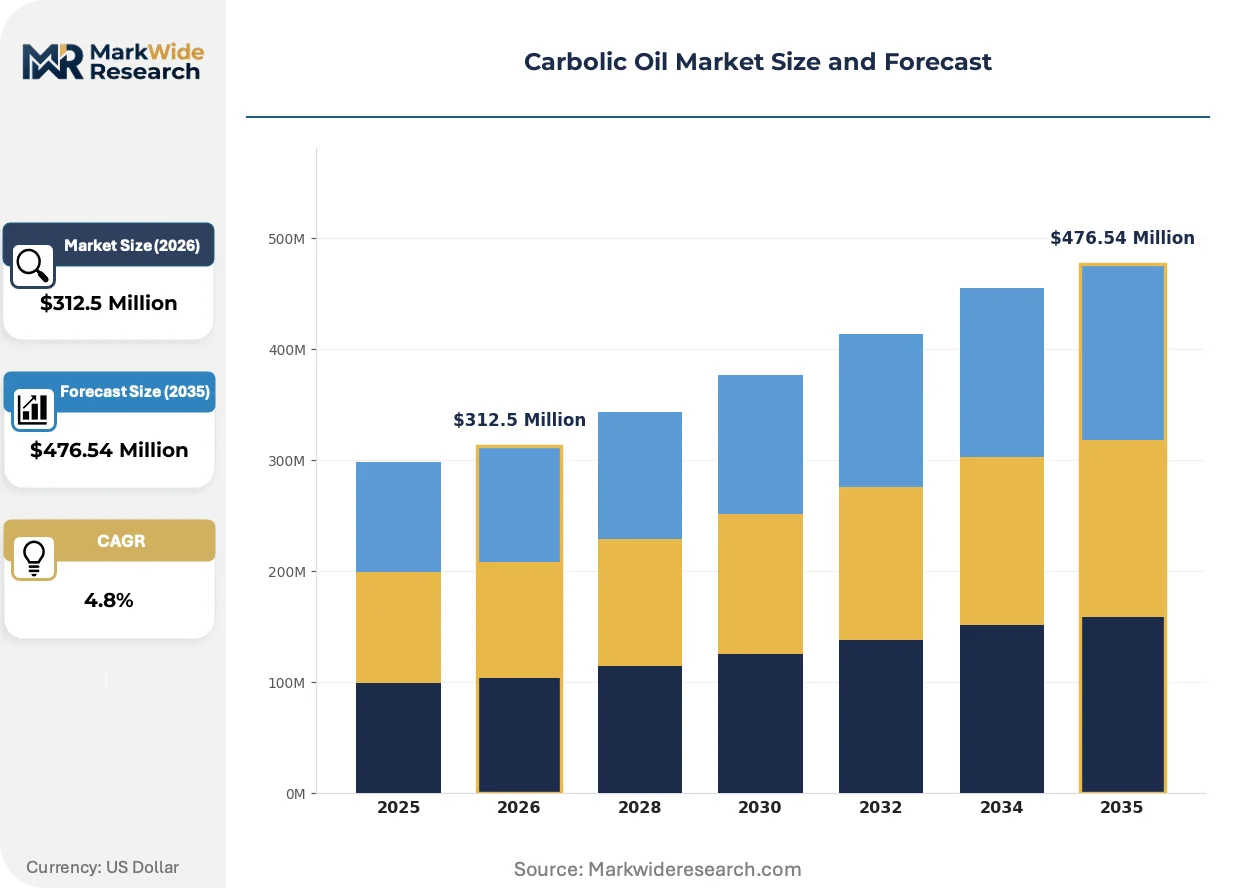
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenolic Compounds, Hydrocarbon Solvents, Biocides, Industrial Chemicals Application: Disinfectants, Pesticides, Adhesives, Coatings End User: Agriculture, Healthcare, Manufacturing, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | NalonChem, DEZA a. s., Jining Carbon Group, Shandong Gude Chemical, Elkem ASA, KUMHO P&B CHEMICALS, Rain Industries Limited, Industrial Química del Nalón, Koppers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbolic Oil Market Emerging Trajectories
Coal-tar distillation technology is fragmenting across multiple purification pathways as regulatory thresholds diverge between pharmaceutical and industrial applications, forcing equipment suppliers to modularize fractionation train designs.
Membrane separation technology for phenol-cresol-xylenol fractionation is fragmenting the traditional atmospheric distillation paradigm. Specialty chemical producers in the Netherlands and Belgium are piloting ceramic nanofiltration modules that reduce energy intensity by half while hitting 99.5% purity targets. This capability compression is enabling smaller-scale distributed production near downstream formulation plants.
ECHA's 2023-2024 REACH restriction proposals on coal-tar pitch and related substances are triggering anticipatory reformulation across European wood preservative manufacturers. Industrial coating applicators are accelerating qualification of alternative biocide carriers to preempt supply interruption. German and Austrian rail tie treatment facilities are diversifying feedstock sourcing to Baltic and Ukrainian tar distillers ahead of enforcement timelines.
Specification-driven procurement consolidation is compressing supplier lists among disinfectant formulators. Large hospital purchasing cooperatives in the United States and France are mandating ISO 17025-certified phenol derivative documentation, disqualifying spot-market traders. This behavior shift is most visible in North American group purchasing organization contracts, where three-year sole-source agreements now predominate for high-purity cresol fractions.
Carbolic Oil Market Segmentation
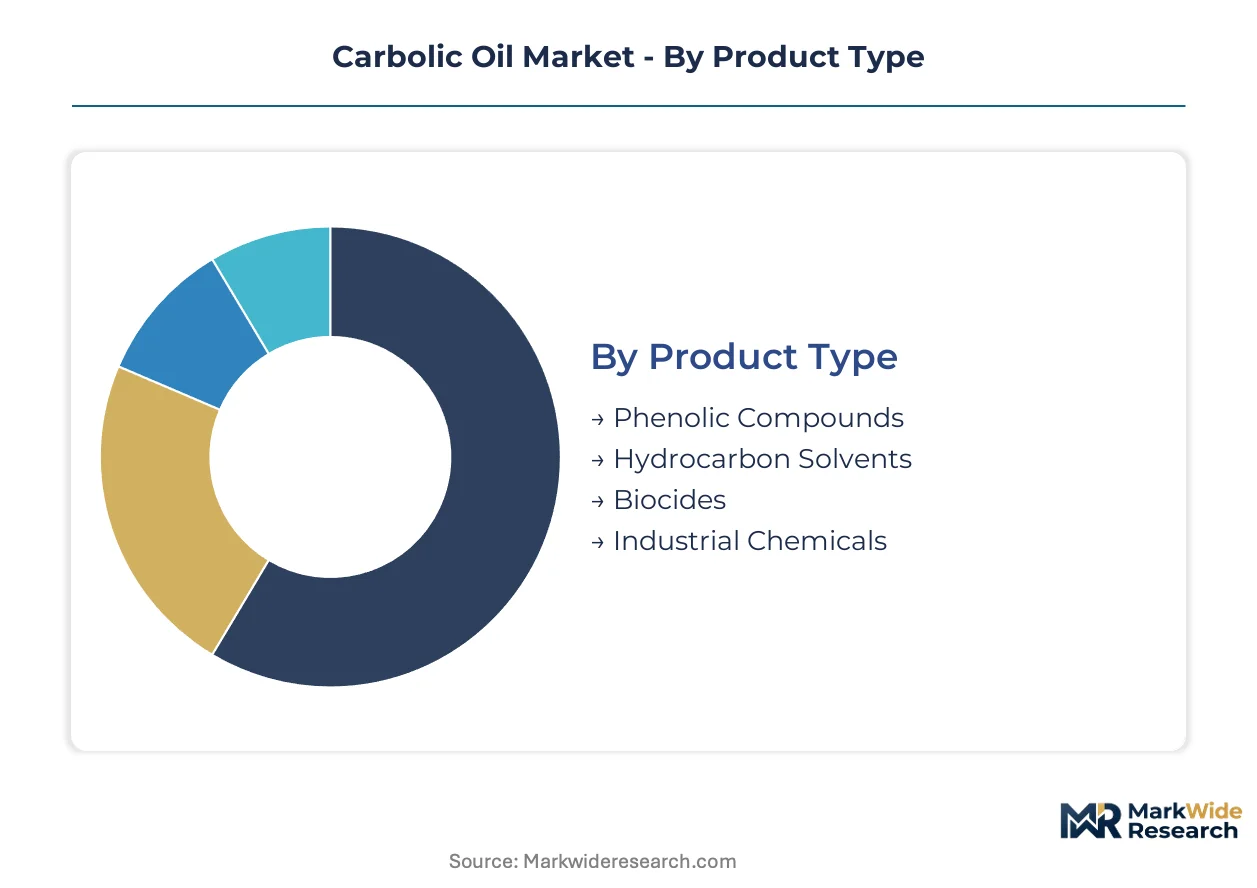
Carbolic oil procurement patterns fragment sharply across purity grades and regulatory jurisdictions. Pharmaceutical certification requirements and industrial solvent specifications create parallel demand tracks that rarely intersect, forcing producers to dedicate discrete distillation trains to each tier.
Product Type:
Phenolic compounds dominate export flows to regulated pharmaceutical markets, while hydrocarbon solvents serve largely domestic industrial coatings demand. Biocides and industrial chemicals occupy intermediate positions with mixed geographic reach.
- Phenolic Compounds:These refined fractions containing phenol, cresol, and xylenol isomers meet USP and EP monograph specifications for pharmaceutical excipient use. Hospital-grade disinfectant manufacturers in India and China absorb rising volumes as CDSCO and NMPA tighten active ingredient documentation requirements.
- Hydrocarbon Solvents:Lower-boiling tar distillate fractions serve industrial degreasing and extraction applications where purity thresholds remain less stringent. Coatings formulators in Germany and Poland leverage these materials for phenolic resin synthesis, though water-based adhesive substitution is compressing growth in legacy solvent applications.
- Biocides:EPA-registered phenol derivatives for wood preservation and agricultural sanitation face REACH Annex XVII cresol concentration caps in European consumer markets.
- Industrial Chemicals:Broad-spectrum tar acid mixtures supply foundry resins and carbon black feedstocks with minimal fractionation.
Phenolic compounds hold the largest share; momentum sits with biocides as ECHA restriction timelines accelerate anticipatory stockpiling.
Application:
Volume concentration varies by end-use certification burden, with pharmaceutical-grade disinfectants commanding price premiums that justify dedicated supply chains.
- Disinfectants:Hospital procurement cooperatives in France and the United States mandate ISO 17025-certified phenol derivative documentation, disqualifying spot-market traders. Tertiary care facility expansion across Gujarat and Maharashtra is absorbing higher volumes of refined cresol fractions.
- Pesticides:Agricultural phenol-based biocides face EPA registration renewal cycles and EU PPP regulation compliance costs that favor established formulators with regulatory affairs capacity.
- Adhesives:Phenolic tackifiers for plywood and engineered wood products concentrate demand in Shandong province furniture manufacturing clusters.
- Coatings:Low-VOC resin systems are displacing traditional phenolic solvents in European automotive and industrial coating applications.
Disinfectants command the dominant revenue position; adhesives are climbing fastest as Asian construction activity sustains plywood demand.
End User:
Customer concentration patterns reflect divergent procurement sophistication, with pharmaceutical and healthcare buyers imposing qualification protocols that industrial manufacturers rarely match.
- Healthcare:Infection control protocol hardening in tertiary care facilities drives specification-grade phenol derivative absorption. Group purchasing organizations in North America now lock three-year sole-source agreements for high-purity cresol supplies.
- Pharmaceuticals:Active pharmaceutical ingredient precursor demand requires GMP-grade phenol derivatives with FDA and EMA validation protocols extending qualification cycles to 18-24 months.
- Agriculture:Wood preservative and biocide applications face lignin-derived phenolic substitution pressure where performance specifications permit flexibility.
- Manufacturing:Foundry resins and carbon materials supply industrial phenol users with lower purity thresholds and spot-market purchasing behavior.
Healthcare absorbs the greatest volume; pharmaceuticals show the steepest margin expansion as certification barriers concentrate supply among qualified refiners.
Distribution Channel:
Channel selection tracks customer scale and specification stringency, with certified pharmaceutical-grade materials bypassing intermediaries entirely.
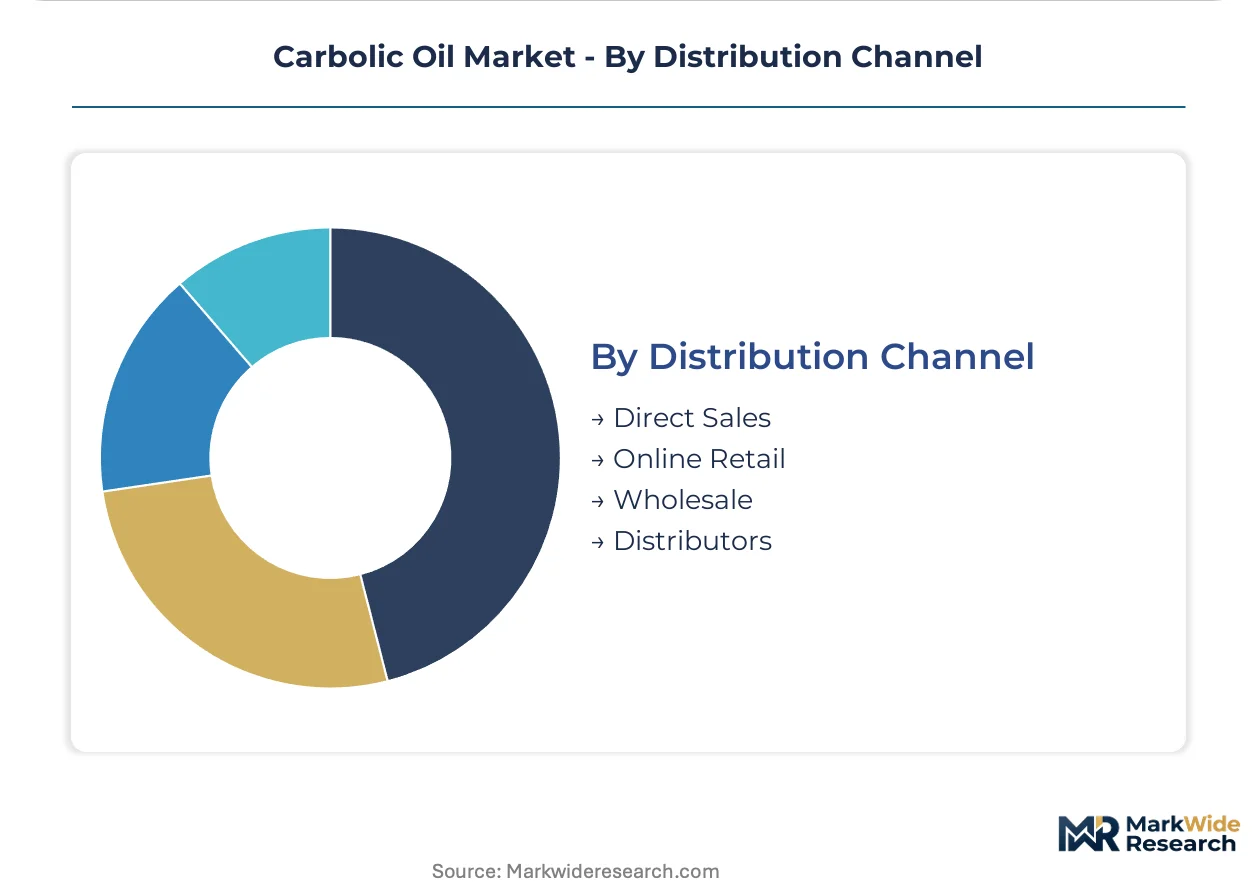
- Direct Sales:Integrated tar distillers with captive coking operations supply hospital purchasing cooperatives and pharmaceutical manufacturers under long-term offtake agreements with embedded certification documentation.
- Distributors:Regional chemical distributors hold inventory positions for industrial-grade phenolic compounds and hydrocarbon solvents serving mid-scale coatings and adhesives formulators.
- Wholesale:Bulk terminal operators aggregate spot-market volumes for foundry resins and carbon black feedstocks with minimal specification differentiation.
- Online Retail:Limited to small-volume laboratory reagents and specialty biocide formulations with established safety documentation.
Direct sales capture the premium tier; distributors handle the greatest transaction volume across fragmented industrial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tar distillers export refined phenolic fractions to French and Dutch pharmaceutical formulators under REACH-certified documentation chains. This trade corridor concentrates high-purity carbolic oil flows toward European healthcare manufacturing clusters.
United States
Hospital purchasing cooperatives absorb specification-grade cresol fractions for disinfectant manufacturing. EPA registration mandates for biocidal phenol derivatives extend qualification timelines for new suppliers. The Gulf Coast petrochemical corridor hosts carbon black producers drawing industrial phenol feedstocks.
Germany
Integrated coking operations sustain captive feedstock supply for phenol derivative refiners serving pharmaceutical excipient markets. ECHA REACH Annex XVII restrictions on cresol concentrations force capacity bifurcation between pharmaceutical-grade and industrial-grade output streams. The Ruhr industrial region anchors tar distillation capacity with flue-gas treatment capabilities.
China
Shandong province furniture manufacturing clusters drive phenolic tackifier demand for plywood adhesives. MEE emissions enforcement for coal-chemical complexes accelerates consolidation toward integrated refiners with environmental compliance infrastructure. The Yangtze River Delta concentrates downstream phenol derivative capacity for export-oriented specialty chemical production.
India
Tertiary care facility expansion across Gujarat and Maharashtra absorbs rising volumes of refined cresol fractions for hospital-grade disinfectants. CDSCO certification requirements for active pharmaceutical ingredient precursors create demand for GMP-grade phenol derivatives. The Gujarat specialty chemical manufacturing cluster anchors domestic tar distillation investments.
Poland
Wood preservative formulators source tar acid mixtures for rail tie treatment applications facing ECHA restriction timelines. Carbon border adjustment mechanisms threaten export competitiveness of coal-tar derived biocides. The Upper Silesian industrial region hosts legacy distillation assets serving Central European foundry resin markets.
Carbolic Oil Market Vendor Landscape
Listed leaders compete with private specialists across integrated versus non-integrated business models. The vendor base concentrates among tar distillers with captive coking operations and standalone fractionators dependent on spot feedstock markets. Three archetypes dominate: integrated carbon chemical conglomerates with mine-to-oven supply chains, regional tar distillers serving industrial coatings demand, and pharmaceutical-grade phenol specialists with regulatory affairs capacity. Competitive moves center on backward integration into coking capacity and portfolio diversification toward high-purity pharmaceutical excipients.
Within the integrated conglomerate tier, Rain Industries Limited and Koppers exemplify scale-driven positions anchored by refinery linkages and North American tar distillation networks respectively. NalonChem occupies a position among European specialists leveraging captive coking operations for feedstock cost advantages. These three entities represent the competitive spectrum from global carbon chemical platforms to regional phenol derivative refiners.
| Leading Market Players |
|---|
| NalonChem |
| DEZA a. s. |
| Jining Carbon Group |
| Shandong Gude Chemical |
| Elkem ASA |
| KUMHO P&B CHEMICALS |
| Rain Industries Limited |
| Industrial Química del Nalón |
| Koppers |
| Others |
Supply Flow & Price Mechanics
Lignin-derived phenolic platforms displacing coal-tar feedstocks in wood preservative applications are simultaneously fragmenting supply geography toward Nordic biorefinery zones and compressing pricing power in legacy industrial-grade carbolic oil tiers. This substitution dynamic forces integrated tar distillers to defend pharmaceutical-grade premiums while ceding ground on commodity biocide contracts.
Pricing Analysis
Atmospheric distillation versus membrane separation technology creates a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade phenolic compounds with USP and EP certification command substantial premiums over industrial-grade tar acid mixtures, with price differentiation driven by FDA validation timelines and REACH Annex XVII compliance documentation. Cost compression in standard-grade cresol fractions is intensifying because European wood preservative formulators are accelerating lignin-based alternatives ahead of ECHA restriction enforcement. Hospital purchasing cooperatives show the least price sensitivity due to three-year sole-source mandates, while spot-market traders in foundry resin applications face acute margin pressure.
Supply Chain Analysis
Germany and Poland anchor European tar distillation capacity with integrated coking operations, while India and China concentrate downstream phenol derivative manufacturing for pharmaceutical and adhesive applications. Feedstock supply draws from bituminous coal carbonization in the Ruhr and Upper Silesian industrial regions, with phenol-cresol-xylenol fractionation equipment sourced from specialized Dutch and Belgian engineering firms. Single-source vulnerability concentrates around German tar distillers exporting REACH-certified fractions to French pharmaceutical formulators. Distribution runs through direct long-term offtake agreements for certified grades and regional chemical distributors for industrial solvents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate lignin-derived phenolic substitution eroding wood preservative market share while defending pharmaceutical-grade certification barriers against emerging biorefinery competitors.
For Market Incumbents: Secure captive coking capacity in India and China to lock in feedstock cost advantages against volatile bituminous coal spot markets. Accelerate CDSCO and NMPA certification investments to preempt domestic pharmaceutical-grade phenol derivative demand from integrated biorefinery entrants. Backward integration into mine-to-oven supply chains remains the critical defensive lever against margin compression in industrial-grade tiers. For New Entrants and Emerging Players: CDSCO fast-track certification for active pharmaceutical ingredient precursors offers the most penetrable entry path into Gujarat's specialty chemical manufacturing cluster. Target water-based adhesive formulation partnerships in Shandong province furniture manufacturing, where phenolic tackifier specifications remain less stringent than pharmaceutical grades. A go-to-market angle emphasizing ceramic nanofiltration purity advantages over legacy atmospheric distillation can differentiate technical offerings to coatings formulators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European tar distillers lacking flue-gas treatment capabilities to meet tightening MEE and REACH emissions enforcement. Long-term viability over the coming decade hinges on pharmaceutical-grade certification depth rather than industrial-scale volume positioning. The signal to watch is CDSCO validation protocol completion rates among mid-scale Indian producers, indicating consolidation timing toward qualified domestic suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coking Capacity | Captive bituminous coal supply secures margin defense against feedstock volatility in European and Asian markets. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA validation protocols extend qualification moats against lignin-derived phenolic substitutes in excipient markets. |
| Membrane Separation Technology Adoption | Ceramic nanofiltration modules reduce energy intensity while hitting purity targets for distributed production near downstream plants. |
| Joint Venture with Domestic Pharmaceutical Manufacturers | CDSCO-aligned partnerships in Gujarat anchor long-term offtake for GMP-grade phenol derivatives in India's expanding API sector. |
| Long-term Supply Agreement with Hospital Purchasing Cooperatives | Three-year sole-source contracts with North American GPOs lock in volume commitments for high-purity cresol fractions. |
Methodological Framework
A spread of perspectives from tar distillation plant managers, pharmaceutical procurement leads at hospital purchasing cooperatives, coatings formulators in Shandong and Gujarat, and regulatory affairs specialists at ECHA and CDSCO converged on the working assumptions. Primary interview insights combined with secondary validation from customs trade data, SEC filings of listed carbon chemical producers, BIS and GB standards documentation, and REACH Annex XVII restriction proposals. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates across the analysis window.
Segmentation dimensions modeled include phenolic compound grade tier, end-use application across disinfectants and adhesives, distribution channel structure, and regional production hub concentration. CAGRs were derived from demand elasticity analysis against healthcare sanitation protocol expansion and pharmaceutical manufacturing growth trajectories. Forecast inputs incorporated ECHA restriction timeline acceleration, MEE emissions enforcement intensity, and CDSCO certification queue progression rates.
Underlying assumptions cover sustained bituminous coal coking economics, REACH compliance tier stability, and pharmaceutical-grade specification divergence from industrial grades, with deviation risk concentrated in lignin-derived phenolic substitution pace and carbon border adjustment mechanism implementation. Recalibration cycles align with material shifts in ECHA enforcement timelines, CDSCO validation protocol changes, and MEE emissions inspection intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Europe Wax Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
White Mineral Oil Market
Oleochemicals
Squalane Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Isooctyl Chloride Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Higher Olefins Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Oily Waste Cans Market
Oleochemicals
Estolides Market