
 Medium-Chain Triglycerides (MCT) Powder Market | 2026-2036
Medium-Chain Triglycerides (MCT) Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Medium-Chain Triglycerides (MCT) Powder Market Insights
Southeast Asia is fragmenting as Indonesia and Malaysia expand fractionation capacity for lauric-rich feedstocks. Stepan Company leverages backward integration into coconut oil supply chains to secure feedstock access. BASF SE sustains R&D intensity in microencapsulation technology for powder stability. Croda International Plc anchors European pharmaceutical-grade production with lipid chemistry expertise.
Medium-chain triglycerides are lipids composed of fatty acids with six to twelve carbon atoms, typically manufactured through esterification of glycerol with fractionated coconut or palm kernel oils, then spray-dried into powder form using carrier matrices like maltodextrin or gum arabic for enhanced dispersibility in beverages and dry mixes. The powder format dominates commercial volumes due to superior shelf stability and convenience in sports nutrition formulations. Medical nutrition applications lead margin pools as clinical validation requirements create formulation barriers. Keto diet positioning competes on consumer education intensity rather than ingredient differentiation alone.
FDA GRAS status and EFSA novel food assessments shape ingredient approval pathways for new MCT sources, while FSSAI in India enforces labeling standards for ayurvedic-positioned MCT products entering health food channels. Stakeholders must monitor evolving carrier system regulations as clean-label preferences pressure maltodextrin replacement with fiber-based alternatives.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing carrier system choices, forcing maltodextrin replacement with fiber-based alternatives and reshaping powder stability specifications across sports nutrition and medical applications.
Growth Catalysts
- Sports Nutrition Demand:Fitness centers and dietary supplement brands in the United States, Germany, and China are expanding MCT powder inclusion in pre-workout and recovery formulations, driven by ketogenic diet positioning and metabolic efficiency claims.
- EFSA Novel Food Pathways:Streamlined approval assessments for new MCT sources from alternative feedstocks are accelerating ingredient innovation timelines and reducing market entry barriers for fractionated lipid processors.
- Microencapsulation Advances:Enhanced spray-drying technologies using gum arabic and modified starch carriers are improving powder dispersibility in ready-to-drink beverages and dry mix applications.
Market Restraints
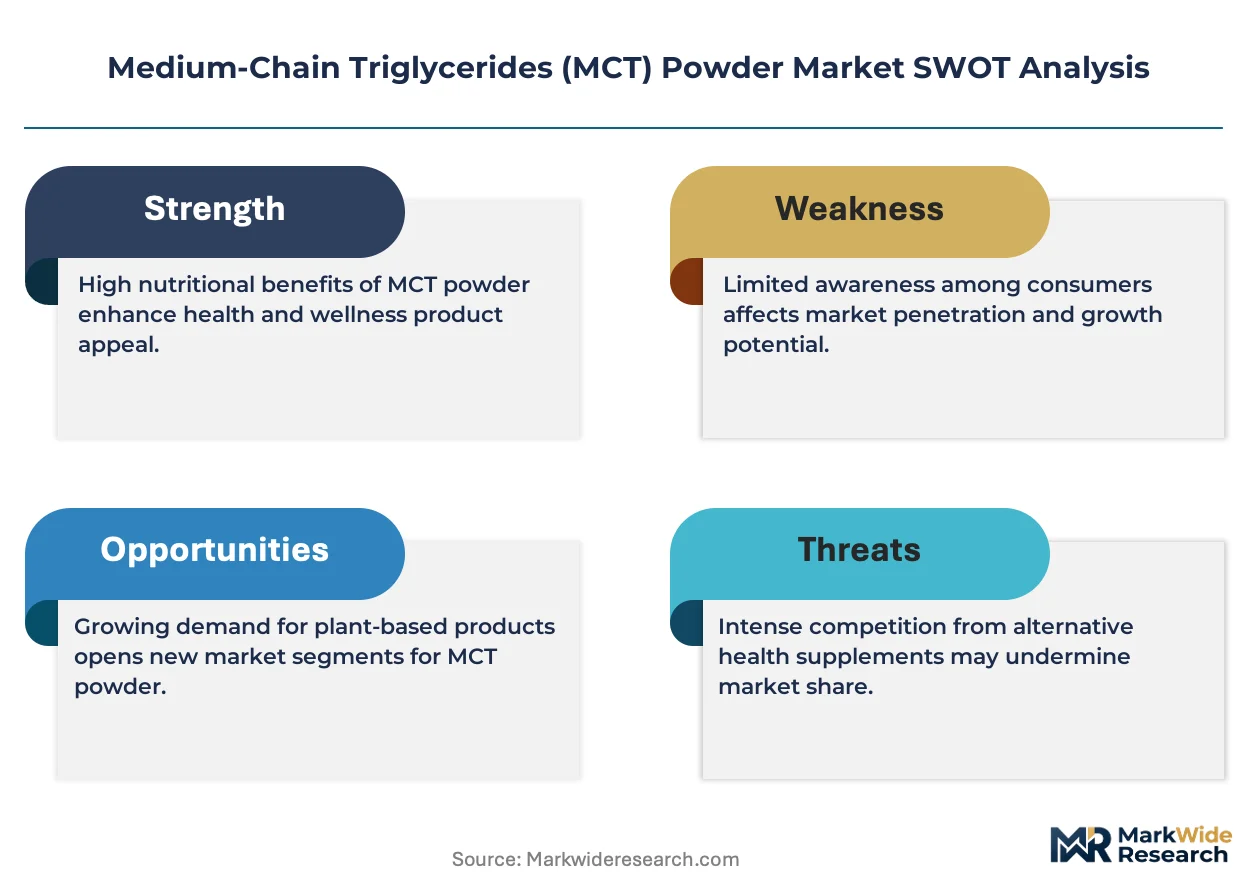
- Coconut Oil Price Volatility:Lauric-rich feedstock costs fluctuate with Indonesian and Malaysian fractionation capacity expansions, squeezing margin pools for non-integrated processors.
- Regulatory Fragmentation:FSSAI labeling standards for ayurvedic-positioned MCT products in India create compliance complexity for brands targeting health food channels with unified global formulations.
- Plant Protein Substitution:Pea and rice protein isolates with added medium-chain fatty acids are capturing functional food positioning in clean-label segments, pressuring pure MCT powder volumes.
Strategic Opportunities
- Medical Nutrition White Space:Clinical validation requirements for pharmaceutical-grade MCT production create formulation barriers that reward lipid chemistry expertise with premium margin structures.
- Southeast Asian Supply Expansion:Indonesia and Malaysia are building fractionation infrastructure that could rebalance feedstock access for European and North American powder manufacturers.
- FDA GRAS Tailwinds:Self-affirmed GRAS status for novel MCT sources enables faster commercialization than full food additive petitions, accelerating product pipeline velocity.
Industry Challenges
- Clean-Label Reformulation Complexity:Replacing maltodextrin with fiber-based carriers requires reformulation of shelf stability protocols and sensory profiles, extending development cycles.
- Clinical Validation Timelines:Medical nutrition applications demand extensive efficacy documentation for hospital and institutional procurement, compressing cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium-Chain Triglycerides (MCT) Powder Market |
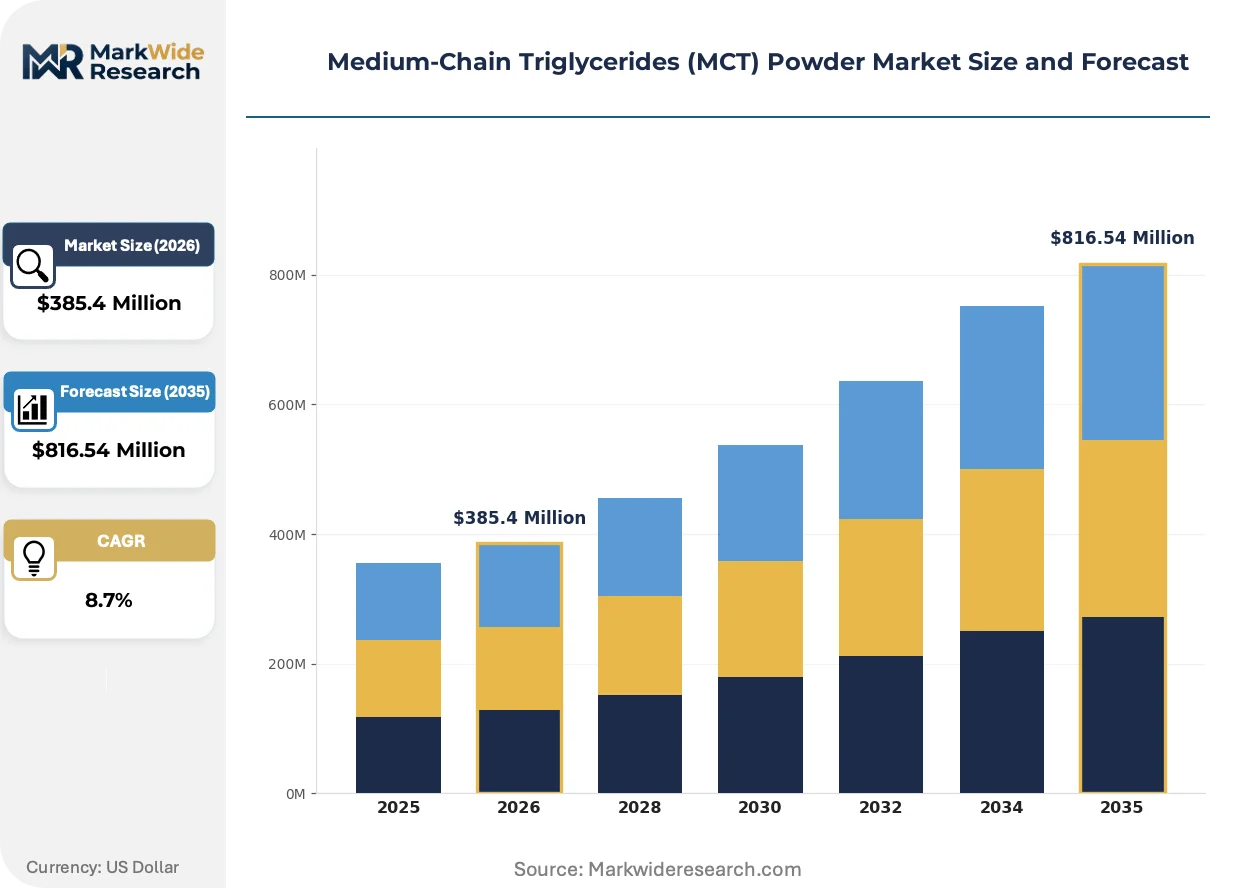
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Organic, Non-Organic End User: Nutraceutical Companies, Food Manufacturers, Dietary Supplement Brands, Fitness Centers Application: Sports Nutrition, Weight Management, Medical Nutrition, Keto Diet Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Stepan Company, Koninklijke DSM N.V., ABITEC Corporation, Croda International Plc, Lonza Group Ltd, BASF SE, Wilmar International, DuPont de Nemours Inc., Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium-Chain Triglycerides (MCT) Powder Market Trends and Innovations
Carrier system innovation and regulatory pressure on formulation transparency are converging to redefine powder stability standards and procurement criteria across functional food and clinical nutrition segments.
Lipid-based microencapsulation using modified starch and gum arabic matrices is rendering obsolete conventional maltodextrin-dominant carrier systems in premium sports nutrition powders. Formulators at dietary supplement brands are adopting these alternatives within eighteen-month procurement cycles. The shift is compressing supplier margins for legacy carrier producers while rewarding backward-integrated fractionators with captive gum arabic supply.
EFSA novel food assessments and FDA GRAS self-affirmation pathways are tightening documentation requirements for new MCT feedstock sources entering European and North American markets. Manufacturers must now submit comprehensive toxicology and exposure data before commercial launch, extending pre-market timelines. Pharmaceutical-grade producers with existing lipid chemistry expertise are capturing disproportionate share of approved novel source introductions.
Direct-to-consumer subscription models for ketogenic dietary supplements are displacing traditional retail pharmacy and mass-market grocery distribution for MCT powder. Brands are unbundling bulk container sales into personalized dosing protocols with recurring replenishment. This pattern concentrates in the United States and Germany, where consumer education intensity around metabolic health supports premium pricing for convenience-positioned offerings.
Medium-Chain Triglycerides (MCT) Powder Market Segmentation
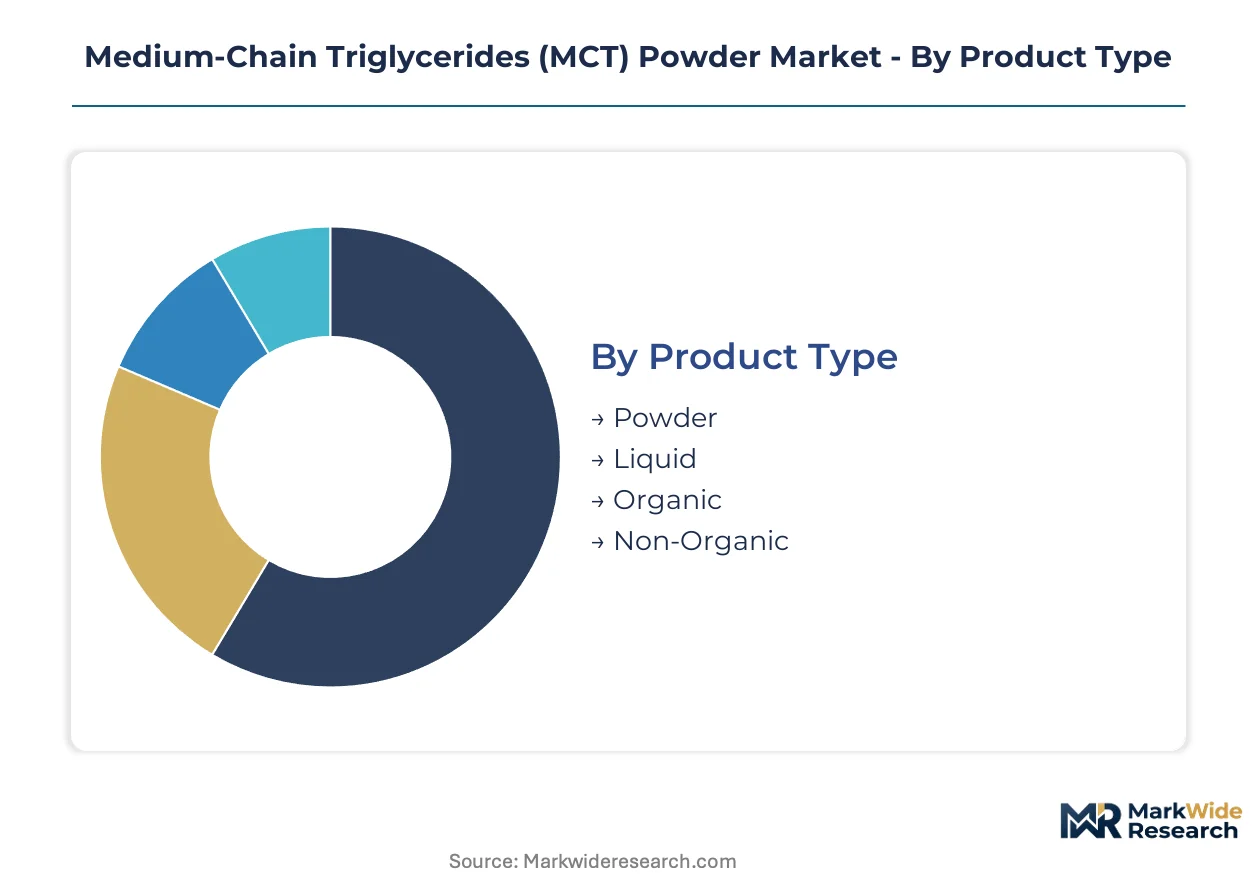
MCT powder segmentation reveals distinct margin profiles and service intensity requirements across formulation types and customer channels. Powder stability specifications and carrier system choices vary sharply between sports nutrition and medical nutrition buyers, driving supplier specialization.
Product Type:
After-sales technical support intensity escalates with formulation complexity, as powder stability troubleshooting and carrier system optimization demand direct supplier engagement.
- Powder:Spray-dried MCT oil using maltodextrin, gum arabic, or modified starch carriers delivers shelf-stable dispersibility for ready-to-drink beverages and dry mix applications. Sports nutrition brands in the United States and Germany concentrate procurement here, prioritizing flowability and dissolution speed in pre-workout formulations.
- Liquid:Unencapsulated MCT oil requires refrigerated supply chains and shorter shelf life management, limiting adoption to food service and small-batch supplement manufacturing. Demand concentrates among artisanal keto product producers seeking minimal processing claims.
- Organic:Certified organic MCT powder commands premium positioning through fractionated coconut oil sourced from certified plantations, with EFSA organic labeling compliance adding documentation overhead.
- Non-Organic:Conventional fractionated coconut or palm kernel oil feedstocks dominate commercial volumes, with Indonesian and Malaysian supply chains providing cost-competitive lauric-rich inputs.
Powder holds the largest share; momentum sits with organic as clean-label mandates intensify.
End User:
Customer technical sophistication determines formulation partnership depth, with pharmaceutical-grade buyers demanding lipid chemistry expertise and sports nutrition brands prioritizing speed-to-market.
- Nutraceutical Companies:Full-service contract manufacturers integrate MCT powder into multi-ingredient stacks, requiring supplier stability data and regulatory documentation packages for FDA GRAS and EFSA novel food submissions.
- Food Manufacturers:Functional food producers embed MCT powder into bar, beverage, and bakery applications, with sensory masking and texture optimization driving carrier system selection.
- Dietary Supplement Brands:Direct-to-consumer marketers in the United States and Germany unbundle bulk powder into personalized dosing protocols, with subscription replenishment models reshaping procurement cadence.
- Fitness Centers:Private-label sports nutrition programs at gym chains source co-branded pre-workout and recovery formulations, with white-label powder supply agreements dominating vendor relationships.
Dietary supplement brands hold the largest share; nutraceutical companies are gaining share fastest through integrated manufacturing expansion.
Application:
Clinical validation requirements create tiered margin pools, with hospital and institutional procurement demanding extensive efficacy documentation.
- Sports Nutrition:Pre-workout and recovery formulations leverage ketogenic diet positioning and metabolic efficiency claims, with fitness centers and supplement brands driving volume through direct-to-consumer channels.
- Weight Management:Satiety and thermogenesis positioning competes with plant protein isolates in clean-label segments, pressuring pure MCT powder differentiation.
- Medical Nutrition:Pharmaceutical-grade production for malabsorption disorders and ketogenic diet therapy requires lipid chemistry expertise, with Croda International Plc and BASF SE capturing premium margin structures through clinical validation barriers.
- Keto Diet:Consumer education intensity around metabolic health supports premium pricing, with personalized dosing protocols and subscription models displacing traditional retail distribution in the United States and Germany.
Sports nutrition holds the largest share; medical nutrition shows the steepest expansion trajectory as clinical validation requirements deepen supplier moats.
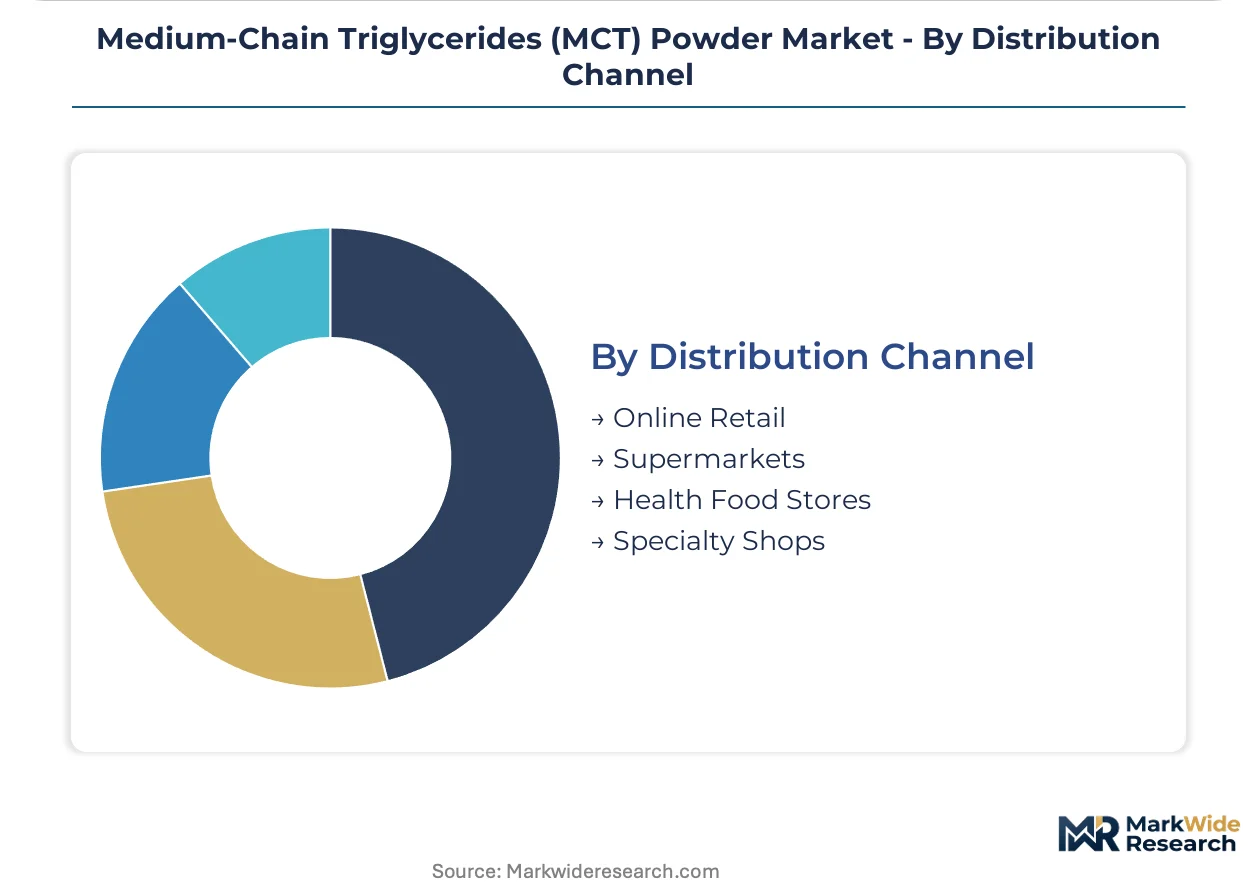
Distribution Channel:
Channel service requirements vary from technical consultation in specialty retail to logistics efficiency in mass-market grocery.
- Online Retail:Amazon and direct-to-consumer brand sites concentrate subscription replenishment for ketogenic dietary supplements, with personalized dosing protocols and convenience positioning commanding premium pricing.
- Supermarkets:Mass-market grocery placement demands price-competitive bulk formats and mainstream label claims, with shelf stability and flowability specifications driving powder format dominance.
- Health Food Stores:Specialty retailers like Whole Foods Market prioritize organic certification and clean-label carrier systems, with maltodextrin-free positioning increasingly table stakes.
- Specialty Shops:Independent supplement retailers and functional medicine clinics serve medical nutrition buyers, with clinical validation documentation and healthcare practitioner education programs supporting premium positioning.
Online retail holds the largest share; specialty shops are climbing the fastest as functional medicine channels expand medical nutrition access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fractionation capacity expansions in Indonesia and Malaysia are reshaping feedstock access for European and North American powder manufacturers, while regulatory divergence between FDA GRAS pathways and EFSA novel food assessments creates compliance complexity for brands pursuing unified formulations.
United States
Fitness centers and dietary supplement brands in California and Texas drive procurement for pre-workout formulations, with FDA GRAS self-affirmation enabling faster commercialization of novel MCT sources. Direct-to-consumer subscription models concentrate in metropolitan clusters across the Northeast and West Coast.
Germany
EFSA novel food assessments shape ingredient approval timelines for sports nutrition brands targeting ketogenic diet positioning. Bavaria and North Rhine-Westphalia host contract manufacturing facilities integrating microencapsulation technologies for powder stability optimization.
China
SAMR registration requirements and GB standards enforcement govern functional food applications, with Yangtze River Delta processors expanding spray-drying capacity for domestic sports nutrition brands. Localized carrier system innovation responds to clean-label import pressures.
Indonesia
Fractionation infrastructure investments in Sumatra and Sulawesi are expanding lauric-rich coconut oil supply for export-oriented powder manufacturers. National agricultural programs support certified organic plantation development to capture premium positioning in European health food channels.
India
FSSAI labeling standards for ayurvedic-positioned MCT products create compliance barriers for unified global formulations, with Maharashtra and Karnataka dietary supplement clusters adapting procurement specifications for domestic health food distribution.
Medium-Chain Triglycerides (MCT) Powder Market Competitive Landscape
Backward-integrated chemical conglomerates and specialized lipid chemistry houses split the market between cost-competitive feedstock control and pharmaceutical-grade formulation expertise. The vendor base concentrates around three strategic archetypes: fractionation-integrated processors with captive coconut oil supply, microencapsulation technology specialists, and pharmaceutical-grade lipid chemistry providers. Capacity expansion in Southeast Asian feedstock processing and carrier system reformulation partnerships represent dominant competitive moves.
Within the integrated-processor tier, Stepan Company exemplifies backward integration into coconut oil supply chains, while Wilmar International occupies a position as a Singapore-based agribusiness with fractionation infrastructure across Southeast Asia. BASF SE anchors the technology-specialist archetype through German chemical manufacturing scale, representing R&D intensity in powder stability systems. These three entities collectively illustrate the competitive tension between feedstock security and formulation innovation that defines supplier positioning.
| Leading Market Players |
|---|
| Stepan Company |
| Koninklijke DSM N.V. |
| ABITEC Corporation |
| Croda International Plc |
| Lonza Group Ltd |
| BASF SE |
| Wilmar International |
| DuPont de Nemours Inc. |
| Cargill |
| Others |
Pricing and Supply Chain Analysis
Indonesian fractionation overcapacity is compressing lauric-rich feedstock premiums and forcing powder manufacturers toward contract renegotiation or backward integration to defend margin structures.
Pricing Analysis
FDA GRAS self-affirmation pathways dictate the pricing tier structure across pharmaceutical-grade, sports nutrition, and commodity powder segments. Three-tier pricing separates clinical-validation-backed medical nutrition from standard sports formulations and bulk ingredient supply. Price differentiation hinges on organic certification compliance and microencapsulation technology sophistication. Cost compression in standard-grade powder is intensifying because Indonesian and Malaysian capacity expansions are flooding lauric-rich feedstock markets. Contract manufacturers exhibit highest price sensitivity; pharmaceutical-grade buyers with lipid chemistry expertise show lowest.
Supply Chain Analysis
Contract manufacturing concentration sits with Bavaria and North Rhine-Westphalia processors in Germany, Yangtze River Delta spray-drying facilities in China, and Sumatra fractionation complexes in Indonesia. Geographic supply concentration centers on Indonesia, Malaysia, and the Philippines for coconut oil feedstocks; Germany and the United States for pharmaceutical-grade formulation. Raw material dependencies rest on fractionated coconut oil, gum arabic carriers, and modified starch matrices. Single-source vulnerability runs through Southeast Asian lauric-rich supply chains exposed to climate disruption. Distribution runs through direct-to-consumer subscription platforms and specialty health food channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier system interoperability is emerging as the platform inflection, with fiber-based maltodextrin replacements creating ecosystem lock-in between fractionators and formulation houses.
For Market Incumbents: Build clinical validation moats around pharmaceutical-grade MCT production for malabsorption and ketogenic therapy applications. Deepen backward integration into certified organic coconut plantations in Sumatra and Sulawesi to secure feedstock access against Indonesian capacity volatility. Expand microencapsulation R&D partnerships with dietary supplement brands seeking clean-label carrier transitions.
For New Entrants and Emerging Players: Establish a beachhead in ayurvedic-positioned MCT powders for Indian health food channels, where FSSAI labeling complexity deters global brands with unified formulations. Target white-label supply agreements with fitness center chains in Texas and California seeking co-branded pre-workout formulations. Pursue direct-to-consumer subscription infrastructure as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across spray-drying and microencapsulation capacity expansions. Long-term viability favors backward-integrated fractionators with captive gum arabic supply and pharmaceutical-grade certification infrastructure. Acquisition target archetype: Southeast Asian feedstock processors with organic certification pipelines and European regulatory dossiers. Monitor Indonesian fractionation utilization rates as the inflection signal for feedstock pricing cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Plantations | Secures lauric-rich feedstock access against Indonesian price volatility and EFSA organic compliance requirements. |
| Microencapsulation Technology Licensing | Enables powder stability optimization for dietary supplement brands transitioning from maltodextrin carriers. |
| Clinical Validation Partnerships with Hospital Systems | Builds procurement barriers for pharmaceutical-grade MCT in malabsorption and ketogenic therapy segments. |
| Direct-to-Consumer Subscription Platform Launch | Captures recurring revenue from ketogenic diet positioning in United States and German metropolitan clusters. |
| FSSAI Regulatory Dossier Development | Unlocks Indian health food channel access for ayurvedic-positioned MCT products with domestic labeling compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, EFSA novel food assessments, FSSAI labeling guidelines, and Indonesian agricultural export data. Primary interviews engaged lipid chemistry R&D directors at pharmaceutical-grade manufacturers, procurement leads at sports nutrition brands, contract manufacturing executives in Germany and China, and regulatory affairs specialists navigating EFSA and FDA pathways. Secondary validation drew from customs trade databases, SEC filings of publicly traded chemical conglomerates, and fractionation capacity reports from Southeast Asian agricultural ministries. Bottom-up volume modeling triangulated against top-down market sizing across powder, liquid, and organic product categories.
Forecast inputs incorporate carrier system transition timelines, clinical validation documentation requirements, and subscription model adoption curves across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, application use case, and distribution channel structure. CAGRs were derived from trend extrapolation of historical volume data adjusted for regulatory approval velocity and feedstock capacity expansion schedules. Industry-specific inputs include EFSA novel food assessment timelines and FDA GRAS self-affirmation completion rates.
Macroeconomic conditions sit as an overlay; deviation in coconut oil commodity cycles, Indonesian agricultural policy, or clean-label regulatory stringency would shift the trajectory. Forecasts reflect documented assumptions regarding fractionation capacity utilization and carrier system substitution elasticity. Quarterly review of EFSA novel food approval volumes and Indonesian plantation certification rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Aminoethylethanolamine Market
Oleochemicals
Cetyl Esters Market
Oleochemicals
Esters Market
Oleochemicals
Global White Oil Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Allyl Caproate Market