
 Europe Arachidonic Acid Market | 2026-2036
Europe Arachidonic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Arachidonic Acid Market Foresight
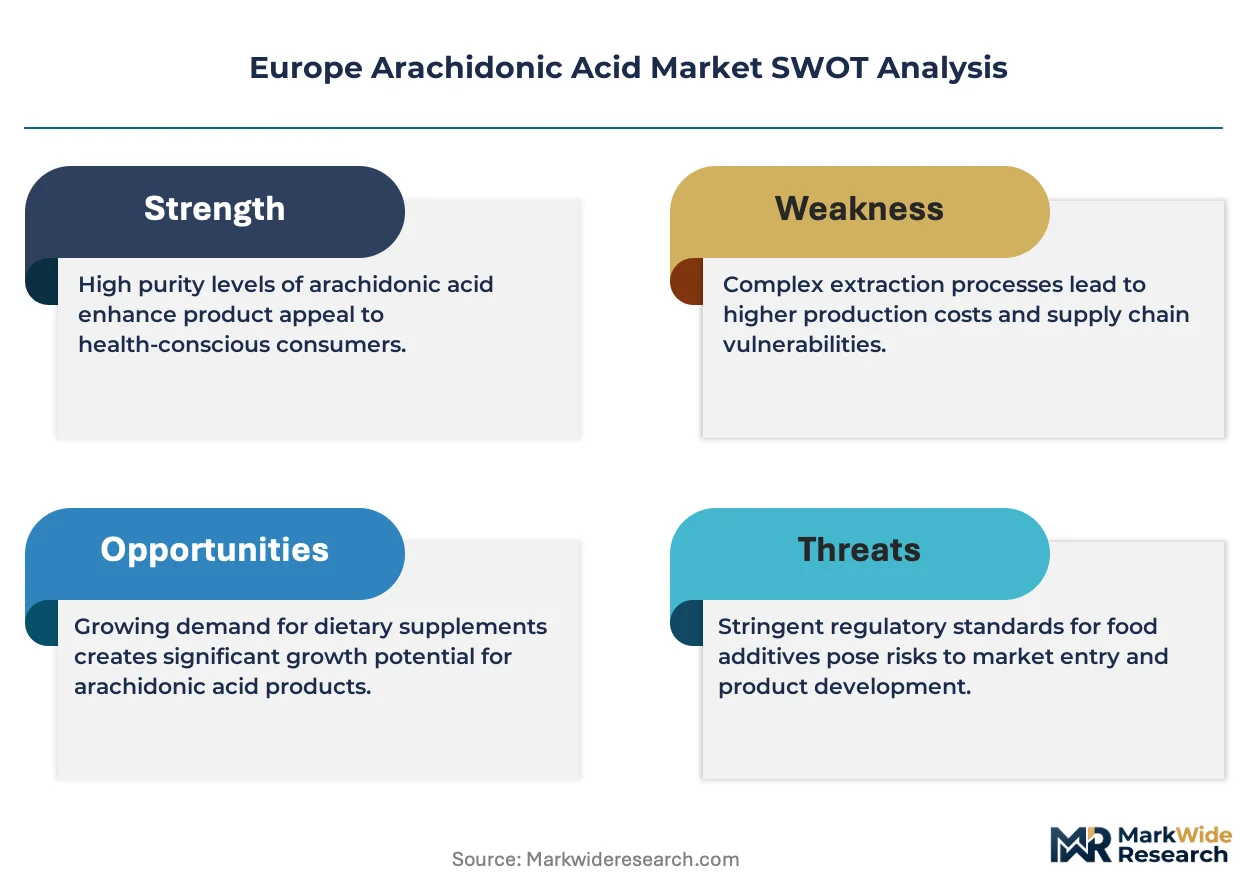
The EU Green Deal is repositioning long-chain polyunsaturated fatty acid procurement toward fermentation-derived and plant-based feedstocks. Cargill leverages its European oilseed processing footprint to secure raw material streams for omega-6 derivative production. Royal DSM sustains technology leadership in microbial fermentation platforms for nutritional lipids. BASF anchors industrial-scale chemical synthesis capacity serving pharmaceutical-grade specifications.
Arachidonic acid is a 20-carbon omega-6 fatty acid with four cis double bonds, typically manufactured through fungal fermentation using Mortierella alpina or extracted from animal tissues, functioning as a critical structural component of cell membranes and precursor to eicosanoid signaling molecules. Powder formulations dominate nutritional applications due to extended shelf stability and ease of incorporation into dry premixes, while emulsion formats gain traction in liquid infant formula systems where dispersion uniformity commands premium positioning. Pharma-grade specifications capture the highest margin pools as batch certification and impurity profiling requirements create qualification barriers that liquid and granule formats in standard nutrition cannot match.
EFSA maintains stringent novel food and health claims oversight for arachidonic acid in infant nutrition, while REACH governs chemical substance registration and bioaccumulation testing for fermentation-derived inputs. The EU F-Gas Regulation indirectly shapes production economics by restricting refrigerant options in low-temperature lipid extraction and crystallization steps. Stakeholders must monitor emerging EU packaging sustainability rules and bio-based content thresholds that will determine facility upgrade priorities and supplier selection criteria across the value chain.
Market Dynamics
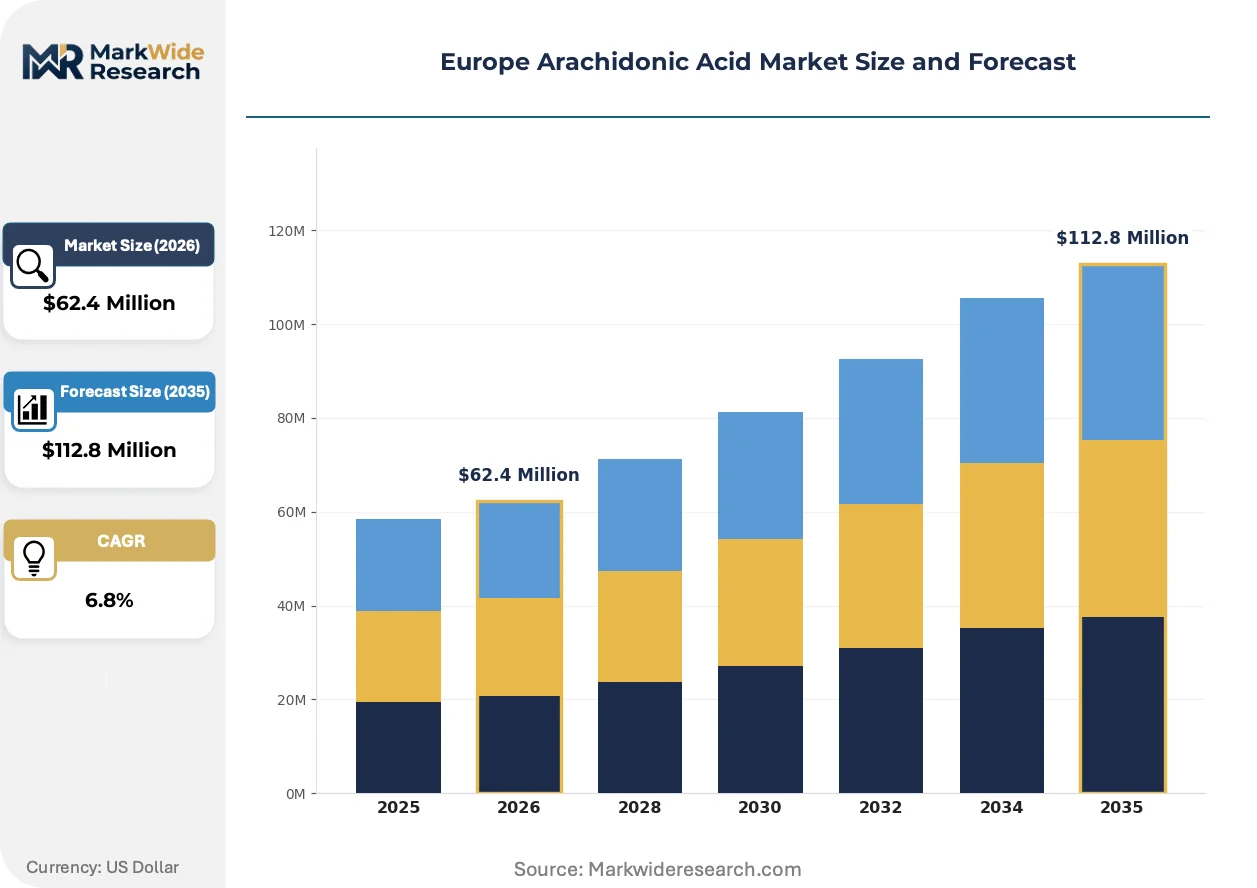
The EU Green Deal's bio-based manufacturing mandates are forcing arachidonic acid suppliers to reconfigure fermentation feedstocks and crystallization energy profiles, while EFSA novel food approvals create asymmetric qualification timelines between incumbent and challenger suppliers.
Growth Catalysts
- EFSA novel food pathways:Streamlined approvals for Mortierella alpina-derived arachidonic acid in infant formula are expanding fortification programs across German and Dutch manufacturing clusters.
- Fermentation platform maturation:Microbial cell engineering advances are reducing batch-to-batch lipid profile variability, improving pharmaceutical-grade yield rates.
- Germany's nutrition corridor concentration:Dense clustering of infant formula producers around Frankfurt and Hamburg creates localized demand pull with shorter logistics loops.
Market Restraints
- Phospholipid feedstock volatility:Rapeseed and sunflower oil price swings directly compress fermentation substrate economics for European producers.
- Single-source supplier risk:Cryogenic extraction equipment for high-purity crystallization concentrates among two German and Swiss engineering houses.
- Docosahexaenoic acid substitution pressure:DHA-ARA ratio optimization in premium infant formula is displacing pure arachidonic acid positioning in some SKUs.
Strategic Opportunities
- Poland's underdeveloped pharma corridor:Warsaw and Łódź lack qualified lipid suppliers for clinical nutrition, creating first-mover positioning for fermentation-capable entrants.
- EU F-Gas Regulation retrofit incentives:Subsidized cooling system upgrades enable energy-efficient extraction processes that qualify for Green Deal procurement preferences.
- Powder-to-emulsion format convergence:Hybrid dry-liquid delivery systems are opening liquid infant formula contracts previously locked by oil-based incumbents.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA's lipid impurity profiling requirements extend batch release cycles by four to six months versus nutritional-grade specifications.
- Fermentation scale-up talent scarcity:Industrial microbiologists with Mortierella alpina strain optimization experience command premium compensation in Basel and Rotterdam clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Arachidonic Acid Market |
| Market Size in 2026 | $62.4 Million |
| Market Size in 2035 | $112.8 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granule, Emulsion Application: Nutrition, Pharmaceuticals, Dietary Supplements, Cosmetics End User: Healthcare Providers, Food Manufacturers, Cosmetic Companies, Research Institutions Quality Grade: Food Grade, Pharma Grade, Cosmetic Grade, Industrial Grade |
| Companies Covered | Cargill, Royal DSM, BASF, Croda International, Evonik Industries, Cayman Chemicals, Cabio Biotech (Wuhan), Xiamen Kingdomway, Guangdong Runke Bioengineering, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Arachidonic Acid Market Shifts & Advancements
Arachidonic acid production is bifurcating between commodity nutritional grades and certified pharmaceutical specifications, with technology investments clustering around energy efficiency and analytical precision rather than capacity expansion.
Continuous fermentation monitoring using Raman spectroscopy and machine learning is integrating real-time lipid composition feedback into process control loops. Dutch infant formula manufacturers are adopting these systems fastest, compressing batch deviation detection from hours to minutes. This integration is enabling just-in-time powder premixing with tighter ARA-DHA ratio tolerances than offline testing permits.
REACH bioaccumulation testing requirements for fermentation-derived substances are tightening impurity disclosure thresholds for long-chain polyunsaturated fatty acids. The regulation is forcing suppliers to revalidate existing Mortierella alpina strain libraries under updated ecotoxicology protocols. Pharmaceutical-grade producers in France's Ile-de-France corridor are absorbing these compliance costs fastest, widening their qualification gap against nutritional-grade competitors.
Buyers in Germany's infant formula sector are consolidating supplier panels from six to three qualified sources per manufacturing site, prioritizing those with integrated powder-emulsion dual-format capabilities. Direct procurement relationships are replacing distributor intermediaries for volume contracts above fifty metric tons annually. This concentration is most visible in FrieslandCampina's Dutch and German facilities, where technical service integration now outweighs price in vendor selection scoring.
Europe Arachidonic Acid Market Segmentation
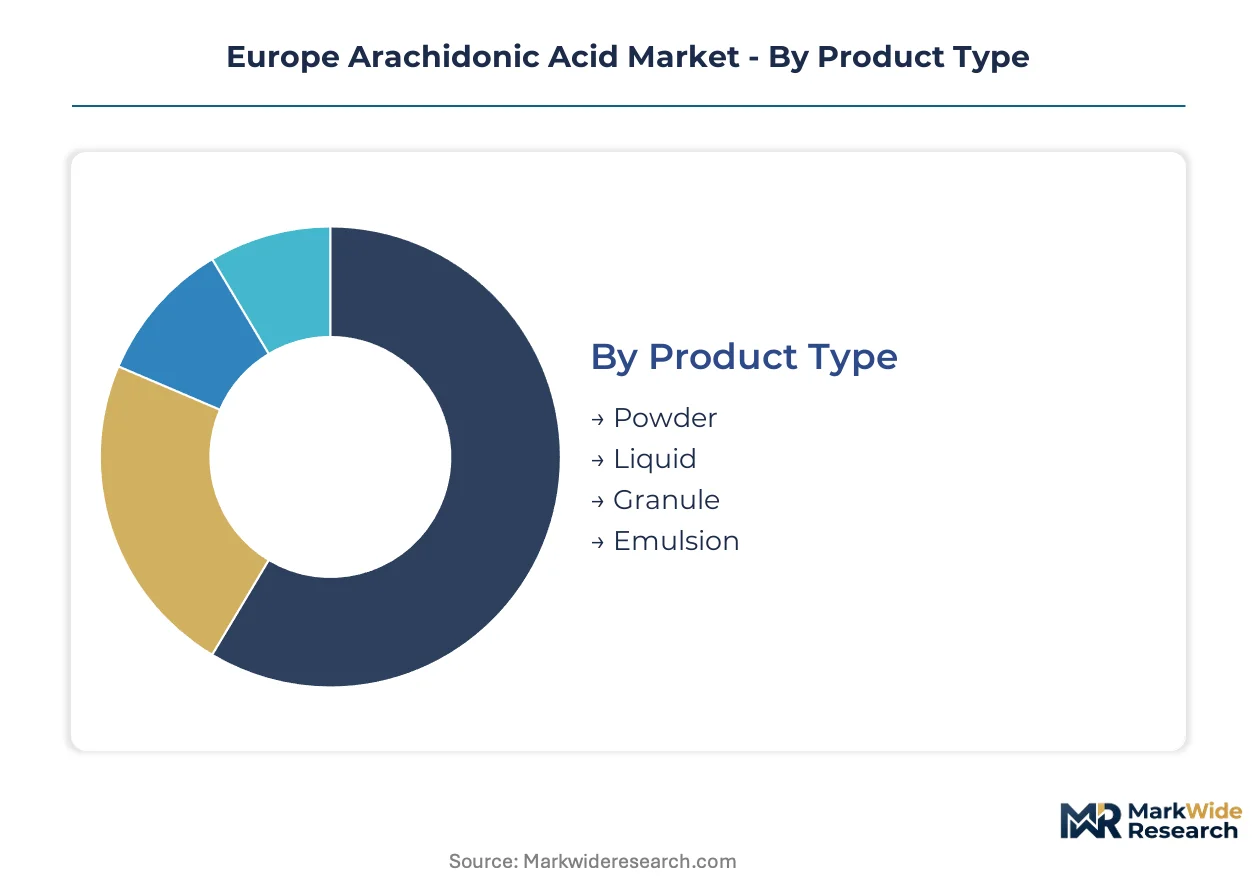
Arachidonic acid procurement patterns in Europe diverge sharply across format specifications and quality tiers. EFSA novel food pathways and EU Green Deal mandates are reshaping which segments absorb capital investment versus maintenance spending.
Product Type:
Formulation chemistry dictates shelf stability, dispersion behavior, and downstream processing economics for European buyers.
- Powder:Microencapsulated lipid matrices with maltodextrin or modified starch carriers deliver 18-24 month stability windows. German infant formula manufacturers around Frankfurt and Hamburg specify powder for dry premix operations where moisture control is critical.
- Liquid:Oil-based suspensions require nitrogen blanketing and cold-chain logistics but enable direct dosing into liquid formula systems. Dutch manufacturers are expanding liquid contracts fastest as hybrid powder-emulsion delivery systems gain technical validation.
- Granule:Intermediate particle size offers flowability advantages for high-speed tableting lines in dietary supplement production. Swiss contract manufacturers prefer granule for omega-6 combination products.
- Emulsion:Aqueous dispersions with surfactant stabilization achieve uniform lipid distribution in ready-to-feed infant formulas. France's pharmaceutical corridor sources emulsion for clinical nutrition applications requiring precise ARA-DHA ratios.
Mature deployment sits with Powder. Newer deployment is concentrated in Emulsion.
Application:
Regulatory qualification barriers and margin structures segment demand across end-use categories with divergent certification timelines.
- Nutrition:Infant formula fortification dominates volume, with EFSA novel food approvals required for Mortierella alpina-derived ARA in EU markets. German and Dutch manufacturing clusters concentrate procurement for 0-12 month formula SKUs.
- Pharmaceuticals:EMA lipid impurity profiling and batch certification create four-to-six month release cycles. France's Ile-de-France corridor absorbs these compliance costs for parenteral nutrition and therapeutic lipid emulsions.
- Dietary Supplements:Capsule and softgel formats target adult omega-6 supplementation with less stringent stability requirements than infant applications. Polish and Romanian markets show expanding retail distribution.
- Cosmetics:Skin barrier function claims drive incorporation into premium dermocosmetic formulations, though volumes remain fractional compared to nutritional applications. Italian cosmetic manufacturers lead sourcing for anti-inflammatory positioning.
Revenue concentration sits with Pharmaceuticals. Volume expansion is climbing fastest in Nutrition.
End User:
Procurement sophistication and technical service requirements stratify the customer base across integrated manufacturers and specialized formulators.
- Food Manufacturers:Infant formula producers in Germany and the Netherlands consolidate supplier panels from six to three qualified sources per site, prioritizing dual-format powder-emulsion capabilities. Direct procurement relationships now dominate contracts above fifty metric tons annually.
- Healthcare Providers:Hospital pharmacy and clinical nutrition departments source pharmaceutical-grade specifications for neonatal and metabolic disorder protocols. France's public hospital networks specify ARA-DHA ratios with tighter tolerances than retail nutrition.
- Cosmetic Companies:Formulation houses in Italy and Spain incorporate ARA into anti-aging and barrier repair positioning, though batch sizes remain small versus nutritional buyers.
- Research Institutions:Academic and contract research organizations source reference-grade materials for clinical trials and cell culture applications, with Swiss and UK universities leading European demand.
Procurement maturity sits with Food Manufacturers. Technical service intensity is expanding most quickly in Healthcare Providers.
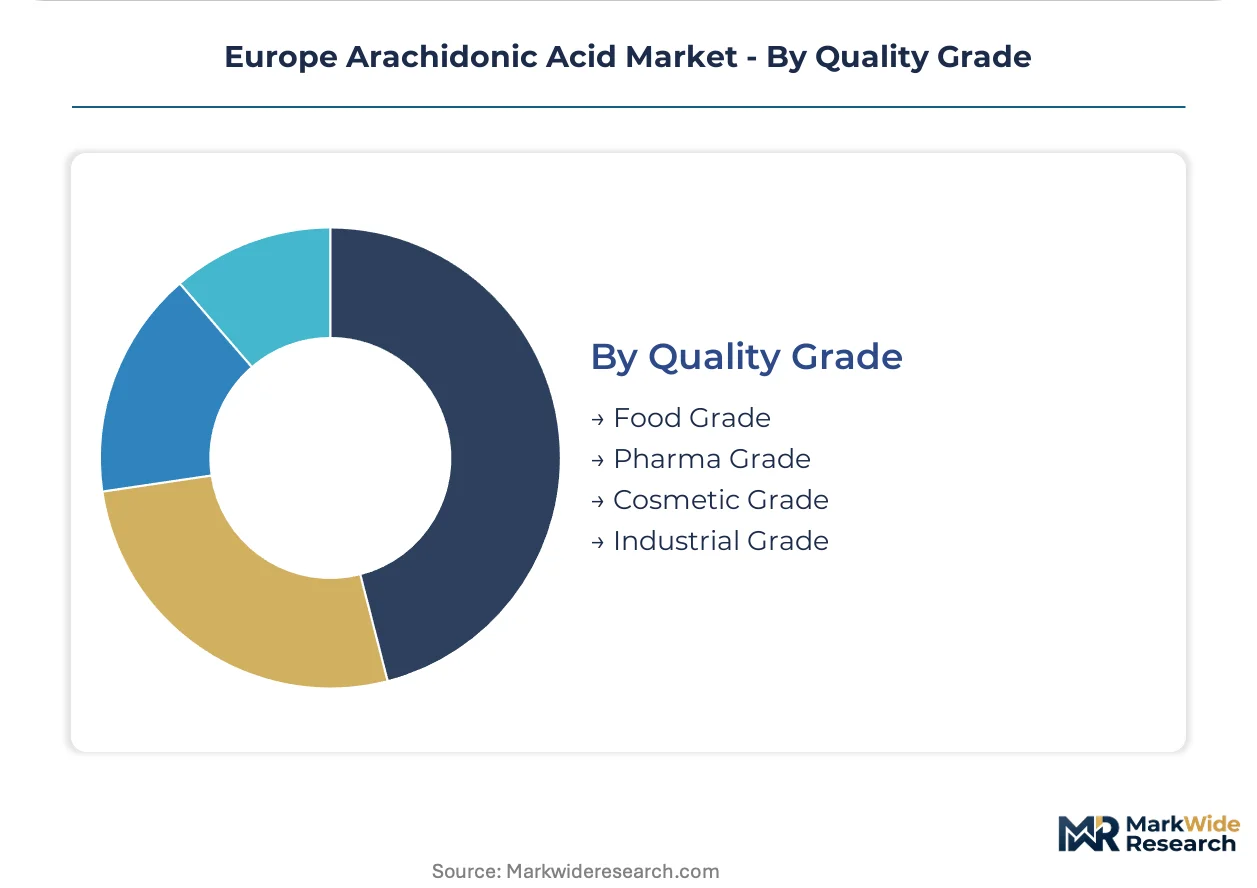
Quality Grade:
Certification depth and analytical rigor create tiered pricing structures that separate commodity from premium positioning.
- Pharma Grade:USP/EP monograph compliance, residual solvent limits, and endotoxin testing command highest margins. EMA batch release requirements in France and Germany sustain qualification barriers that nutritional grades cannot match.
- Food Grade:EFSA novel food and health claims oversight governs infant nutrition applications, with HACCP and FSSC 22000 certification standard for German and Dutch manufacturing clusters.
- Cosmetic Grade:Microbiological and heavy metal specifications align with EU Cosmetics Regulation requirements, though analytical depth trails pharmaceutical standards. Italian and Spanish formulators drive specification setting.
- Industrial Grade:Technical applications in lubricants and polymer additives absorb lowest-purity fractions, with limited European demand compared to Asian industrial markets.
Margin concentration sits with Pharma Grade. Volume scale is gaining share fastest in Food Grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Hamburg anchor Europe's arachidonic acid procurement, with dense infant formula manufacturing clusters driving concentrated demand pull and shortened logistics loops across the German nutrition corridor.
Germany
Infant formula producers around Frankfurt and Hamburg consolidate supplier panels from six to three qualified sources per site, prioritizing dual-format powder-emulsion capabilities. EFSA novel food approvals for Mortierella alpina-derived ARA streamline fortification programs. The North Rhine-Westphalia nutrition cluster absorbs pharmaceutical-grade specifications for clinical nutrition applications.
Netherlands
FrieslandCampina's Dutch facilities lead adoption of hybrid powder-emulsion delivery systems for liquid infant formula contracts. Continuous fermentation monitoring using Raman spectroscopy compresses batch deviation detection timelines. The Rotterdam-Breda corridor concentrates microbial fermentation talent and cryogenic extraction equipment access.
France
EMA lipid impurity profiling requirements extend batch release cycles by four to six months, sustaining qualification barriers for pharmaceutical-grade producers. The Ile-de-France corridor absorbs these compliance costs fastest for parenteral nutrition and therapeutic lipid emulsions. Paris-region hospitals specify tighter ARA-DHA ratio tolerances than retail nutrition.
Switzerland
Swiss contract manufacturers prefer granule formats for omega-6 combination products in dietary supplement production. Swissmedic pharmaceutical-grade certification creates tiered entry barriers for nutritional lipid suppliers. The Basel cluster commands premium compensation for industrial microbiologists with Mortierella alpina strain optimization experience.
Poland
Warsaw and Łódź lack qualified lipid suppliers for clinical nutrition, creating first-mover positioning for fermentation-capable entrants. Polish retail distribution networks expand adult omega-6 supplementation capsule formats. The underdeveloped pharma corridor offers asymmetric opportunity for pharmaceutical-grade qualification investments.
Europe Arachidonic Acid Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade tiers, with pharmaceutical specifications commanding qualification barriers that nutritional grades cannot match. The vendor base stratifies between integrated fermentation-platform operators, oilseed-processing diversifiers, and chemical-synthesis specialists. Three archetypes dominate: microbial fermentation leaders leveraging Mortierella alpina platforms, agricultural processors securing feedstock streams, and industrial chemical houses anchoring synthetic capacity. Competitive moves concentrate on dual-format capability expansion and Green Deal compliance retrofitting rather than pure capacity additions.
Among fermentation-platform specialists, Royal DSM exemplifies technology leadership in microbial lipid production, while BASF anchors industrial-scale chemical synthesis capacity serving pharmaceutical-grade specifications. Cargill occupies a position bridging agricultural feedstock control with downstream omega-6 derivative production through its European oilseed processing footprint. These three represent the tiered structure: DSM sits within premium-margin fermentation, BASF within synthetic pharma-grade, and Cargill within integrated feedstock-to-derivative supply control.
| Leading Market Players |
|---|
| Cargill |
| Royal DSM |
| BASF |
| Croda International |
| Evonik Industries |
| Cayman Chemicals |
| Cabio Biotech (Wuhan) |
| Xiamen Kingdomway |
| Guangdong Runke Bioengineering |
| Others |
Supply & Pricing Matrix
Industrial microbiologists with Mortierella alpina strain optimization experience in the Basel and Rotterdam clusters command premium compensation that directly widens pricing spreads between pharmaceutical-grade and nutritional-grade tiers. Labor-cost differentials between these specialized fermentation hubs and peripheral European markets create asymmetric margin structures that suppliers exploit through tiered certification positioning.
Pricing Analysis
Yield-guarantee contracts tied to batch consistency metrics anchor value-based pricing for pharmaceutical-grade arachidonic acid. Three-tier pricing structure across premium, standard, and economy levels separates EMA-certified specifications from EFSA novel food grades and industrial feedstock tiers. Price differentiation rests on impurity profiling depth and endotoxin testing rigor. Cost compression in nutritional-grade powder formats is intensifying because German infant formula manufacturers consolidate supplier panels and demand volume discounts.
Supply Chain Analysis
Dual-sourcing requirements embedded in FrieslandCampina's vendor qualification protocols force infant formula manufacturers to maintain three qualified suppliers per site. Geographic supply concentration centers on Germany, the Netherlands, and Switzerland for fermentation capacity and cryogenic extraction equipment. Raw material dependencies draw from rapeseed oil, sunflower phospholipids, and nitrogen blanketing systems. Single-source vulnerability concentrates in Swiss and German engineering houses for high-purity crystallization units. Distribution runs through direct procurement relationships for contracts above fifty metric tons annually, replacing distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Arachidonic Acid Market sits in a technology-transition phase where Raman spectroscopy-enabled continuous fermentation monitoring is displacing offline batch testing protocols. This shift compresses deviation detection timelines and reconfigures supplier qualification criteria.
For Market Incumbents: Lock in dual-format powder-emulsion capabilities to defend against hybrid delivery system challengers. Prioritize EU F-Gas Regulation compliance retrofits to secure Green Deal procurement preferences. Backward integration into cryogenic extraction equipment partnerships mitigates single-source vulnerability from Swiss and German engineering houses.
For New Entrants and Emerging Players: Contract research organizations serving clinical nutrition trials represent the most penetrable channel partner type for pharmaceutical-grade qualification. Target Poland's underdeveloped pharma corridor in Warsaw and Łódź where qualified lipid suppliers remain absent. Pursue first-mover positioning through EMA batch certification investments that incumbent nutritional-grade players cannot match.
For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-platform specialists given EFSA novel food approval streamlining for Mortierella alpina-derived arachidonic acid. Long-term viability hinges on microbial cell engineering capabilities that reduce batch-to-batch variability. Acquisition targets should demonstrate integrated analytical precision and energy-efficient extraction processes. Signal to watch: consolidation of German infant formula supplier panels from six to three qualified sources per manufacturing site.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Format Capability Expansion | Hybrid powder-emulsion systems unlock liquid infant formula contracts previously held by oil-based incumbents. |
| Green Manufacturing Transition | EU F-Gas Regulation retrofit subsidies enable energy-efficient extraction qualifying for Green Deal procurement. |
| Pharmaceutical-Grade Certification | EMA lipid impurity profiling investments widen qualification gaps against nutritional-grade competitors. |
| Regional Capacity Expansion | Fermentation-capable facilities in Poland's underdeveloped pharma corridor capture first-mover positioning. |
| Long-Term Supply Agreement | Direct procurement relationships above fifty metric tons annually replace distributor intermediaries for volume contracts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fermentation platform directors, infant formula procurement leads, EMA regulatory affairs specialists, and cryogenic extraction equipment engineers combined with EFSA novel food approval databases, REACH registration dossiers, and EU customs trade statistics. Bottom-up volume modeling across product formats and quality grades triangulated against top-down market sizing from industry association reports.
Granularity-level framing applied country-specific fermentation capacity modeling for Germany, the Netherlands, France, Switzerland, and Poland alongside format-level demand segmentation across powder, liquid, granule, and emulsion specifications. End-use industry splits captured infant formula fortification, pharmaceutical-grade parenteral nutrition, dietary supplements, and cosmetic applications. CAGRs derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific inputs included EFSA approval timelines, EMA batch release cycle durations, and EU F-Gas Regulation compliance cost curves.
Caveats apply where EFSA novel food pathway delays, phospholipid feedstock price volatility, or DHA substitution acceleration in premium infant formula could materially shift the outlook. Deviation in EMA lipid impurity profiling requirement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Butyl Stearate Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Partially Hydrogenated Oil Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Asia-Pacific Oleochemicals Market