
 Stearyl Tartrate Market | 2026-2036
Stearyl Tartrate Market Size, Share, and Industry Trends Forecast 2026-2036
Stearyl Tartrate Market Analysis
The capital-intensity divergence between integrated oleochemical producers and specialty ester formulators is collapsing as mid-scale players adopt continuous esterification systems. Croda International Plc leverages backward integration into renewable fatty alcohol feedstocks to secure margin control across cosmetic-grade stearyl tartrate batches. Stepan Company anchors its position through dedicated emulsifier technology centers in North America that sustain formulation partnerships with multinational food manufacturers. Evonik Industries AG differentiates via pharmaceutical-grade certification pathways that command premium positioning in drug-delivery applications.
Stearyl tartrate is an ester synthesized from stearic acid and tartaric acid, functioning primarily as an anionic emulsifier and dough-conditioning agent with HLB values typically ranging from 8 to 12. The compound stabilizes oil-in-water interfaces in baked goods, creams, and topical formulations while meeting food-grade purity thresholds under Codex Alimentarius specifications. Cosmetic-grade and food-grade segments dominate current volume flows, with pharmaceutical-grade production representing the fastest-expanding margin pool as parenteral compatibility requirements intensify. Powder and liquid forms split demand along customer scale lines, where industrial bakeries favor bulk powder handling and boutique cosmetic labs specify liquid emulsions for precision dosing.
FDA food additive regulations under CFR 172.836 and EFSA food-contact material evaluations shape permissible migration limits and purity benchmarks for stearyl tartrate entering packaged food and pharmaceutical channels. REACH registration obligations in Europe and BIS certification requirements in India further segment market access by compliance tier rather than production cost alone. Stakeholders must monitor evolving pharmacopeial monograph revisions and biobased content thresholds, as these standards will determine which manufacturing configurations retain commercial viability across regulated end-use segments.
Market Dynamics
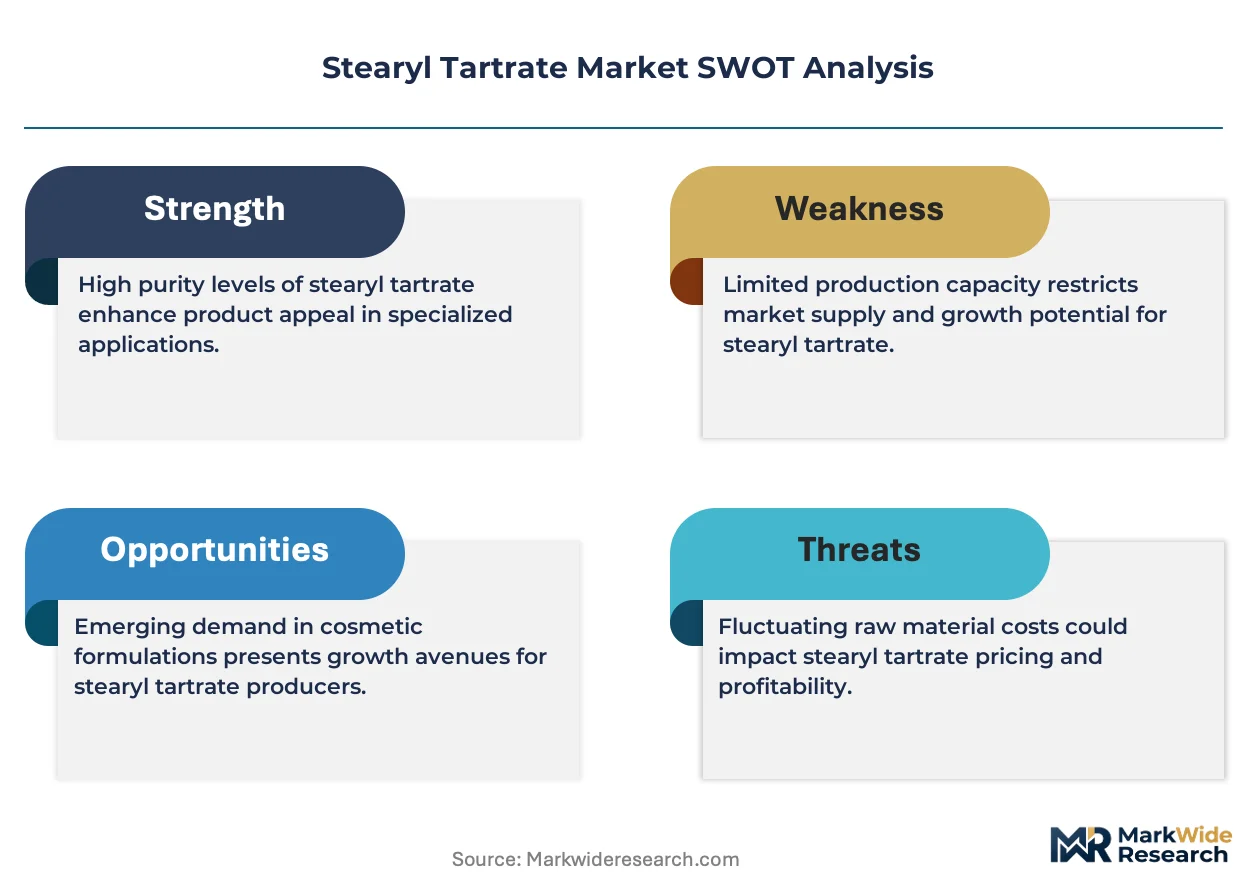
Clean-label emulsifier mandates from EFSA and FDA are compressing synthetic additive portfolios while elevating tartaric acid esters in bakery and cosmetic formulations. Manufacturers must now reconfigure esterification capacity to serve dual food-grade and pharmaceutical-grade purity tiers under diverging compliance timelines.
Growth Catalysts
- EFSA food-contact evaluations:Tightened migration limits for packaged baked goods are redirecting formulator procurement toward stearyl tartrate from synthetic alternatives.
- Pharmaceutical-grade parenteral compatibility:Rising demand for biocompatible drug-delivery vehicles is expanding high-purity ester production capacity.
- German oleochemical clusters:Integrated fatty alcohol-to-ester supply chains in North Rhine-Westphalia are shortening lead times for European cosmetic manufacturers.
Market Restraints
- Palm kernel oil price volatility:Stearic acid feedstock costs fluctuate with Malaysian export duties and sustainability certification premiums.
- REACH registration concentration:Only a handful of EU-based producers hold full substance dossiers, creating supply bottleneck risk for non-integrated buyers.
- Enzymatic esterification substitution:Lipase-catalyzed processes for alternative emulsifiers threaten batch-scale tartaric ester economics.
Strategic Opportunities
- India BIS certification pathway:Early compliance with Bureau of Indian Standards food additive specifications opens access to subcontinent bakery expansion.
- Continuous esterification technology:Adoption of fixed-bed reactor systems by mid-scale producers collapses unit capital intensity versus batch operations.
- US FDA food-contact substance notifications:Streamlined pre-market consultation pathways accelerate clean-label positioning in North American packaged goods.
Industry Challenges
- Pharmacopeial monograph harmonization:Divergent USP, EP, and JP purity specifications force multi-standard inventory management for pharmaceutical-grade batches.
- Legacy batch reactor retrofit costs:Transitioning to continuous processing demands capital outlays that strain privately held formulators.
- Tartaric acid supply security:Dependence on wine industry byproduct streams creates seasonal availability constraints for non-synthetic tartaric acid sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stearyl Tartrate Market |
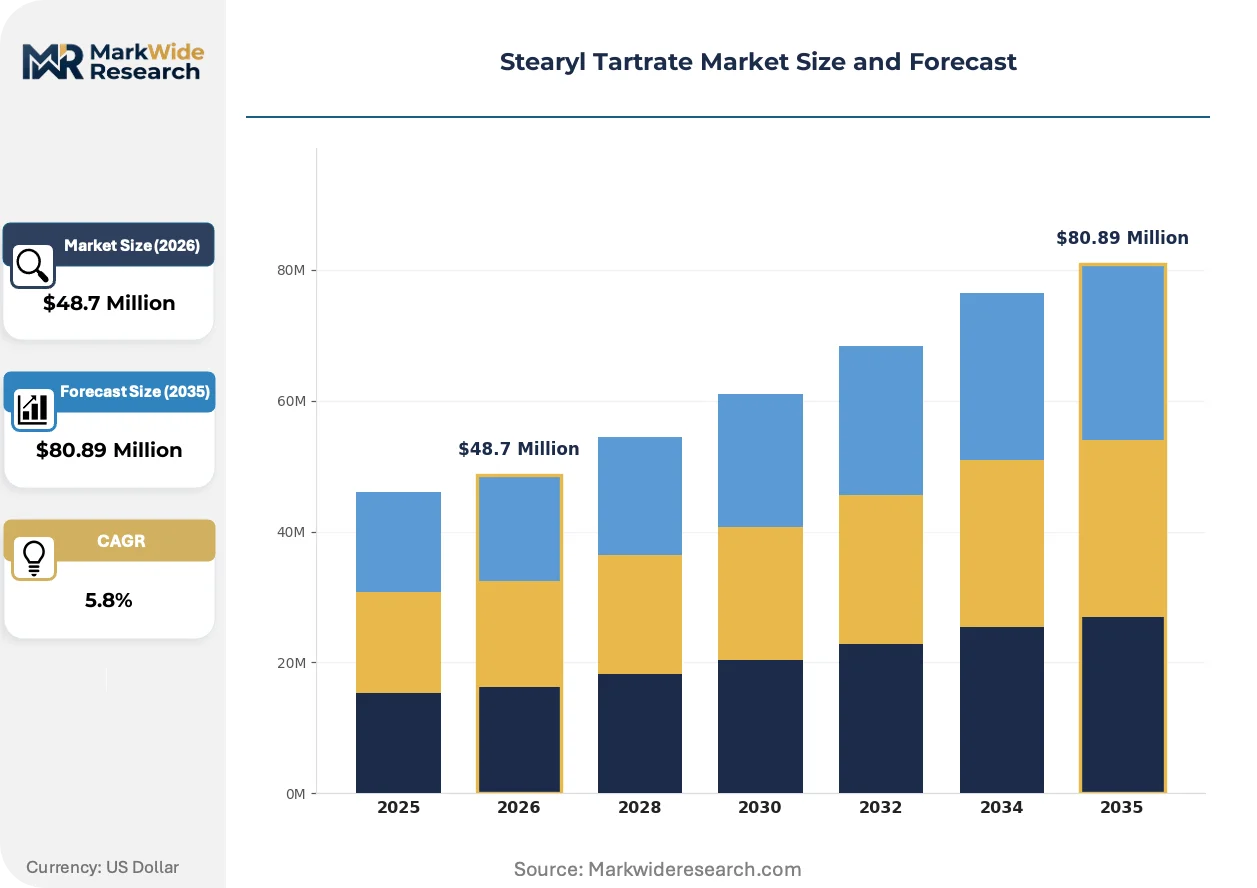
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $80.89 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cosmetics, Pharmaceuticals, Food Additives, Personal Care Form: Powder, Liquid, Granule, Emulsion Grade: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Packaging Type: Bags, Bottles, Drums, Sachets |
| Companies Covered | Oleon NV, Stepan Company, Croda International Plc, Evonik Industries AG, KLK OLEO, Emery Oleochemicals, IOI Oleochemicals, Acme Synthetic Chemicals, Faci Asia Pacific Pte Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stearyl Tartrate Market Emerging Trajectories
Enzyme-catalyzed esterification and continuous reactor design are displacing conventional batch sulfuric acid processes. Regulatory convergence on biobased content thresholds and pharmacopeial grade specifications is simultaneously reshaping capital allocation and customer qualification protocols.
Continuous fixed-bed esterification systems utilizing immobilized lipase biocatalysts are displacing traditional sulfuric acid batch reactors in mid-scale specialty ester plants. Industrial bakeries in Germany and cosmetic formulators in France are adopting these outputs for cleaner label declarations. The technology is displacing capital-intensive acid-catalyzed infrastructure while compressing energy consumption per kilogram of emulsifier output.
REACH substance evaluation deadlines for tartaric acid derivatives are forcing dossier updates and extended toxicity testing obligations on EU-registered manufacturers. The industrial consequence is a bifurcation between integrated producers with in-house regulatory affairs capacity and import-dependent distributors facing registration gaps. Pharmaceutical-grade segments are responding by consolidating supplier qualification lists to those with completed REACH Annex XV dossiers.
Direct procurement contracts between industrial bakeries and oleochemical producers are bypassing traditional specialty chemical distributors in Western Europe. Large-scale bread manufacturers in the Netherlands and biscuit producers in Belgium now specify stearyl tartrate volumes through annual framework agreements rather than spot purchasing. This channel compression is most visible in the Benelux region, where consolidated bakery groups command formulation input standardization across multiple production facilities.
Stearyl Tartrate Market Segmentation
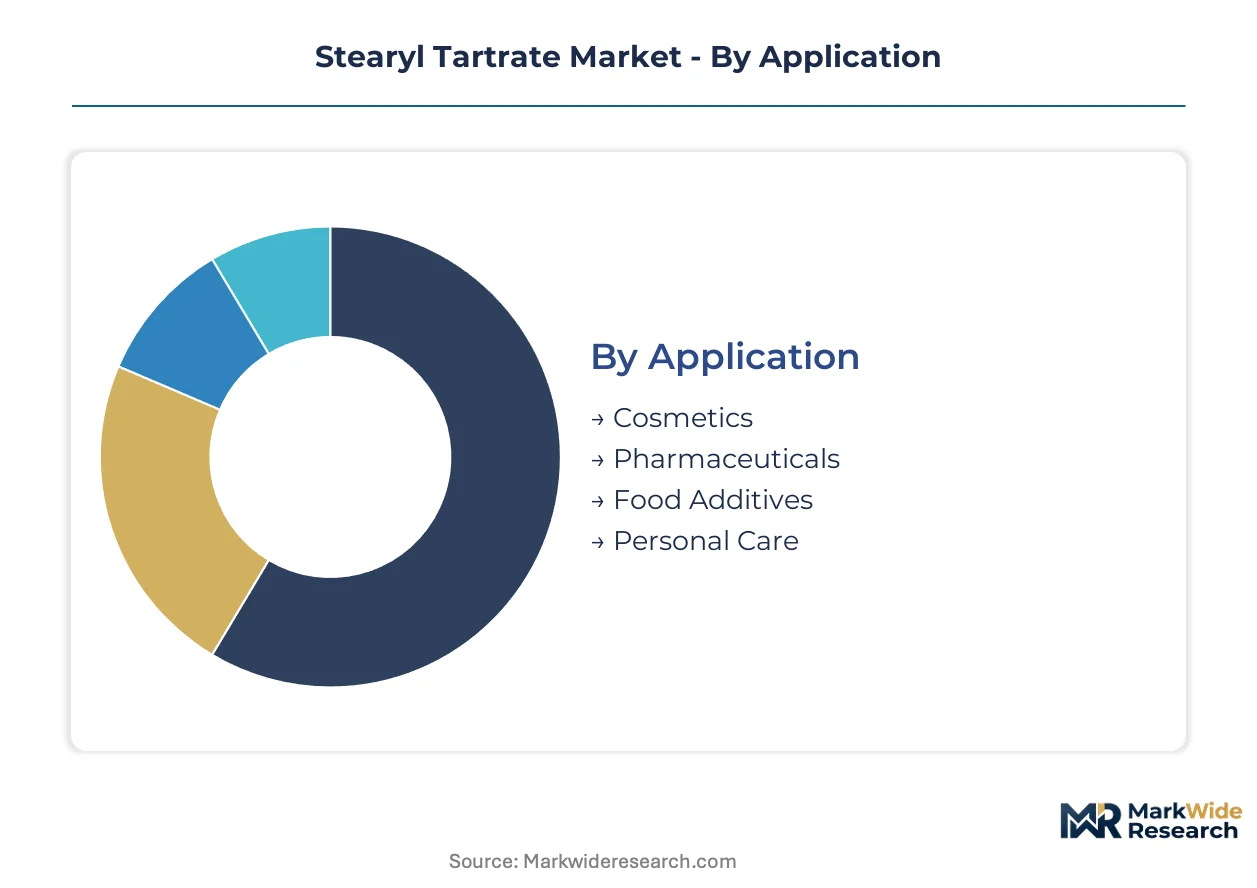
Stearyl tartrate procurement patterns diver sharply across end-use channels, with pharmaceutical formulators demanding certified purity tiers while industrial bakeries prioritize bulk handling economics. Channel-specific packaging and grade requirements create distinct margin pools that reward manufacturers with flexible esterification assets.
Application:
Cosmetic laboratories and pharmaceutical compounders source through specialized distributors with certification documentation, while food manufacturers procure directly from oleochemical producers under annual framework agreements.
- Cosmetics:Facial creams and lotions utilize stearyl tartrate for oil-in-water emulsion stability at HLB values between 8 and 10. French and German cosmetic formulators are consolidating supplier lists to REACH-registered producers with dedicated cosmetic-grade batch protocols.
- Pharmaceuticals:Parenteral drug-delivery systems demand USP-grade material with endotoxin limits below 20 EU per gram. This segment commands the steepest expansion trajectory as biologic formulation compatibility requirements intensify across European and North American injectables markets.
- Food Additives:Industrial bakeries in Belgium and the Netherlands specify stearyl tartrate for dough conditioning in packaged bread and biscuit production. Clean-label mandates from EFSA are redirecting procurement from synthetic emulsifiers toward tartaric acid esters.
- Personal Care:Hair conditioners and body lotions incorporate lower-purity cosmetic-grade material through regional distributors serving mid-tier formulators in India and Southeast Asia.
By volume, Food Additives leads. By growth pace, Pharmaceuticals is ahead.
Form:
Handling economics and precision dosing requirements split demand between bulk powder systems and liquid emulsions, with granule and emulsion formats occupying niche positions.
- Powder:Free-flowing crystalline material dominates industrial bakery procurement for bulk silo handling and automated dosing. German bread manufacturers specify powder form for integration with existing flour handling infrastructure.
- Liquid:Pre-dissolved emulsions serve boutique cosmetic laboratories requiring precision micro-dosing without dust exposure controls. French skincare formulators in the Provence-Alpes-Côte d'Azur cluster favor liquid delivery for small-batch flexibility.
- Granule:Low-dust agglomerated particles bridge powder flowability and liquid dispersion speed for mid-scale pharmaceutical tablet coating operations.
- Emulsion:Pre-hydrated concentrates target ready-to-use cosmetic formulations where water-phase incorporation must occur without heating cycles.
Powder captures the largest shipment volumes. Liquid formats are expanding most quickly among premium cosmetic channels.
Grade:
Purity thresholds determine regulatory access and pricing power, with pharmaceutical certification creating the steepest barriers to supplier qualification.
- Food Grade:Codex Alimentarius-compliant material with acid value below 5 mg KOH per gram serves packaged baked goods and confectionery. EFSA food-contact evaluations are tightening migration limit compliance documentation requirements.
- Pharmaceutical Grade:USP-NF monograph conformance with residual solvent limits below ICH Q3C thresholds qualifies material for oral and parenteral drug applications. This grade claims the fastest share gains as biologic drug-delivery vehicle demand accelerates.
- Cosmetic Grade:Intermediate purity tier meeting EC 1223/2009 cosmetic regulation specifications for rinse-off and leave-on applications.
- Industrial Grade:Technical specification material for lubricant and textile processing auxiliary applications outside regulated consumer channels.
Food Grade moves the highest tonnages. Pharmaceutical Grade is climbing the fastest on value expansion.
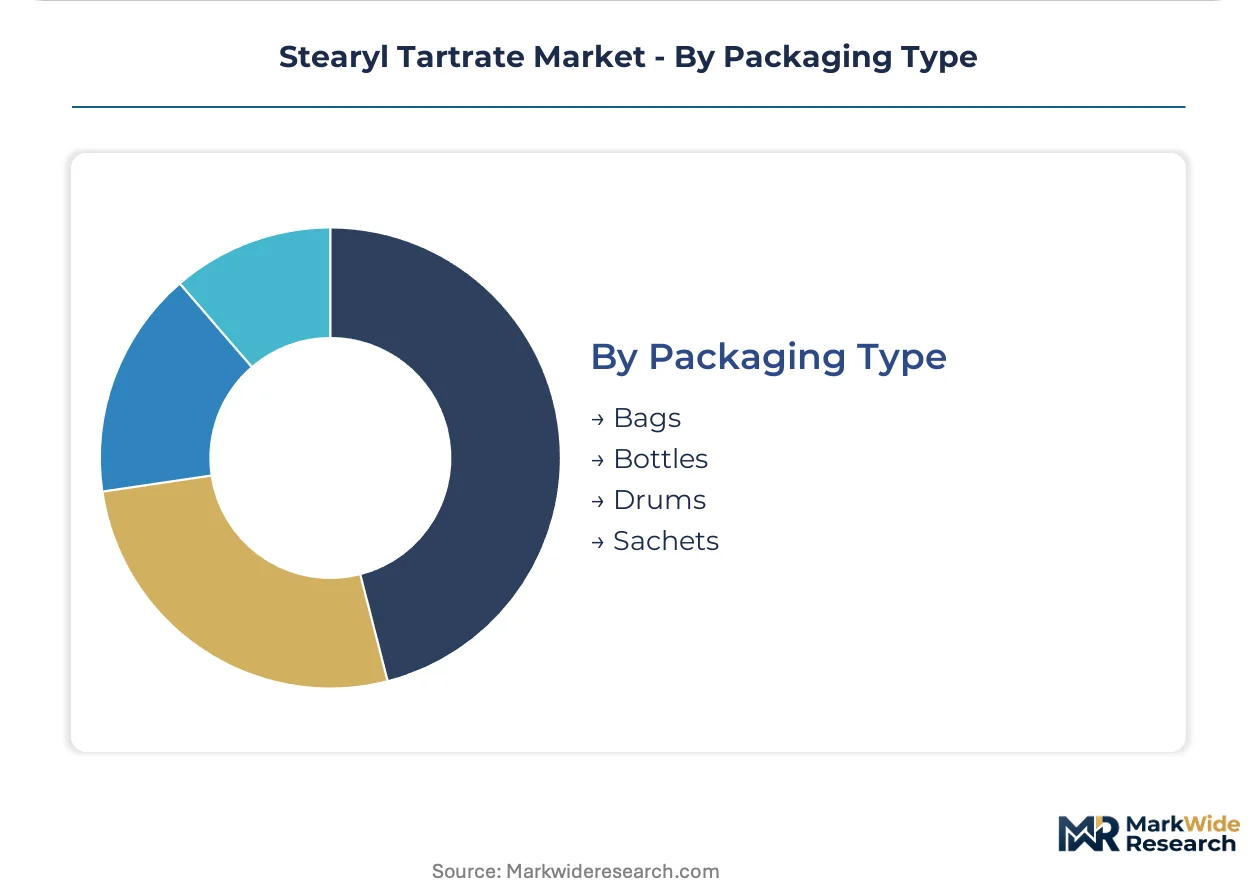
Packaging Type:
Scale economics and contamination risk management drive format selection, with bulk drums serving manufacturing plants and sachets targeting laboratory sampling workflows.
- Bags:Multi-wall paper or polyethylene sacks holding 25 kg serve industrial bakeries with high-throughput silo filling operations and established dust control systems.
- Bottles:HDPE containers from 500 ml to 5 liters supply cosmetic laboratories with manageable handling weights and resealable storage for liquid emulsions.
- Drums:200-liter steel or fiber drums dominate pharmaceutical and food-grade bulk shipments to manufacturing facilities with dedicated raw material warehouses.
- Sachets:Single-use foil pouches containing 10-100 grams support quality control sampling and small-batch pharmaceutical formulation development.
Drums lead in total volume throughput. Sachets are gaining share fastest in pharmaceutical sampling channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German oleochemical clusters command pricing leverage over Asian feedstock-dependent competitors, while Indian tariff structures compress margins for non-certified importers. This asymmetry shapes procurement routing and capacity investment across the forecast window.
Germany
Industrial bakeries in North Rhine-Westphalia and cosmetic formulators in Hamburg drive food-grade and cosmetic-grade demand. REACH registration requirements under ECHA enforcement create supply bottlenecks for non-integrated distributors. The Cologne-Düsseldorf corridor hosts integrated fatty alcohol-to-ester processing chains that shorten lead times for European customers.
United States
Multinational food manufacturers and pharmaceutical compounders anchor consumption across the Midwest and Northeast. FDA food-contact substance notifications under CFR 172.836 streamline clean-label positioning for packaged baked goods. Chicago-area emulsifier technology centers sustain formulation partnerships with industrial bakery groups.
India
Bakery sector expansion in Maharashtra and Gujarat fuels food additive procurement growth. BIS certification requirements for food additives create compliance barriers for unregistered imports. The Mumbai-Pune industrial corridor concentrates oleochemical processing capacity serving domestic and export markets.
France
Cosmetic laboratories in Provence-Alpes-Côte d'Azur and Île-de-France prioritize liquid emulsion formats for precision dosing. EC 1223/2009 cosmetic regulation specifications govern purity thresholds for leave-on applications. Lyon-based specialty distributors consolidate supplier qualification lists to REACH-registered producers.
Belgium
Biscuit producers and industrial bakeries in Flanders specify stearyl tartrate through direct procurement frameworks rather than spot purchasing. EFSA food-contact evaluations tighten migration limit documentation for packaged goods. The Antwerp-Ghent logistics hub channels bulk powder shipments to consolidated bakery groups.
Stearyl Tartrate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated oleochemical majors controlling feedstock economics and specialty ester formulators commanding premium-grade certification pathways. The vendor base concentrates around backward-integrated producers with captive fatty alcohol supply and mid-scale continuous processing adopters collapsing unit capital intensity. Three archetypes dominate: integrated oleochemical conglomerates with renewable feedstock control, specialty ester houses with pharmacopeial certification capacity, and regional distributors with regulatory dossier completion. Competitive moves center on continuous esterification technology licensing and REACH registration consolidation to secure European market access.
Among integrated oleochemical majors, Croda International Plc and Stepan Company exemplify archetypes with differentiated positioning strategies. Evonik Industries AG occupies a position within the pharmaceutical-grade certification tier, anchoring premium positioning through compendial conformance capabilities. These three entities represent the structural segmentation between feedstock-integrated volume players and purity-specialized margin capturers.
| Leading Market Players |
|---|
| Oleon NV |
| Stepan Company |
| Croda International Plc |
| Evonik Industries AG |
| KLK OLEO |
| Emery Oleochemicals |
| IOI Oleochemicals |
| Acme Synthetic Chemicals |
| Faci Asia Pacific Pte Ltd |
| Others |
Supply Flow & Price Mechanics
Continuous esterification technology adoption by mid-scale German producers is displacing traditional batch sulfuric acid processes, simultaneously compressing unit capital requirements and redrawing supply geography toward North Rhine-Westphalia oleochemical clusters. This substitution dynamic elevates REACH-registered integrated manufacturers while eroding pricing power among import-dependent distributors lacking backward integration into renewable fatty alcohol feedstocks.
Pricing Analysis
Certification-grade customization premiums separate pharmaceutical-grade batches from standard food-grade material. Three-tier pricing structure across pharmaceutical, food, and cosmetic grade levels reflects divergent purity thresholds and regulatory documentation burdens. Cost compression in food-grade tiers intensifies because industrial bakeries negotiate annual framework agreements with consolidated volume commitments. Pharmaceutical compounders exhibit least price sensitivity due to parenteral compatibility requirements and supplier qualification switching costs.
Supply Chain Analysis
Germany, Malaysia, and India anchor stearyl tartrate production across integrated oleochemical majors, palm kernel oil processing hubs, and emerging specialty ester formulators respectively. Stearic acid feedstock draws from Malaysian palm oil derivatives, tartaric acid from wine industry byproduct streams, and renewable fatty alcohols from European oleochemical cracking. Single-source vulnerability concentrates in REACH registration holders, where only a handful of EU-based producers maintain complete substance dossiers. Distribution runs through direct procurement frameworks between industrial bakeries and oleochemical producers, bypassing traditional specialty chemical distributors in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats in this market, as REACH dossier completion and pharmacopeial certification pathways impose years-long qualification timelines that lock out unregistered competitors.
For Market Incumbents: Secure REACH registration consolidation through Annex XV dossier updates to defend against supply bottleneck exploitation by emerging enzymatic esterification specialists. Prioritize backward integration into renewable fatty alcohol feedstocks to neutralize palm kernel oil price volatility and sustain margin control across cosmetic-grade batches. Channel control through dedicated emulsifier technology centers sustains formulation partnerships with multinational food manufacturers. For New Entrants and Emerging Players: Lead with continuous fixed-bed reactor systems to collapse unit capital intensity versus legacy batch operations, targeting mid-scale pharmaceutical-grade production where certification scarcity commands premium positioning. India BIS certification pathway offers most penetrable regulatory entry point, as early compliance with Bureau of Indian Standards food additive specifications opens access to subcontinent bakery expansion. Go-to-market angle should emphasize clean-label emulsifier credentials aligned with EFSA migration limit tightening. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated oleochemical majors with captive feedstock supply and completed REACH registrations. Long-term viability over the coming decade hinges on regulatory dossier depth rather than production cost alone. Acquisition target archetype: mid-scale continuous processing adopters with pharmaceutical-grade certification capacity but lacking backward integration. Signal to watch is pharmacopeial monograph harmonization progress across USP, EP, and JP specifications, which would force multi-standard inventory rationalization and supplier list consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Fatty Alcohols | Croda International Plc secures margin control across cosmetic-grade batches through captive feedstock supply. |
| Continuous Esterification Technology Licensing | Fixed-bed reactor adoption collapses unit capital intensity for mid-scale specialty ester producers. |
| REACH Registration Consolidation | Annex XV dossier completion secures European market access against import-dependent distributor gaps. |
| Pharmaceutical-Grade Certification Investment | USP-NF monograph conformance unlocks parenteral drug-delivery vehicle demand expansion. |
| Direct Procurement Framework Expansion | Annual agreements between industrial bakeries and oleochemical producers bypass distributor markups. |
Methodological Framework
Desk research of customs and trade flow databases, pharmacopeial monograph repositories, and ECHA registration filings preceded structured interviews with oleochemical plant managers, cosmetic formulation R&D directors, pharmaceutical procurement leads, and specialty chemical distribution channel partners. Primary fieldwork across Germany, India, and the United States validated secondary data on esterification capacity configurations and grade-specific pricing spreads. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers to ensure cross-verification of volume and value outputs.
Variance decomposition across grade tier, end-use industry, packaging format, and regional production hub dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segmented growth rate aggregation rather than single-point extrapolation. Key forecast inputs included REACH evaluation timeline assumptions, palm kernel oil price trajectory modeling, and pharmaceutical parenteral compatibility demand curves.
Forecasts assume regulatory continuity in REACH enforcement, FDA food-contact substance notification pathways, and BIS certification requirements; material policy shifts would require re-modeling of supplier qualification timelines and migration limit compliance costs. Specific risk factors encompass tartaric acid supply seasonality from wine industry byproduct dependence and enzymatic esterification technology disruption of batch economics. Recalibration cycles align with material shifts in pharmacopeial monograph harmonization progress and clean-label mandate adoption rates across EFSA and FDA jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Tallow Amine Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Esters Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Squalane Market
Oleochemicals
Partially Hydrogenated Oil Market
Oleochemicals
Oleyl Alcohol Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
Ethylhexyl Cocoate Market