
 Oleochemicals Market | 2026-2036
Oleochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Oleochemicals Market Intelligence
The EU Green Deal is repositioning oleochemical procurement standards across European personal care and detergent supply chains. Wilmar International leverages its integrated palm oil refining network across Southeast Asia to secure feedstock cost advantages. Cargill Incorporated sustains North American market presence through soybean-derived fatty acid specialization. Emery Oleochemicals anchors its competitiveness in high-purity fatty alcohols for surfactant applications.
Oleochemicals comprise fatty acids, alcohols, esters, and glycerol derived from plant and animal fats through hydrolysis, transesterification, or hydrogenation, typically operating at 80-200°C with alkali or metal oxide catalysts to yield products with carbon chain lengths of C8-C22 for industrial functionalization. These compounds serve as renewable substitutes for petroleum-derived chemicals in surfactants, lubricants, and polymer additives. Fatty acids dominate product type volumes due to their ubiquity in soap and detergent manufacturing, while fatty alcohols command premium positioning in personal care formulations. Methyl esters represent the fastest-expanding application segment as biodiesel mandates expand across transport energy markets.
REACH compliance in Europe, EPA biofuel certification in the United States, and BIS quality standards in India collectively shape oleochemical purity specifications and cross-border market access conditions. ECHA substance evaluation protocols are tightening trace contaminant thresholds for glycerol and fatty acid derivatives used in cosmetic applications. Stakeholders must monitor feedstock certification fragmentation between RSPO mass balance and segregated supply chains when configuring procurement strategies.
Market Dynamics
The EU Green Deal's chemical sector decarbonization mandates are compressing qualification timelines for bio-based feedstocks, forcing personal care and detergent formulators to reconfigure procurement architectures around certified sustainable palm and soybean derivatives.
Growth Catalysts
- EU Green Deal mandates:Chemical sector decarbonization protocols in Europe are accelerating bio-based feedstock qualification, expanding oleochemical sourcing volumes for surfactant manufacturers.
- Personal care formulators:Plant-derived surfactants are replacing petrochemical alternatives in shampoo and skincare formulations, pulling fatty alcohol demand upward.
- Indonesia-Malaysia clusters:Integrated palm oil processing infrastructure concentrates cost-competitive feedstock supply, anchoring regional production gravity.
Market Restraints
- Feedstock price volatility:Crude palm oil and soybean oil futures exhibit pronounced cyclicality, compressing margin stability for fatty acid producers.
- RSPO certification fragmentation:Mass balance versus segregated supply chain standards create procurement complexity, raising compliance overhead for cosmetic-grade glycerol.
- Technical substitution limits:Petrochemical-derived linear alkylbenzene sulfonates retain cost advantages in heavy-duty detergent applications, slowing displacement rates.
Strategic Opportunities
- Biodiesel mandate expansion:Transport energy regulations in Southeast Asia and Latin America are opening methyl ester demand corridors for oleochemical producers.
- High-purity fatty alcohols:Personal care segments in South Korea and Japan are specifying cosmetic-grade C12-C14 alcohols, creating premium pricing tiers.
- Enzymatic transesterification:Lipase-catalyzed processing at ambient temperatures is converging with continuous flow reactor design, enabling energy cost reductions.
Industry Challenges
- REACH substance evaluation timelines:ECHA protocols for glycerol and fatty acid derivative contaminants are extending certification cycles, delaying market access.
- Hydrolysis catalyst R&D gaps:Specialized chemical engineers with alkali and metal oxide catalyst expertise remain scarce, constraining process optimization.
- Legacy equipment retrofit costs:Batch reactor systems require substantial capital outlay for continuous flow conversion, burdening mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oleochemicals Market |
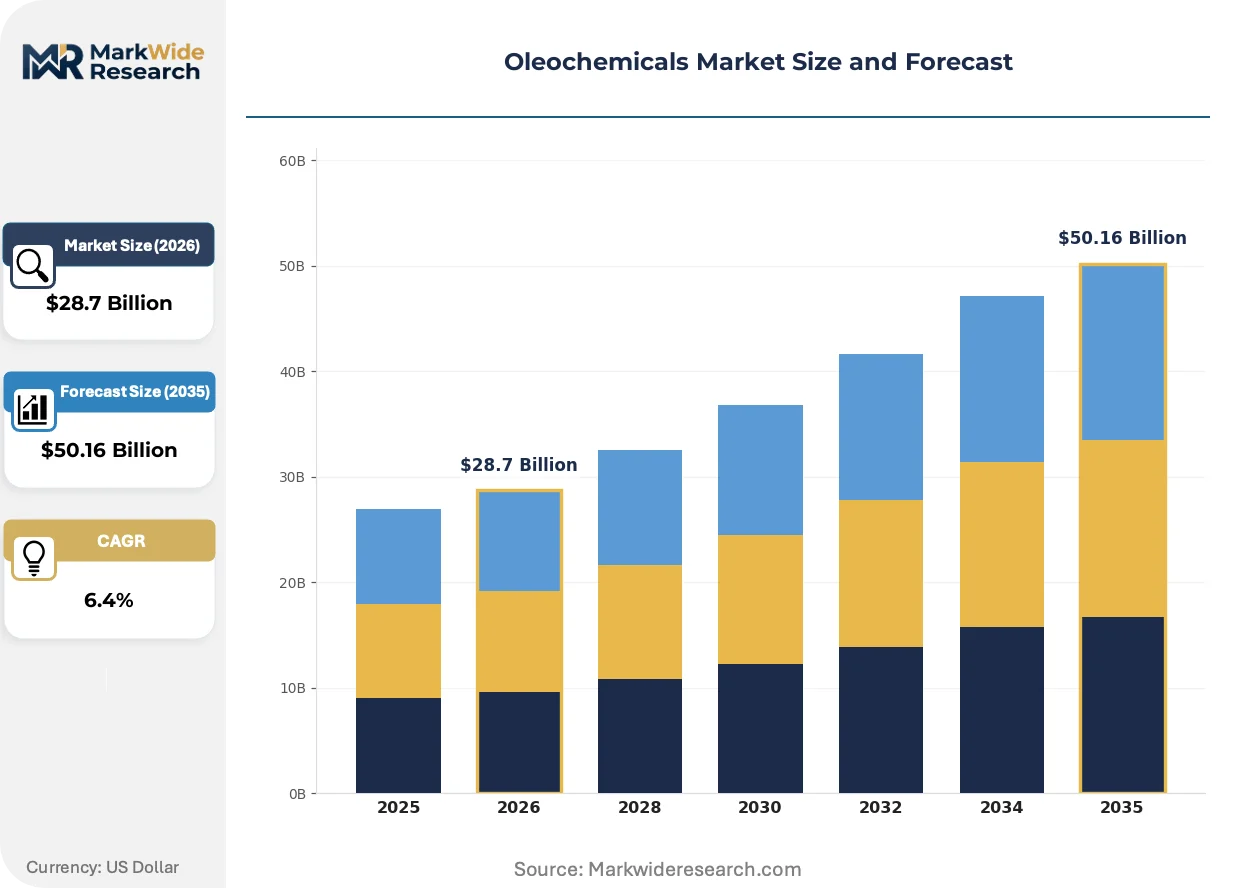
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fatty Acids, Glycerol, Methyl Esters, Fatty Alcohols, Soap Noodles Application: Personal Care, Detergents, Lubricants, Biofuels, Food Additives End User Industry: Cosmetics Manufacturers, Chemical Industry, Automotive Lubricants, Renewable Energy, Food Processing Form: Liquid, Powder, Granules, Flakes |
| Companies Covered | Wilmar International Ltd., Cargill Incorporated, Emery Oleochemicals, Akzo Nobel N.V., Evonik Industries AG, KLK Oleo, BASF SE, Godrej Industries, IOI Oleochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oleochemicals Market Strategic Shifts & Innovations
Enzymatic processing architectures and regulatory tightening are compressing traditional process economics while opening premium application segments for oleochemical derivatives.
Enzymatic transesterification using immobilized lipase catalysts is rewriting energy efficiency benchmarks in fatty acid methyl ester production. Southeast Asian integrated refiners are piloting these systems at commercial scale. The technology is rewriting capital allocation patterns, redirecting investment from thermal cracking units toward biocatalytic platforms.
REACH substance evaluation protocols are tightening trace contaminant thresholds for cosmetic-grade glycerol and fatty acid derivatives. ECHA's expanded substance evaluation workload is extending registration timelines. Personal care formulators in Germany and France are responding by qualifying segregated RSPO supply chains ahead of regulatory deadlines.
Direct sourcing contracts between personal care brands and Indonesian-Malaysian refiners are displacing multi-tier distributor networks. Specialty chemical distributors in Europe are losing volume to backward-integrated formulators. This pattern is most visible in the Netherlands and Belgium, where detergent manufacturers are establishing captive supply relationships with Southeast Asian producers.
Oleochemicals Market Segmentation
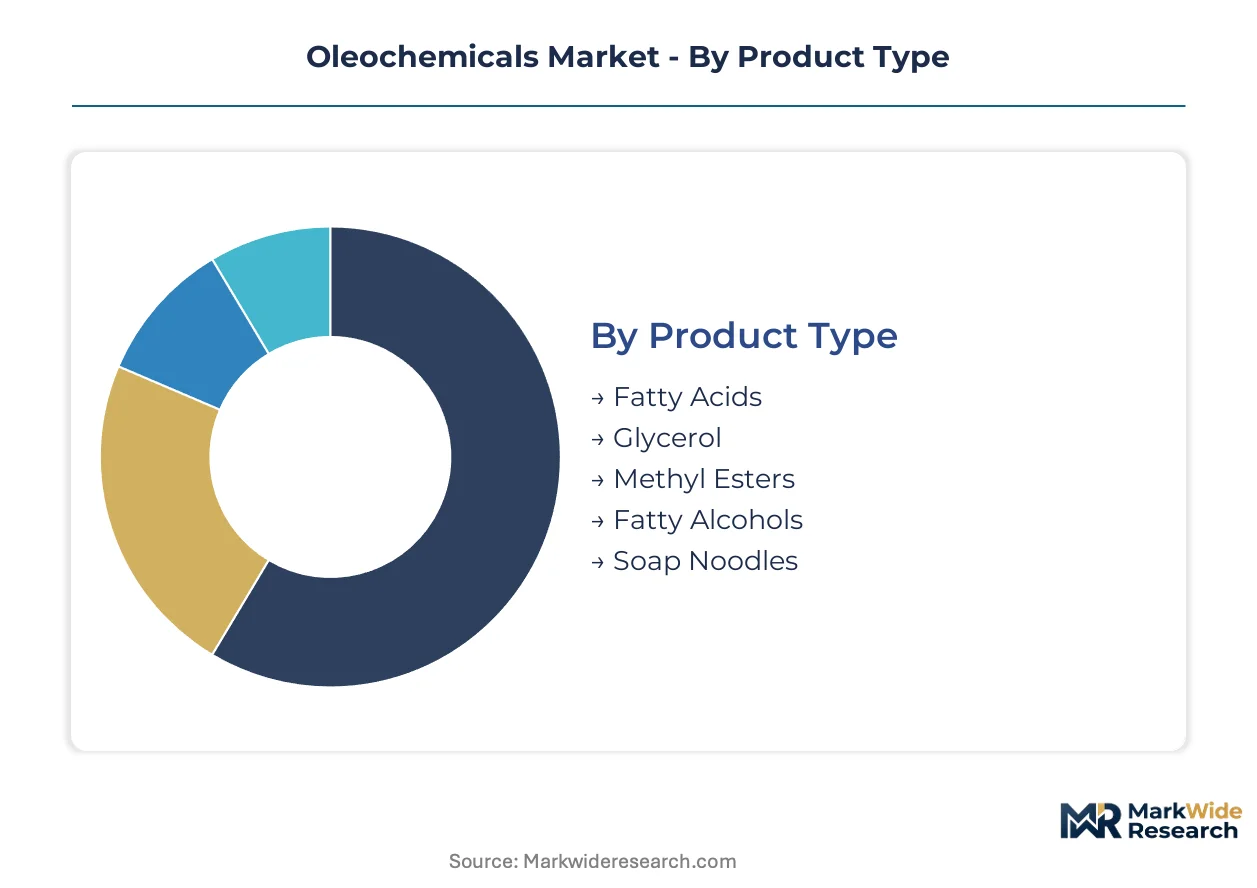
Oleochemical procurement patterns diverge sharply across product chemistry and end-use specifications. Formulators select feedstock derivatives based on carbon chain length, purity grade, and certification status rather than commodity pricing alone.
Product Type:
Buyers prioritize functional performance and downstream compatibility when selecting oleochemical derivatives.
- Fatty Acids:Saturated and unsaturated carboxylic acids with C8-C22 chain lengths serve as foundational intermediates for soap manufacturing and lubricant additives. Detergent producers in Germany and the United States consume bulk volumes of stearic and oleic acid grades, though margin compression from palm oil price cyclicality constrains long-term contract flexibility.
- Fatty Alcohols:Hydrogenated derivatives of fatty acids yielding C12-C18 alcohols function as non-ionic surfactant precursors for premium personal care formulations. South Korean cosmetics manufacturers specify cosmetic-grade C12-C14 fractions, creating supply scarcity for high-purity segregated RSPO-certified material.
- Glycerol:Trihydric alcohol byproduct of transesterification processes, refined to USP or technical grades for pharmaceutical and industrial applications.
- Methyl Esters:Fatty acid methyl esters produced via methanolysis of triglycerides for biodiesel and solvent applications.
- Soap Noodles:Pre-saponified fatty acid salts used as direct feedstock for finished bar soap manufacturing.
Volume sits with Fatty Acids; growth tilts toward Fatty Alcohols.
Application:
End-use performance requirements dictate purity thresholds and certification complexity across demand segments.
- Personal Care:Shampoo, skincare, and cosmetic formulations require cosmetic-grade fatty alcohols and glycerol with tight contaminant specifications. ECHA substance evaluation protocols for glycerol derivatives are extending qualification timelines for European formulators.
- Biofuels:Fatty acid methyl esters blended into diesel transportation fuels under mandate programs in Indonesia and Brazil. Transport energy regulations across Southeast Asia and Latin America are expanding methyl ester offtake volumes faster than stationary power applications.
- Detergents:Household and industrial cleaning products utilize fatty acids and alcohols as primary surfactant feedstocks.
- Lubricants:Biodegradable base stocks and additives for automotive and industrial machinery applications.
- Food Additives:Emulsifiers and processing aids derived from edible-grade oleochemical feedstocks.
Revenue concentrates in Personal Care; steepest expansion trajectory belongs to Biofuels.
End User Industry:
Procurement sophistication varies with regulatory exposure and brand positioning requirements.
- Cosmetics Manufacturers:Multinational personal care brands specify segregated RSPO supply chains and REACH-compliant glycerol derivatives. Direct sourcing contracts with Indonesian refiners are displacing European distributor networks in the Netherlands and Belgium.
- Renewable Energy:Biodiesel blenders and renewable diesel producers purchase methyl esters under long-term offtake agreements.
- Chemical Industry:Intermediate processors converting oleochemicals into surfactants, polymer additives, and specialty esters.
- Automotive Lubricants:Formulators of biodegradable and high-performance engine oils.
- Food Processing:Manufacturers of emulsifiers, anti-foam agents, and release agents for edible applications.
Margin capture favors Cosmetics Manufacturers; volume scaling aligns with Renewable Energy.
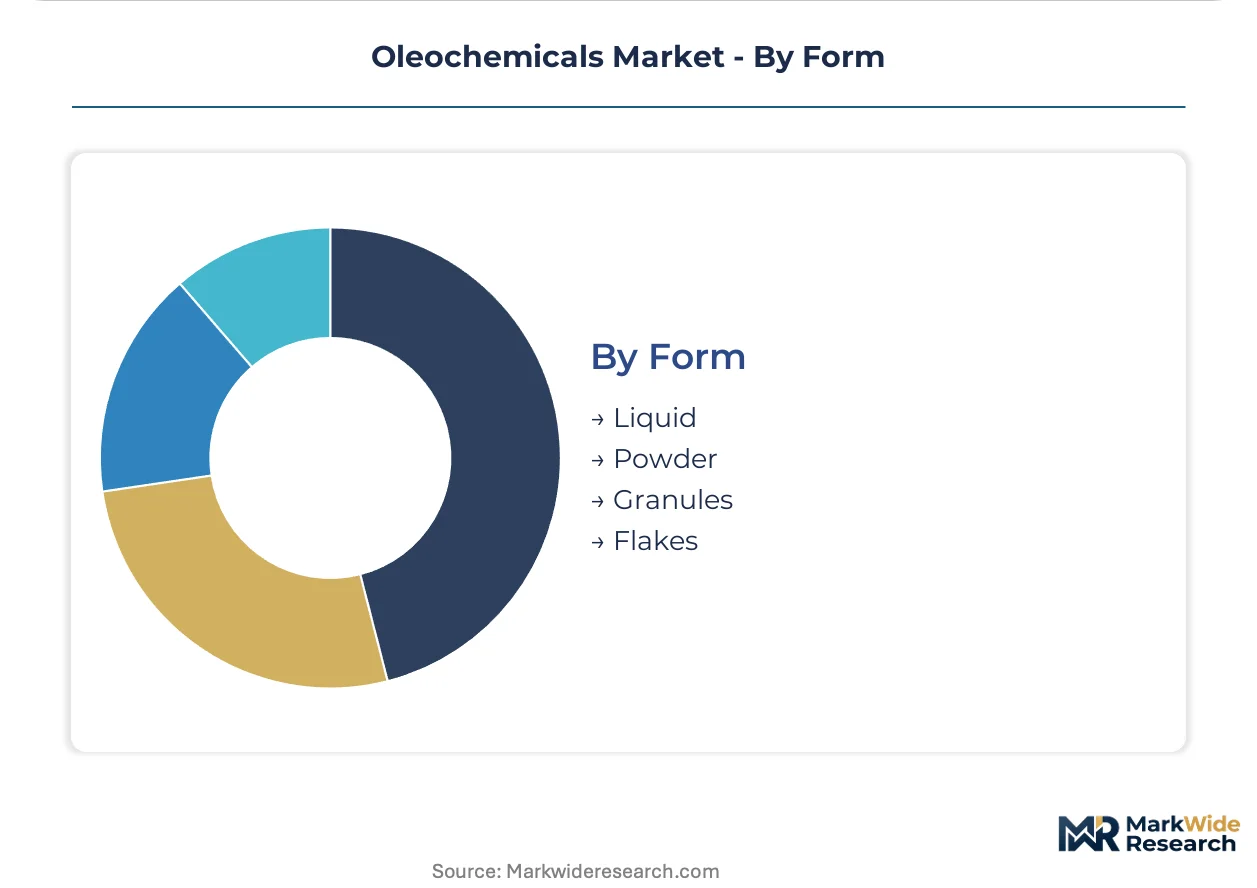
Form:
Physical state selection balances handling economics, dissolution kinetics, and storage stability.
- Liquid:Bulk fatty acids and glycerol shipped in tank containers for continuous process integration. Indonesian integrated refiners leverage liquid form for cost-efficient export to European detergent manufacturers.
- Flakes:Solidified fatty alcohols and acids enabling precise metering in batch cosmetic compounding. Japanese and South Korean personal care formulators prefer flaked material for controlled dissolution in heated vessels.
- Powder:Micronized derivatives for rapid dispersion in dry blend applications.
- Granules:Free-flowing solid forms for intermediate bulk handling and reduced dust generation.
Throughput dominance rests with Liquid; premium positioning concentrates in Flakes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johor Bahru anchors Southeast Asian oleochemical production through integrated palm oil refining corridors connecting Malaysian estates to Port of Tanjung Pelepas export terminals. Rotterdam and Hamburg serve as European distribution nodes where EU Green Deal compliance protocols reshape import specifications. Texas Gulf Coast petrochemical complexes are retrofitting for bio-based feedstock processing.
Indonesia
Surabaya and Medan house integrated palm oil clusters converting crude palm oil into fatty acids and methyl esters for European detergent manufacturers. The national biofuel mandate program expands domestic methyl ester absorption while reserving export volumes. Dumai port facilities on Sumatra's eastern coast process feedstock from Riau province plantations for shipment to Rotterdam and Hamburg.
Malaysia
Klang Valley refiners supply cosmetic-grade fatty alcohols to South Korean and Japanese personal care formulators under segregated RSPO certification protocols. The Malaysian Palm Oil Board enforces sustainability traceability standards that exceed baseline international requirements. Pasir Gudang industrial zones near Johor Bahru concentrate hydrogenation capacity for C12-C18 alcohol production.
Germany
Düsseldorf and Hamburg-based formulators source REACH-compliant glycerol derivatives for shampoo and skincare applications under tightening ECHA substance evaluation timelines. The EU Green Deal chemical sector decarbonization mandates compress bio-based feedstock qualification windows. BASF Ludwigshafen operations integrate oleochemical intermediates into surfactant and polymer additive production.
United States
Iowa and Illinois soybean processing facilities supply fatty acid feedstocks to Chicago-area lubricant and detergent manufacturers. EPA biofuel certification requirements shape methyl ester purity specifications for transport energy blending. Texas Gulf Coast chemical complexes near Houston are adding transesterification capacity to capture biodiesel mandate growth across Latin American export markets.
Netherlands
Rotterdam port terminals serve as European entry points for Indonesian and Malaysian oleochemical shipments, with direct sourcing contracts displacing traditional distributor networks. The Dutch national implementation of EU Green Deal protocols accelerates segregated RSPO supply chain adoption. Amsterdam-based personal care brands establish backward integration into Southeast Asian refining capacity.
Oleochemicals Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tier and purity grade dimensions. The market structures around three archetypes: integrated plantation-refiners controlling feedstock origination, specialty chemical houses commanding cosmetic-grade fatty alcohol premiums, and diversified agribusiness operators leveraging oilseed crushing scale. Consolidation pressures concentrate among mid-scale batch producers lacking continuous flow reactor technology. Competitive moves center on backward integration into plantation assets and enzymatic processing licensing.
Among integrated plantation-refiners, Wilmar International Ltd. and IOI Oleo occupy positions exemplifying Southeast Asian feedstock control. Cargill Incorporated represents the agribusiness archetype with North American oilseed processing scale. Specialty chemical positioning concentrates with Emery Oleochemicals and Evonik Industries AG, where high-purity fatty alcohol specialization commands pricing premiums in personal care applications. Godrej Industries anchors Indian market presence through domestic oleochemical manufacturing infrastructure.
| Leading Market Players |
|---|
| Wilmar International Ltd. |
| Cargill Incorporated |
| Emery Oleochemicals |
| Akzo Nobel N.V. |
| Evonik Industries AG |
| KLK Oleo |
| BASF SE |
| Godrej Industries |
| IOI Oleochemical |
| Others |
Cost & Logistics Intelligence
Specialized chemical engineers with alkali and metal oxide catalyst expertise concentrate in Germany and the Netherlands, where labor-cost differentials between these European technical centers and Southeast Asian integrated refiners drive pricing-tier spreads across fatty acid and fatty alcohol grades.
Pricing Analysis
Yield-based pricing anchors contract structures for cosmetic-grade fatty alcohols sold to South Korean and Japanese personal care formulators. Three-tier pricing structure across premium, standard, and economy levels separates segregated RSPO-certified material from mass balance and uncertified grades. Pricing pressure stems from crude palm oil futures cyclicality compressing margins for Indonesian fatty acid producers. Detergent manufacturers exhibit highest price sensitivity due to commodity surfactant substitution options, while cosmetics manufacturers absorb premiums for REACH-compliant glycerol derivatives.
Supply Chain Analysis
Direct-to-formulator channels displace European distributor networks as Dutch and Belgian personal care brands establish captive supply relationships with Malaysian and Indonesian refiners. Raw material flows draw from crude palm oil plantations in Riau province and Sumatra, plus soybean crushing operations across Iowa and Illinois. Supply chain risk centers on RSPO certification fragmentation between mass balance and segregated standards. Distribution runs through Rotterdam and Hamburg port terminals serving as European entry points for Southeast Asian shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's chemical sector decarbonization mandates function as a cost-of-compliance barrier, creating a moat for producers with pre-qualified bio-based feedstock certifications while raising entry costs for uncertified competitors.
For Market Incumbents: To counter enzymatic transesterification technology disruption from Southeast Asian pilot facilities, BASF and Evonik should deepen backward integration into segregated RSPO supply chains while licensing continuous flow reactor designs to mid-scale batch producers seeking retrofit pathways.
For New Entrants and Emerging Players: Enter via high-purity C12-C14 fatty alcohol segments serving South Korean cosmetics manufacturers, where supply scarcity for cosmetic-grade segregated RSPO material creates white-space opportunity alongside enzymatic processing partnerships with Indonesian integrated refiners.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty chemical houses commanding cosmetic-grade fatty alcohol premiums given ECHA substance evaluation timeline extensions, with long-term viability hinging on REACH compliance infrastructure; monitor ECHA substance evaluation backlog clearance as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Wilmar International secures feedstock cost advantages through Riau province estate control. |
| Enzymatic Processing Licensing | Immobilized lipase catalyst technology redirects capital from thermal cracking toward biocatalytic platforms. |
| Segregated RSPO Supply Chain Qualification | Amsterdam-based personal care brands establish direct sourcing ahead of EU Green Deal deadlines. |
| Continuous Flow Reactor Conversion | Mid-scale batch producers reduce energy costs through retrofit capital deployment. |
| Long-term Methyl Ester Offtake Agreements | Biodiesel blenders in Indonesia and Brazil lock in transport energy mandate volumes. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, cross-referenced with primary interviews involving plant managers at Malaysian and Indonesian refiners, procurement leads at German detergent manufacturers, technical R&D directors in enzymatic processing, and distribution channel partners in Rotterdam. Secondary sources included Malaysian Palm Oil Board sustainability reports, ECHA substance evaluation databases, EPA biofuel certification records, and SEC filings from listed agribusiness operators. Bottom-up capacity assessments and top-down demand modeling underwent iterative triangulation.
Data-stream reconciliation across production volume disclosures, trade flow records, and end-use consumption surveys shaped the analytical framework across the analysis window. Segmentation dimensions encompassed product chemistry, application performance requirements, certification tier, carbon chain length, and regional production hub clustering. CAGRs derived from trend extrapolation of feedstock cost trajectories, regulatory mandate expansion rates, and substitution elasticity estimates for petrochemical surfactants.
Forecast precision tightens around the base case; tail outcomes carry wider variance under crude palm oil price volatility extremes and ECHA registration timeline delays. Forecasts reflect assumptions regarding EU Green Deal implementation pacing and biodiesel mandate adherence across Southeast Asia and Latin America. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Ethylene Bis Stearamide Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market