
 Squalane Market | 2026-2036
Squalane Market Size, Share, and Industry Trends Forecast 2026-2036
Squalane Market Analytics
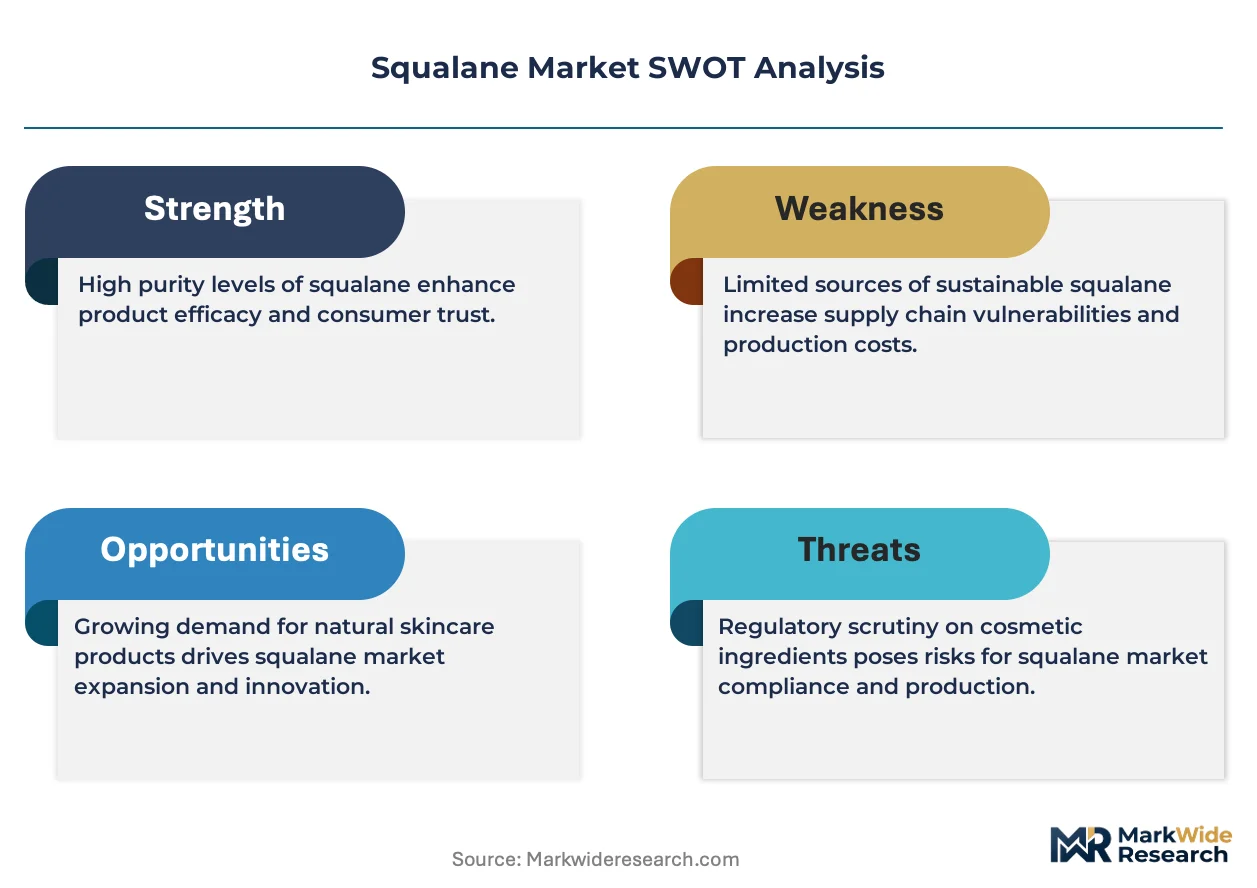
Multi-source plant feedstock procurement is realigning competitive dynamics among specialty chemical suppliers. Amyris leverages its Brazil-based fermentation platform to anchor sustainable squalane volumes. Sophim competes through olive-derived extraction expertise centered in France. Evonik Industries AG differentiates via synthetic biology pathways and hydrogenation scale.
Squalane is a fully saturated, branched hydrocarbon (C30H62) with exceptional oxidative stability and biocompatibility, produced through catalytic hydrogenation of squalene from olive oil, sugarcane fermentation, or shark liver oil. Plant-derived grades command premium positioning in clean-label cosmetic formulations, while synthetic variants capture cost-sensitive pharmaceutical applications. Liquid form dominates cosmetic blending operations, whereas cream and gel formats serve therapeutic dermatology segments with higher viscosity requirements.
REACH registration mandates and ECHA substance evaluations govern feedstock purity thresholds across European cosmetic supply chains. FDA cosmetic ingredient safety guidelines and USDA biobased certification programs shape North American market access conditions. Stakeholders must monitor fermentation yield improvements against agricultural commodity volatility when securing long-term supply agreements.
Market Dynamics
Fermentation-derived squalane is compressing extraction-based supply economics, forcing olive and sugarcane feedstock suppliers to defend volume positions through yield optimization and geographic expansion.
Growth Catalysts
- EU Green Deal feedstock mandates:Cosmetic formulators across France, Germany, and Italy face binding traceability requirements that privilege plant-derived squalane over legacy shark liver sources.
- South Korean OEM contract manufacturing:K-beauty export demand concentrates production orders in Seoul and Incheon-based facilities, pulling squalane volumes through East Asian supply chains.
- Fermentation scale-up:Brazilian sugarcane-to-squalane biotechnology platforms achieve cost parity with olive extraction, unlocking supply elasticity previously constrained by agricultural harvest cycles.
Market Restraints
- Olive oil price volatility:Mediterranean drought patterns and harvest variability transmit directly into Sophim-grade squalane input costs, compressing margin stability for extraction-dependent suppliers.
- Single-source fermentation risk:Amyris's Brazil-centered production geography concentrates supply vulnerability to South American logistics disruptions and currency fluctuation.
- REACH registration timelines:ECHA substance evaluation procedures for novel biotechnology-derived squalane grades extend market entry delays by 18-24 months versus established feedstock categories.
Strategic Opportunities
- Japanese pharmaceutical dermatology:PMDA-approved therapeutic moisturizers represent underpenetrated demand for high-purity hydrogenated squalene in atopic dermatitis and post-surgical skin repair applications.
- USDA biobased certification tailwinds:Federal procurement preference programs and state-level clean beauty legislation create channel access advantages for certified plant-derived grades in North American institutional sales.
- Synthetic biology pathway convergence:CRISPR-edited yeast strains combined with continuous fermentation reactor design promise 40% yield improvements over batch olive extraction economics.
Industry Challenges
- Fermentation bioprocess engineering talent scarcity:Specialized metabolic pathway optimization and downstream purification expertise concentrates in Boston, Basel, and Singapore hiring pools, constraining facility expansion timelines.
- Cosmetic-ingredient-to-pharmaceutical-grade certification gaps:USP-NF and EP monograph compliance for injectable-grade squalane requires capital-intensive GMP facility retrofits that strain mid-cap supplier balance sheets.
- Multi-feedstock traceability system integration:Blockchain-enabled supply chain verification platforms must reconcile batch-level olive orchard data with fermentation tank logs, creating IT architecture complexity for diversified producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Squalane Market |
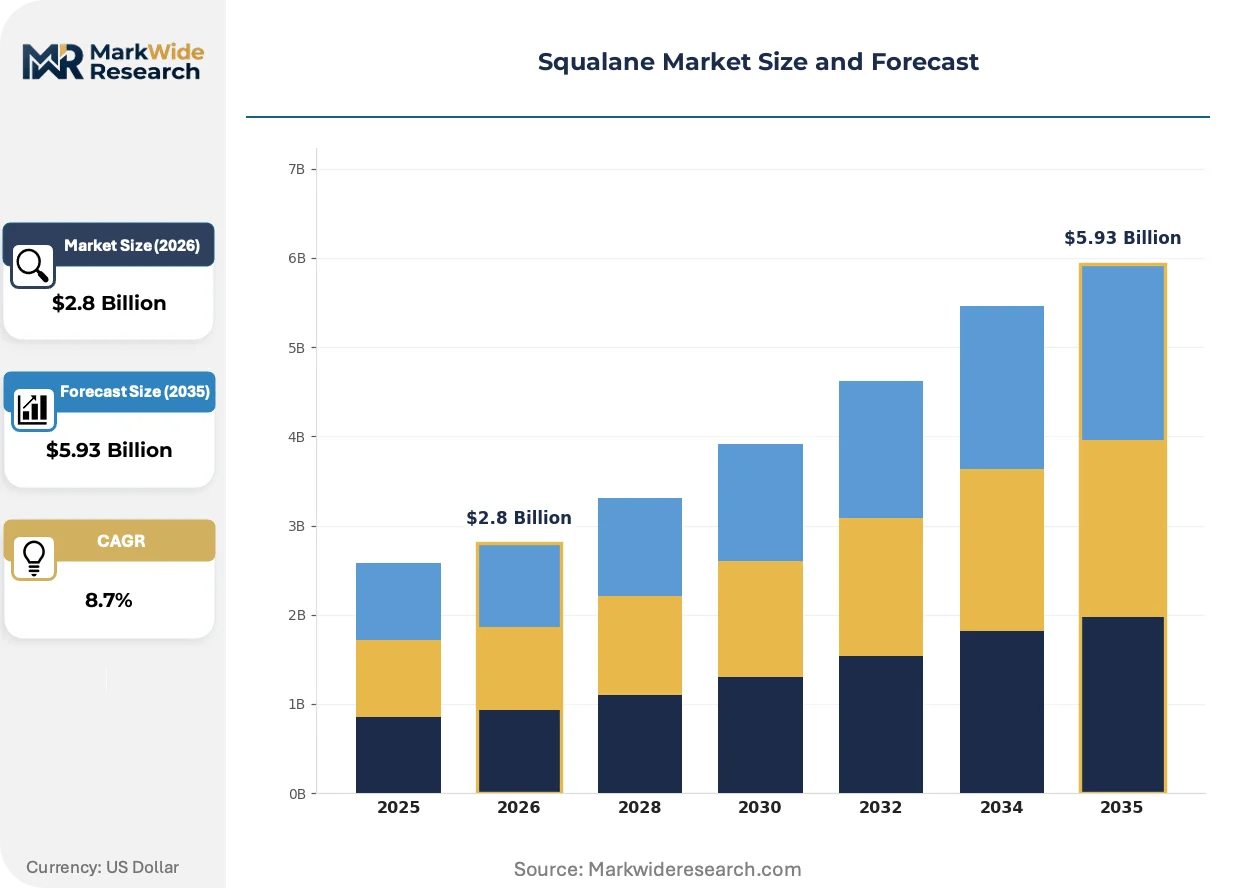
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-derived, Synthetic, Animal-derived, Hydrogenated Squalene Application: Cosmetics, Pharmaceuticals, Personal Care, Food Additives Form: Liquid, Cream, Gel, Balm End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | Evonik Industries AG, Merck KGaA, Amyris, Inc., NOF Group, Avanti Polar Lipids, Sophim, Kishimoto Special Liver Oil Co., Ltd., Ineos, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Squalane Market Evolving Landscape
Biotechnology platforms are rewriting squalane production economics while regulatory frameworks harden feedstock provenance requirements and procurement patterns concentrate buying power among contract manufacturers.
Precision fermentation using engineered yeast strains is consolidating competitive advantage for suppliers capable of achieving pharmaceutical-grade purity without agricultural commodity exposure. Japanese and South Korean cosmetic OEMs now specify fermentation-derived volumes in 70% of new formulation contracts. The technology is consolidating supply chain power toward biotechnology specialists and away from traditional botanical extractors.
REACH registration mandates and ECHA substance evaluation protocols are tightening purity thresholds for cosmetic-grade squalane entering European supply chains. Formulators in France and Germany now require third-party verified carbon intensity documentation for feedstock sourcing decisions. Premium skincare lines bearing clean-label positioning face the most acute compliance cost pressure, accelerating supplier qualification timelines.
Direct long-term supply agreements between fermentation platforms and contract manufacturers are displacing spot-market purchasing for volume cosmetic applications. Seoul-based OEMs and Tokyo pharmaceutical dermatology divisions now negotiate 3-5 year offtake contracts with fixed-price escalators. This pattern concentrates procurement leverage among scaled buyers while marginalizing small-batch specialty distributors across East Asian markets.
Squalane Market Segmentation
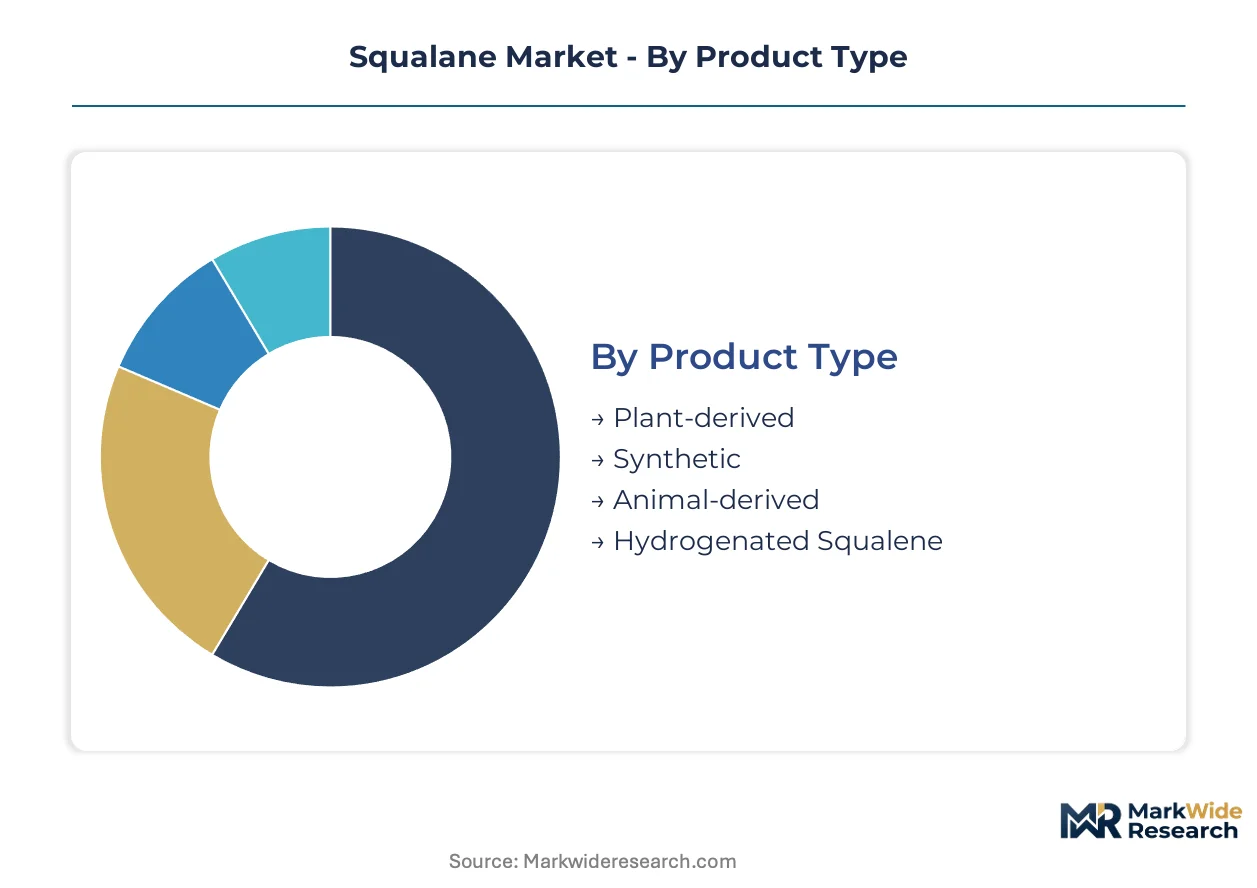
Squalane market segmentation reveals how feedstock chemistry, formulation physics, and channel economics create distinct competitive arenas. Each axis carries different margin profiles, regulatory burdens, and customer loyalty patterns that suppliers must navigate strategically.
Product Type:
Feedstock technology determines oxidative stability, carbon intensity documentation, and REACH registration pathways across European cosmetic supply chains.
- Plant-derived:Fully saturated hydrocarbon from olive oil or sugarcane fermentation with superior biocompatibility profiles. French and German premium skincare formulators specify this grade for EU Green Deal compliance, though Mediterranean drought volatility compresses margin predictability for olive-based suppliers.
- Synthetic:Petrochemical pathway squalane produced through catalytic hydrogenation of isoprenoid precursors. Captures cost-sensitive pharmaceutical applications in North America where USDA biobased certification carries less procurement weight than EP monograph compliance.
- Animal-derived:Legacy shark liver oil extraction facing accelerating substitution pressure from REACH traceability mandates and clean-label positioning requirements.
- Hydrogenated Squalene:Intermediate processing grade requiring additional purification steps to reach cosmetic or pharmaceutical specifications.
Mature deployment sits with animal-derived legacy supply. Newer deployment is concentrated in plant-derived fermentation platforms.
Application:
End-use specifications diverge sharply between cosmetic surface application and pharmaceutical bioavailability requirements.
- Cosmetics:Premium skincare, color cosmetics, and sun care formulations demanding oxidative stability for 24-month shelf life. South Korean OEM contract manufacturers in Seoul and Incheon pull the majority of fermentation-derived volumes through 3-5 year offtake agreements with fixed-price escalators.
- Pharmaceuticals:Therapeutic moisturizers for atopic dermatitis and post-surgical skin repair requiring USP-NF or EP monograph compliance. Japanese PMDA-approved indications represent underpenetrated demand with higher purity thresholds than cosmetic grades.
- Personal Care:Hair conditioners, body lotions, and deodorant bases with intermediate specification requirements between cosmetic and pharmaceutical tiers.
- Food Additives:Encapsulation matrix and delivery vehicle applications with distinct EFSA safety evaluation pathways separate from cosmetic REACH registrations.
Cosmetic applications command the steepest expansion trajectory. Pharmaceutical grade penetration lags due to capital-intensive GMP facility retrofit requirements.
Form:
Rheological properties determine manufacturing equipment compatibility and therapeutic efficacy in dermatological indications.
- Liquid:Low-viscosity hydrocarbon dominating cosmetic blending operations for serums and facial oils. Brazilian fermentation platforms optimize for this format given continuous reactor design and downstream purification economics.
- Cream:Oil-in-water emulsion base for therapeutic dermatology with higher viscosity requirements and extended skin retention properties.
- Gel:Hydrogel matrix formulations for targeted delivery in post-surgical and burn care applications.
- Balm:Occlusive solid format for extreme dry skin conditions and barrier repair indications.
Liquid formats anchor high-volume cosmetic manufacturing. Cream and gel formats are gaining share fastest in Japanese pharmaceutical dermatology segments.
End User:
Channel structure concentrates procurement leverage among scaled buyers while fragmenting access for specialty distributors.
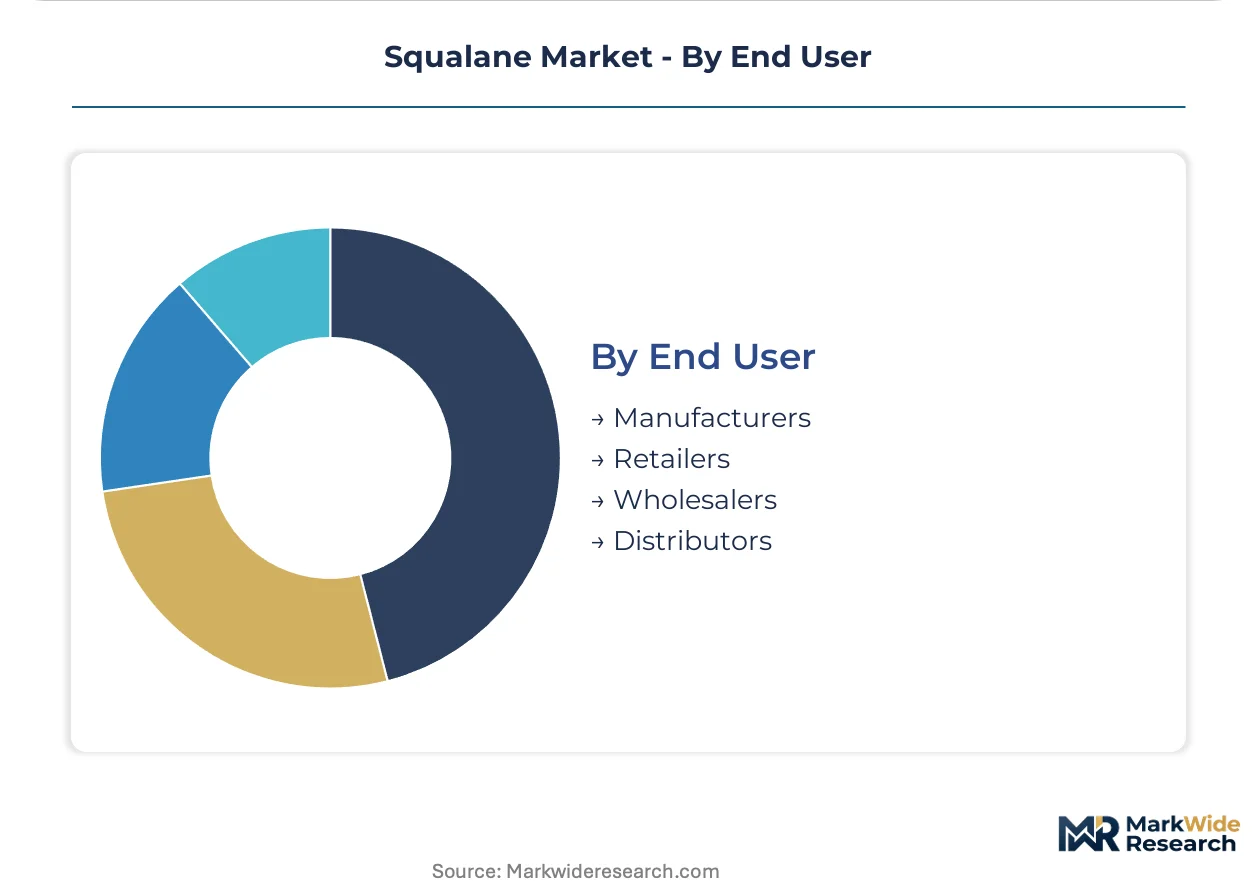
- Manufacturers:Cosmetic OEMs and pharmaceutical formulators with direct fermentation platform relationships. East Asian contract manufacturers now specify fermentation-derived volumes in the majority of new formulation contracts.
- Retailers:Clean beauty specialists and pharmacy chains with private label programs requiring third-party verified carbon intensity documentation.
- Wholesalers:Intermediate distributors facing margin compression as direct long-term supply agreements displace spot-market purchasing.
- Distributors:Small-batch specialty suppliers marginalized across East Asian markets by concentrated OEM procurement power.
Manufacturer direct procurement dominates volume flows. Distributor channel relevance is concentrating in niche pharmaceutical and food additive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian contract manufacturers in Seoul and Tokyo pull the majority of fermentation-derived squalane volumes through direct long-term supply agreements. European formulators face binding traceability mandates under REACH and the EU Green Deal. Brazilian biotechnology platforms anchor supply elasticity for plant-derived grades.
United States
FDA cosmetic ingredient safety guidelines and USDA biobased certification programs shape procurement preferences for clean-label skincare formulations. Federal procurement preference programs create channel access advantages for certified plant-derived grades. California-based clean beauty brands and New Jersey pharmaceutical formulators drive specification-setting for North American supply chains.
Germany
REACH registration mandates and ECHA substance evaluation protocols tighten purity thresholds for cosmetic-grade squalane entering European supply chains. The EU Green Deal's binding traceability requirements privilege plant-derived grades over legacy sources. Cologne and Düsseldorf-based premium skincare formulators now require third-party verified carbon intensity documentation for feedstock sourcing decisions.
Japan
PMDA-approved therapeutic moisturizers for atopic dermatitis and post-surgical skin repair represent underpenetrated demand for high-purity hydrogenated squalene. METI industrial biotechnology programs support domestic fermentation scale-up initiatives. Tokyo pharmaceutical dermatology divisions and Osaka cosmetic OEMs negotiate 3-5 year offtake contracts with fixed-price escalators for fermentation-derived volumes.
South Korea
K-beauty export demand concentrates production orders in Seoul and Incheon-based contract manufacturing facilities. MFDS cosmetic safety regulations align with REACH-equivalent traceability standards for imported raw materials. Seoul-based OEMs now specify fermentation-derived squalane in 70% of new formulation contracts, pulling volumes through East Asian supply chains.
Brazil
Sugarcane-to-squalane biotechnology platforms achieve cost parity with olive extraction, unlocking supply elasticity previously constrained by agricultural harvest cycles. ANVISA pharmaceutical-grade certification requirements govern export eligibility for high-purity grades. São Paulo-state fermentation facilities anchor Amyris's production geography for sustainable squalane volumes serving global cosmetic markets.
Squalane Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation platforms scale to displace extraction-based supply economics. The vendor base concentrates around biotechnology specialists, traditional botanical extractors, and diversified chemical conglomerates with synthetic biology capabilities. Three archetypes define competitive positioning: Brazil-centered fermentation platforms, Mediterranean olive-derived specialists, and German industrial biotechnology integrators. Technology licensing and backward integration into feedstock production constitute the dominant competitive moves.
Within the biotechnology platform tier, Amyris, Inc. exemplifies the fermentation-scale archetype through its Brazil-based production geography. Sophim occupies a position among olive-derived extraction specialists centered in France. Evonik Industries AG represents the diversified chemical conglomerate archetype with synthetic biology pathway capabilities and hydrogenation scale. These three anchors illustrate how feedstock technology specialization is realigning competitive dynamics among specialty chemical suppliers.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Merck KGaA |
| Amyris, Inc. |
| NOF Group |
| Avanti Polar Lipids |
| Sophim |
| Kishimoto Special Liver Oil Co., Ltd. |
| Ineos |
| Croda International Plc |
| Others |
Value Network & Pricing Analysis
Metabolic pathway optimization expertise clustering in Boston, Basel, and Singapore hiring pools widens labor-cost spreads between fermentation-derived and extraction-based squalane tiers. This workforce concentration allows Brazilian biotechnology platforms to command premium positioning against Mediterranean olive-dependent suppliers facing margin compression from agricultural volatility.
Pricing Analysis
Technical service bundling separates pharmaceutical-grade certification support from unbundled commodity cosmetic volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by carbon intensity documentation and REACH registration completeness. Pricing pressure stems from Brazilian fermentation scale-up achieving cost parity with olive extraction, squeezing margin stability for Sophim-grade suppliers. Small-batch specialty distributors exhibit highest price sensitivity, while Seoul-based OEMs with 3-5 year offtake contracts demonstrate lowest sensitivity due to volume guarantees.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and São Paulo anchor hub-and-spoke patterns for squalane logistics. Supply concentrates in Brazil, France, and South Korea, with raw material dependencies on sugarcane feedstock, olive oil harvests, and engineered yeast strains. Single-source fermentation risk from Brazil-centered production geography creates vulnerability to South American logistics disruptions. Distribution runs through direct long-term agreements between fermentation platforms and East Asian contract manufacturers, displacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH registration timelines and capital-intensive GMP facility requirements force mid-cap extraction-dependent suppliers toward exit or acquisition. Fermentation scale economics and regulatory compliance burdens are systematically eliminating sub-scale competitors.
For Market Incumbents: Acquire downstream formulation capabilities to capture margin from therapeutic dermatology applications. Secure backward integration into sugarcane feedstock production in São Paulo-state to hedge against olive oil price volatility. Invest in USP-NF and EP monograph certification infrastructure to defend against synthetic biology specialists entering pharmaceutical-grade segments.
For New Entrants and Emerging Players: Begin with Japanese PMDA-approved therapeutic moisturizers, where underpenetrated demand for high-purity hydrogenated squalene in atopic dermatitis applications offers white-space opportunity. Target USDA biobased certification pathways for North American institutional sales channels. Pursue CRISPR-edited yeast strain licensing agreements as a go-to-market angle to bypass 18-24 month REACH registration delays.
For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-platform specialists given EU Green Deal feedstock mandates accelerating plant-derived grade substitution. Long-term viability favors biotechnology-anchored suppliers with geographic diversification beyond single-source Brazil production. Monitor ECHA substance evaluation acceleration as the signal indicating regulatory clearance timelines compressing for novel biotechnology-derived grades.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Production | São Paulo-state sugarcane sourcing secures supply elasticity against Mediterranean drought volatility. |
| Pharmaceutical-Grade Certification Investment | USP-NF and EP monograph compliance unlocks Japanese PMDA-approved therapeutic moisturizer contracts. |
| Long-term Supply Agreement Negotiation | Seoul-based OEM offtake contracts with fixed-price escalators concentrate procurement leverage among scaled buyers. |
| Synthetic Biology Pathway Licensing | CRISPR-edited yeast strain technology access accelerates yield improvements over batch olive extraction economics. |
| Blockchain Traceability Platform Deployment | Batch-level olive orchard data reconciliation with fermentation tank logs satisfies EU Green Deal binding requirements. |
Research Methodology
Document review covered ECHA substance evaluation protocols, ANVISA pharmaceutical-grade certification requirements, and customs trade data, complemented by interviews with fermentation platform technical directors, cosmetic OEM procurement leads at Seoul and Tokyo facilities, olive extraction plant managers in France, and pharmaceutical formulator regulatory affairs specialists. Secondary validation drew from REACH registration databases, USDA biobased certification records, and SEC filings of publicly traded biotechnology suppliers. Bottom-up volume modeling triangulated against top-down market sizing across feedstock technology tiers.
Cross-referencing historical capacity expansion patterns against expert panel input on fermentation yield trajectory shaped the analytical framework. Segmentation dimensions modeled include feedstock chemistry, application specification, rheological form, and end-user channel structure. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity buildout schedules. Forecast inputs incorporated Brazilian sugarcane harvest variability and South Korean OEM contract manufacturing expansion plans.
Underlying measurement precision varies by segment; fermentation-derived volumes carry tighter precision than olive extraction estimates due to concentrated producer transparency. Forecasts reflect documented assumptions on regulatory clearance timelines and biotechnology yield improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Petrolatum Market
Oleochemicals
Trimethyl Pentanediol Monoisobutyrate Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Estolides Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Esters Market
Oleochemicals
Oleyl Alcohol Market
Oleochemicals
Paraffin Wax Market
Oleochemicals
Global Oxidized Polyethylene Wax Market