
 Synthetic Monitoring Market | 2026-2036
Synthetic Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Monitoring Market Intelligence
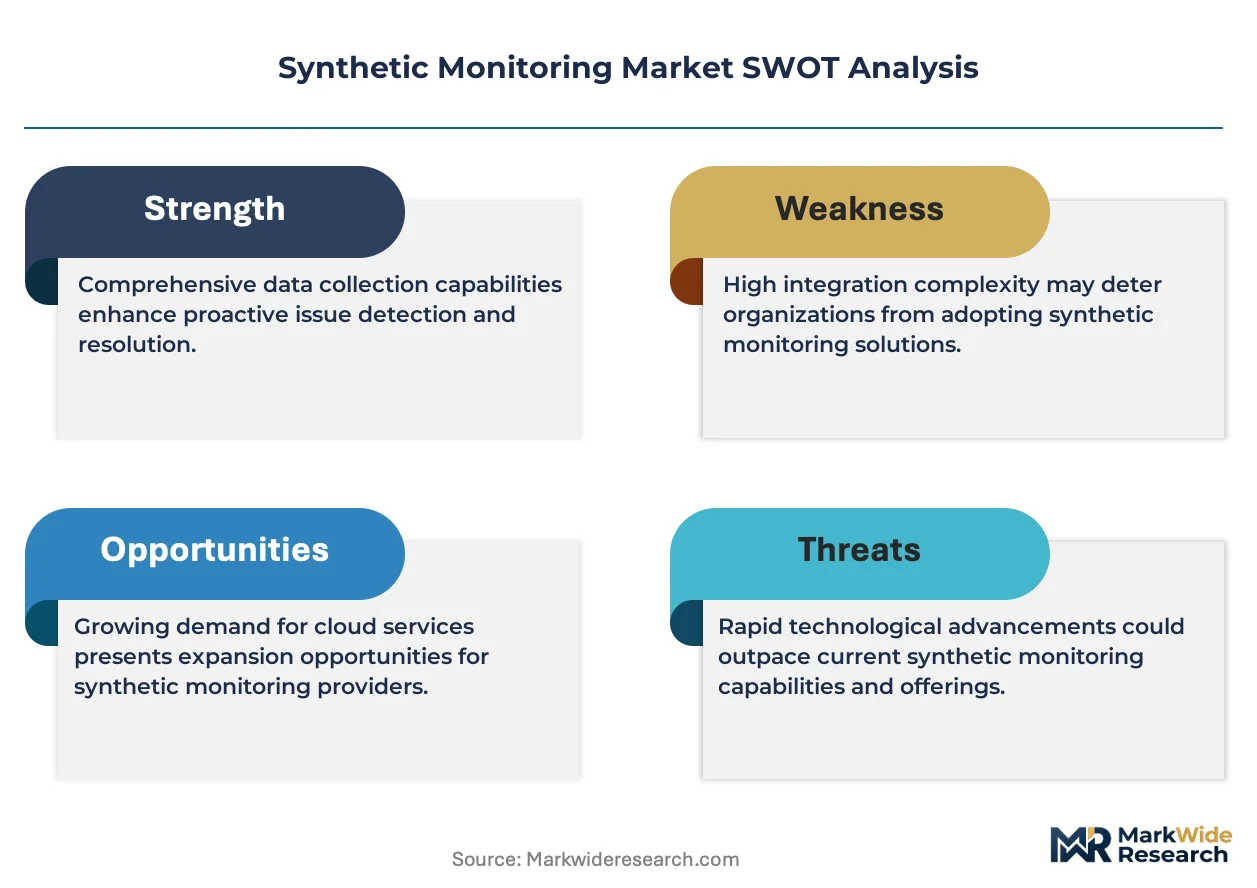
The capital investment gap between developing proprietary global monitoring infrastructure and leveraging public cloud platforms is bifurcating the competitive landscape. Dynatrace differentiates with its AI-powered observability platform, providing deep diagnostics. Broadcom competes by integrating synthetic monitoring into its wider enterprise software stack for existing customers. New Relic positions its solution as a core component of a unified data platform for developers.
Synthetic monitoring is a method of proactively simulating user interactions and transaction paths to test application performance and availability. It utilizes scripted checks deployed from a network of global points of presence to measure uptime and response times before real users are impacted. Web Application Monitoring and API Monitoring constitute the largest solution types, reflecting the architecture of modern software. Within deployment models, cloud-based solutions are rapidly displacing on-premises installations due to superior scalability.
Regulations such as Europe's GDPR and the US HIPAA mandate stringent data privacy and service availability standards. These frameworks compel organizations to adopt proactive tools for SLA monitoring and performance testing to ensure compliance and avoid penalties. Vendor selection will increasingly hinge on the ability to provide unified real-user and synthetic monitoring data on a single, correlated platform.
Market Dynamics
The convergence of cloud-native application architectures and stringent regulatory mandates for service availability is the central force shaping the market. This dynamic compels organizations to adopt proactive, rather than reactive, performance validation strategies to protect user experience and ensure compliance.
Growth Catalysts
- E-Commerce Proliferation:The expansion of online retail and digital marketplaces requires continuous performance validation to prevent revenue loss from downtime or slow transaction speeds, driving demand for constant monitoring.
- Regulatory Compliance Pressure:Mandates such as Europe's GDPR and the US HIPAA require organizations to ensure service availability and protect user data, making proactive monitoring essential for demonstrating compliance.
- API-Driven Architectures:The increasing reliance on microservices and third-party APIs across modern applications creates complex dependencies that necessitate dedicated API monitoring to isolate performance bottlenecks before they impact end-users.
Market Restraints
- Infrastructure Cost:The significant capital expenditure and operational complexity required to build and maintain a proprietary global network of monitoring points of presence acts as a barrier for new entrants.
- False Positive Risk:Poorly configured or overly simplistic synthetic tests can generate false alarms, leading to alert fatigue among DevOps and SRE teams and diminishing trust in the monitoring system.
- Substitution from Real User Monitoring:Solutions focused exclusively on synthetic data face competition from Real User Monitoring (RUM), which captures actual session issues that scripted tests might miss, creating a demand for integrated platforms.
Strategic Opportunities
- Emerging Digital Economies:Markets in Southeast Asia and Latin America with rapidly growing internet penetration and e-commerce sectors represent significant white space for synthetic monitoring solution providers.
- AI and Predictive Analytics:Integrating artificial intelligence and machine learning algorithms enables the shift from reactive alerting to predictive identification of potential performance degradations before they occur.
- IoT and Edge Application Monitoring:The expansion of IoT devices and edge computing deployments opens a new frontier for synthetic monitoring beyond traditional web and mobile applications, testing performance from device to cloud.
Industry Challenges
- DevOps and SRE Talent Scarcity:A persistent shortage of skilled engineers capable of designing, implementing, and maintaining sophisticated synthetic testing scripts and interpreting complex performance data hinders effective adoption.
- Integration with Legacy Systems:Enterprises with hybrid environments face significant challenges in integrating modern synthetic monitoring tools with monolithic legacy applications and disparate on-premises infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Monitoring Market |
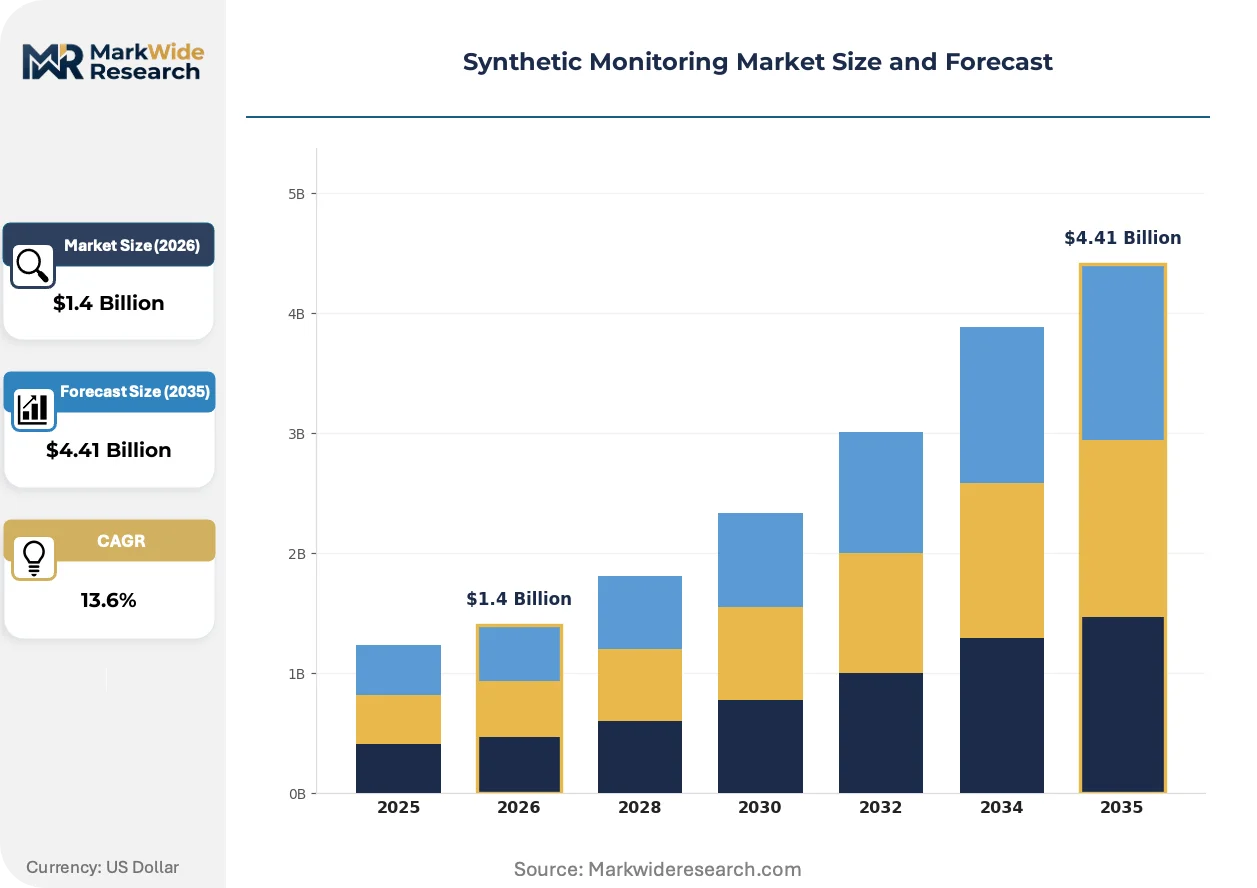
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Solution Type: API Monitoring, Web Application Monitoring, Transaction Monitoring, Mobile Application Monitoring, User Experience Monitoring Use Case: Performance Testing, Availability Testing, SLA Monitoring, Functional Testing, Load Testing End User Industry: Financial Services, E-Commerce Platforms, Telecommunications, Software Development Firms, Media & Entertainment |
| Companies Covered | Datadog, Broadcom, Dynatrace, Dell Technologies, IBM Corporation, New Relic, SolarWinds, LogicMonitor, AppDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Monitoring Market Strategic Shifts & Innovations
The market's evolution is defined by a strategic shift from isolated uptime checking to integrated digital experience observability. This transition prioritizes predictive insights and platform consolidation over fragmented, reactive alerting tools.
AI-powered observability is a key technological evolution, automating root cause analysis for complex application issues. Enterprise organizations in the finance and retail sectors are rapidly adopting these systems. This adoption is bifurcating the market between vendors offering deep, predictive diagnostics and those providing basic availability checks.
Regulatory frameworks like Europe’s Corporate Sustainability Reporting Directive (CSRD) are expanding non-financial reporting requirements. This forces large companies to document and verify digital service uptime and performance as part of their operational resilience disclosures. The financial services and telecommunications sectors are most impacted, integrating synthetic monitoring as a core compliance function.
A prominent demand-side shift is the move away from procuring individual point solutions toward acquiring unified observability platforms. This pattern disrupts specialist tool vendors as DevOps teams consolidate synthetic monitoring with APM and RUM into a single data model. This trend is most visible within large enterprises in the United States.
Synthetic Monitoring Market Segmentation
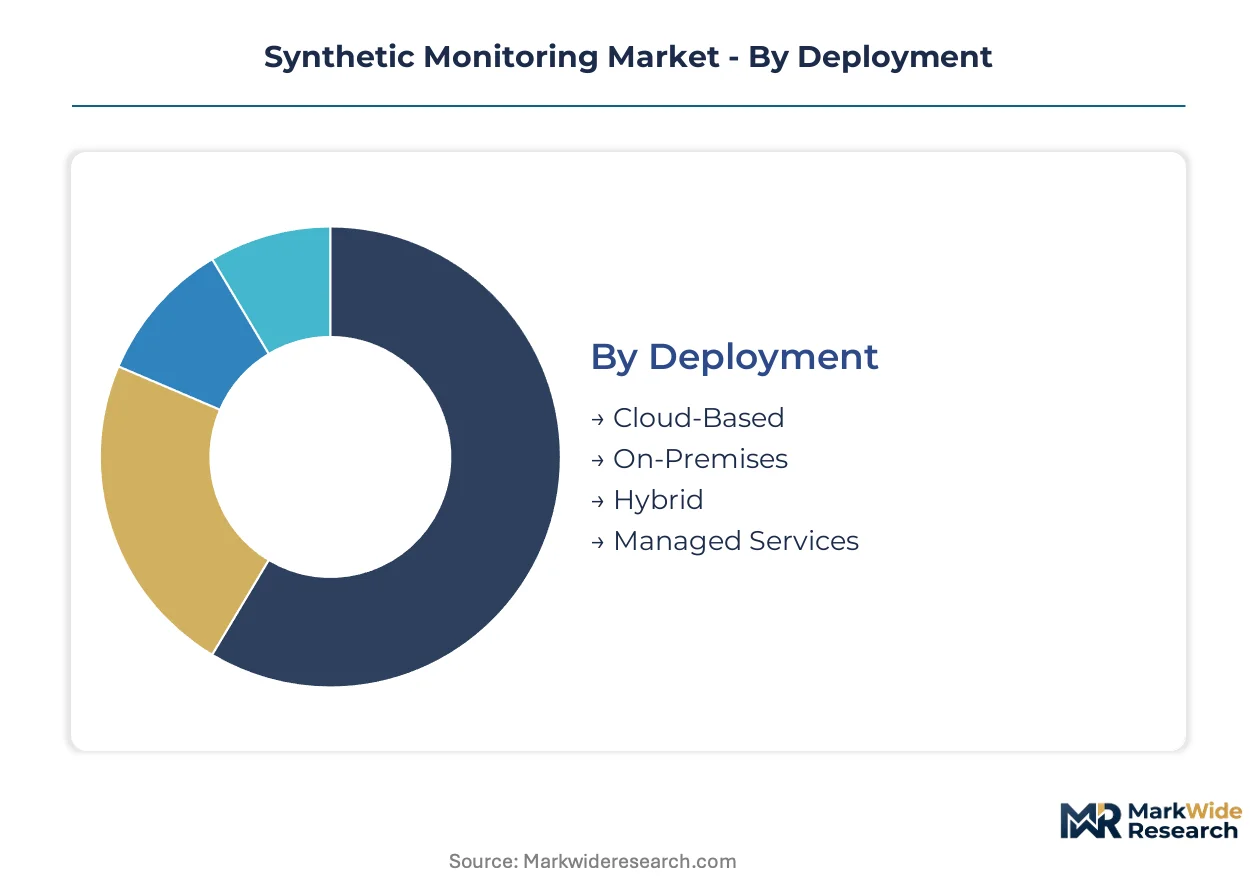
The Synthetic Monitoring Market's segmentation illuminates the diverse operational models and functional requirements driving its expansion. Understanding these distinct segments helps solution providers tailor offerings to specific deployment preferences, technical needs, and industry-specific compliance mandates.
Deployment:
The channel mix for synthetic monitoring solutions reflects evolving infrastructure preferences and operational flexibility requirements.
- Cloud-Based:These solutions are hosted and managed by vendors, offering scalability, reduced infrastructure overhead, and global accessibility for monitoring applications from various geographic locations. Demand is concentrating in digital-native enterprises in the United States seeking rapid deployment and continuous updates.
- Managed Services:Third-party providers handle the entire synthetic monitoring lifecycle, including setup, configuration, and incident management, reducing the burden on internal IT teams. This model appeals to organizations with limited in-house expertise or those prioritizing core business functions over monitoring infrastructure.
- On-Premises:Enterprises deploy and manage monitoring software within their own data centers, providing complete control over data security and compliance for highly regulated industries. Financial services firms often prefer this model for sensitive data.
- Hybrid:This approach combines on-premises and cloud-based components, allowing organizations to monitor both internal and external applications while maintaining control over critical systems.
By volume, Cloud-Based solutions lead. By growth pace, Managed Services is ahead.
Solution Type:
Application architecture dictates the specific monitoring tools required, influencing solution type adoption across various enterprise environments.
- API Monitoring:This solution type validates the performance and availability of application programming interfaces, which form the backbone of modern microservices architectures. Demand is strong in software development firms that rely heavily on interconnected services.
- Web Application Monitoring:These tools simulate user journeys through web interfaces to measure page load times, transaction completion, and overall user experience. E-commerce platforms utilize this extensively to prevent revenue loss from performance issues.
- Transaction Monitoring:This focuses on tracking multi-step business processes, such as checkout flows or login procedures, to ensure each step completes successfully and within performance thresholds.
- Mobile Application Monitoring:These solutions test the performance and responsiveness of native and hybrid mobile applications across different devices and network conditions.
- User Experience Monitoring:This segment encompasses tools that provide a holistic view of the end-user's interaction with an application, combining various synthetic checks to gauge satisfaction.
Web Application Monitoring commands the largest share of deployments. API Monitoring exhibits the steepest expansion trajectory.
Use Case:
The application of synthetic monitoring varies depending on the specific objective, ranging from proactive validation to compliance assurance.
- Performance Testing:This involves simulating user load to identify bottlenecks and validate application responsiveness under expected and peak traffic conditions. Telecommunications companies use this to ensure network stability.
- SLA Monitoring:Organizations use synthetic checks to continuously verify that applications meet agreed-upon service level agreements with internal or external customers. Financial services entities rely on this for regulatory reporting.
- Availability Testing:This fundamental use case confirms that applications and their underlying infrastructure are accessible and operational from various global locations.
- Functional Testing:Synthetic monitoring scripts can validate the correct operation of specific application features and business logic, ensuring critical functions work as intended.
- Load Testing:This involves subjecting an application to a heavy, controlled workload to observe its behavior and identify performance limits before deployment.
Performance Testing accounts for the highest number of implementations. SLA Monitoring is gaining share fastest among use cases.
End User Industry:
Industry-specific demands, regulatory pressures, and digital transformation initiatives shape the adoption patterns of synthetic monitoring.
- E-Commerce Platforms:These businesses depend on uninterrupted online operations and fast transaction speeds to maintain customer satisfaction and revenue. Continuous performance validation is critical for their success.
- Financial Services:Highly regulated and transaction-intensive, this sector requires robust monitoring to ensure service availability, data integrity, and compliance with regulations like GDPR and HIPAA.
- Telecommunications:Service providers monitor their vast network infrastructure and customer-facing applications to guarantee call quality, data speeds, and consistent service delivery.
- Software Development Firms:These companies integrate synthetic monitoring into their DevOps pipelines for continuous integration and continuous delivery, ensuring code quality and performance before release.
- Media & Entertainment:Streaming services and content platforms utilize synthetic monitoring to validate content delivery, user experience, and application responsiveness across diverse devices.
E-Commerce Platforms represent the largest segment in terms of expenditure. Financial Services show significant investment in advanced monitoring capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity contrasts significantly across global regions, with some enterprises prioritizing robust, feature-rich solutions over cost, while others seek more budget-conscious monitoring options. Digital-native enterprises in developed economies often exhibit lower price sensitivity for advanced synthetic monitoring capabilities. Emerging markets frequently balance performance needs with infrastructure expenditure constraints.
United States
The United States leads the market due to its high concentration of digital-native enterprises and extensive e-commerce activity. Organizations require continuous performance validation for complex application ecosystems. Regulations like HIPAA and SEC mandates compel stringent service availability and data integrity. Technology hubs in Silicon Valley and New York City drive innovation and adoption of advanced AI-powered observability platforms.
Germany
German enterprises demonstrate strong demand for synthetic monitoring, particularly within its robust manufacturing and financial services sectors. Data privacy regulations such as GDPR necessitate proactive user experience testing to ensure compliance. The country's digital transformation initiatives, especially in cities like Munich and Berlin, foster significant investment in cloud-based monitoring solutions.
United Kingdom
Organizations in the United Kingdom prioritize synthetic monitoring for their expansive financial services and e-commerce platforms. The UK's adherence to GDPR principles and the Financial Conduct Authority's (FCA) operational resilience guidelines mandate continuous performance and availability checks. London's financial district and technology clusters in Manchester are key adoption centers for unified observability platforms.
Japan
Japanese companies are increasingly adopting synthetic monitoring to support their growing e-commerce presence and advanced IoT applications. Guidelines from METI encourage digital transformation and robust IT infrastructure. Major metropolitan areas like Tokyo and Osaka are seeing significant investment in API monitoring and web application monitoring to ensure service quality.
India
India's rapidly expanding digital economy and burgeoning e-commerce sector fuel substantial demand for synthetic monitoring solutions. Government initiatives like the PLI scheme and emerging data protection laws influence the need for reliable application performance. Technology hubs in Bengaluru and Hyderabad are experiencing rapid adoption for both internal IT services and global delivery centers.
Synthetic Monitoring Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the synthetic monitoring market. The competitive structure is tiered, with established enterprise software vendors competing alongside specialized observability providers. Strategic archetypes include full-stack observability platforms, niche synthetic monitoring specialists, and infrastructure-focused IT management suites. Portfolio diversification and strategic partnerships are dominant competitive moves.
Full-stack observability platforms, such as Dynatrace, differentiate through AI-powered diagnostics and deep integration across various monitoring domains. Broadcom, a major enterprise software provider, integrates synthetic monitoring into its broader portfolio for existing large enterprise customers. New Relic positions its solution as a core component of a unified data platform, emphasizing developer-centric tools and data correlation for performance insights.
| Leading Market Players |
|---|
| Datadog |
| Broadcom |
| Dynatrace |
| Dell Technologies |
| IBM Corporation |
| New Relic |
| SolarWinds |
| LogicMonitor |
| AppDynamics |
| Others |
Cost & Logistics Intelligence
A 30-day inventory buffer for synthetic monitoring software licenses directly shapes supply chain resilience and influences vendor pricing power. This buffer allows vendors to manage fluctuating demand for cloud-based solutions, impacting subscription costs and service level agreements.
Pricing Analysis
After-sales support and managed services represent a significant revenue tier, driving long-term customer value. SaaS-tiered subscription models dominate, reflecting the cloud-based nature of synthetic monitoring solutions. Solutions differentiate based on AI-powered diagnostic capabilities and global points of presence. Pricing softness stems from the increasing availability of integrated observability platforms, compelling vendors to offer competitive bundles. Small and medium-sized enterprises exhibit higher price sensitivity compared to large enterprises in financial services.
Supply Chain Analysis
The United States and Germany anchor the development and deployment of advanced synthetic monitoring software. Key development hubs exist in the United States, particularly Silicon Valley, and Europe, with Germany and the United Kingdom contributing significantly to software engineering talent. Software development talent and access to global cloud infrastructure providers (e.g., AWS, Azure, GCP) are critical dependencies. Single-source vulnerability for specialized AI/ML components poses a structural risk. Distribution primarily runs through direct sales channels and cloud marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Synthetic Monitoring Market is entering a cyclical recovery, driven by renewed enterprise IT spending on digital transformation initiatives. This rebound is accelerating investment in proactive performance validation tools across industries.
For Market Incumbents: Secure existing enterprise accounts by deepening integration with broader observability platforms. This defends against the threat of specialized point solutions and offers a unified data model. Focus R&D on AI-powered predictive analytics to enhance diagnostic capabilities, a key lever for competitive advantage. Consolidate smaller, niche synthetic monitoring providers to expand geographic reach or specialized application coverage.
For New Entrants and Emerging Players: Differentiate on niche industry compliance or specific technology stacks like IoT and edge computing. The most penetrable segment lies in emerging digital economies in Southeast Asia, which require localized monitoring solutions. Offer a value-based go-to-market angle focused on simplified deployment and rapid time-to-value for small and medium-sized businesses. Target API monitoring solutions for microservices architectures.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because the market rewards unified observability and predictive insights. Acquisition targets include specialist synthetic monitoring firms with strong AI capabilities or those offering advanced mobile application monitoring. A key signal to watch is the increasing adoption rate of full-stack observability platforms by large enterprises, indicating market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Enhances competitive positioning by offering a unified view of application performance across diverse environments. |
| AI-Powered Diagnostics | Improves root cause analysis, reducing mean time to resolution for complex application issues. |
| Geographic Expansion | Captures demand in emerging digital economies like India and Southeast Asia for new revenue streams. |
| Compliance-Focused Solutions | Addresses stringent regulatory mandates such as GDPR and HIPAA, attracting financial services clients. |
| API Monitoring Specialization | Catters to the architectural shift towards microservices, isolating performance bottlenecks in interconnected services. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. This involved engaging CTOs, DevOps engineers, IT procurement officers, and cloud platform architects. Secondary sources included SEC filings, industry association reports, government digital transformation initiatives, and technology news archives. Bottom-up data aggregation and top-down market sizing provided robust triangulation.
The analysis window for this study spans from 2026 to 2035, employing a robust analytical framework. Segmentation dimensions modeled included deployment, solution type, use case, end-user industry, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included enterprise cloud adoption rates and regulatory compliance spending.
Material uncertainties — including macroeconomic downturns or unforeseen technological disruptions — sit outside the modeled envelope, influencing future market trajectories. Forecasts reflect assumptions regarding digital transformation pace and regulatory enforcement. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Canada ICT Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Global Data Historian Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
US Digital Market
Digital Solutions
Digital BSS Market
Digital Solutions
Digital Marketing Software Market
Digital Solutions
China Cloud OSS BSS Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Data Cleansing Tools Market