
 China Cloud OSS BSS Market | 2026-2036
China Cloud OSS BSS Market Size, Share, and Industry Trends Forecast 2026-2036
China Cloud OSS BSS Market Insights
China's national 5G infrastructure rollout is reshaping procurement patterns for cloud-native operations support systems. Huawei Technologies Co., Ltd. anchors domestic supply through its FusionSphere stack and carrier-grade certifications. Alibaba Group Holding Limited leverages its public cloud dominance to capture enterprise BSS workloads outside traditional telecom. China Mobile Limited controls the largest internal migration timeline, directly influencing vendor roadmaps.
Cloud OSS BSS denotes the integrated software layer that automates telecom service fulfillment, assurance, and billing through virtualized, API-driven architectures running on distributed cloud infrastructure. These systems replace legacy hardware-dependent stacks with containerized microservices orchestrated via Kubernetes, enabling elastic scaling as subscriber data volumes surge past petabyte thresholds. Hybrid Cloud deployment captures the dominant project pipeline as carriers phase out on-premise legacy estates while retaining sensitive subscriber data in sovereign private environments. AI and Machine Learning within the Technology segment commands disproportionate R&D allocation as operators deploy predictive fault detection and dynamic pricing algorithms.
MIIT mandates GB standards compliance and cybersecurity review for all cloud infrastructure serving critical information infrastructure operators. SAMR enforces data localization and cross-border transfer rules that constrain foreign SaaS architectures. Stakeholders must monitor regulatory timing for mandatory cloud service security assessments, as certification delays determine vendor eligibility for state-owned carrier tenders.
Market Dynamics
China's telecom carriers are dismantling monolithic legacy OSS BSS stacks through containerized microservices migration, driven by MIIT mandates for 5G standalone core readiness and petabyte-scale subscriber data processing requirements.
Growth Catalysts
- MIIT 5G SA Core Mandates:Certification deadlines for cloud-native network functions force procurement cycles at China Mobile, China Telecom, and China Unicom, compressing vendor qualification timelines.
- Petabyte Data Volumes:Subscriber behavior analytics and real-time billing reconciliation demand elastic Kubernetes-orchestrated infrastructure that legacy hardware cannot provision.
- Beijing-Shanghai Procurement Concentration:State-owned carrier headquarters and MIIT-affiliated testing labs centralize tender awards, reducing vendor sales cycle friction.
Market Restraints
- GB Standards Compliance Burden:MIIT cybersecurity reviews and SAMR data localization audits extend product launch timelines by 8-14 months for foreign-architecture vendors.
- Domestic Vendor Concentration:Huawei and ZTE capture 70%+ of carrier-grade certification slots, limiting competitive entry for specialized international players.
- Hybrid Cloud Integration Complexity:Sovereign private cloud requirements for subscriber data prevent pure public cloud BSS deployments, fragmenting vendor addressable scope.
Strategic Opportunities
- Guangdong-Shenzhen Enterprise Edge:Manufacturing and logistics verticals outside traditional telecom represent unserved BSS workload demand for cloud-native billing platforms.
- AI/ML Convergence with Assurance:Predictive fault detection algorithms trained on network telemetry create attach-rate expansion for analytics modules.
- Dual Carbon Policy Tailwinds:MEE energy efficiency mandates for data centers favor vendors offering carbon-aware workload orchestration in their cloud stacks.
Industry Challenges
- Container Orchestration Talent Scarcity:Kubernetes-native telco engineering expertise concentrates in Beijing and Hangzhou, inflating implementation costs for provincial carrier branches.
- Legacy API Migration Friction:SOAP-to-REST protocol translation and data schema reconciliation delay production cutovers by 6-12 months per carrier domain.
- Cross-Department Coordination Burden:Network operations, IT, and finance teams maintain conflicting KPIs, slowing unified cloud transformation governance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cloud OSS BSS Market |
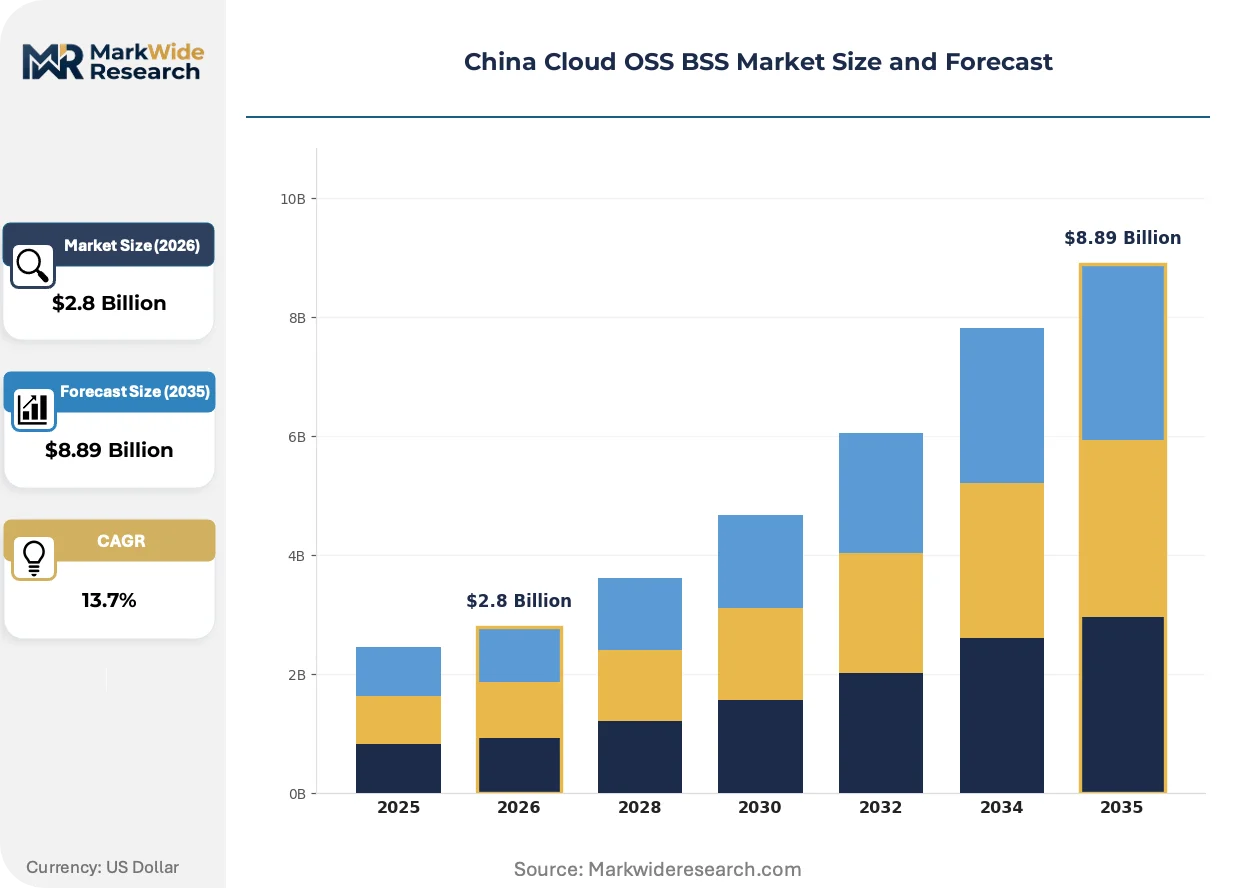
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Billing, Revenue Management, CRM, Service Provisioning Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise End User: Telecommunications, Managed Service Providers, Enterprises, Startups Technology: AI, Machine Learning, API Management, Microservices |
| Companies Covered | China Telecom Corporation Limited, Alibaba Group Holding Limited, Huawei Technologies Co., Ltd., Baidu, Inc., Tencent Holdings Limited, ZTE Corporation, China Unicom (Hong Kong) Limited, Inspur Group Limited, China Mobile Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cloud OSS BSS Market Trends and Innovations
Cloud-native architectures are compressing traditional three-year telecom software refresh cycles into continuous delivery pipelines, forcing vendors to restructure R&D, support, and pricing models around subscription consumption rather than perpetual licenses.
Containerized microservices is collapsing the boundary between network function virtualization and business support systems. China Mobile's 2024 infrastructure tenders require vendors to demonstrate unified Kubernetes control planes spanning core network elements and BSS workloads. This convergence eliminates the historical separation between network engineering and IT procurement teams, compressing vendor qualification into single integrated assessments.
MIIT's mandatory cloud service security assessment framework is reshaping vendor eligibility criteria. The regulation requires third-party penetration testing and source code audit deposits for all infrastructure serving critical information infrastructure operators. Foreign-architecture vendors face extended certification timelines, while domestic stack providers with pre-approved GB compliance documentation capture disproportionate tender participation rights.
State-owned carriers are consolidating vendor relationships through framework agreements that bundle OSS, BSS, and network equipment procurement. China Telecom's integrated supplier panels reduce the number of approved vendors per category from 15-20 to 5-7 qualified partners. This concentration rewards full-stack providers and marginalizes point-solution specialists who cannot satisfy cross-domain certification requirements.
China Cloud OSS BSS Market Segmentation
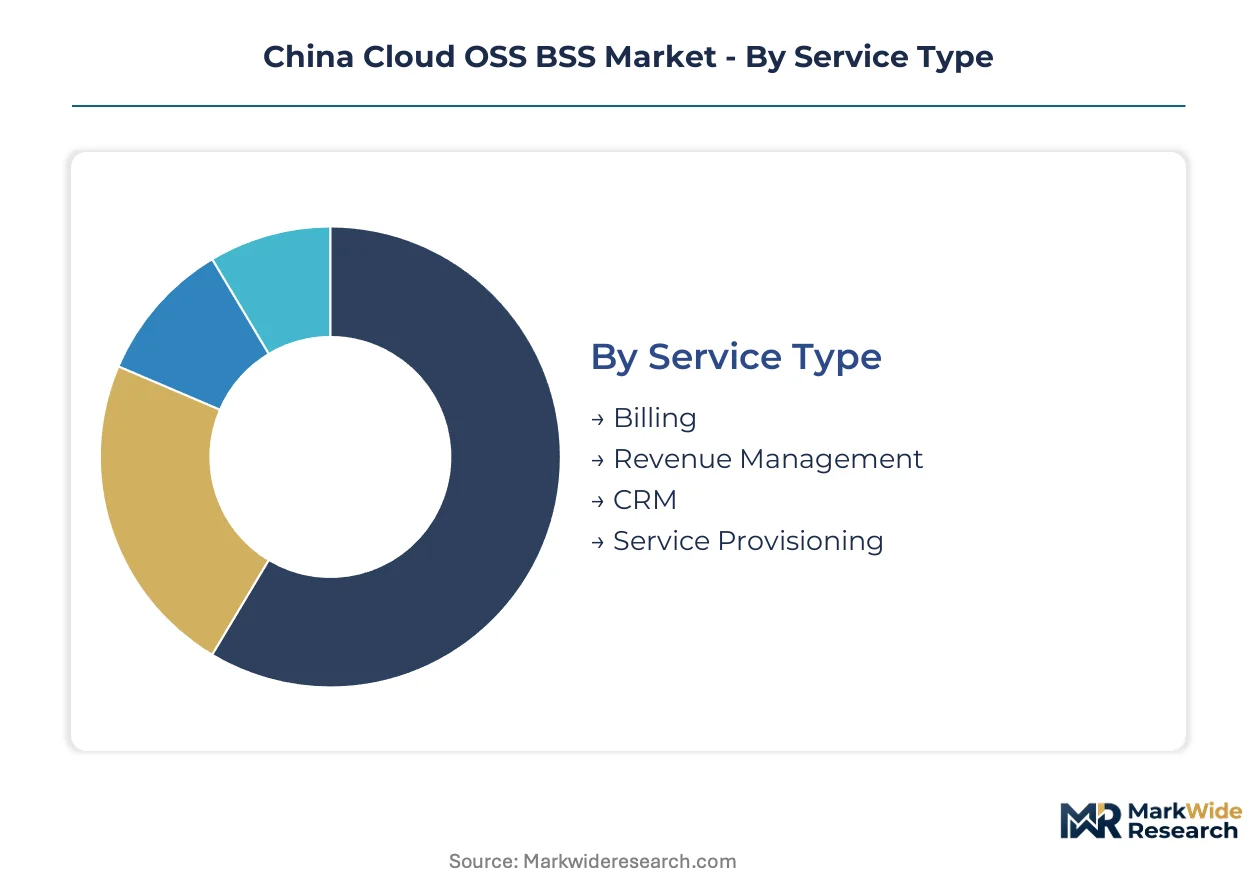
Cloud OSS BSS procurement patterns diverge sharply across service layers and infrastructure choices. MIIT certification requirements and data sovereignty rules create distinct addressable markets for each segment combination.
Service Type:
Post-deployment support intensity varies dramatically across functional modules, with revenue assurance systems demanding continuous algorithm tuning and billing platforms requiring 24/7 SLA coverage.
- Billing:Real-time rating engines process petabyte-scale usage records through containerized microservices architectures. China Mobile's internal migration timeline concentrates demand in Beijing and Shanghai, where carrier innovation labs validate cloud-native charging systems against 5G standalone core specifications.
- Revenue Management:Fraud detection and partner settlement modules leverage machine learning pipelines trained on historical transaction patterns. Provincial carrier branches in Guangdong and Jiangsu drive procurement as they modernize legacy mediation systems.
- CRM:Subscriber lifecycle management platforms integrate with enterprise SaaS ecosystems.
- Service Provisioning:Automated network slice activation tools enable zero-touch service delivery.
Billing holds the largest share; momentum sits with Revenue Management as AI-driven fraud prevention gains tender weighting.
Deployment Model:
Cost tiering separates sovereign-compliant private infrastructure from elastic public cloud consumption, with hybrid architectures commanding premium implementation services.
- Hybrid Cloud:Split-stack deployments retain subscriber data in MIIT-certified private zones while bursting compute to public cloud. State-owned carriers mandate this architecture for sensitive billing records, creating vendor qualification barriers for pure-public providers.
- Private Cloud:Dedicated OpenStack or VMware estates serve critical information infrastructure operators under GB standards compliance. Beijing and Shanghai headquarters prioritize these deployments for core network-adjacent workloads.
- Public Cloud:Alibaba Cloud and Tencent Cloud capture enterprise BSS workloads outside traditional telecom procurement channels.
- On-Premise:Legacy hardware-dependent stacks persist in provincial branches with extended depreciation schedules.
Hybrid Cloud holds the largest share; Private Cloud is climbing the fastest as cybersecurity review timelines shorten for pre-certified domestic stacks.
End User:
Customer type determines contract structure, with telecommunications carriers demanding multi-year framework agreements and enterprises preferring consumption-based subscriptions.
- Telecommunications:China Mobile, China Telecom, and China Unicom drive procurement volume through consolidated vendor panels. MIIT-mandated 5G standalone core deadlines compress qualification cycles to 8-14 months.
- Enterprises:Manufacturing and logistics verticals in Guangdong-Shenzhen adopt cloud-native billing for IoT connectivity management. These workloads bypass carrier-grade certification requirements, opening addressable scope for specialized SaaS vendors.
- Managed Service Providers:Regional systems integrators bundle OSS BSS with managed network services.
- Startups:MVNOs and edge computing ventures consume API-first provisioning modules.
Telecommunications holds the largest share; Enterprises are expanding most quickly as industrial digitization creates non-traditional demand.
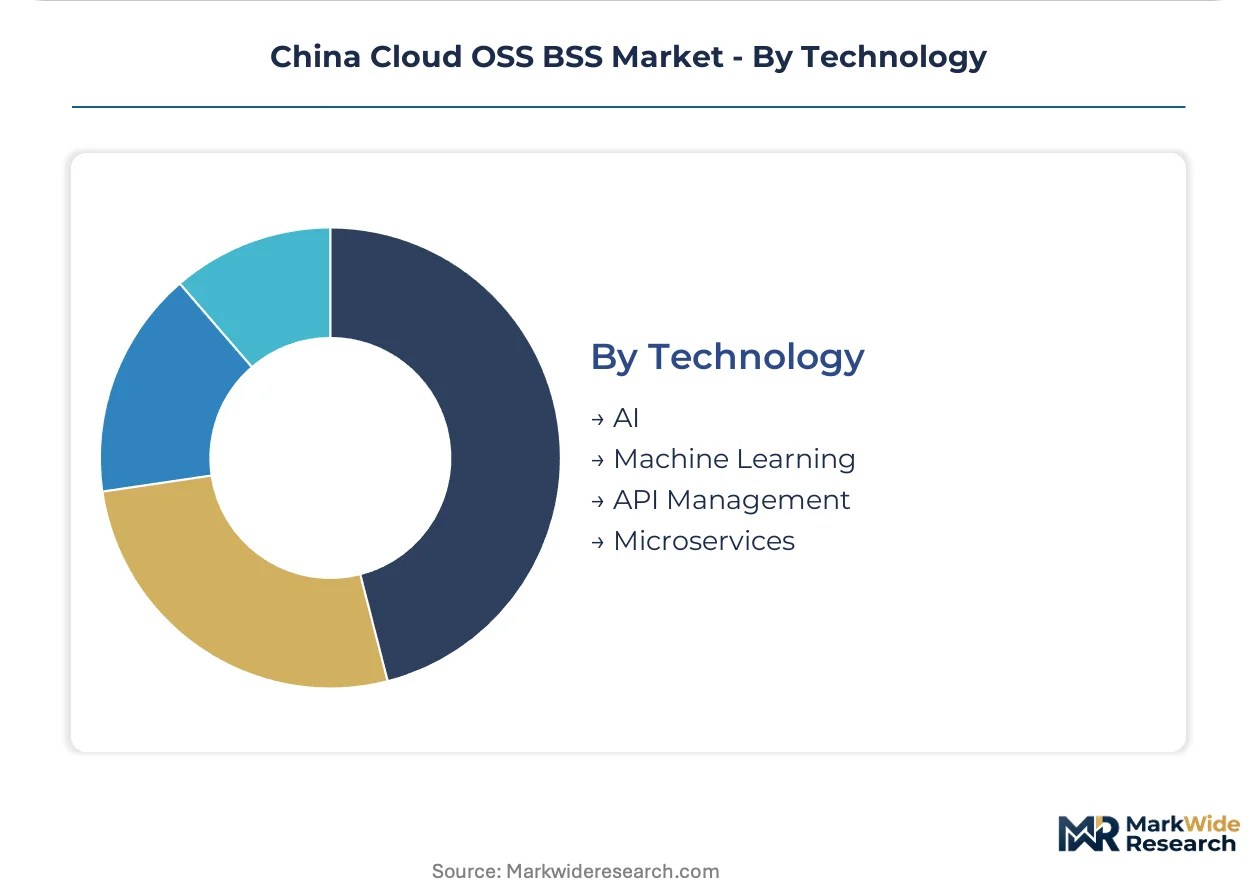
Technology:
Margin concentration follows R&D intensity, with AI/ML modules capturing disproportionate attach rates against commodity infrastructure layers.
- AI:Predictive fault detection algorithms trained on network telemetry reduce mean time to repair. China Telecom's integrated supplier panels prioritize vendors demonstrating production-grade AI operations in carrier environments.
- Machine Learning:Dynamic pricing engines adjust tariff structures based on real-time demand elasticity. Beijing-based innovation labs validate these systems against MIIT data localization requirements.
- API Management:RESTful service meshes enable microservices communication across hybrid estates.
- Microservices:Containerized function decomposition replaces monolithic legacy architectures.
AI holds the largest share; momentum sits with Machine Learning as pricing optimization gains procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT anchors procurement concentration through its 5G standalone core mandates and cybersecurity certification framework. Provincial carrier branches and enterprise verticals distribute demand across distinct industrial clusters.
Beijing-Tianjin-Hebei
State-owned carrier headquarters and MIIT-affiliated testing labs concentrate cloud-native OSS BSS procurement. GB standards compliance reviews and mandatory security assessments originate from Beijing regulatory offices. Zhongguancun technology corridor hosts validation facilities where vendors demonstrate Kubernetes-orchestrated charging systems against 5G SA specifications.
Yangtze River Delta
Shanghai-based innovation labs drive billing platform modernization for China Mobile and China Telecom. SAMR data localization audits enforce sovereign private cloud requirements for subscriber records. Hangzhou's cloud computing cluster supplies container orchestration talent for hybrid deployment implementations.
Pearl River Delta
Guangdong manufacturing and logistics verticals generate enterprise BSS demand outside traditional telecom channels. Shenzhen's IoT device ecosystem requires cloud-native connectivity management platforms. Provincial carrier branches in Guangzhou modernize legacy mediation systems under MIIT-mandated timelines.
Sichuan-Chongqing
Western region data center expansion supports disaster recovery and latency-sensitive workloads. MEE energy efficiency mandates favor carbon-aware workload orchestration in cloud stacks. Chengdu's telecommunications hub validates AI-driven fraud detection modules for provincial deployment.
China Cloud OSS BSS Market Competitive Landscape
State-owned carriers and hyperscale cloud providers split the market through divergent certification pathways. Carrier-affiliated vendors capture infrastructure-adjacent workloads under framework agreements. Technology conglomerates and specialized telecom equipment suppliers represent the dominant strategic archetypes. Competitive positioning hardens through integrated supplier panels and pre-certified domestic stack documentation.
Within the carrier-affiliated tier, China Mobile Limited, China Telecom Corporation Limited, and China Unicom (Hong Kong) Limited exemplify demand-side concentration through consolidated procurement governance. These entities occupy positions as both end-users and ecosystem orchestrators, directly influencing vendor roadmaps through internal migration timelines and tender specifications. Their framework agreements reduce approved vendor counts per category, rewarding full-stack providers capable of satisfying cross-domain certification requirements spanning OSS, BSS, and network equipment domains.
| Leading Market Players |
|---|
| China Telecom Corporation Limited |
| Alibaba Group Holding Limited |
| Huawei Technologies Co., Ltd. |
| Baidu, Inc. |
| Tencent Holdings Limited |
| ZTE Corporation |
| China Unicom (Hong Kong) Limited |
| Inspur Group Limited |
| China Mobile Limited |
| Others |
Pricing and Supply Chain Analysis
Beijing's certification infrastructure anchors vendor qualification costs, compressing pricing power for foreign-architecture suppliers while domestic stack providers capture premium positioning through pre-approved GB compliance documentation. MIIT-mandated security assessments and SAMR data localization audits extend product launch timelines, forcing procurement concentration toward carriers with framework agreement leverage.
Pricing Analysis
Price spreads between Beijing-Shanghai headquarters and provincial carrier branches reflect talent scarcity premiums for Kubernetes-native engineering expertise. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified domestic stacks from foreign-architecture alternatives and legacy hardware-dependent systems. Pricing pressure stems from carrier consolidation of vendor panels, which reduces approved suppliers per category and intensifies competitive bidding. Enterprise verticals in Guangdong-Shenzhen demonstrate highest price sensitivity due to bypassing carrier-grade certification requirements, while state-owned carriers absorb premium pricing for sovereign-compliant private cloud deployments.
Supply Chain Analysis
Extended payment terms from state-owned carriers and supply-chain finance facilities strain working capital for specialized software vendors competing against full-stack providers. Component sourcing draws from domestic cloud computing clusters in Hangzhou and Shenzhen, with critical orchestration tooling anchored in open-source Kubernetes ecosystems. Single-source vulnerability concentrates around MIIT-affiliated testing labs for certification validation, creating bottleneck risk for vendor qualification timelines. Distribution runs through consolidated framework agreements that bundle OSS, BSS, and network equipment procurement, marginalizing point-solution specialists unable to satisfy cross-domain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's 5G standalone core mandates are compressing traditional procurement cycles into continuous delivery pipelines, creating high-growth disruption as containerized microservices displace legacy hardware stacks. Cloud-native architectures are collapsing historical boundaries between network engineering and IT procurement, forcing vendor restructuring around subscription consumption models.
For Market Incumbents: Pre-empt margin compression from carrier vendor panel consolidation by deepening certification investment in MIIT-affiliated testing labs and expanding framework agreement participation across OSS, BSS, and network equipment domains. Threat substitution from hyperscale cloud providers demands defensive capability expansion into AI-driven assurance modules to maintain attach-rate positioning. Vertical integration into container orchestration tooling supply reinforces cost control against talent scarcity inflation in Beijing and Hangzhou.
For New Entrants and Emerging Players: Pursue white-space opportunity in Guangdong-Shenzhen enterprise verticals where manufacturing and logistics IoT connectivity management bypasses carrier-grade certification requirements. The most penetrable segment sits with cloud-native billing platforms for non-traditional telecom workloads. Go-to-market execution should leverage API-first provisioning modules targeting MVNOs and edge computing ventures through consumption-based subscription models rather than perpetual licensing.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure consolidation play because state-owned carriers are reducing approved vendor counts per category from double-digit rosters to five-to-seven qualified partners, rewarding full-stack providers with cross-domain certification capabilities. Acquisition target archetype: specialized AI/ML analytics vendors with production-grade carrier deployments. Signal to watch: MIIT regulatory timing for mandatory cloud service security assessments, as certification delays determine vendor eligibility for state-owned carrier tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified Kubernetes control planes spanning core network and BSS workloads satisfy China Mobile's integrated tender requirements. |
| Acquisition of Specialist Firm | AI-driven fraud detection vendors with MIIT-validated algorithms capture revenue management attach-rate expansion. |
| Strategic Partnership | Framework agreements with state-owned carriers bundle OSS, BSS, and network equipment procurement into consolidated panels. |
| Geographic Expansion | Guangdong-Shenzhen enterprise edge penetration targets manufacturing IoT billing outside traditional telecom channels. |
| Product Launch | Carbon-aware workload orchestration aligns with MEE energy efficiency mandates for data center operations. |
Research Methodology
Operator-level perspectives from network operations directors, IT procurement officers, platform engineers, and integration specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against MIIT regulatory filings, carrier tender documentation, hyperscaler capex disclosures, and GB standards compliance databases. Bottom-up segment sizing triangulated against top-down market reconstruction across service type, deployment model, end user, and technology dimensions.
Scenario-bracketing framed the analytical approach across the projection horizon, with CAGRs derived from elasticity modeling against 5G standalone core deployment timelines and petabyte-scale data volume trajectories. Segmentation dimensions modeled include service layer functional modules, sovereign compliance architecture choices, customer type contract structures, and AI/ML technology intensity tiers. Forecast inputs incorporated carrier internal migration timelines, MIIT certification queue visibility, and provincial branch modernization schedules.
Sensitivities concentrate around MIIT regulatory timing revisions, carrier vendor panel consolidation acceleration, and cross-border data transfer rule tightening by SAMR. Forecasts reflect assumptions regarding certification timeline stability and framework agreement structure continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Europe API Management Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Global Web Push Notification Software Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
India Digital Twin Market