
 Global Mobile Content Management Market | 2026-2036
Global Mobile Content Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Content Management Market Foresight
ISO 27001 certification is bifurcating the competitive landscape into qualified enterprise vendors and unqualified regional suppliers. Microsoft Corporation leverages its Azure cloud backbone to sustain hybrid deployment leadership across regulated industries. VMware, Inc. anchors its position through deep virtualization integration that extends mobile content security into endpoint infrastructure. Citrix Systems, Inc. competes on workspace virtualization specialization that controls enterprise mobility stacks without native device management.
Mobile Content Management encompasses software platforms that govern the creation, distribution, and security of digital assets across smartphones, tablets, and ruggedized field devices through encryption protocols, containerization, and policy-driven access controls. These systems enforce data loss prevention while enabling offline synchronization and real-time collaboration for distributed workforces. Cloud-Based deployment captures the dominant margin pool as enterprises abandon capital-intensive on-premises infrastructure, while Content Security solutions lead solution-type revenue due to escalating breach remediation costs. Workflow Automation represents the fastest-expanding segment as manufacturers digitize shop-floor approval chains and field service dispatch protocols.
FDA 21 CFR Part 11 shapes product requirements for healthcare deployments by mandating audit trails and electronic signature validity on mobile clinical documentation. The EU AI Act and GDPR impose algorithmic transparency and data residency constraints that restrict non-European cloud providers from processing sensitive mobile content without localized infrastructure. EMA guidance on electronic data integrity further tightens validation standards for pharmaceutical field forces. Stakeholders must monitor evolving cross-border data localization mandates that threaten unified global platform architectures.
Market Dynamics
Zero-trust architecture mandates from federal agencies are restructuring enterprise procurement criteria, forcing vendors to recertify platforms around continuous authentication rather than perimeter-based security models.
Growth Catalysts
- FDA 21 CFR Part 11:Healthcare providers deploy mobile clinical documentation platforms with audit trails and electronic signatures to meet validation requirements for pharmaceutical field forces.
- Shop-floor digitization:Manufacturers automate approval chains and dispatch protocols through workflow automation modules embedded in mobile content platforms.
- Germany:Industrial Mittelstand clusters drive concentrated demand for ruggedized device management solutions integrating with legacy SCADA infrastructure.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dominance in Western Europe creates vendor lock-in risks for enterprises requiring data residency guarantees under GDPR.
- Containerization performance overhead:Encryption and policy enforcement layers introduce latency that degrades real-time collaboration on low-bandwidth field networks.
- Substitution by native MDM:Device manufacturers bundle increasingly capable mobile device management tools that erode standalone content security value propositions.
Strategic Opportunities
- India:PLI scheme incentives for electronics manufacturing create demand for secure content distribution across distributed production facilities.
- EU AI Act compliance services:Algorithmic transparency requirements open revenue streams for vendors offering automated documentation and explainability tooling.
- Edge-AI convergence:On-device inference capabilities enable offline content classification and policy enforcement without cloud round-trips.
Industry Challenges
- Zero-trust engineering talent scarcity:Shortage of architects capable of implementing continuous verification architectures slows enterprise deployment timelines.
- EMA validation documentation:Pharmaceutical content platforms require 12-18 month qualification cycles that compress competitive windows.
- Legacy ERP integration friction:SAP and Oracle back-end connectivity demands custom middleware development for policy synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Content Management Market |
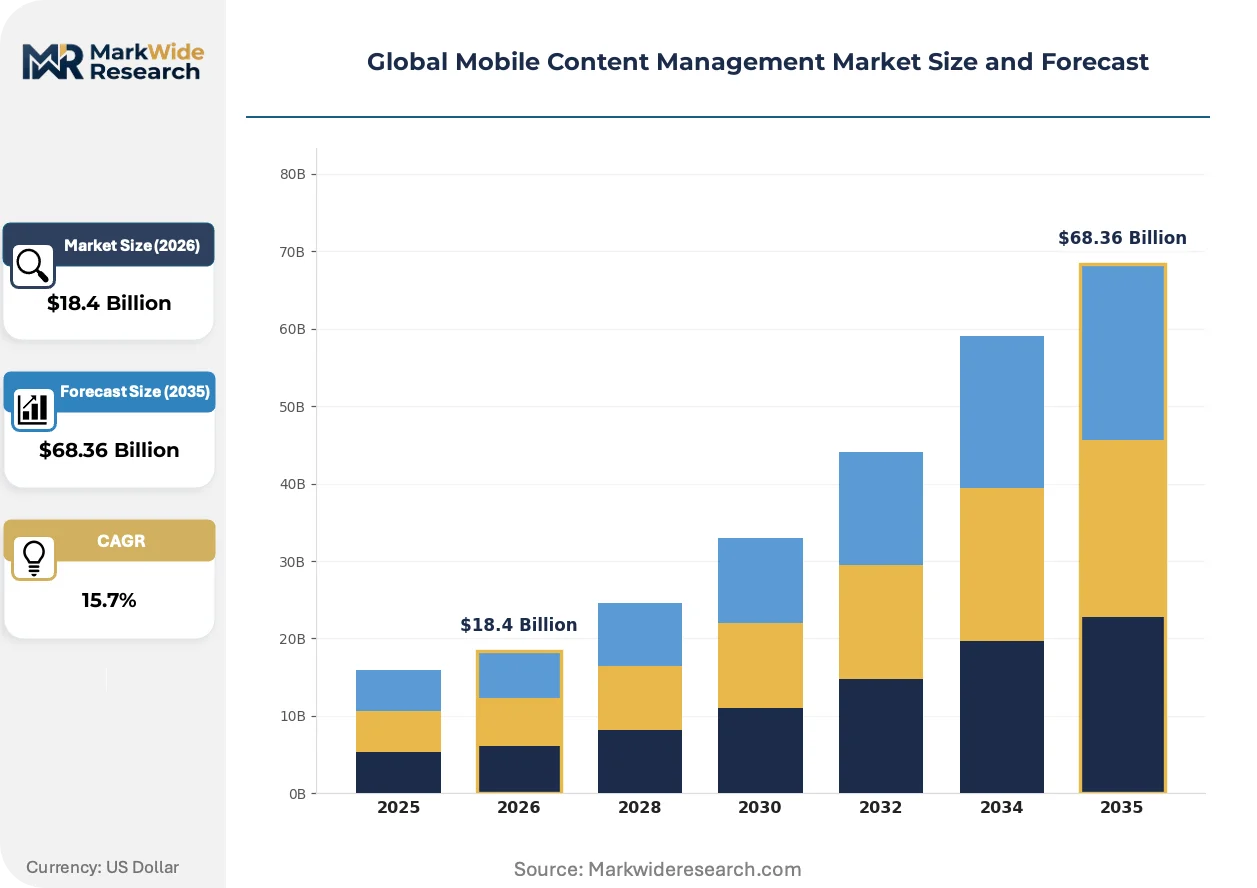
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $68.36 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Content Security, Collaboration Tools, Document Management, Workflow Automation, Data Analytics Use Case: Field Services, Legal Case Management, Sales Enablement, Training & Development, Customer Support End User Industry: Financial Services, Manufacturing, Education, Hospitality, Public Sector |
| Companies Covered | Microsoft Corporation, IBM Corporation, Cisco Systems, VMware, Inc., SAP SE, Adobe Inc., Citrix Systems, Inc., Google LLC, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Content Management Market Shifts & Advancements
Platform architectures are fragmenting as sovereignty requirements and edge computing capabilities redistribute processing away from centralized cloud infrastructure toward hybrid and on-premises deployment models.
Containerization technology is decomposing monolithic mobile content platforms into modular microservices that enable selective deployment of encryption, DLP, and synchronization functions. Healthcare systems in the United States adopt containerized clinical documentation modules faster than full-suite replacements. This decomposition allows CIOs to swap individual security components without forklift upgrades.
GDPR Article 44 transfer mechanism restrictions are compelling non-European cloud providers to establish localized infrastructure or exit sensitive data processing markets. German and French healthcare authorities now reject platform certifications lacking EU-based encryption key custody. Vendors respond by licensing technology to regional hosting partners rather than operating direct services.
Subscription-to-outcome contracting is compressing sales cycles as procurement teams demand guaranteed breach remediation cost coverage rather than per-seat licensing. Financial services institutions in Singapore and Australia lead this shift, tying vendor payments to measurable reduction in data loss incidents. Implementation timelines shorten where vendors accept liability transfer clauses.
Global Mobile Content Management Market Segmentation
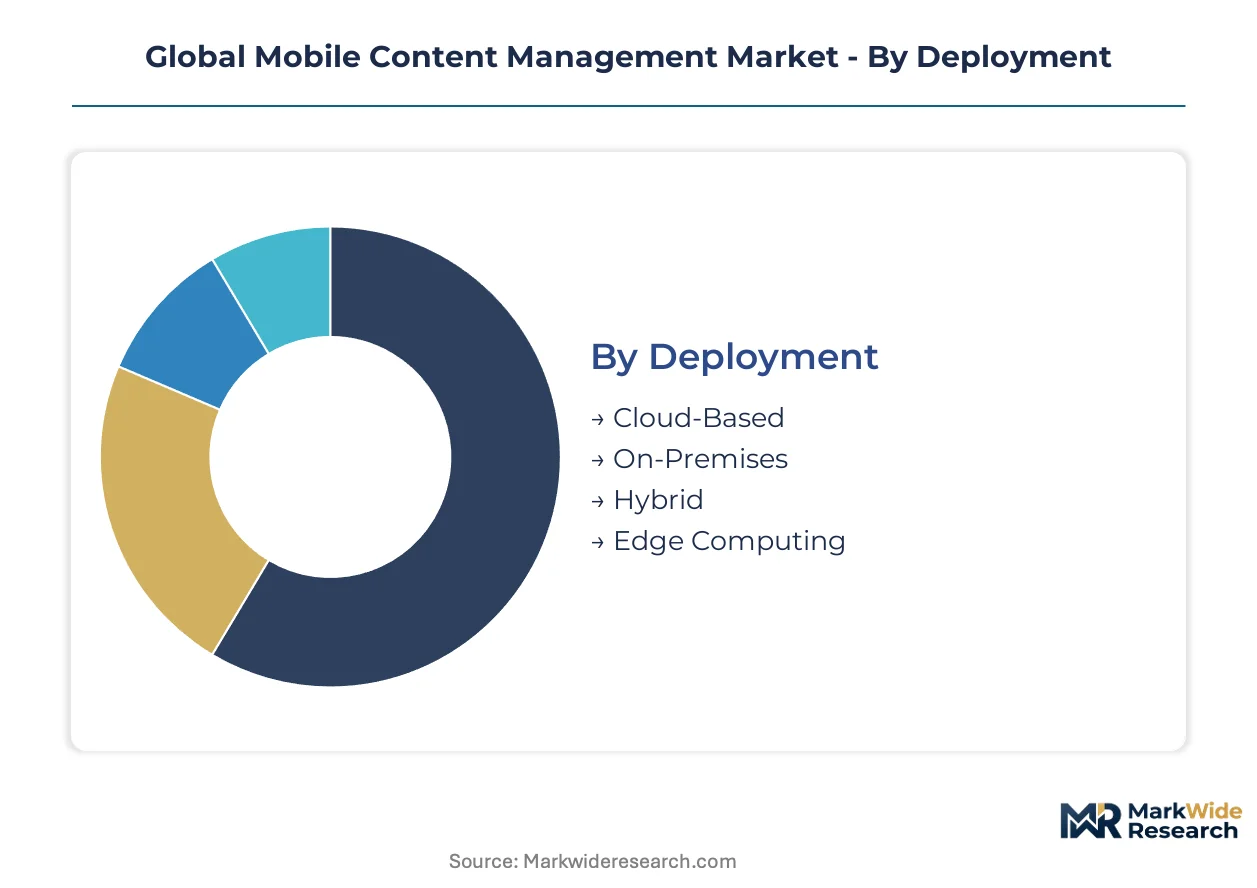
Deployment architecture determines channel economics and margin capture for mobile content platforms. Solution type dictates compliance burden and integration complexity. Use case and end-user industry shape pricing power and contract duration.
Deployment:
Cloud-Based solutions flow through direct vendor sales and hyperscaler marketplaces. On-Premises and Hybrid deployments route through systems integrators and value-added resellers. Edge Computing penetrates via industrial automation distributors.
- Cloud-Based:Multi-tenant SaaS platforms deliver encryption, containerization, and policy enforcement through centralized infrastructure. Financial services institutions in Singapore and Australia concentrate demand here, driven by subscription-to-outcome contracting that ties vendor payments to measurable breach reduction.
- Hybrid:Architectures split sensitive data processing on-premises while leveraging cloud scalability for non-critical workloads. German healthcare authorities mandate this model under GDPR Article 44 transfer restrictions, requiring EU-based encryption key custody for clinical content.
- On-Premises:Fully captive infrastructure serving defense contractors and classified government facilities with air-gapped security requirements.
- Edge Computing:On-device inference enables offline content classification and policy enforcement without cloud round-trips, penetrating manufacturing shop floors with low-bandwidth constraints.
By volume, Cloud-Based leads. By growth pace, Edge Computing is climbing the fastest.
Solution Type:
Cost tier stratification separates premium-certified platforms from standard compliance offerings. Content Security commands the highest per-seat pricing due to breach remediation guarantees.
- Content Security:Encryption protocols, data loss prevention, and containerization enforce policy-driven access controls across distributed workforces. Escalating breach remediation costs concentrate enterprise procurement here, with FDA 21 CFR Part 11 validation requirements further tightening healthcare specifications.
- Workflow Automation:Digitized approval chains and dispatch protocols embedded in mobile platforms. Manufacturers automating shop-floor processes drive steepest expansion trajectory for this segment.
- Collaboration Tools:Real-time document co-editing and offline synchronization for field teams.
- Document Management:Centralized repository functions with version control and audit trails.
- Data Analytics:Usage pattern analysis and content performance dashboards for platform administrators.
By margin contribution, Content Security dominates. By expansion velocity, Workflow Automation gains share fastest.
Use Case:
Application maturity varies sharply: Field Services and Sales Enablement represent established deployments, while Legal Case Management demands specialized compliance tooling.
- Field Services:Ruggedized device management with offline synchronization for technicians operating beyond reliable connectivity. German industrial Mittelstand clusters concentrate demand, integrating mobile platforms with legacy SCADA infrastructure.
- Legal Case Management:Privilege-protected document handling with chain-of-custody tracking. E-discovery integration requirements and bar association ethics rules create specialized procurement criteria.
- Sales Enablement:Content distribution to mobile representatives with usage analytics and pitch optimization.
- Training & Development:Microlearning delivery and certification tracking for distributed workforces.
- Customer Support:Knowledge base access and case resolution tools for mobile service agents.
By installed base, Field Services leads. By contract value growth, Legal Case Management is pulling ahead.
End User Industry:
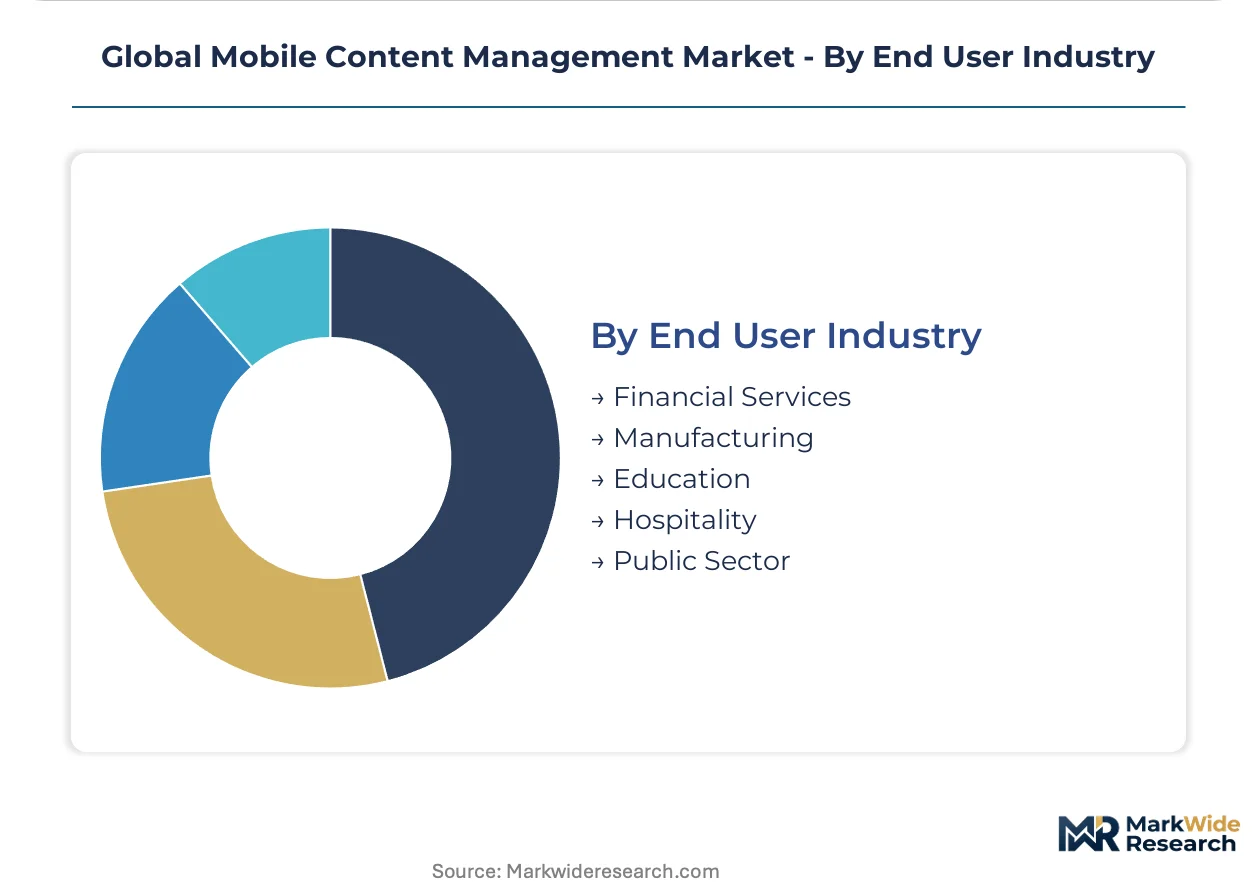
Customer type determines sales cycle length and customization depth. Financial Services and Public Sector impose the most stringent certification requirements.
- Financial Services:Zero-trust architecture mandates from federal agencies restructure procurement criteria, forcing continuous authentication recertification. Singapore and Australian institutions pioneer subscription-to-outcome contracting with liability transfer clauses.
- Manufacturing:Shop-floor digitization automates approval chains and dispatch protocols. India's PLI scheme incentives for electronics manufacturing create distributed production facility demand.
- Public Sector:Sovereign data residency requirements and classified information handling specifications.
- Education:Campus-wide mobile learning platforms with FERPA-compliant student data protection.
- Hospitality:Guest service optimization and staff coordination across property portfolios.
By compliance spend per employee, Financial Services leads. By deployment acceleration, Manufacturing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in financial services and healthcare sectors drive geographic demand concentration. Federal zero-trust mandates in the United States reshape vendor qualification criteria. European data residency requirements fragment platform architectures across national boundaries.
United States
Healthcare systems and federal agencies dominate enterprise procurement volumes. FDA 21 CFR Part 11 validation requirements force audit trail capabilities into clinical mobile documentation platforms. The Boston-Cambridge biotech corridor concentrates pharmaceutical field force deployments requiring electronic signature compliance.
Germany
Industrial Mittelstand manufacturers automate shop-floor approval chains through workflow modules. GDPR Article 44 transfer restrictions compel EU-based encryption key custody for clinical content processing. The Stuttgart automotive cluster integrates ruggedized device management with legacy SCADA infrastructure.
India
Electronics manufacturing incentives under the PLI scheme create distributed production facility demand. RBI guidelines on data localization influence financial institution procurement criteria. The Bengaluru-Telangana technology corridor hosts deployment of secure content distribution across multi-site operations.
Singapore
Financial services institutions pioneer subscription-to-outcome contracting with liability transfer clauses. MAS technology risk management guidelines shape vendor certification requirements. The Marina Bay financial district concentrates demand for breach-remediation-guaranteed platforms.
Australia
Banking and insurance sectors drive zero-trust architecture adoption across mobile data access points. APRA CPS 234 information security requirements mandate continuous authentication recertification. The Sydney-Melbourne financial corridor leads outcome-based vendor payment structures tied to measurable incident reduction.
Global Mobile Content Management Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with cloud infrastructure backbones. The vendor base concentrates around three strategic archetypes: hyperscale platform providers with native security integration, virtualization specialists extending endpoint infrastructure control, and enterprise software incumbents bundling content management into broader productivity suites. Competitive moves center on hybrid deployment certification for regulated industries and localized infrastructure partnerships to satisfy data residency mandates.
Within the hyperscale platform tier, Microsoft Corporation and Google LLC anchor positions through cloud-native delivery models. VMware, Inc. and Citrix Systems, Inc. occupy specialist positions in workspace virtualization. IBM Corporation exemplifies the enterprise systems integrator archetype combining consulting services with platform deployment. These named entities represent the competitive concentration visible in procurement data without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Cisco Systems |
| VMware, Inc. |
| SAP SE |
| Adobe Inc. |
| Citrix Systems, Inc. |
| Google LLC |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Hyperscale cloud infrastructure utilization rates above 80 percent in Western Europe and North America create margin compression dynamics that cascade through vendor pricing structures and enterprise procurement negotiations. This capacity concentration forces mid-tier platform providers to absorb infrastructure costs or exit regulated segments, while buyers with multi-year commitments extract performance guarantees that reset price floors annually.
Pricing Analysis
Cost-plus contracts with AWS and Azure price indexation clauses dominate enterprise SaaS procurement, embedding hyperscaler margin expansion into downstream vendor economics. Pricing stratifies across ISO 27001-certified premium tiers, standard compliance offerings, and economy self-service modules, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier intensifies because native MDM bundling erodes standalone value propositions. Healthcare and financial services buyers demonstrate lowest price sensitivity due to breach remediation liability exposure, while education and hospitality segments drive hardest bargain terms.
Supply Chain Analysis
Just-in-time infrastructure provisioning prevails among cloud-native vendors, though GDPR Article 44 compliance has forced strategic stockpiling of EU-based encryption hardware by healthcare-focused providers. Supply concentration centers on the United States, Ireland, and Germany for hyperscale data center capacity, with Singapore and Australia as secondary hubs for Asia-Pacific financial services. Component dependencies include specialized HSM modules, containerization microservices stacks, and zero-trust authentication SDKs. Single-source vulnerability in EU-based encryption key custody creates regulatory lock-in risk. Distribution runs through direct vendor sales, hyperscaler marketplaces, and systems integrators serving hybrid deployment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile content management market is entering a cyclical recovery phase as enterprise IT modernization budgets rebound from post-pandemic austerity, with federal zero-trust mandates acting as the primary cyclical accelerator forcing replacement cycles.
For Market Incumbents: Fortify hybrid deployment certification portfolios to defend against VMware and Citrix workspace virtualization specialists encroaching on endpoint infrastructure control. Prioritize EU-based infrastructure partnerships to neutralize GDPR Article 44 transfer mechanism risks that threaten non-European cloud provider market access. Deepen vertical integration into containerized microservices development to accelerate healthcare module swap-out cycles without forklift upgrades. For New Entrants and Emerging Players: FDA 21 CFR Part 11 fast-track validation services open white-space in pharmaceutical field force documentation, where 12-18 month qualification cycles compress competitive windows for established vendors. Target India's PLI scheme electronics manufacturing clusters with ruggedized device management solutions integrating legacy SCADA infrastructure. Pursue outcome-based contracting pilots with Singapore financial institutions to bypass per-seat pricing commoditization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors containerization specialists with healthcare certification depth over monolithic platform consolidators facing decomposition pressure. Long-term viability over a 5-10 year window rests on edge-AI inference capabilities that enable offline policy enforcement without cloud dependency. The signal to watch is EMA validation documentation backlog length as an inflection indicator for pharmaceutical content platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | Federal agency mandates force continuous authentication recertification across financial services procurement. |
| EU Data Residency Partnership | GDPR Article 44 restrictions compel localized encryption key custody for German healthcare authority approval. |
| Containerized Microservices Decomposition | Healthcare CIOs swap individual security components without full platform replacement, accelerating sales cycles. |
| Outcome-Based Contracting Pilot | Singapore banks tie vendor payments to measurable breach reduction, compressing implementation timelines. |
| Edge-AI Inference Development | On-device content classification enables offline policy enforcement for low-bandwidth manufacturing shop floors. |
Research Methodology
A standing panel of CISOs, healthcare IT procurement directors, federal agency technology officers, and systems integration specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie enterprise mobility metrics, and FDA 510(k) submission databases. Bottom-up deployment volume estimates triangulated against top-down addressable market sizing from healthcare and financial services employment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment architecture, solution type, use case maturity, and end-user industry vertical with regional adoption pattern overlays. CAGRs derived from segment-level growth rate reconciliation against macro IT spending forecasts, with zero-trust mandate implementation timelines and GDPR enforcement intensity as key mobile content management-specific inputs.
Decision-makers should treat outputs as directional under assumptions of sustained federal compliance mandate enforcement and stable hyperscaler pricing; material deviation in either would warrant model refresh. Revision becomes warranted when native MDM capability bundling crosses thresholds that eliminate standalone content security value propositions in enterprise segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Data Governance Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
P2P Rental Apps Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
AI Marketing Tool Market
Digital Solutions
Harbor Management Software Market
Digital Solutions
Transport Management System Market