
 Global Data Historian Market | 2026-2036
Global Data Historian Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Historian Market Foresight
Multi-source software procurement is repositioning how industrial enterprises acquire data historian capabilities. AVEVA leverages cloud-native architectures to extend its footprint across hybrid deployments. Siemens anchors European demand through deep integration with automation hardware portfolios. Honeywell International competes on process industry specialization, particularly in refining and petrochemical verticals.
A data historian is a time-series database system engineered to capture, compress, and archive high-frequency operational data from industrial control systems, typically supporting millisecond-resolution timestamps and proprietary compression algorithms to manage terabyte-scale datasets. Its primary purpose is to enable longitudinal process analysis, regulatory evidence retention, and predictive diagnostics across continuous and batch manufacturing environments. Deployment configurations show cloud-based and hybrid cloud models gaining traction as facilities prioritize remote accessibility and IT-OT convergence, while on-premise installations retain dominance in highly regulated sites with strict air-gap requirements. End user industry dynamics reveal energy and utilities commanding the largest installed base, though predictive maintenance applications within manufacturing plants represent the fastest-expanding margin pool.
The US EPA mandates emissions monitoring and record-keeping that directly necessitate historian-backed audit trails for power generation and chemical processing facilities. IEC 61850 and ISO 27001 jointly shape product requirements, with cybersecurity standards tightening market access for vendors lacking certified data governance frameworks. Stakeholders must evaluate whether edge-deployment architectures or centralized cloud aggregation better aligns with evolving OT cybersecurity postures and cross-border data residency constraints.
Market Dynamics
IT-OT convergence is compressing deployment timelines for data historian platforms as industrial enterprises demand real-time visibility across hybrid infrastructure without compromising air-gapped security postures.
Growth Catalysts
- EPA emissions mandates:US power generation and chemical processing facilities require timestamped audit trails for regulatory evidence retention, directly necessitating high-fidelity historian architectures.
- Wind turbine fleet digitization:Offshore wind operators deploy millisecond-resolution monitoring to optimize blade pitch algorithms and predictive gearbox maintenance across North Sea installations.
- IEC 61850 standardization:Substation automation interoperability requirements accelerate replacement of proprietary SCADA archives with standardized time-series databases.
Market Restraints
- Specialized OT cybersecurity talent scarcity:Certified industrial security architects command premium compensation, inflating implementation costs for mid-sized manufacturing facilities.
- Legacy protocol fragmentation:Proprietary DCS communication stacks from 1990s-era installations resist native integration with modern REST API historian architectures.
- Edge hardware supply concentration:Industrial-grade time-series compute modules depend on concentrated semiconductor fabrication in East Asian foundries.
Strategic Opportunities
- Saudi giga-project industrialization:NEOM and Red Sea tourism developments require greenfield historian deployment for smart city infrastructure and desalination plant optimization.
- ISO 50001 energy management convergence:Manufacturing facilities combine historian data with energy accounting systems to satisfy certification and carbon disclosure requirements.
- Pharmaceutical batch record unification:FDA 21 CFR Part 11 compliance drives replacement of paper-based batch records with electronic historian-backed manufacturing execution systems.
Industry Challenges
- Millisecond timestamp synchronization:Distributed control architectures spanning multiple plants struggle to maintain coherent event sequencing across network latency variations.
- Terabyte-scale compression algorithm optimization:Engineering teams balance storage cost reduction against query performance degradation when selecting proprietary versus open-source compression schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Historian Market |
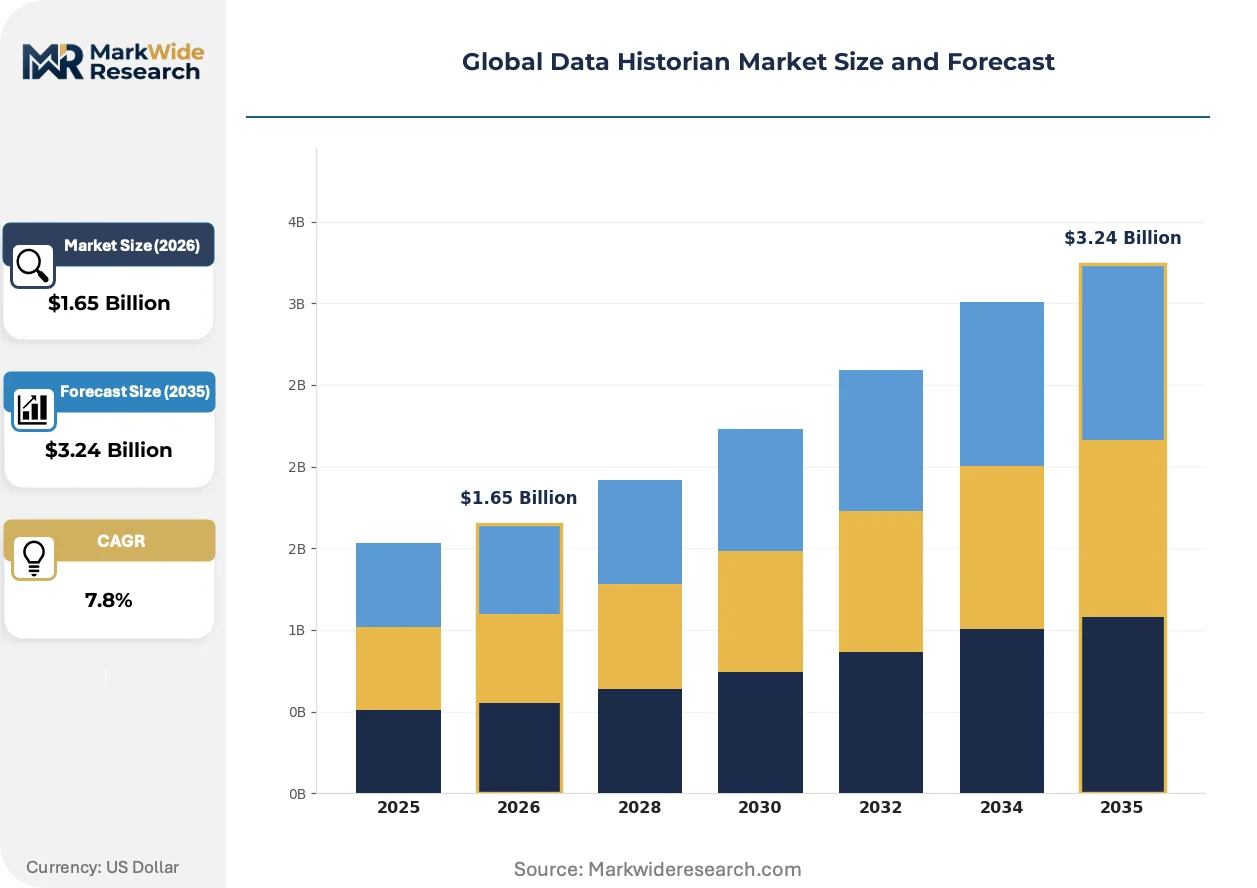
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid Cloud, Edge Deployment Solution Type: Real-Time Data Acquisition, Historical Data Storage, Analytics Integration, Visualization Tools, Reporting Modules End User Industry: Energy & Utilities, Manufacturing Plants, Chemical Processing, Oil & Gas Exploration, Power Generation Application: Process Monitoring, Quality Control, Predictive Maintenance, Compliance Reporting, Operational Optimization |
| Companies Covered | Siemens, AVEVA, General Electric, ABB, Emerson Electric, Honeywell International, Rockwell Automation, IBM, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Historian Market Shifts & Advancements
Cloud-native architectures are displacing monolithic on-premise deployments as vendors compete to deliver elastic scalability without sacrificing deterministic response times critical to process control.
Edge-deployed time-series pre-processing is electrifying data historian architectures by filtering noise and executing anomaly detection before cloud transmission. Chemical processing facilities in the US Gulf Coast adopt these architectures aggressively to reduce bandwidth costs and satisfy OSHA process safety management requirements for local alarm response. The structural consequence is compressing centralized cloud aggregation models in favor of distributed intelligence hierarchies.
EU CSRD sustainability reporting mandates force industrial facilities to harmonize operational historian data with financial disclosure systems. German automotive manufacturers face particular pressure to document Scope 3 emissions through supplier chain traceability. Battery cell production lines in Hungary and Poland respond by deploying unified historian-ERP integration platforms that automate carbon intensity calculations per production batch.
Subscription-based historian licensing is displacing perpetual software ownership across North American manufacturing sectors. Mid-sized food and beverage processors in the US Midwest prefer operational expenditure models that bundle maintenance and cybersecurity updates. This shift is most visible in dairy processing cooperatives where seasonal production variability makes fixed capital commitments economically unattractive.
Global Data Historian Market Segmentation
Data historian procurement decisions hinge on certification burdens, deployment constraints, and end-use regulatory exposure. Segmentation reveals where compliance complexity concentrates margin capture and which configurations face steepest validation requirements.
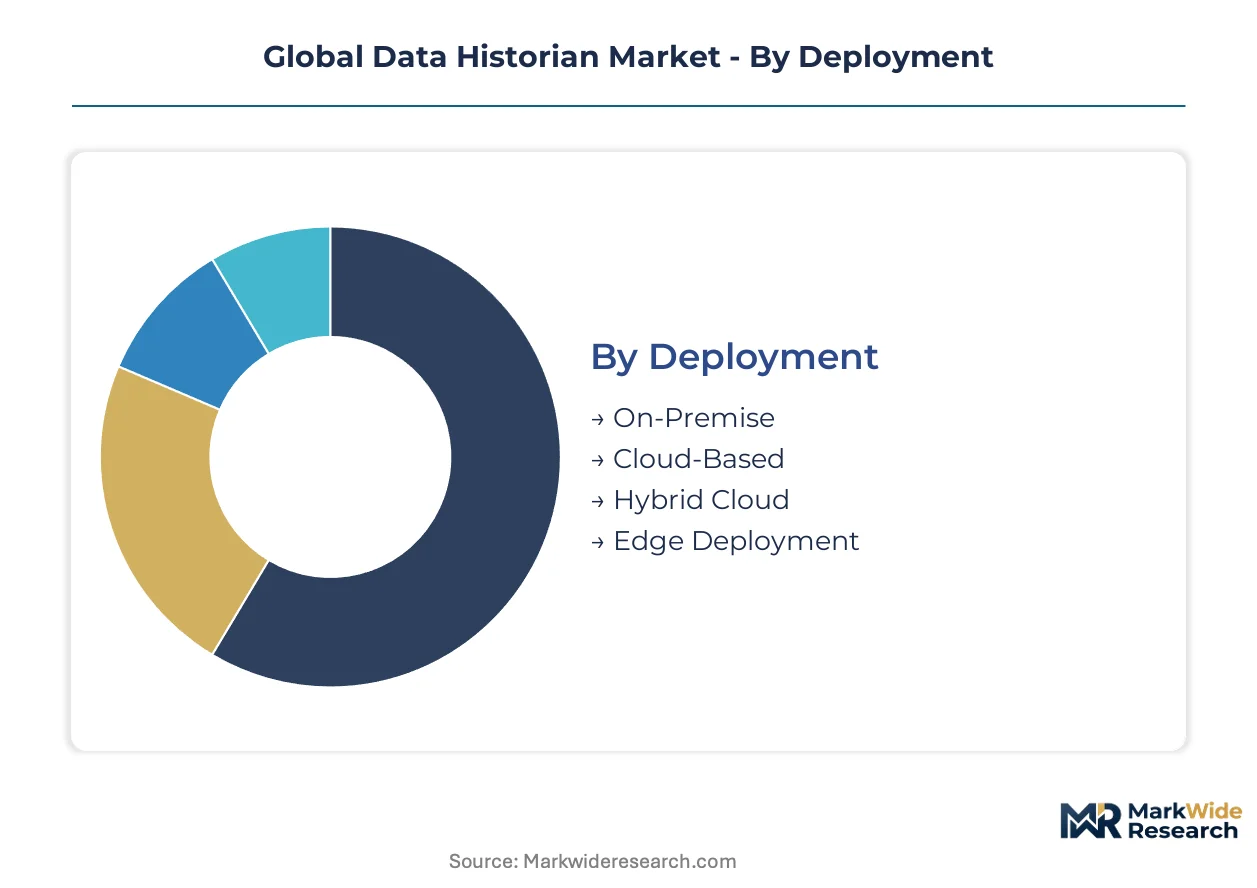
Deployment:
On-premise installations carry the heaviest certification burden under FDA 21 CFR Part 11 and EPA emissions audit mandates, while cloud and edge variants navigate ISO 27001 and IEC 62443 cybersecurity frameworks with differing evidence packages.
- On-Premise:Air-gapped server architectures with proprietary compression engines dominate pharmaceutical batch record retention and nuclear facility safety parameter display systems. German chemical manufacturers prefer these configurations for REACH documentation integrity.
- Cloud-Based:Elastic storage pools with REST API ingestion support remote wind farm monitoring and distributed solar asset management. US independent power producers adopt these for FERC compliance reporting without capital-intensive infrastructure.
- Hybrid Cloud:Tiered architectures buffer critical control data locally while archiving non-operational datasets to public cloud tiers. Japanese automotive plants deploy these for METI-mandated supply chain traceability with domestic data residency.
- Edge Deployment:Ruggedized time-series compute modules preprocess millisecond-resolution turbine vibration data before upstream transmission. North Sea offshore operators favor these for bandwidth-constrained environments.
On-premise sits at the top of the volume ranking, with edge deployment climbing the fastest.
Solution Type:
Cost tiering separates validated mission-critical modules from commodity visualization layers, with acquisition budgets clustering around real-time acquisition and regulatory reporting bundles.
- Real-Time Data Acquisition:Millisecond-precision ingestion engines with OPC UA and MQTT protocol handlers capture turbine SCADA streams and refinery DCS tags. Saudi Aramco's upstream facilities specify these for wellhead pressure monitoring across Ghawar field.
- Historical Data Storage:Proprietary compression algorithms managing petabyte-scale archives support decade-long EPA emissions evidence retention. US Gulf Coast petrochemical complexes require these for Clean Air Act audit trails.
- Analytics Integration:Machine learning pipelines for anomaly detection and predictive correlation. Indian cement manufacturers adopt these for CEA energy efficiency compliance.
- Visualization Tools:Operator dashboards and trend displays with role-based access controls. Brazilian sugar-ethanol mills deploy these for ANVISA batch process oversight.
- Reporting Modules:Automated regulatory document generation with electronic signature workflows. EU battery cell producers integrate these for CSRD carbon disclosure automation.
Historical data storage commands the largest installed base, with analytics integration gaining share fastest.
End User Industry:
Application maturity varies sharply, with energy and utilities holding decades of operational telemetry while battery manufacturing represents greenfield deployment opportunity.
- Energy & Utilities:Transmission grid operators and distribution utilities deploy historians for IEC 61850 substation automation and renewable integration monitoring. TenneT in the Netherlands relies on these for North Sea offshore wind corridor balancing.
- Manufacturing Plants:Discrete and batch producers unify PLC data for OEE metrics and predictive maintenance. Hungarian automotive suppliers connect these to ERP systems for Scope 3 emissions tracking.
- Chemical Processing:Continuous reactors and batch trains require OSHA process safety management alarm archiving. BASF's Ludwigshafen complex maintains these for Seveso III directive compliance.
- Oil & Gas Exploration:Subsea wellhead monitoring and pipeline integrity management across harsh environments. Petrobras deploys these for pre-salt field digital twin construction.
- Power Generation:Combined cycle gas turbines and coal fleet optimization with emissions monitoring. Uniper's German plants utilize these for EU ETS verification data.
Energy and utilities sits at the top of the volume ranking, with manufacturing plants climbing the fastest.
Application:
Margin concentration aligns with regulatory enforcement intensity, where compliance reporting commands premium pricing against commoditized process monitoring.
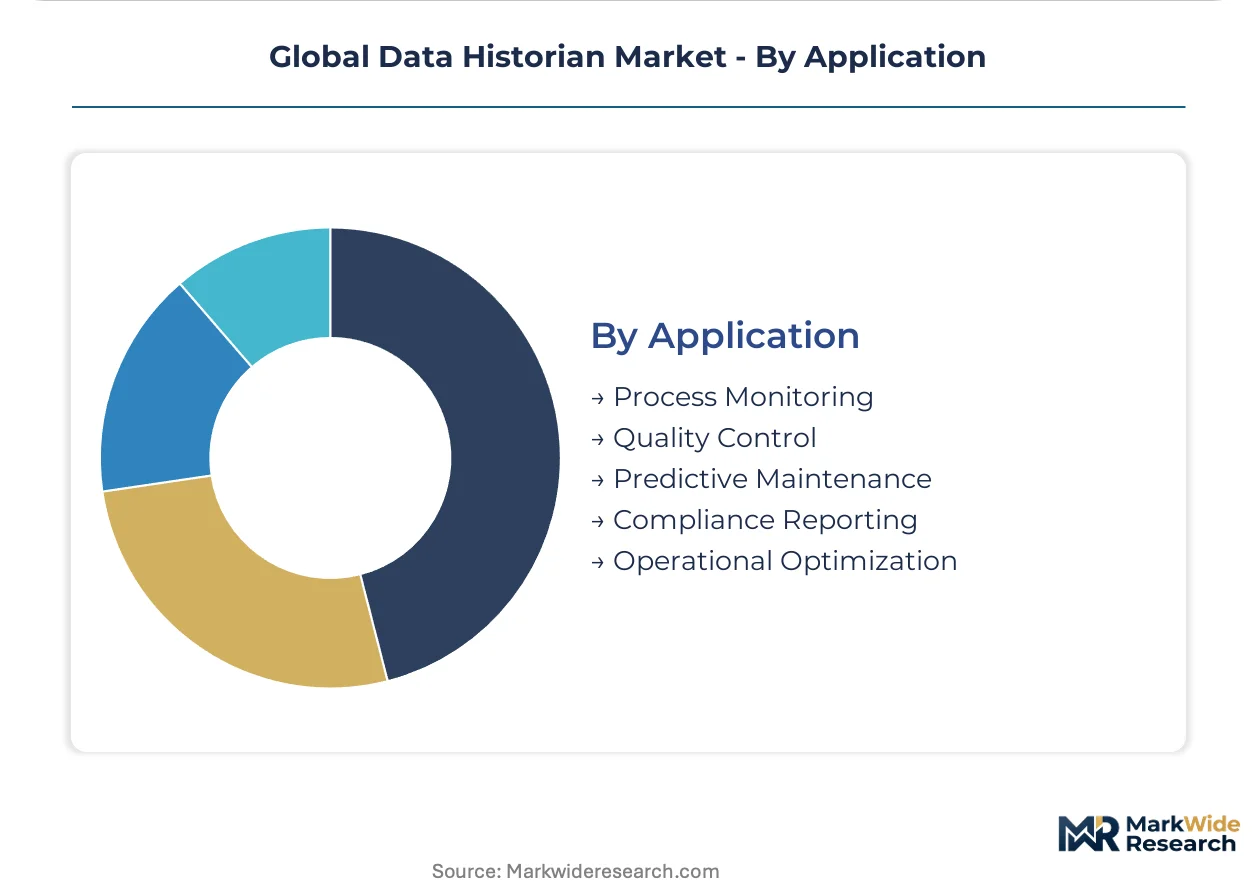
- Process Monitoring:Real-time operational visibility for control room operators and shift supervisors. South Korean steelmakers at POSCO deploy these for blast furnace thermal profiling.
- Quality Control:Statistical process control integration with LIMS for batch deviation detection. Swiss pharmaceutical manufacturers at Lonza employ these for FDA inspection readiness.
- Predictive Maintenance:Vibration analysis and thermal trend forecasting for rotating equipment. Australian mining operators at BHP use these for remote conveyor belt monitoring.
- Compliance Reporting:Structured evidence packages for EPA, EMA, and national regulator submissions. French nuclear operators at EDF maintain these for ASN safety case documentation.
- Operational Optimization:Energy intensity reduction and throughput maximization algorithms. Canadian oil sands producers at Suncor apply these for carbon cost minimization.
Process monitoring sits at the top of the volume ranking, with predictive maintenance climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial software development anchors European demand concentration for data historian platforms, with Siemens anchoring automation hardware integration across Ludwigshafen chemical complexes and Bavarian automotive plants.
United States
Power generation utilities and Gulf Coast petrochemical operators drive procurement intensity. EPA emissions mandates under the Clean Air Act require timestamped audit trails that directly necessitate high-fidelity historian architectures. Houston and Louisiana chemical processing corridors deploy these systems for OSHA process safety management compliance.
Germany
Automotive manufacturers and chemical producers dominate enterprise adoption patterns. EU CSRD sustainability reporting mandates force facilities to harmonize operational historian data with financial disclosure systems. BASF's Ludwigshafen complex and Bavarian battery cell production lines deploy unified historian-ERP integration for Scope 3 emissions documentation.
China
Steelmakers and cement manufacturers accelerate digitization of legacy production assets. The country's dual carbon goals pressure industrial facilities to unify energy accounting with operational data streams. Yangtze River Delta heavy industry clusters adopt millisecond-resolution monitoring for blast furnace thermal profiling and energy intensity reduction.
Saudi Arabia
NEOM giga-projects and Red Sea tourism developments require greenfield historian deployment for smart city infrastructure. Saudi Aramco's upstream facilities specify real-time data acquisition modules for wellhead pressure monitoring across the Ghawar field. Desalination plant optimization drives edge-deployment architectures in bandwidth-constrained environments.
Japan
Automotive plants and electronics manufacturers prioritize hybrid cloud configurations with domestic data residency. METI-mandated supply chain traceability requirements shape procurement decisions. Toyota City and Nagoya industrial corridors deploy tiered architectures that buffer critical control data locally while archiving non-operational datasets to compliant cloud tiers.
Global Data Historian Market Competitive Landscape
Global majors compete with regional champions across automation hardware integration and cloud-native deployment capabilities. Market structure consolidates around three tiers: diversified industrial conglomerates with captive software portfolios, pure-play industrial software specialists, and cloud-native platform vendors entering from adjacent IT markets. Dominant competitive moves include strategic partnerships between automation hardware vendors and hyperscale cloud providers, plus portfolio diversification through vertical integration into edge compute modules.
Within the diversified industrial tier, Siemens and ABB exemplify European automation conglomerates that anchor demand through deep hardware-software integration. AVEVA represents the pure-play software specialist archetype, competing on cloud-native architectures and hybrid deployment flexibility. Honeywell International occupies a position among process industry-focused conglomerates with particular concentration in refining and petrochemical verticals. These three anchors illustrate how vendor selection increasingly hinges on existing automation infrastructure ownership and regulatory compliance specialization rather than standalone software capabilities.
| Leading Market Players |
|---|
| Siemens |
| AVEVA |
| General Electric |
| ABB |
| Emerson Electric |
| Honeywell International |
| Rockwell Automation |
| IBM |
| Yokogawa Electric Corporation |
| Others |
Supply & Pricing Matrix
Mid-sized food and beverage processors in the US Midwest demanding operational expenditure models over capital-intensive perpetual licenses force vendors to restructure software delivery architectures, compressing upfront revenue recognition and shifting margin capture toward recurring service bundles.
Pricing Analysis
Input-cost pass-through from semiconductor fabrication and industrial-grade edge compute modules drives subscription tier adjustments, particularly for bandwidth-intensive cloud-native deployments. Three-tier pricing structure across premium, standard, and economy levels separates validated FDA 21 CFR Part 11 compliance bundles from commodity visualization layers. Cost compression in the economy tier intensifies because hyperscale cloud providers are commoditizing storage pools. Pharmaceutical batch record retention buyers show least price sensitivity; seasonal dairy cooperatives exhibit highest.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia's NEOM developments and Japan's METI-mandated data residency requirements reshape sourcing toward localized assembly of ruggedized time-series compute modules. Semiconductor fabrication concentrates in Taiwan, South Korea, and China. Raw material dependencies include advanced memory chips, precision timing oscillators, and industrial-grade enclosures. Single-source vulnerability from East Asian foundry concentration threatens edge hardware availability. Distribution runs through automation hardware OEMs and direct enterprise software procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in data historian platforms rests on cloud-native delivery cost-down trajectories and premium-tier certification bundling for pharmaceutical and nuclear safety applications.
For Market Incumbents: Cement hybrid deployment dominance through captive edge hardware production and IEC 62443 certification pre-validation. Deepen integration with Siemens and ABB automation portfolios to lock out pure-play cloud entrants. Prioritize backward integration into time-series compute module manufacturing to offset semiconductor supply volatility. For New Entrants and Emerging Players: Capture predictive maintenance applications in battery cell manufacturing as the fastest-penetrating greenfield segment. ISO 50001 energy management convergence in Hungarian and Polish production lines offers unclaimed white space. Lead with API-first architectures that bypass legacy DCS protocol fragmentation. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platform vendors possessing OT cybersecurity certification frameworks and hybrid deployment flexibility. Five-to-ten year viability favors pure-play specialists over diversified conglomerates with captive software portfolios. Watch IEC 61850 substation automation replacement cycles as inflection indicator for standardized time-series database demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies historian-ERP systems for EU CSRD carbon disclosure automation in German automotive plants. |
| Strategic Partnership | Links automation hardware vendors with hyperscale cloud providers for hybrid deployment elasticity. |
| Acquisition of Specialist Firm | Adds millisecond-resolution compression algorithms for terabyte-scale EPA emissions evidence retention. |
| Geographic Expansion | Targets Saudi giga-projects and Red Sea desalination plant optimization for greenfield edge deployment. |
| Product Launch | Introduces subscription-based licensing for mid-sized North American food and beverage processors. |
Research Methodology
Bottom-up end-use industry modeling reconciled against top-down supply-side tracking forms the analytical core. Primary interviews with control system engineers, OT cybersecurity architects, plant managers at chemical processing facilities, and procurement leads at power generation utilities combined with secondary validation from FERC filings, EPA emissions databases, IEC standard documentation, and SEC 10-K software revenue disclosures. Triangulation validates deployment configuration splits and solution type adoption curves.
Input-output matrices map historian data ingestion volumes against compression algorithm efficiency gains and cloud storage cost trajectories across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type tier, end-use industry vertical, and application purpose. CAGRs derive from regression of historical utility capital expenditure patterns and manufacturing digitization survey data. Forecast inputs incorporate offshore wind fleet expansion timelines and pharmaceutical batch record digitization mandates.
Regulatory enforcement intensity shifts, semiconductor supply disruption duration, and OT cybersecurity talent availability are the dominant revision risks. Forecasts reflect documented assumptions on IEC 61850 adoption velocity and cloud migration willingness in air-gapped nuclear facilities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Agriculture Software Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Asia-Pacific Data Monetization Market
Digital Solutions
Indonesia Digital Software Solutions Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Enterprise Mobility Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Real Time Store Monitoring Platform Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Email Marketing Market