
 Digital Marketing Software Market | 2026-2036
Digital Marketing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Marketing Software Market Intelligence
Generative AI integration into campaign orchestration layers is reconfiguring how marketing teams architect customer journeys. HubSpot leverages its inbound methodology to anchor mid-market adoption across CRM-adjacent workflows. ZoomInfo sustains its data moat through proprietary B2B contact intelligence that rivals generic intent platforms. Hootsuite competes by extending social listening into predictive audience segmentation tools.
Digital marketing software encompasses applications that automate, measure, and optimize promotional activities across digital channels through algorithms processing behavioral signals, conversion events, and attribution models. Cloud-based deployment dominates solution delivery, though hybrid architectures gain traction among financial services firms subject to data residency requirements. Marketing automation captures the deepest margin pools due to recurring subscription structures and workflow stickiness, while social media management segments experience the fastest uptake from influencer economy participants. Content management solutions remain mature, with differentiation shifting toward AI-assisted asset generation rather than repository scale.
The EU AI Act, GDPR, and FCC truth-in-advertising standards collectively reshape product roadmaps by mandating explainability in automated decisioning and consent granularity in data collection. California's CCPA amplifies these pressures for vendors serving US enterprise clients. Stakeholders must monitor evolving algorithmic accountability frameworks that could bifurcate product development between privacy-preserving and performance-optimized architectures.
Market Dynamics
Generative AI is compressing campaign production timelines while fragmenting vendor control over creative workflows, forcing incumbents to rebuild orchestration layers around prompt-to-deployment pipelines rather than static template libraries.
Growth Catalysts
- EU AI Act:Explainability mandates for automated personalization engines are accelerating procurement of compliant martech stacks by European retail and financial services advertisers.
- Programmatic media migration:CPG and retail brands are redirecting television and print budgets into algorithmic buying platforms that optimize creative rotation in real time.
- Cloud-native architectures:Containerized deployment models are reducing implementation friction for mid-market marketing automation deployments across North American and Asian enterprise subsidiaries.
Market Restraints
- First-party data scarcity:Deprecation of third-party cookies by Chrome and Safari is constraining audience addressability and forcing expensive identity graph construction.
- Compliance cost escalation:Simultaneous GDPR, CCPA, and EU AI Act obligations are inflating legal and engineering overhead for cross-border campaign management.
- Technical debt in legacy stacks:On-premise email and web content management systems resist API-native integration with modern customer data platforms.
Strategic Opportunities
- Synthetic media generation:Text-to-image and text-to-video engines are collapsing production costs for personalized creative variants at scale.
- India's digital acceleration:PLI scheme subsidies for data center infrastructure are lowering cloud egress costs for regional martech deployment.
- Retail media networks:Closed-loop attribution from on-site search and display inventory is capturing brand budgets previously allocated to open-web programmatic.
Industry Challenges
- Prompt engineering talent scarcity:Marketing organizations lack personnel capable of optimizing generative model outputs for brand-consistent creative production.
- Cross-platform identity resolution:Fragmented device graphs and consent frameworks complicate unified customer profile construction across walled gardens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Marketing Software Market |
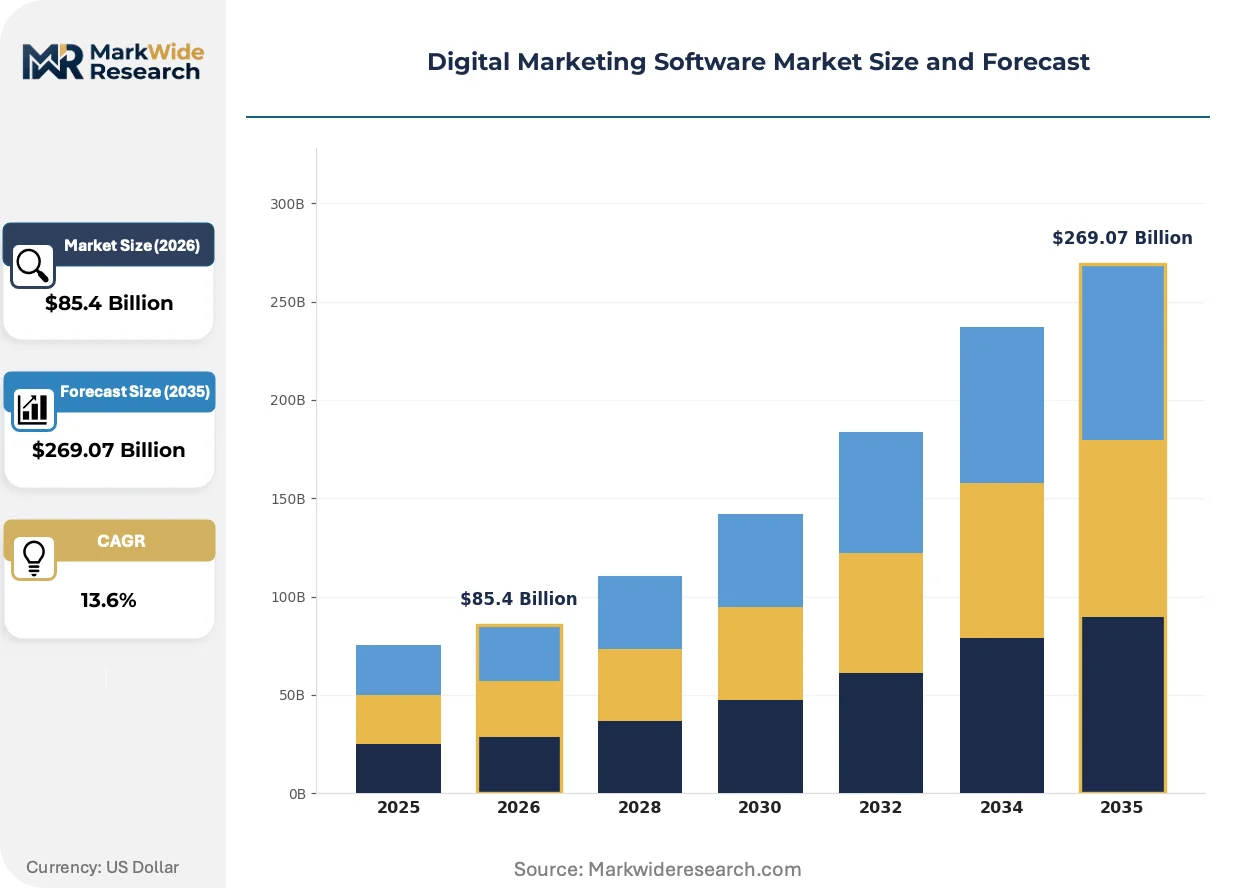
| Market Size in 2026 | $85.4 Billion |
| Market Size in 2035 | $269.07 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Open-Source Solution Type: Content Management, Email Marketing, Social Media Management, Search Engine Optimization, Marketing Automation Application: Lead Generation, Customer Engagement, Brand Awareness, Conversion Rate Optimization, Market Analytics End User: Small Enterprises, Medium Enterprises, Large Corporations, Digital Agencies, Freelancers |
| Companies Covered | Basis, ZoomInfo, HubSpot, Adswerve, WebFX, Hootsuite, Duda, GumGum, ActiveCampaign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Marketing Software Market Strategic Shifts & Innovations
Automation layers are absorbing tasks previously requiring creative and analytics specialists, compressing team structures while elevating the strategic importance of data architecture and model governance.
Multimodal generative engines that synthesize copy, imagery, and video from unified prompts are hybridizing previously siloed creative production workflows. Mid-market B2B software vendors are adopting these tools fastest, collapsing agency retainer relationships and internal creative team headcounts. The structural result is hybridizing cost structures away from labor-heavy campaign builds toward compute-intensive generation and curation layers.
The EU AI Act's risk classification system for automated decision-making is forcing transparency documentation into product roadmaps. Vendors must now embed explainability interfaces that surface model logic to end-users and auditors. European financial services and healthcare advertisers face the steepest compliance curves, with procurement teams demanding algorithmic impact assessments as standard contract terms.
Self-service buying portals are displacing traditional sales-led martech procurement for sub-fifty-thousand-dollar annual contract values. Marketing operations leaders now evaluate and deploy point solutions without IT procurement involvement, compressing vendor sales cycles from quarters to weeks. This pattern is most pronounced in US and UK technology and professional services verticals where decentralized budget authority prevails.
Digital Marketing Software Market Segmentation
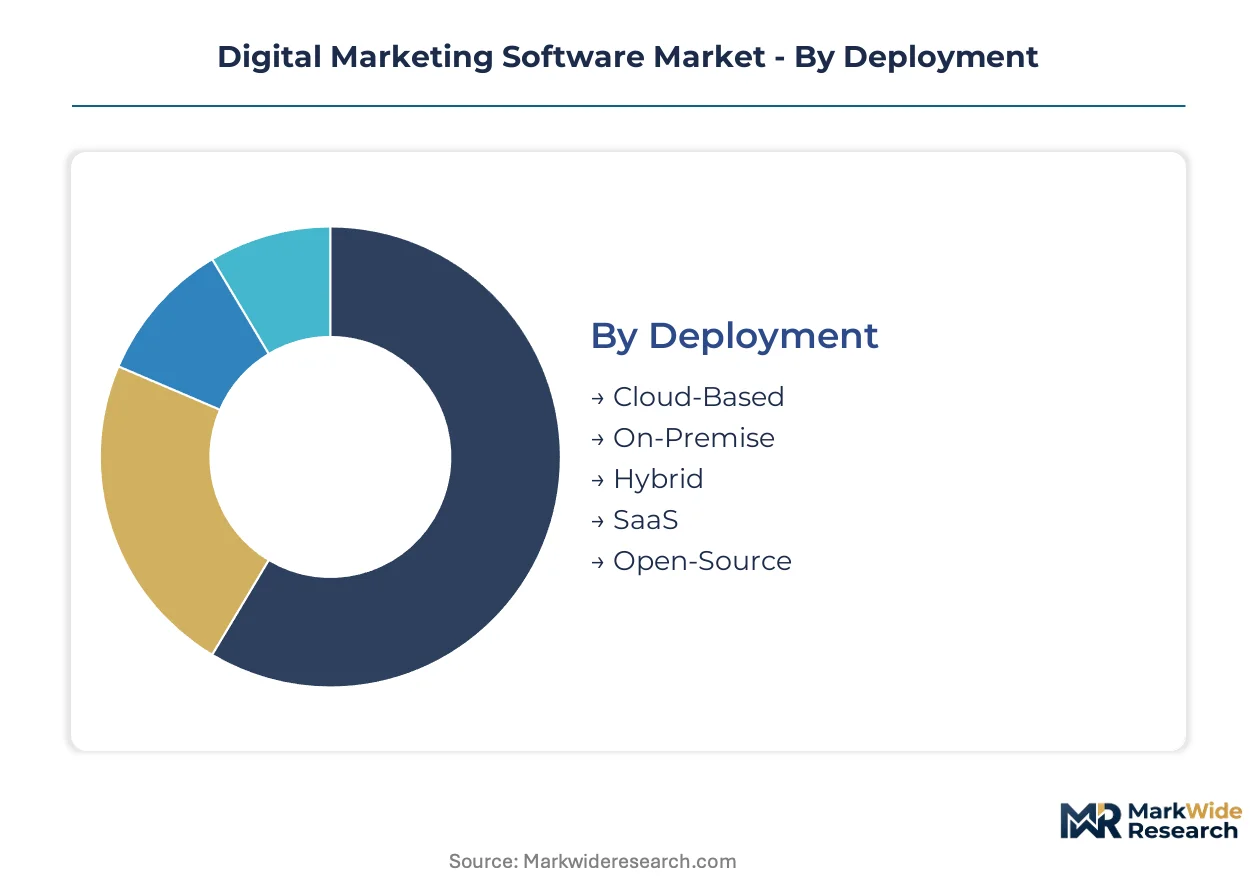
Segmentation in digital marketing software reveals how vendor architectures align with distinct operational constraints and budget tiers. Deployment models separate privacy-sensitive financial institutions from agile retail operators, while solution types map to specific workflow automation needs across the customer lifecycle.
Deployment:
Mature SaaS platforms dominate volume, though hybrid architectures are gaining traction among regulated sectors balancing agility with data sovereignty requirements.
- Cloud-Based:Multi-tenant architectures deliver elastic compute for campaign orchestration during seasonal demand spikes. Retail brands in the United States concentrate procurement here, driven by real-time personalization engine requirements and API-native integration with customer data platforms.
- Hybrid:Split-stack configurations keep sensitive identity graphs on-premise while pushing creative generation workloads to public cloud. German financial services advertisers and French healthcare marketers are accelerating adoption due to GDPR Article 32 security mandates and national data residency statutes.
- On-Premise:Air-gapped installations persist in defense-adjacent sectors and certain Swiss banking consortiums with legacy compliance frameworks.
- SaaS:Subscription-native delivery captures mid-market marketing automation with pre-built connector libraries to Salesforce and HubSpot ecosystems.
- Open-Source:Mautic and comparable platforms serve cost-constrained digital agencies in India and Eastern Europe with self-hosted email orchestration.
Cloud-Based handles the majority of throughput; Hybrid is expanding most quickly among regulated European advertisers.
Solution Type:
Margin concentration follows workflow stickiness, with automation layers commanding premium pricing against commoditized repository functions.
- Marketing Automation:Trigger-based journey builders and lead scoring algorithms embed deeply into CRM workflows, creating switching costs that sustain recurring revenue. Enterprise technology vendors in the United States deploy these most aggressively, integrating predictive models that compress sales cycles.
- Social Media Management:Unified publishing, listening, and influencer identification tools are climbing fastest as TikTok and Instagram commerce integrations become standard procurement requirements. UK and US direct-to-consumer brands are the primary demand source, reallocating television production budgets toward platform-native content pipelines.
- Content Management:Headless architectures with AI-assisted asset generation are displacing traditional web CMS in publisher and media verticals.
- Email Marketing:Deliverability optimization and first-party data activation remain core to B2B nurture programs despite channel maturity.
- Search Engine Optimization:Rank tracking and technical audit suites face margin pressure from free Google Search Console capabilities and AI-generated content detection challenges.
Marketing Automation commands the deepest margin pools; Social Media Management is gaining share fastest from influencer economy expansion.
Application:
Use-case segmentation tracks budget authority migration from brand marketing to revenue operations functions.
- Conversion Rate Optimization:A/B testing and personalization engines quantify experiment ROI, attracting procurement from growth teams with direct revenue accountability. E-commerce operators in the United States and United Kingdom prioritize these tools as third-party cookie deprecation forces on-site behavioral targeting.
- Lead Generation:Intent data platforms and form optimization tools concentrate demand in B2B technology and professional services verticals. German and French industrial manufacturers are expanding procurement here as account-based marketing programs require precise contact intelligence.
- Customer Engagement:Loyalty program orchestration and lifecycle messaging retain existing customer bases for subscription software and direct-to-consumer brands.
- Brand Awareness:Reach and frequency optimization across connected TV and digital audio attracts CPG advertisers with traditional media backgrounds.
- Market Analytics:Attribution modeling and competitive intelligence serve strategy functions with longer evaluation cycles and centralized procurement authority.
Conversion Rate Optimization absorbs the largest technology budgets; Lead Generation shows the steepest expansion trajectory as B2B digital transformation accelerates.
End User:
Organizational scale determines implementation complexity and sales motion design across vendor go-to-market strategies.
- Large Corporations:Custom implementation services and dedicated customer success resources support multi-brand martech stacks with hundreds of seats. US-based Fortune 500 retailers and financial institutions command the deepest integration investments, often maintaining dedicated marketing operations centers.
- Digital Agencies:Multi-tenant management consoles and white-label reporting serve campaign execution for brand portfolios. UK and US agencies are consolidating point solutions into unified platforms to reduce client onboarding friction.
- Medium Enterprises:Pre-configured workflow templates and self-service onboarding balance capability with limited marketing operations headcount.
- Small Enterprises:Freemium tiers and simplified UIs from Mailchimp and HubSpot dominate, though churn rates exceed enterprise segments significantly.
- Freelancers:Individual creator tools with AI-assisted content generation are emerging as a discrete micro-segment serving influencer economy participants.
Large Corporations represent the highest absolute spending; Digital Agencies are climbing fastest as managed service models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based martech vendors export orchestration platforms to European retail advertisers navigating GDPR and EU AI Act compliance obligations. Trade flows concentrate through London and Frankfurt as regional deployment hubs.
United States
Enterprise technology and financial services advertisers drive martech stack investments with deep CRM integration requirements. FCC truth-in-advertising standards shape automated decisioning transparency for cross-border campaigns. Marketing operations centers concentrate in New York and San Francisco, where vendor headquarters proximity accelerates pilot-to-production timelines.
Germany
Industrial manufacturers and automotive brands expand procurement of intent data platforms for account-based marketing programs. GDPR Article 32 security mandates accelerate hybrid deployment adoption among Frankfurt and Munich financial services advertisers. Bavarian software clusters develop privacy-preserving personalization engines for EU-regulated sectors.
United Kingdom
Direct-to-consumer brands and digital agencies reallocate television budgets toward TikTok and Instagram commerce integrations. UK-specific data protection regulations post-Brexit create parallel compliance frameworks for vendors serving British and EU clients simultaneously. London's advertising technology corridor hosts managed service providers consolidating point solutions into unified platforms.
India
PLI scheme subsidies for data center infrastructure reduce cloud egress costs for regional martech deployment among mid-market enterprises. TRAI regulations on data localization influence vendor architecture decisions for financial services advertisers. Bangalore and Hyderabad software clusters produce self-hosted email orchestration tools for cost-constrained digital agencies.
Japan
Enterprise B2B software vendors deploy predictive lead scoring algorithms to compress sales cycles in manufacturing and technology verticals. METI guidelines on AI governance shape transparency requirements for automated personalization engines. Tokyo and Osaka marketing operations centers prioritize consent granularity in customer data platform implementations.
Digital Marketing Software Market Key Industry Players
On the supply side, the industry is consolidating around three distinct tiers: integrated suite vendors, specialized point-solution providers, and open-source alternatives. The top tier commands premium pricing through workflow stickiness and API-native architectures. Strategic archetypes include CRM-adjacent platform builders, data intelligence specialists, and social-native workflow automators. Dominant competitive moves encompass M&A activity targeting identity graph capabilities and strategic partnerships with cloud infrastructure providers.
Within the CRM-adjacent platform tier, HubSpot represents mid-market inbound methodology adoption, while ActiveCampaign exemplifies automation-first positioning for smaller enterprises. ZoomInfo anchors the data intelligence archetype through proprietary B2B contact intelligence. These three companies occupy positions across distinct budget authority segments, with HubSpot and ActiveCampaign serving marketing operations leaders directly and ZoomInfo targeting revenue operations functions with longer procurement cycles.
| Leading Market Players |
|---|
| Basis |
| ZoomInfo |
| HubSpot |
| Adswerve |
| WebFX |
| Hootsuite |
| Duda |
| GumGum |
| ActiveCampaign |
| Others |
Cost & Logistics Intelligence
Elastic compute overcapacity in North American cloud regions is compressing infrastructure-as-a-service margins and forcing SaaS vendors toward consumption-based pricing models that align customer spend with actual workload utilization.
Pricing Analysis
Legacy on-premise licensing versus cloud-native subscription versus AI-augmented premium tiers defines the current pricing architecture across vendor portfolios. Three-tier pricing structure across enterprise, professional, and starter levels segments buyer archetypes by integration complexity and seat count. Price differentiation rests on API call volume entitlements and model inference quotas rather than core feature gates. Pricing pressure stems from open-source alternatives gaining traction among cost-constrained digital agencies in India and Eastern Europe. Small enterprises exhibit highest price sensitivity, while Fortune 500 retailers with dedicated marketing operations centers absorb premium pricing for compliant hybrid deployments.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for hardware-dependent edge computing components used in on-premise martech installations. Software supply concentrates in the United States, Ireland, and India, with development clusters anchored in San Francisco, Dublin, and Bangalore. Raw material dependencies center on GPU accelerators from NVIDIA and AMD, high-bandwidth memory from SK Hynix and Samsung, and specialized networking silicon from Broadcom. Single-source vulnerability in CUDA-optimized inference chips creates procurement bottlenecks for generative AI feature rollouts. Distribution runs through hyperscaler marketplaces—AWS Marketplace, Azure Marketplace, Google Cloud Marketplace—rather than traditional value-added reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital marketing software market is recovering from post-pandemic budget retrenchment as CPG advertisers redirect television spend into programmatic channels, restoring procurement velocity across enterprise martech stacks.
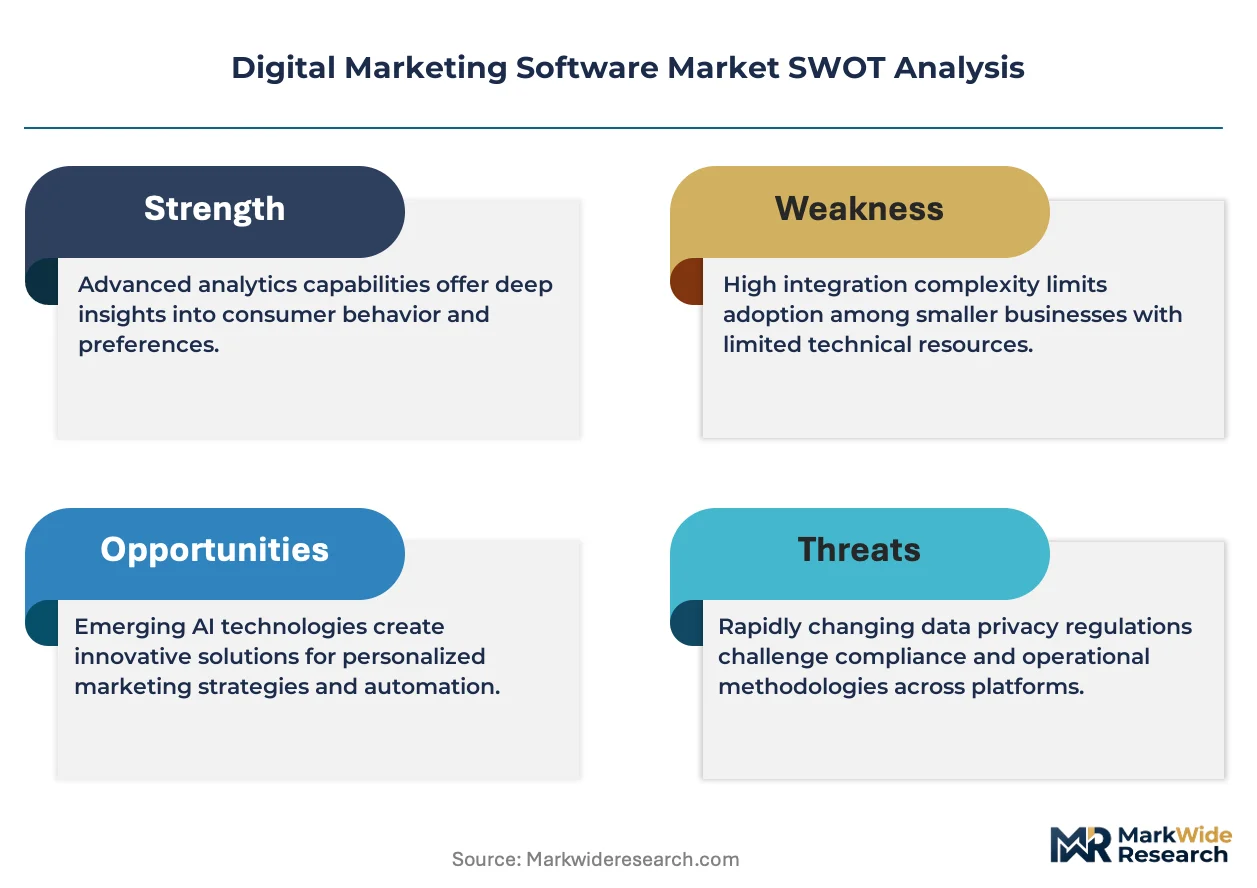
For Market Incumbents: Entrench workflow stickiness by embedding generative AI orchestration layers deeper into CRM-adjacent customer journeys, raising switching costs for HubSpot and Salesforce ecosystem users. Acquire identity graph capabilities to offset third-party cookie deprecation threats from Chrome and Safari privacy changes. Expand hybrid deployment engineering capacity in Frankfurt and Munich to capture GDPR Article 32 compliance budgets from German financial services advertisers. For New Entrants and Emerging Players: Build out synthetic media generation tools targeting mid-market B2B software vendors in the United Kingdom and United States, where agency retainer relationships are collapsing fastest. India's PLI-subsidized data center infrastructure offers the most penetrable geography for cost-competitive cloud egress pricing. Pursue self-service buying portal distribution to bypass traditional enterprise sales cycles and compress vendor evaluation timelines from quarters to weeks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among marketing automation vendors with pre-built Salesforce and HubSpot connector libraries and workflow template marketplaces. Long-term viability favors platforms with proprietary data moats—B2B contact intelligence, intent signal aggregation, or retail media network closed-loop attribution—rather than commoditized publishing tools. Monitor EU AI Act enforcement patterns as an inflection indicator; steep compliance curves in European financial services and healthcare verticals will consolidate procurement around explainability-ready vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Integration | Embedding prompt-to-deployment pipelines collapses creative production timelines and displaces static template libraries. |
| Hybrid Deployment Expansion | Split-stack configurations capture GDPR-mandated data residency budgets from German and French regulated advertisers. |
| Identity Graph Acquisition | Proprietary first-party data assets offset third-party cookie deprecation from Chrome and Safari privacy changes. |
| Self-Service Portal Launch | Sub-fifty-thousand-dollar ACV procurement bypasses IT involvement and compresses sales cycles to weeks. |
| Retail Media Network Partnership | Closed-loop attribution from on-site search inventory captures brand budgets from open-web programmatic channels. |
Research Approach
Initial hypotheses were tested against primary input from chief marketing officers, marketing operations directors, martech procurement leads, and CRM integration specialists and refined through secondary validation against SEC filings, hyperscaler capex disclosures, App Annie platform usage data, and EU regulatory filings. Bottom-up sizing from vendor revenue disclosures and top-down triangulation from advertising spend macro indicators were reconciled to produce segment-level estimates.
Demand-supply balance modeling across the projection horizon incorporated deployment model adoption curves, organization size penetration rates, vertical-specific compliance requirements, and regional cloud infrastructure maturity. Segmentation dimensions included solution type, application use case, end-user scale, and geographic regulatory cluster. CAGRs were derived from fitted growth curves anchored to observed procurement patterns and vendor booking disclosures, with generative AI feature attach rates and first-party data infrastructure buildout timelines as key demand-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by well-capitalized cloud hyperscalers or rapid open-source platform maturation would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
New Zealand ICT Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Digital Onboarding Software Market
Digital Solutions
Business Document Work Process Management Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
Data Monetization Market
Digital Solutions
Revops Platform Market
Digital Solutions
South Korea Digital Twin Market