
 Global Mesh App and Service Architecture Market | 2026-2036
Global Mesh App and Service Architecture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mesh App and Service Architecture Market Foresight
North American cloud infrastructure providers is consolidating around Kubernetes-native service mesh platforms. Microsoft Corporation leverages its Azure Service Mesh integration to anchor enterprise hybrid deployments. Google LLC sustains technology leadership through Istio's open-source governance and Anthos commercialization. HashiCorp competes with its Consul platform by emphasizing multi-datacenter federation for financial services workloads.
Mesh App and Service Architecture denotes a distributed systems design pattern where inter-service communication, security, and observability are abstracted into a dedicated infrastructure layer rather than embedded within application code. This architecture employs sidecar proxy containers—typically Envoy-based—that intercept all network traffic using Layer 7 protocols to enforce mutual TLS encryption, circuit breaking, and granular telemetry collection. The primary commercial purpose is decoupling operational concerns from business logic, enabling development teams to deploy polyglot microservices without rebuilding networking stacks per language runtime. Cloud-native deployment configurations command the largest addressable base as organizations retire monolithic applications, though edge deployment segments are expanding fastest where 5G network slicing requires localized service discovery with sub-50ms latency constraints. Security mesh solutions capture disproportionate margin pools because regulatory mandates for zero-trust architectures force premium pricing on FIPS 140-2 validated implementations.
FCC guidelines on telecommunications infrastructure resilience intersect with NIST cybersecurity frameworks to mandate encrypted service-to-service communication for critical infrastructure operators. EMA data integrity requirements and FDA 21 CFR Part 11 provisions compel pharmaceutical and financial enterprises to deploy tamper-evident observability pipelines with immutable audit logs. Enterprises must evaluate whether their current API gateway investments can evolve into full mesh architectures or require wholesale replacement as traffic encryption becomes default rather than optional.
Market Dynamics
Zero-trust security mandates from financial regulators are forcing infrastructure teams to migrate from perimeter-based network security to identity-verified service-to-service communication architectures.
Growth Catalysts
- EU AI Act compliance requirements:European enterprises deploy observability pipelines with immutable audit trails to satisfy algorithmic accountability mandates. German automotive manufacturers lead adoption.
- 5G network slicing deployments:Telecommunications operators in South Korea and Japan require sub-50ms latency service discovery at the edge, driving localized mesh control plane installations.
- Microservices decomposition of ERP systems:Industrial manufacturers fragment monolithic applications into polyglot services, creating demand for language-agnostic traffic management infrastructure.
Market Restraints
- Envoy proxy computational overhead:Sidecar resource consumption increases cloud compute costs by 15-30% versus traditional API gateway architectures.
- Certified engineer scarcity:Kubernetes-native networking expertise concentrates in Silicon Valley and Bangalore, limiting enterprise deployment velocity elsewhere.
- FIPS 140-2 validation timelines:Cryptographic module certification delays federal and financial sector deployments by 12-18 months.
Strategic Opportunities
- India's PLI scheme for cloud infrastructure:Domestic data center expansion creates demand for sovereign-controlled service mesh deployments with in-country key management.
- eBPF-based sidecar-less architectures:Kernel-level traffic interception converges with Cilium's dataplane to reduce latency and resource overhead versus proxy-based models.
- FDA 21 CFR Part 11 pharmaceutical pipelines:Tamper-evident observability requirements in drug manufacturing create premium-priced validated mesh implementations.
Industry Challenges
- Legacy mainframe integration complexity:Financial institutions struggle to bridge COBOL-based core banking systems with cloud-native microservices without transaction integrity loss.
- Multi-cluster federation operational burden:Platform teams lack runbook maturity for diagnosing failures across geographically distributed control planes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mesh App and Service Architecture Market |
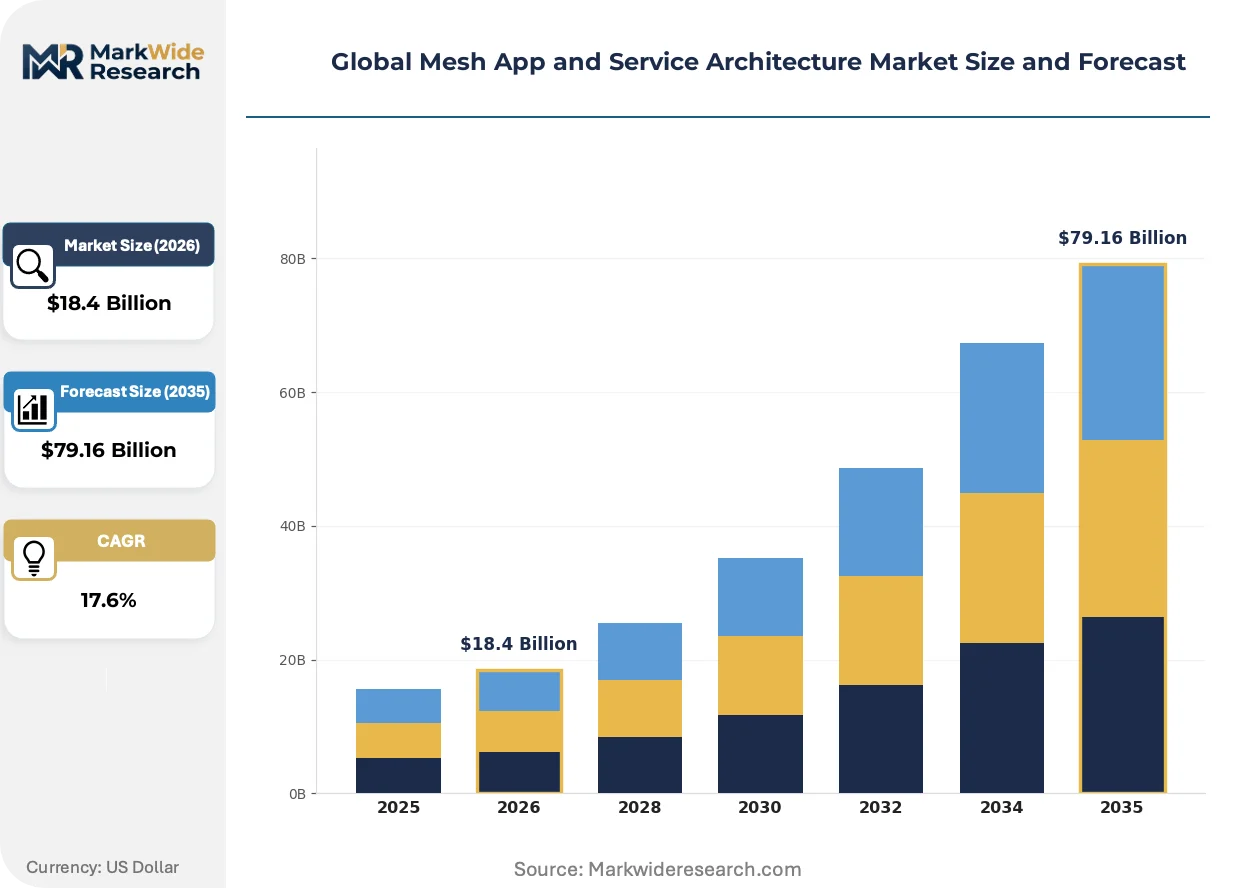
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $79.16 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Native, On-Premises, Hybrid, Multi-Cloud, Edge Solution Type: Service Mesh, API Gateway, Microservices Proxy, Observability Tools, Security Mesh Use Case: Application Modernization, Traffic Management, Load Balancing, Secure Communication, Service Discovery End User: Financial Institutions, Telecommunications Providers, IT & Software Companies, Government Agencies, E-Commerce Platforms |
| Companies Covered | Microsoft Corporation, Google LLC, IBM Corporation, Apple Inc, Amazon, Docker, Inc, Cisco, Axway Software, HashiCorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mesh App and Service Architecture Market Shifts & Advancements
Service mesh architectures are bifurcating between Kubernetes-native control planes and ambient mesh models that eliminate sidecar proxies entirely. This divergence reflects competing pressures for operational simplicity versus maximum configurability.
Ambient mesh architectures using zonal tunnels and waypoint proxies is overtaking traditional sidecar deployments in latency-sensitive environments. Telecommunications operators adopting 5G standalone cores favor this model for reduced per-pod resource overhead. The shift is compressing margins for Envoy-centric platform vendors while rewarding kernel-level networking specialists.
The EU AI Act's algorithmic transparency requirements are mandating explainable traffic routing decisions in automated systems. Financial services firms must now document why specific service instances receive request traffic. German insurers and Dutch pension funds are deploying annotated service graphs to satisfy supervisory review.
Platform engineering teams are consolidating procurement around internal developer platforms with embedded mesh capabilities. Traditional best-of-breed service mesh vendors face displacement by infrastructure-as-a-product offerings from hyperscale cloud providers. This consolidation is most visible in North American enterprises with mature Kubernetes operations.
Global Mesh App and Service Architecture Market Segmentation
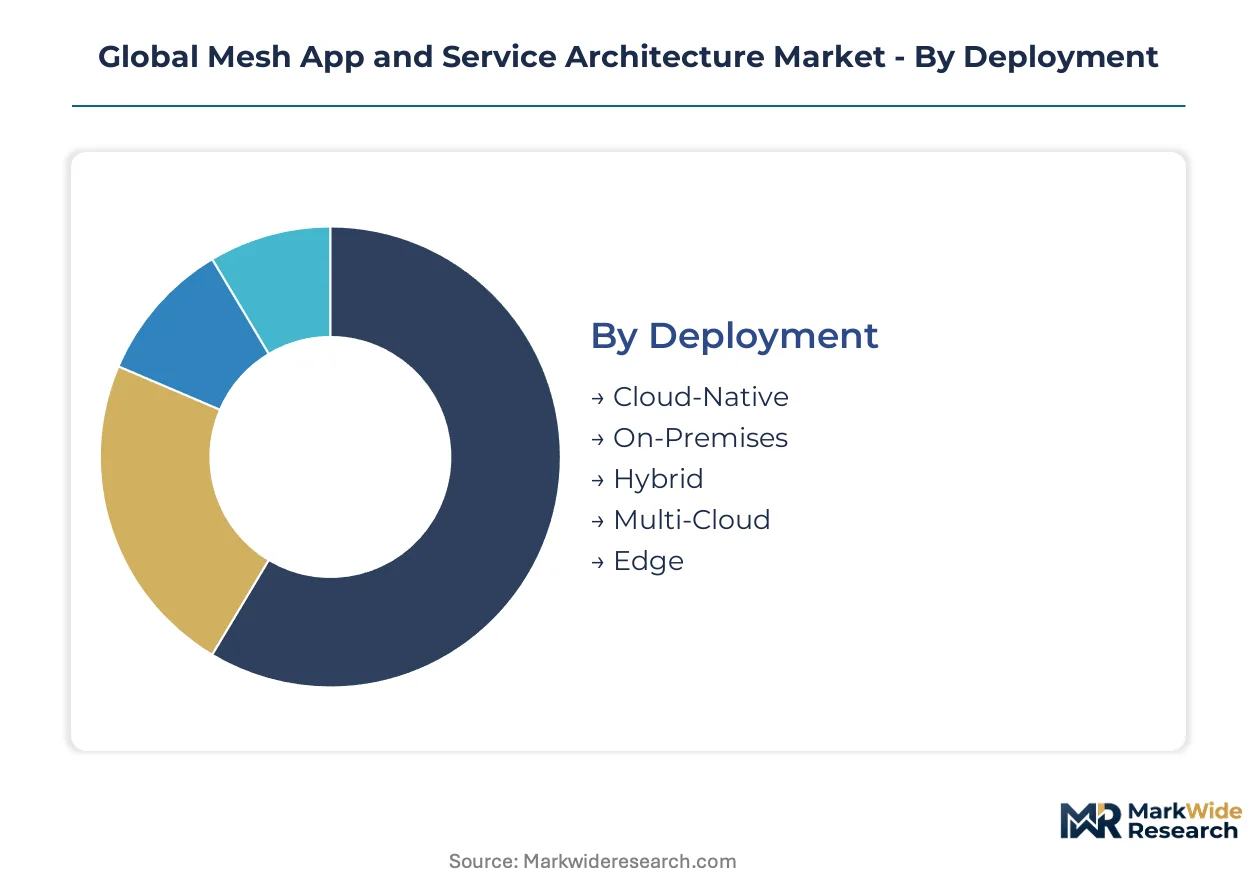
Segmentation in mesh architectures reveals how regulatory certification burdens concentrate in specific deployment modes and end-use verticals. Financial institutions and pharmaceutical manufacturers face distinct compliance pathways that reshape procurement priorities across solution categories.
Deployment:
FIPS 140-2 validation requirements fall heaviest on cloud-native and edge deployments handling federal data, while hybrid configurations navigate dual compliance regimes across on-premises and cloud boundaries.
- Cloud-Native:Kubernetes-orchested control planes with automated sidecar injection dominate enterprise microservices migrations. Demand concentrates among North American SaaS providers modernizing monolithic applications under NIST cybersecurity framework mandates.
- Edge:Localized control planes with sub-50ms latency service discovery support 5G standalone core deployments. South Korean and Japanese telecommunications operators drive procurement for network slicing workloads requiring in-country data residency.
- On-Premises:Air-gapped installations with sovereign key management satisfy India's data localization requirements under RBI guidelines.
- Hybrid:Federated control planes bridge legacy mainframe systems with cloud workloads, attracting German automotive manufacturers modernizing ERP infrastructure.
- Multi-Cloud:Cross-provider traffic encryption addresses vendor lock-in concerns for European enterprises under GDPR data transfer restrictions.
Cloud-Native sits at the top of the volume ranking, with Edge climbing the fastest.
Solution Type:
Margin structures diverge sharply between commodity traffic management tools and validated security implementations carrying regulatory premium pricing.
- Security Mesh:FIPS 140-2 validated mutual TLS enforcement with tamper-evident audit logging commands premium pricing. FDA 21 CFR Part 11 compliance requirements in pharmaceutical manufacturing sustain elevated margins.
- Observability Tools:Immutable telemetry pipelines with algorithmic transparency annotations satisfy EU AI Act mandates. German insurers and Dutch pension funds deploy annotated service graphs for supervisory review.
- Service Mesh:Full-stack control planes with sidecar proxy orchestration remain the reference architecture for Kubernetes-native enterprises.
- API Gateway:Legacy perimeter-based traffic management faces displacement as mesh architectures internalize encryption functions.
- Microservices Proxy:Language-agnostic Envoy-based sidecars enable polyglot service decomposition in industrial manufacturing environments.
Security Mesh captures the highest margin pool, with Observability Tools expanding most quickly.
Use Case:
Application modernization projects generate foundational demand, while secure communication workloads attract compliance-driven premium pricing.
- Application Modernization:Monolithic decomposition into microservices creates greenfield mesh deployments. German industrial manufacturers fragment legacy ERP systems into polyglot services.
- Secure Communication:Zero-trust service-to-service encryption replaces perimeter-based network security. FCC guidelines mandate encrypted communication for critical infrastructure operators.
- Traffic Management:Intelligent request routing with circuit breaking and retry logic supports high-availability financial services.
- Service Discovery:Automated endpoint registration enables dynamic scaling in containerized environments.
- Load Balancing:Layer 7 traffic distribution optimizes resource utilization across distributed service instances.
Application Modernization leads current deployment volumes, with Secure Communication gaining share fastest.
End User:
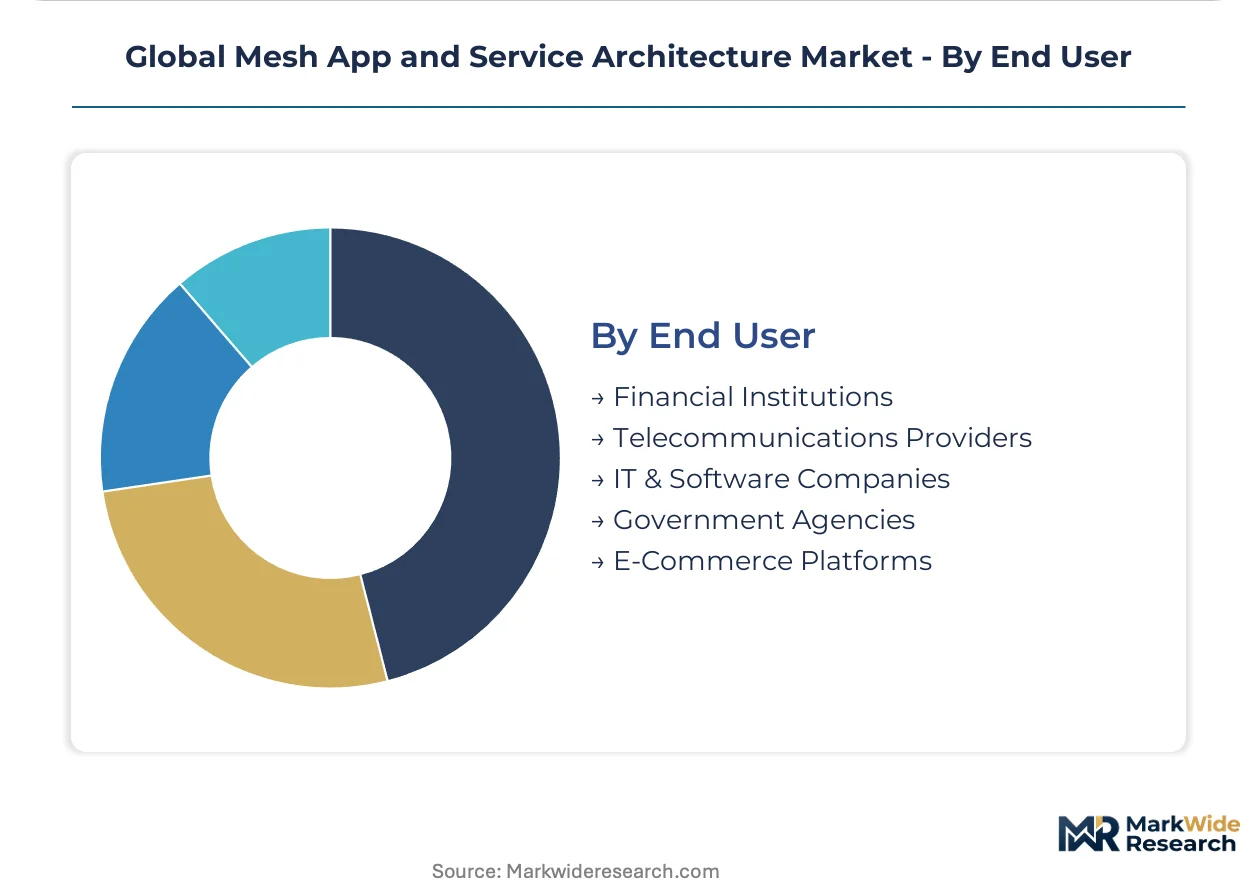
Procurement authority concentrates in regulated verticals where audit-ready observability justifies premium infrastructure investment.
- Financial Institutions:Zero-trust mandates from banking regulators drive identity-verified service-to-service architectures. EMA data integrity requirements and FDA 21 CFR Part 11 provisions compel tamper-evident pipelines.
- Government Agencies:FIPS 140-2 cryptographic module certification delays deployment timelines by 12-18 months but locks in long-term vendor relationships.
- Telecommunications Providers:5G network slicing requirements in South Korea and Japan drive edge-localized mesh installations.
- IT & Software Companies:Internal developer platforms with embedded mesh capabilities displace best-of-breed vendor procurement.
- E-Commerce Platforms:High-velocity deployment cycles favor managed mesh services from hyperscale cloud providers.
Financial Institutions anchor current revenue concentration, with Government Agencies climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping deployment patterns as enterprises migrate mesh infrastructure to jurisdictions with streamlined cryptographic certification pathways. The cost-of-compliance gap between FIPS 140-2 validation regimes and lighter-touch alternatives is concentrating edge installations in specific national markets.
United States
FCC resilience guidelines and NIST cybersecurity frameworks mandate encrypted service-to-service communication for critical infrastructure operators. Federal procurement requirements lock vendors into 12-18 month FIPS validation cycles. Silicon Valley platform engineering teams and Seattle cloud infrastructure hubs anchor Kubernetes-native control plane development.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria decompose legacy ERP systems into polyglot microservices, creating demand for hybrid mesh federation. EU AI Act algorithmic transparency requirements compel annotated service graphs for supervisory review. Frankfurt financial services clusters deploy tamper-evident observability pipelines under BaFin scrutiny.
India
RBI data localization guidelines and the PLI scheme for cloud infrastructure drive sovereign-controlled service mesh deployments with in-country key management. Bangalore and Hyderabad concentrate Kubernetes-native networking expertise, accelerating enterprise deployment velocity. Domestic data center expansion in Maharashtra and Telangana supports air-gapped installations for public sector workloads.
South Korea
5G standalone core deployments require sub-50ms latency service discovery at the edge, driving localized mesh control plane installations. METI-aligned telecommunications operators in Seoul and Busan procure network slicing infrastructure with in-country data residency. Government cloud mandates favor domestic vendors for critical communication workloads.
Japan
Telecommunications operators in Tokyo and Osaka adopt ambient mesh architectures for reduced per-pod resource overhead in latency-sensitive environments. METI industrial digitization programs subsidize microservices modernization for automotive and electronics manufacturers. Fukuoka and Nagoya industrial clusters integrate edge-localized service discovery with factory automation systems.
Global Mesh App and Service Architecture Market Competitive Landscape
United States hyperscalers anchor one tier; European and Indian specialists hold differentiated positions in sovereign-cloud and edge-optimized segments. The vendor structure concentrates around three strategic archetypes: Kubernetes-native platform integrators, open-source governance stewards, and multi-datacenter federation specialists. Consolidation pressure intensifies as internal developer platforms displace best-of-breed procurement. M&A activity targets eBPF-based sidecar-less technology assets; strategic partnerships bridge legacy mainframe integration gaps.
Within the hyperscaler tier, Microsoft Corporation and Google LLC exemplify competing control plane philosophies—Azure Service Mesh integration versus Istio's open-source governance commercialized through Anthos. HashiCorp occupies a distinct position emphasizing multi-datacenter federation for regulated workloads. These three anchors represent divergent bets on architectural evolution: sidecar retention, ambient transition, and infrastructure-as-code automation respectively.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Apple Inc |
| Amazon |
| Docker, Inc |
| Cisco |
| Axway Software |
| HashiCorp |
| Others |
Supply & Pricing Matrix
Kubernetes-native networking expertise concentrated in Silicon Valley and Bangalore creates labor-cost differentials that widen pricing-tier spreads between premium FIPS-validated implementations and standard cloud-native deployments.
Pricing Analysis
Distributor margins for validated security mesh solutions compress as hyperscale cloud providers integrate mesh capabilities into bundled infrastructure-as-a-product offerings. Three-tier pricing structure across premium FIPS 140-2 validated, standard enterprise-grade, and economy managed-service tiers reflects certification investment differentials. Pricing pressure stems from eBPF-based sidecar-less architectures reducing resource overhead versus traditional Envoy proxy models. Government agencies and federal contractors demonstrate lowest price sensitivity due to mandated compliance requirements, while mid-market SaaS providers exhibit highest sensitivity to per-pod compute costs.
Supply Chain Analysis
Dual-sourcing requirements for cryptographic modules mandate multi-supplier qualification across FIPS 140-2 validation labs in the United States and commercial certification bodies in Europe. Control plane development concentrates in the United States, India, and Israel, while sidecar proxy manufacturing draws from Taiwan and South Korea for high-performance silicon. Supply chain risk centers on single-source vulnerability for FIPS-validated hardware security modules. Distribution runs through hyperscale cloud marketplaces, systems integrators with federal contracting authority, and direct enterprise sales for air-gapped sovereign deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme for cloud infrastructure offers 15-20% cost advantages versus US-based FIPS validation timelines for equivalent security implementations.
For Market Incumbents: Anchor defensive positioning through accelerated FIPS 140-2 pre-validation investments that lock out competitors from federal procurement cycles. Consolidate around eBPF-based sidecar-less technology acquisitions to neutralize latency advantages held by kernel-level networking specialists. Threat substitution from internal developer platforms with embedded mesh capabilities demands channel control reinforcement through hyperscaler marketplace exclusivity arrangements. For New Entrants and Emerging Players: Cloud-native developer tool marketplaces offer lowest-friction customer acquisition routes for ambient mesh architectures targeting telecommunications operators. White-space concentrates in India's sovereign-controlled service mesh segment where RBI data localization requirements exclude incumbent hyperscalers. Target German automotive manufacturers modernizing ERP systems through polyglot microservices decomposition. Go-to-market leverage rests on Kubernetes-native networking expertise concentrated in Bangalore and Hyderabad delivery centers. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, targeting eBPF-based dataplane technology to compress sidecar resource overhead. Long-term viability favors vendors with dual-track certification strategies spanning FIPS 140-2 and EU AI Act compliance pathways. Acquisition target archetype: kernel-level networking specialists with telecommunications operator reference deployments. Signal to watch: METI subsidy disbursement velocity for Japanese industrial digitization programs as edge-localized mesh demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding mesh capabilities into internal developer platforms displaces best-of-breed vendor procurement at North American enterprises. |
| Acquisition of Specialist Firm | eBPF-based sidecar-less technology targets compress latency advantages held by traditional Envoy-centric platform vendors. |
| Strategic Partnership | Alliances with legacy mainframe integration specialists bridge COBOL-based core banking systems with cloud-native microservices. |
| Geographic Expansion | Domestic data center buildout in Maharashtra and Telangana supports sovereign-controlled deployments under RBI guidelines. |
| Product Launch | FIPS 140-2 pre-validated control planes lock in long-term federal procurement relationships before competitor certification completion. |
Research Methodology
Direct dialogue with platform engineering directors, Kubernetes site reliability engineers, federal procurement officers, telecommunications network architects, and pharmaceutical IT compliance leads grounded demand-side intelligence. Secondary validation drew from SEC filings of publicly traded cloud infrastructure providers, NIST cybersecurity framework documentation, EMA data integrity guidance, FDA 21 CFR Part 11 provisions, and hyperscaler capex disclosure reports. Bottom-up deployment estimates across cloud-native, edge, hybrid, and multi-cloud configurations triangulated with top-down market sizing from infrastructure software spending analyses.
Bottom-up modeling of control plane installations across deployment modes and solution types converged with top-down software infrastructure spending allocation estimates over the projection horizon. Segmentation dimensions spanned deployment architecture, solution category, use case application, and end-user vertical with regional adoption pattern differentiation. CAGRs derived from installation base expansion rates, average revenue per deployment trends, and validated pricing tier trajectories. Forecast inputs incorporated 5G standalone core deployment schedules, EU AI Act implementation timelines, and FIPS 140-2 validation pipeline throughput.
The model assumes a particular technology adoption path; alternative pathways for ambient mesh architectures would alter the outlook if telecommunications operators accelerate zonal tunnel deployments beyond current METI-aligned schedules. Deviation in FIPS 140-2 validation lab capacity or EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
Revops Platform Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Digital Onboarding Software Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Webrtc Market
Digital Solutions
Global Website Builders Market
Digital Solutions
Ediscovery Market