
 Europe Data Virtualization Market | 2026-2036
Europe Data Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Virtualization Market Insights
Enterprise software distribution is rewriting how data virtualization platforms reach European buyers. Oracle Corporation leverages its established database footprint to anchor large financial services contracts across Frankfurt and London. IBM Corporation competes through hybrid cloud specialization, sustaining R&D intensity in mainframe-connected virtualization layers. QlikTech International AB differentiates via embedded analytics integration, occupying the mid-market segment with partner-channel density.
Data virtualization creates an abstraction layer that federates disparate sources—SQL databases, cloud warehouses, streaming pipelines—into queryable logical views without physical consolidation. The architecture employs metadata-driven query optimization and on-the-fly transformation to deliver sub-second response across distributed environments. Cloud deployment now leads solution uptake as European enterprises exit rigid on-premises data center commitments. Banking and telecommunications end users represent the fastest-expanding vertical pair, driven by real-time risk calculation and subscriber 360 initiatives. API management solutions concentrate margin pools, since governance and security modules command premium pricing against commodity integration tooling.
GDPR enforcement by national data protection authorities and the EU AI Act's risk-classification framework shape product roadmaps, mandating lineage tracking and automated policy enforcement within virtualization stacks. EMA guidelines on clinical data traceability extend these requirements into healthcare deployments. Procurement and architecture teams must evaluate vendor compliance attestations before committing to multi-year federation platforms.
Market Dynamics
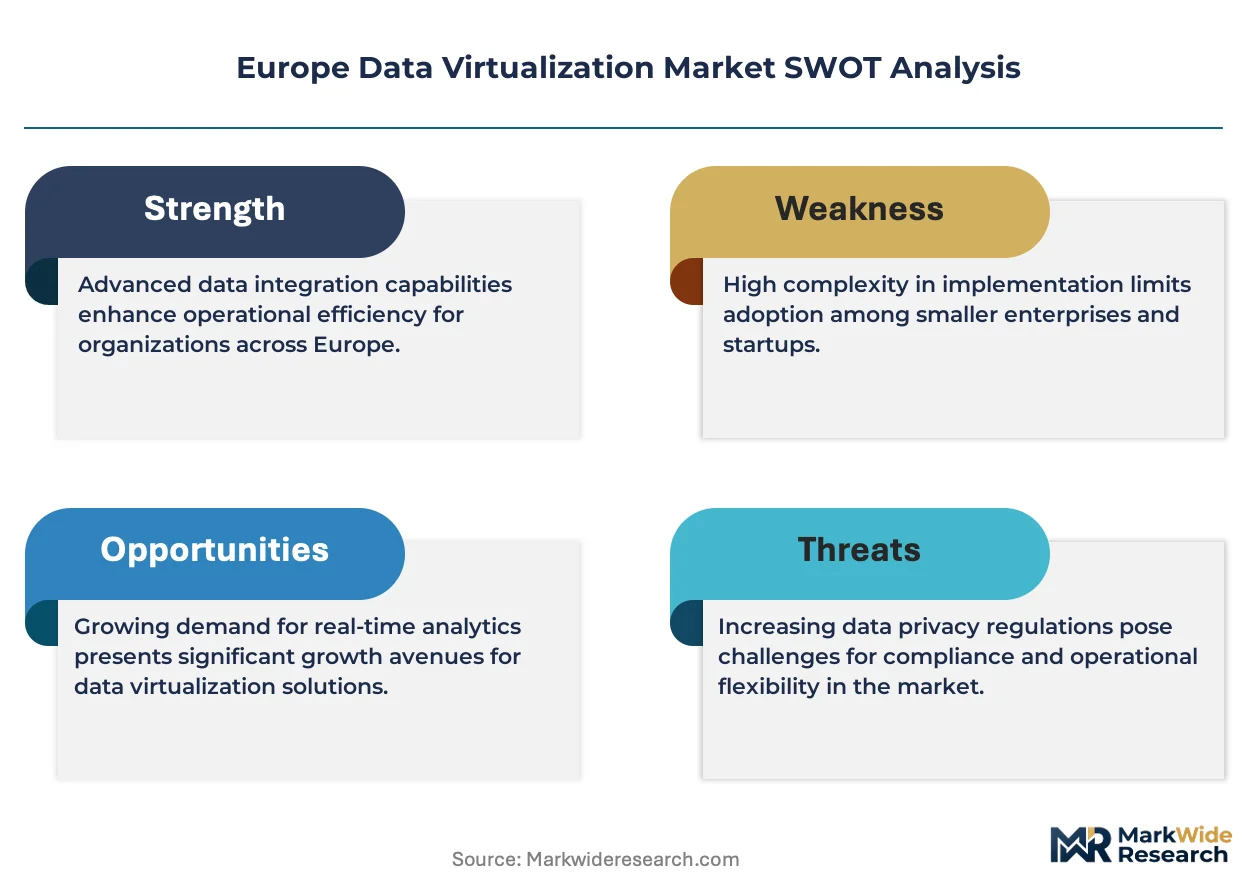
The EU AI Act's risk-classification framework and GDPR enforcement are compressing procurement cycles, forcing architecture teams to prioritize governed data federation over point-to-point integration stacks.
Growth Catalysts
- GDPR Compliance Mandates:National data protection authorities across Germany and France are levying penalties for inadequate data lineage, compelling enterprises to deploy virtualization layers with automated policy enforcement.
- Cloud-Native Migration:Banking institutions in the United Kingdom and Nordic markets are exiting rigid on-premises commitments, accelerating demand for elastic query federation across distributed warehouses.
- Real-Time Analytics:Telecommunications operators require sub-second subscriber 360 views, driving virtualization adoption to unify streaming pipelines with historical SQL databases without physical consolidation.
Market Restraints
- Specialized Talent Scarcity:Metadata engineering and query optimization expertise concentrates in London, Frankfurt, and Amsterdam, inflating implementation costs for peripheral markets.
- Legacy System Inertia:Mainframe-connected data architectures in continental European banks resist abstraction-layer insertion, extending pilot-to-production timelines.
- Input Cost Volatility:Cloud egress fees and cross-region data transfer tariffs from hyperscale providers erode virtualization's promised cost advantages at scale.
Strategic Opportunities
- Eastern European Expansion:Poland and Czech Republic enterprise markets remain underpenetrated for governed data federation, presenting first-mover advantages for cloud-native vendors.
- Healthcare Data Traceability:EMA guidelines on clinical trial data lineage create procurement tailwinds for virtualization platforms with automated audit trails in pharmaceutical deployments.
- API Monetization Convergence:The intersection of data virtualization with API management tooling enables new revenue streams through governed data product marketplaces.
Industry Challenges
- Metadata Governance Complexity:Cross-border data residency requirements under GDPR fragment logical data catalogs, requiring jurisdiction-specific policy orchestration.
- Query Performance Optimization:Distributed join operations across heterogeneous sources demand specialized caching strategies that stretch existing DBA skill sets.
- Vendor Lock-In Risks:Proprietary query languages and metadata formats complicate multi-year platform commitments and future migration planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Virtualization Market |
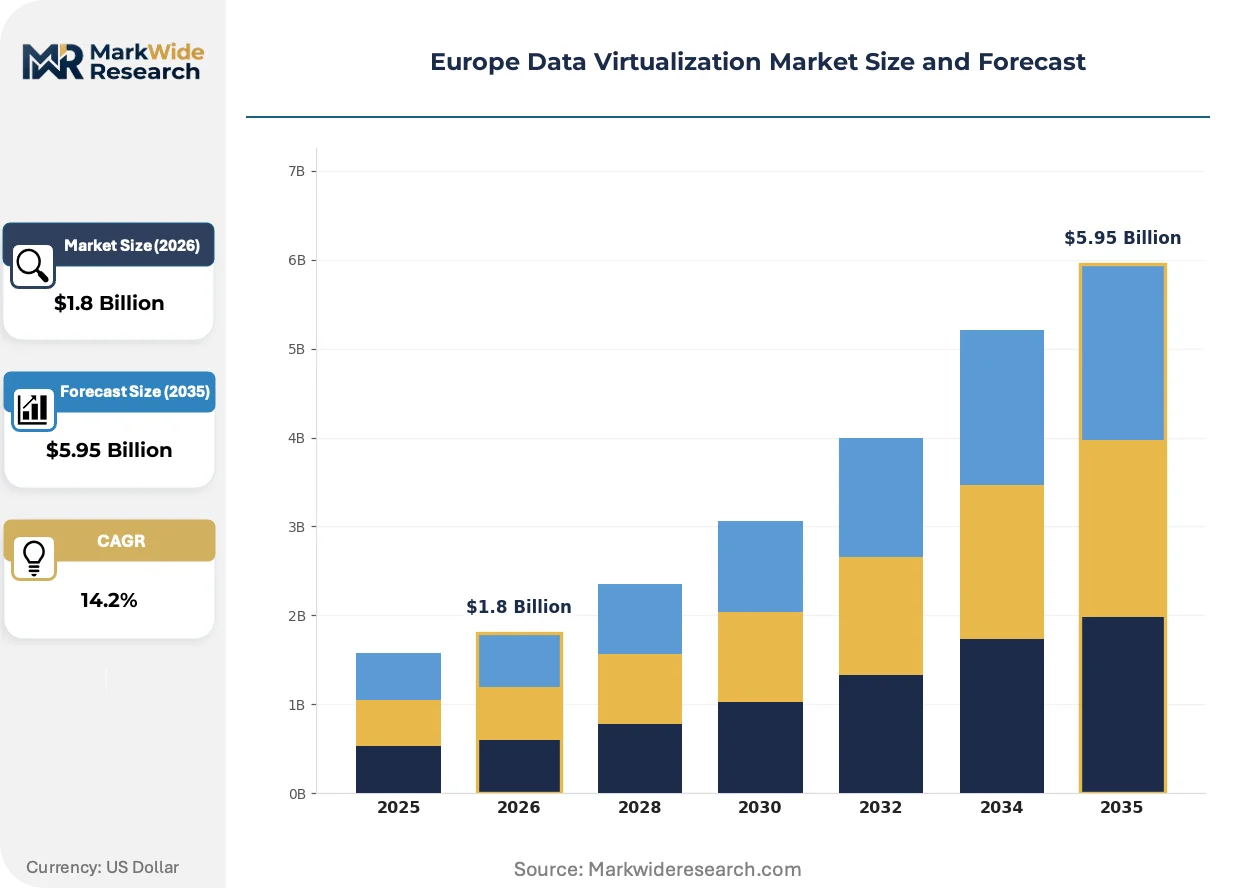
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid Cloud, Multi-Cloud End User: Banking, Healthcare, Retail, Telecommunications Solution: Data Integration, Data Warehousing, API Management, Business Intelligence Technology: Streaming Analytics, ETL Tools, NoSQL, Data Lakes |
| Companies Covered | Oracle Corporation, IBM Corporation, Cisco Systems, Inc., Salesforce.com, Inc., Workday, Inc., Alteryx, Inc., Domo, Inc., Cluvio GmbH, QlikTech International AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Virtualization Market Trends and Innovations
Query optimization engines and automated lineage tracking are compressing the gap between raw data infrastructure and consumable analytics, reshaping how European enterprises architect their information supply chains.
Semantic layer platforms are digitizing business logic abstraction, embedding governance rules directly into queryable views. German automotive manufacturers and French insurers are deploying these layers at scale, collapsing the traditional ETL pipeline into real-time federation. This compression is digitizing how domain experts access governed data without engineering intervention.
The EU AI Act's risk-classification framework mandates automated documentation of training data provenance. Virtualization vendors are embedding lineage APIs that satisfy high-risk system requirements. Healthcare and financial services deployments in the Netherlands and Spain are prioritizing these capabilities in procurement evaluations.
Buyer committees now mandate proof-of-concept benchmarks against existing integration stacks before committing to multi-year virtualization contracts. Systems integrators in the United Kingdom are responding with outcome-guaranteed implementation partnerships. This behavioral shift is most pronounced in banking and telecommunications verticals where data volume complexity previously favored incumbent tooling.
Europe Data Virtualization Market Segmentation
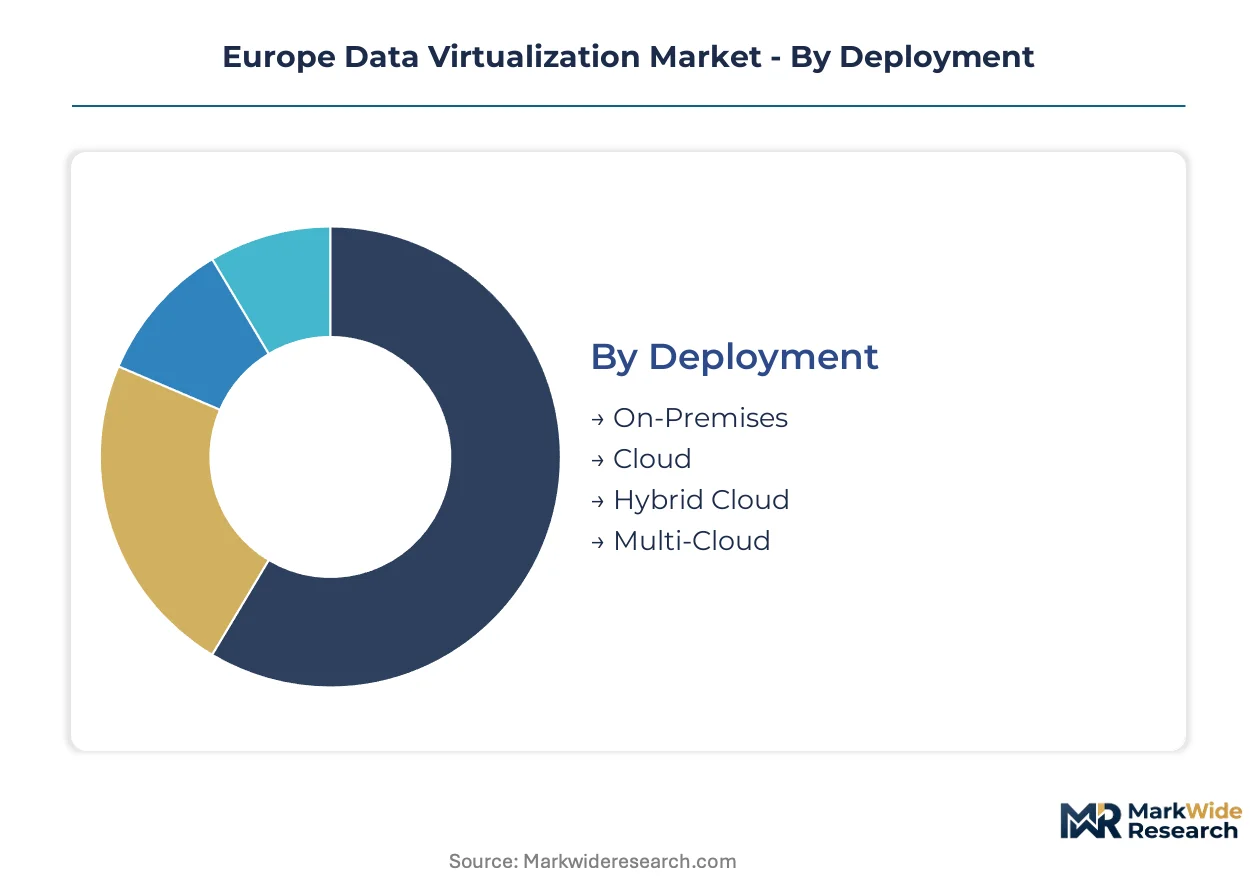
Deployment architecture determines service intensity and renewal economics in European data virtualization procurement. Banking and telecommunications buyers in Frankfurt and London prioritize vendor responsiveness during live query optimization failures.
Deployment:
After-sales service intensity varies sharply by infrastructure location, with cloud-native deployments demanding 24/7 managed query optimization support.
- Cloud:Elastic compute pools enable sub-second federation across distributed warehouses without physical data movement. United Kingdom banking institutions are consolidating on this architecture to exit rigid data center commitments while maintaining GDPR-compliant residency controls.
- Hybrid Cloud:Split query execution between on-premises mainframes and cloud warehouses preserves legacy system investments. German automotive manufacturers deploy this model to federate engineering data lakes with supplier cloud platforms without wholesale migration.
- On-Premises:Retained by continental European banks with mainframe-centric risk calculation systems requiring jurisdictional data sovereignty.
- Multi-Cloud:Emerging among Nordic enterprises seeking to avoid hyperscaler lock-in through cross-cloud query federation.
By volume, Cloud leads. By growth pace, Hybrid Cloud is ahead.
End User:
Application criticality shapes pricing tolerance, with real-time risk systems commanding premium support tiers over batch analytics.
- Banking:Real-time counterparty exposure calculation drives sub-second query requirements across fragmented trading book databases. French and German institutions are prioritizing virtualization layers with automated lineage tracking for EU AI Act compliance.
- Telecommunications:Subscriber 360 initiatives unify streaming call detail records with historical billing archives. Nordic operators are expanding fastest due to 5G network data volume spikes.
- Healthcare:EMA clinical trial traceability mandates are accelerating procurement in Netherlands and Spain pharmaceutical deployments.
- Retail:Inventory federation across omnichannel warehouses concentrates demand in United Kingdom and French markets.
Banking captures the largest revenue pool. Telecommunications is expanding most quickly.
Solution:
Margin concentration follows governance complexity, with API security modules pricing at multiples of basic integration tooling.
- API Management:Governed data product marketplaces enable monetization of federated datasets through policy-enforced access controls. United Kingdom systems integrators are bundling outcome-guaranteed implementation partnerships around this capability.
- Data Integration:Metadata-driven pipeline orchestration remains the volume anchor across mid-market European enterprises.
- Business Intelligence:Embedded semantic layers are digitizing domain expert access without engineering intervention in German manufacturing deployments.
- Data Warehousing:Logical warehouse abstraction is displacing physical consolidation in cloud-native Nordic migrations.
Data Integration leads by deployment count. API Management is climbing the fastest.
Technology:
Skill scarcity concentrates in streaming optimization, inflating implementation costs for real-time federation projects.
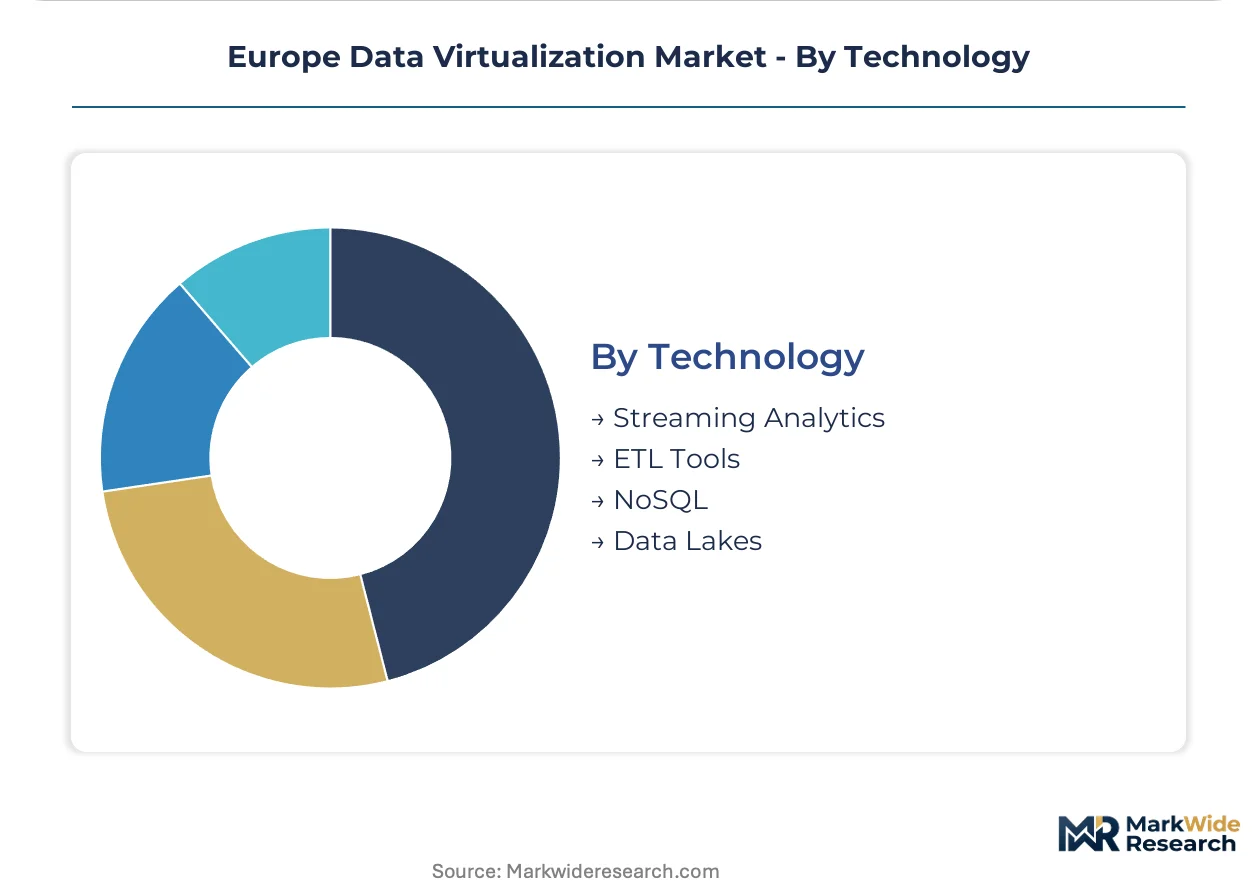
- Streaming Analytics:Continuous query processing across Apache Kafka and cloud event hubs enables real-time risk and subscriber analytics. London and Amsterdam talent pools dominate this specialization.
- Data Lakes:Object storage federation without schema enforcement supports exploratory analytics in pharmaceutical research deployments.
- ETL Tools:Traditional batch extraction remains entrenched in mainframe-connected continental banking architectures.
- NoSQL:Document and graph store federation addresses product catalog and social network analytics in retail and media verticals.
ETL Tools retains the largest installed base. Streaming Analytics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in London and Frankfurt procurement clusters while peripheral markets absorb implementation premiums. United Kingdom banking institutions negotiate outcome-guaranteed service contracts unavailable in Warsaw or Prague. German automotive manufacturers command volume discounts that compress margins for vendors serving smaller Nordic operators.
Germany
Frankfurt banking clusters drive demand for real-time counterparty exposure calculation across fragmented trading systems. The EU AI Act's risk-classification framework mandates automated lineage tracking in financial services deployments. Bavarian automotive manufacturers federate engineering data lakes with supplier cloud platforms through hybrid cloud architectures.
United Kingdom
London financial services firms prioritize 24/7 managed query optimization support during live system failures. GDPR enforcement by the Information Commissioner's Office accelerates procurement of virtualization layers with automated policy enforcement. Telecommunications operators in Manchester and Birmingham expand subscriber 360 initiatives unifying streaming pipelines with historical archives.
France
Parisian insurers deploy semantic layer platforms to collapse traditional ETL pipelines into real-time federation. The CNIL levies penalties for inadequate data lineage, compelling enterprises toward governed data federation. Lyon-based pharmaceutical operations prioritize EMA-compliant clinical trial traceability capabilities in procurement evaluations.
Netherlands
Amsterdam talent pools dominate streaming analytics specialization, inflating implementation costs for real-time federation projects. Healthcare deployments in Utrecht and Rotterdam prioritize automated audit trails satisfying EMA guidelines on clinical data traceability. Dutch banking institutions consolidate on cloud-native architectures to exit rigid data center commitments.
Sweden
Nordic telecommunications operators expand fastest due to 5G network data volume spikes requiring sub-second subscriber analytics. Swedish enterprises seek multi-cloud query federation to avoid hyperscaler lock-in across distributed warehouses. Stockholm procurement teams mandate proof-of-concept benchmarks before committing to multi-year virtualization contracts.
Europe Data Virtualization Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower governance modules. The vendor base stratifies between database incumbents anchoring financial services contracts and cloud-native challengers capturing mid-market share. Three archetypes dominate: legacy database vendors extending virtualization layers, pure-play federation specialists, and analytics-integrated platform providers. Competitive moves concentrate on hybrid cloud partnership structures and embedded AI governance certifications.
Within the legacy platform tier, Oracle Corporation and IBM Corporation represent database incumbents leveraging established enterprise footprints. QlikTech International AB exemplifies the analytics-integrated archetype occupying mid-market segments through partner-channel density. Cisco Systems, Inc. sits within the infrastructure-anchored category, extending network-centric data fabrics toward virtualization adjacencies.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| Cisco Systems, Inc. |
| Salesforce.com, Inc. |
| Workday, Inc. |
| Alteryx, Inc. |
| Domo, Inc. |
| Cluvio GmbH |
| QlikTech International AB |
| Others |
Pricing and Supply Chain Analysis
Frankfurt's banking technology cluster anchors European data virtualization capacity, concentrating vendor engineering resources and support infrastructure. This geographic density translates into pricing power for enterprise deployments, while peripheral markets absorb talent scarcity premiums that stretch implementation budgets.
Pricing Analysis
The customization-premium spread separates governed enterprise tiers from standardized mid-market offerings. Subscription-based SaaS pricing dominates cloud-native deployments, with GDPR compliance certification and automated lineage enforcement commanding substantial premiums over basic federation tooling. Price differentiation hinges on query optimization service levels and cross-border data residency orchestration. Cost compression in the mid-market segment intensifies as channel partners bundle outcome-guaranteed implementations. Banking institutions in London and Frankfurt exhibit lowest price sensitivity due to regulatory compliance imperatives, while retail and mid-market manufacturing buyers in Eastern Europe resist premium tiers.
Supply Chain Analysis
Tariff exposure between United States and European Union cloud infrastructure providers dominates supply chain risk assessment for data virtualization platforms. Engineering talent concentrates in United Kingdom, Germany, and Netherlands, with query optimization specialists clustering in London and Amsterdam. Raw material dependencies include hyperscale compute capacity, API management licensing, and metadata governance tooling. Single-source vulnerability persists for streaming analytics components tethered to Apache Kafka commercial distributions. Distribution runs through systems integrators in United Kingdom and Germany, with outcome-based partnerships displacing direct vendor relationships in banking verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data virtualization incumbents face substitution pressure from modern data mesh architectures and lakehouse platforms that collapse federation into storage-compute layers. Defending installed base requires demonstrating differentiated governance capabilities that standalone alternatives cannot replicate.
For Market Incumbents: Harden hybrid cloud integration depth to preserve mainframe-connected banking relationships against cloud-native challengers. Anchor financial services contracts through embedded EU AI Act compliance automation that substitutes cannot match. Prioritize capacity expansion in Amsterdam and London talent pools to reduce delivery cost inflation. Certification investment in EMA-aligned healthcare deployments creates defensible positioning against generalized competitors. For New Entrants and Emerging Players: Establish a beachhead in Poland and Czech Republic enterprise markets where governed data federation remains underpenetrated. Target healthcare pharmaceutical deployments in Netherlands and Spain where EMA traceability mandates accelerate procurement without incumbent saturation. Channel partnerships with United Kingdom systems integrators provide fastest route to outcome-guaranteed credibility in banking proof-of-concept evaluations. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-anchored infrastructure play because regulatory enforcement deepens data governance requirements across European verticals. Acquisition candidates with automated lineage APIs and multi-cloud query federation capabilities command strategic premium. The signal to watch is EU AI Act high-risk system designations expanding beyond financial services into healthcare and critical infrastructure sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded semantic layers collapse ETL pipelines for German automotive manufacturers. |
| Geographic Expansion | Eastern European first-mover positioning captures underserved Polish and Czech enterprise demand. |
| Strategic Partnership | Outcome-guaranteed systems integrator alliances accelerate banking procurement cycles in London. |
| Acquisition of Specialist Firm | Streaming analytics talent pools in Amsterdam address skill scarcity inflating project costs. |
| Product Launch | EMA-compliant lineage APIs satisfy pharmaceutical traceability mandates in Netherlands deployments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vendor financial disclosures, EU regulatory filings, and hyperscaler infrastructure deployment data. Interviews with CTOs, IT procurement officers, platform engineers, and channel partners across Frankfurt, London, and Amsterdam informed demand-side validation. Secondary sources include EMA guideline documents, GDPR enforcement records from national data protection authorities, and cloud provider capex disclosures. Bottom-up deployment counts across banking, telecommunications, and healthcare verticals triangulate against top-down addressable market sizing.
Forecast inputs incorporate deployment architecture shifts, vertical adoption patterns, and regulatory compliance timeline accelerations across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, end-user vertical, solution type, and regional adoption cluster. CAGRs derive from elasticity-adjusted penetration curves applied to baseline infrastructure spending. Query performance benchmarks and proof-of-concept success rates inform technology-specific growth assumptions.
Sensitivities concentrate around EU AI Act enforcement intensity, cloud egress fee volatility, and talent pool expansion in peripheral markets. Forecasts reflect assumptions about regulatory compliance deadlines and hyperscaler pricing stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Global Data Virtualization Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Event Apps Market
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Kubernetes Solutions Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Global Dock and Yard Management System Market