

On-Demand Warehousing Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
On-Demand Warehousing Platforms Market Insights
Asset-light leasing models are rewriting competitive entry barriers in on-demand warehousing. Flexe leverages its national network of partner facilities to offer elastic capacity without capital-intensive real estate holdings. Stord anchors its position through backward integration into proprietary warehouse management software. Flowspace competes by specializing in rapid onboarding for mid-market brands seeking seasonal surge capacity.
On-demand warehousing platforms constitute digital marketplaces that connect unused or underutilized warehouse space with businesses requiring flexible storage and fulfillment capacity, typically operating through cloud-based inventory synchronization and real-time slot allocation algorithms. These systems serve the primary commercial purpose of converting fixed logistics costs into variable operating expenses for shippers with volatile demand patterns. Cloud-based platform architecture currently leads deployment volume due to lower infrastructure barriers and faster implementation cycles. API-integrated service offerings represent the fastest-expanding segment as enterprise clients demand seamless connectivity with existing ERP and order management systems. Inventory management services command the deepest margin pools because recurring software subscriptions generate predictable revenue streams distinct from transactional space matching.
OSHA workplace safety standards and FAA drone delivery frameworks in the United States, alongside EU Green Deal logistics emissions regulations and Germany's KBA transport compliance requirements, collectively shape facility certification demands and last-mile automation investments. China's MIIT cloud service licensing rules and GB standards for data localization further constrain platform architecture choices for operators serving multinational clients. Stakeholders must monitor evolving building energy codes and autonomous vehicle pilot programs as these will determine which platform operators can offer compliant cold storage and same-day delivery services at scale.
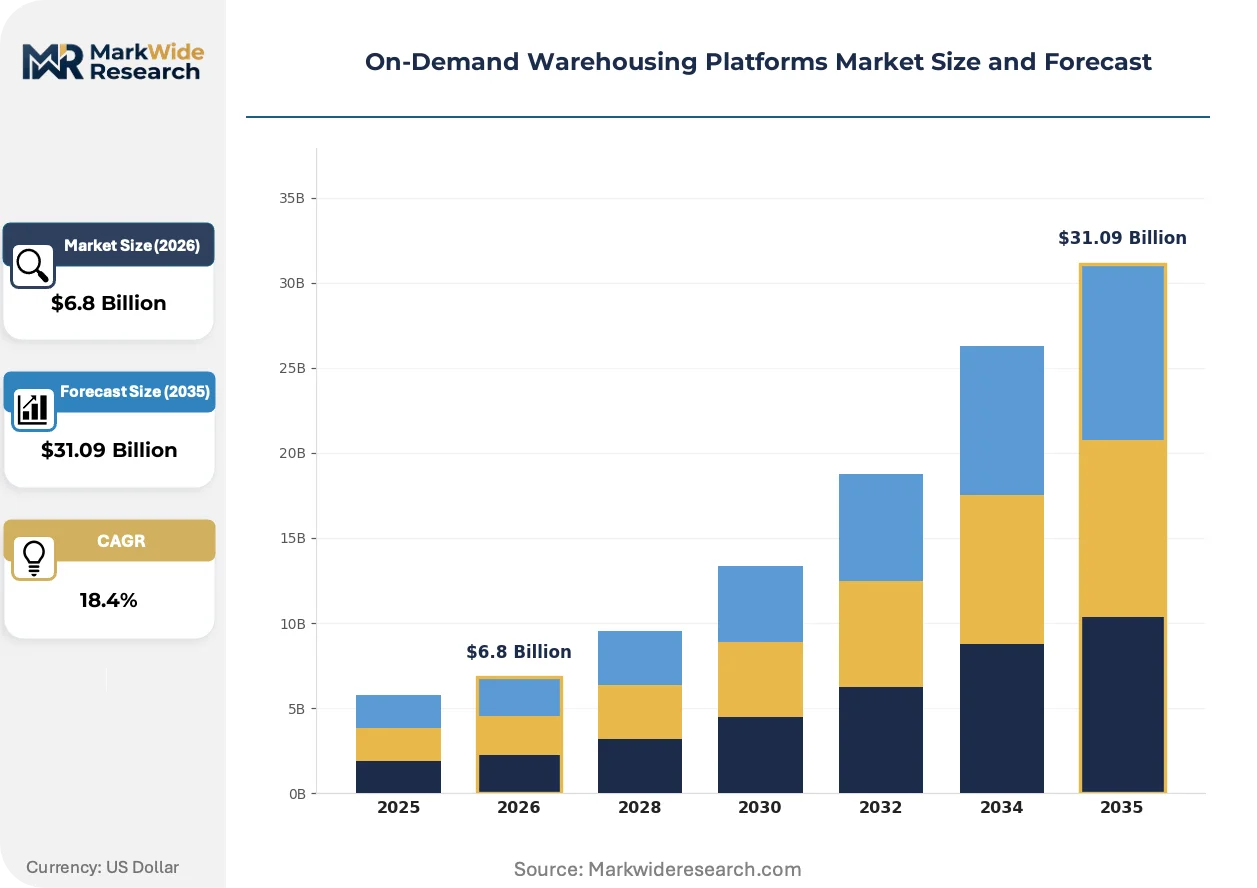
Market Dynamics
API-integrated logistics networks are compressing deployment timelines from months to weeks, forcing warehouse operators to restructure capital allocation away from fixed infrastructure toward software-centric capacity orchestration.
Growth Catalysts
- E-commerce fulfillment surge:Retail chains and consumer electronics vendors require elastic storage to manage volatile seasonal demand without long-term lease commitments.
- EU Green Deal logistics emissions regulations:Facility certification demands for carbon-efficient operations are accelerating platform adoption among operators seeking compliant capacity expansion.
- Cloud-based inventory synchronization:Real-time slot allocation algorithms enable shippers to convert fixed logistics costs into variable operating expenses.
Market Restraints
- Data localization mandates:China's GB standards and MIIT cloud service licensing rules constrain platform architecture choices for multinational clients.
- Cold storage capex intensity:Temperature-controlled infrastructure requires specialized equipment that limits rapid facility onboarding.
- Legacy ERP integration friction:Proprietary warehouse management systems create technical debt that slows API connectivity deployment.
Strategic Opportunities
- Drone delivery corridors:FAA pilot programs and autonomous vehicle frameworks in the United States create compliant last-mile infrastructure partnerships.
- Germany's KBA transport compliance requirements:Certification standards for automated logistics equipment generate demand for pre-certified platform networks.
- Mid-market brand seasonal surge capacity:Rapid onboarding protocols for consumer packaged goods companies unlock underutilized warehouse space during peak periods.
Industry Challenges
- Workforce certification gaps:OSHA workplace safety standards require specialized training for autonomous equipment operation that outpaces available talent pipelines.
- Multi-tenant security protocols:Shared warehouse environments demand segmented data architectures that complicate software development cycles.
- Cross-border customs synchronization:Real-time inventory visibility across jurisdictions requires harmonized regulatory reporting that platforms struggle to standardize.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Demand Warehousing Platforms Market Trends and Innovations
Digital twin technology and predictive slot pricing algorithms are restructuring how warehouse capacity gets discovered, contracted, and utilized across fragmented real estate markets.
Edge computing nodes deployed within warehouse facilities are collapsing latency between inventory sensors and allocation engines. Third-party logistics providers operating cross-border fulfillment are adopting these systems fastest. The technology is collapsing the distinction between physical space availability and digital booking confirmation.
Germany's KBA transport compliance requirements are mandating telematics integration for automated material handling equipment. Warehouse operators must retrofit facilities with certified tracking systems or face operational restrictions. Cold storage networks serving pharmaceutical distribution are investing most aggressively to meet these standards.
Shippers now contract capacity through dynamic marketplaces rather than bilateral lease negotiations. Mid-market brands previously locked into annual contracts access surge space through API-integrated procurement platforms. This pattern concentrates in the United States where dense last-mile delivery ecosystems support rapid inventory repositioning.
On-Demand Warehousing Platforms Market Segmentation
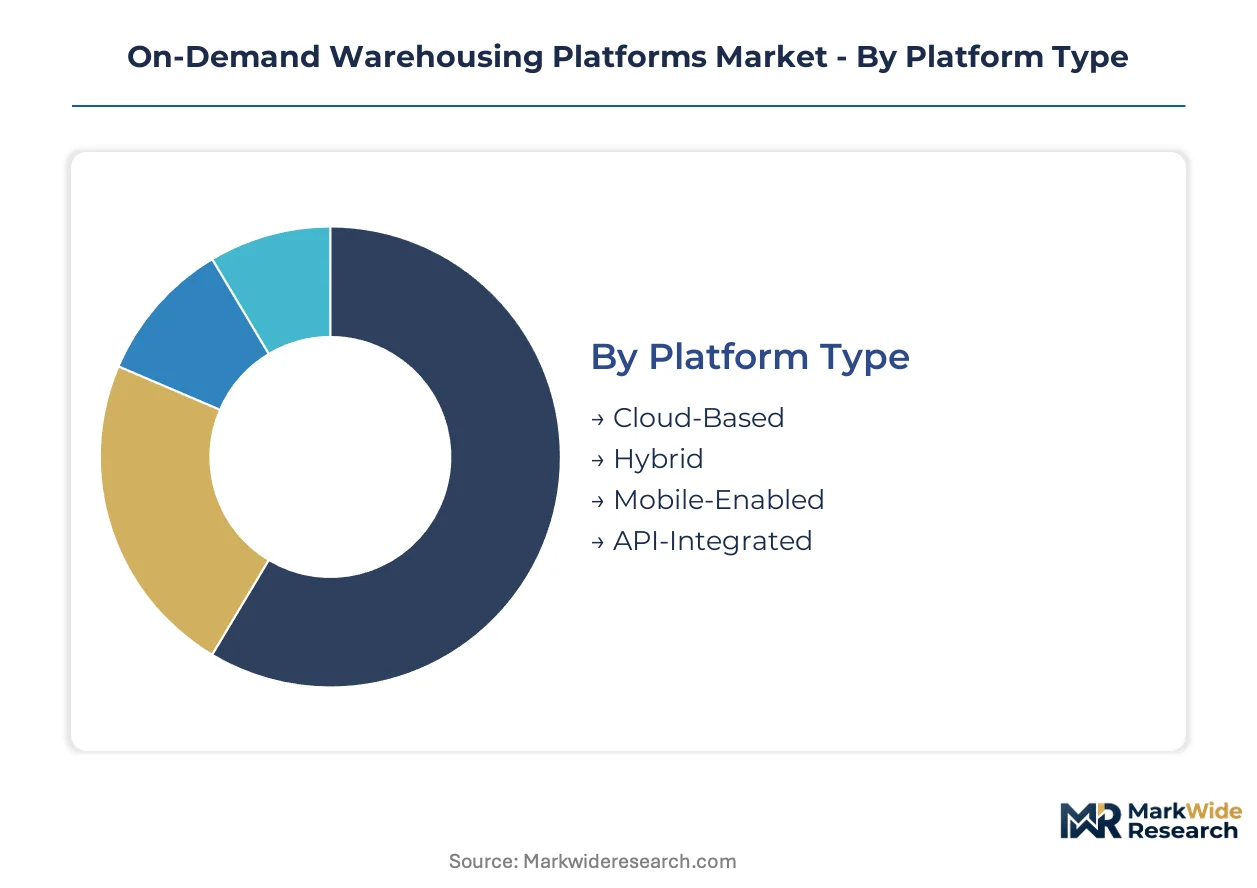
On-demand warehousing platforms fragment across four distinct dimensions, each revealing divergent margin structures and customer stickiness profiles. Platform architecture choices determine integration complexity, while service bundling strategies separate transactional space brokers from recurring revenue operators.
Platform Type:
After-sales service intensity varies dramatically by deployment architecture, with cloud-native platforms requiring continuous API maintenance and hybrid systems demanding on-premise technical support.
- Cloud-Based:Pure SaaS delivery eliminates local infrastructure burdens. E-commerce fulfillment operators in the United States favor this architecture for rapid scaling without capital commitment.
- API-Integrated:Real-time ERP connectivity commands premium positioning. Third-party logistics providers in Germany adopt these systems fastest to satisfy KBA transport compliance requirements for automated material handling.
- Hybrid:Blended cloud-edge deployments serve multinational clients navigating China's MIIT data localization rules.
- Mobile-Enabled:Smartphone-native interfaces target mid-market brands with limited technical staff.
Cloud-Based holds the largest share; momentum sits with API-Integrated.
Service Offering:
Cost tier separation defines competitive positioning, with software-centric services capturing recurring revenue and space-matching functions competing on transaction efficiency.
- Inventory Management:Cloud-based synchronization platforms convert fixed warehouse costs into variable operating expenses. Retail chains deploy these systems to manage volatile seasonal demand without long-term lease exposure.
- Order Fulfillment:End-to-end picking, packing, and shipping orchestration integrates with last-mile delivery networks. Consumer electronics vendors in the United States concentrate demand here for same-day delivery capabilities.
- Space Leasing:Elastic capacity matching serves startups seeking surge storage without capital intensity.
- Real-Time Tracking:Sensor-based visibility tools satisfy pharmaceutical cold chain requirements.
- Transportation Coordination:Multi-carrier rate optimization appeals to cost-sensitive manufacturers.
Inventory Management commands the deepest margin pools; Order Fulfillment is gaining share fastest.
Application:
Volume concentration patterns reveal which use cases justify platform infrastructure investments versus spot-market alternatives.
- E-Commerce Fulfillment:Seasonal surge capacity underpins platform economics. Retail chains and consumer electronics vendors drive adoption across the United States, Germany, and China.
- Cold Storage Solutions:Temperature-controlled infrastructure requires specialized equipment certification. Food and beverage suppliers face EU Green Deal emissions regulations that accelerate compliant platform adoption.
- Third-Party Logistics:Asset-light 3PLs use platforms to extend geographic coverage without facility ownership.
- Direct Store Delivery:Rapid replenishment cycles serve fragmented retail footprints.
- Reverse Logistics:Returns processing complexity creates demand for flexible space allocation.
E-Commerce Fulfillment holds the largest share; Cold Storage Solutions shows the steepest expansion trajectory.
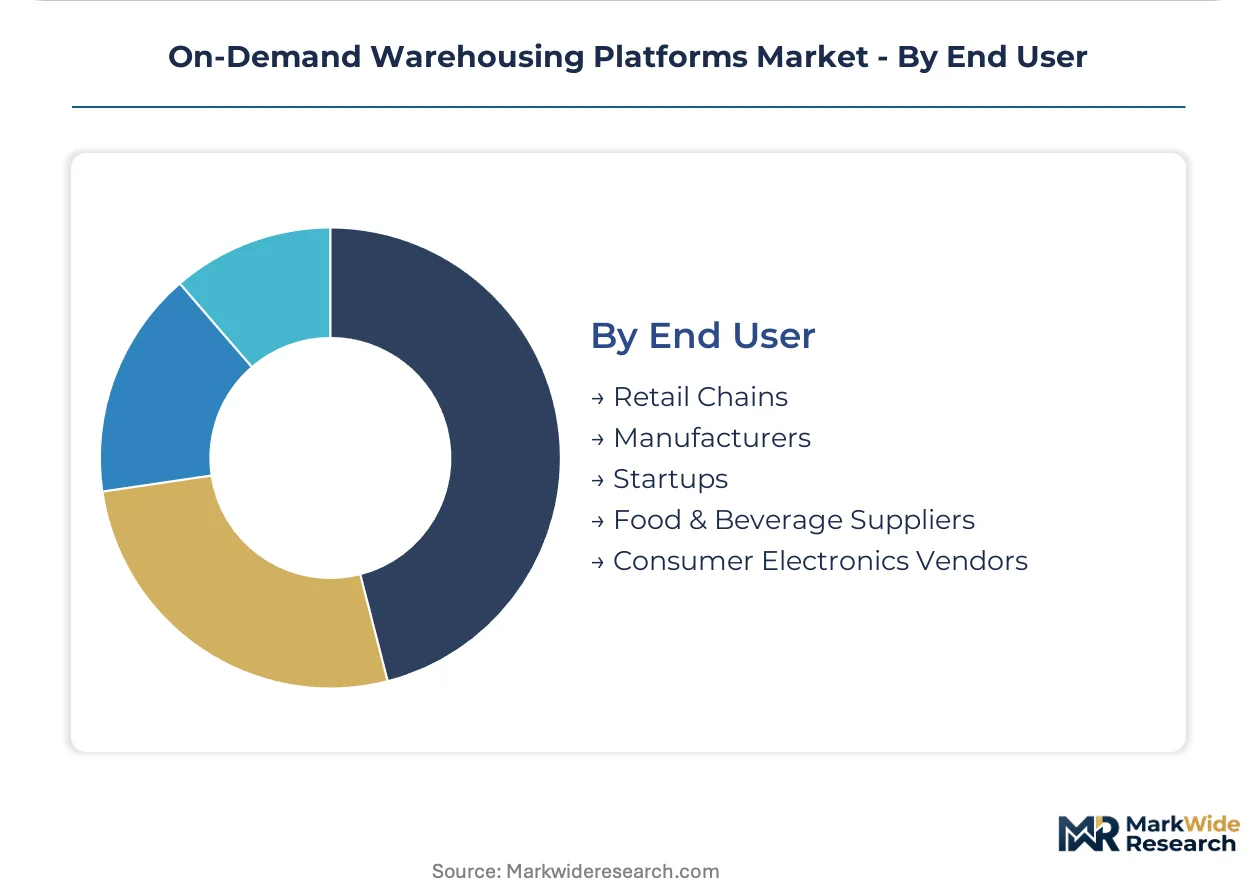
End User:
Customer type determines contract duration, integration depth, and susceptibility to churn from competing capacity sources.
- Retail Chains:Omnichannel inventory repositioning demands elastic warehouse networks. Dense last-mile ecosystems in the United States support rapid deployment of platform-based surge capacity.
- Consumer Electronics Vendors:Product launch volatility and seasonal peaks create ideal platform economics. These buyers prioritize API-integrated procurement over bilateral lease negotiations.
- Startups:Capital constraints and demand uncertainty make variable cost structures attractive.
- Manufacturers:Just-in-time inventory strategies require proximity to production facilities.
- Food & Beverage Suppliers:Cold chain compliance requirements filter platform selection toward certified networks.
Retail Chains hold the largest share; Consumer Electronics Vendors are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany, where dense last-mile networks and strict certification requirements create premium capture opportunities unavailable in emerging markets with fragmented logistics infrastructure.
United States
E-commerce fulfillment operators and consumer electronics vendors drive platform adoption through seasonal surge demand. OSHA workplace safety standards and FAA drone delivery pilot programs shape facility certification and automation investments. The Los Angeles-Inland Empire corridor anchors the nation's largest on-demand warehousing cluster, with operators competing on API integration speed.
Germany
Retail chains and automotive suppliers require elastic storage to manage just-in-time inventory without long-term lease exposure. EU Green Deal logistics emissions regulations and KBA transport compliance requirements mandate telematics integration for automated material handling equipment. The Rhine-Ruhr metropolitan region concentrates platform activity near major distribution hubs.
China
Consumer electronics vendors and cross-border e-commerce platforms seek variable cost structures amid demand volatility. MIIT cloud service licensing rules and GB standards for data localization constrain multinational platform architecture choices. The Yangtze River Delta, particularly Shanghai and surrounding provinces, hosts the densest concentration of compliant warehousing capacity.
United Kingdom
Omnichannel retailers reposition inventory across elastic warehouse networks to serve fragmented urban delivery requirements. CSRD sustainability reporting obligations and building energy codes accelerate demand for certified carbon-efficient platform capacity. The Midlands logistics triangle—Birmingham, Leicester, Nottingham—serves as the primary hub for on-demand fulfillment services.
India
Startup ecosystems and mid-market brands adopt asset-light warehousing to avoid capital-intensive real estate commitments. BIS warehouse safety standards and state-level logistics policies create compliance complexity for platform operators. Maharashtra and Karnataka, centered on Mumbai and Bangalore, concentrate venture-backed logistics technology deployment.
On-Demand Warehousing Platforms Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in inventory synchronization and slot allocation algorithms. The vendor base shows moderate concentration, with national networks competing against regional specialists and vertical software providers. Three archetypes dominate: asset-light marketplace operators, backward-integrated software-platform hybrids, and rapid-onboarding specialists serving seasonal demand. Competitive moves center on API partnership expansion and proprietary warehouse management system development.
Within the asset-light marketplace tier, Flexe exemplifies network aggregation without real estate ownership. Stord occupies a position combining proprietary software with physical infrastructure control. Flowspace represents rapid onboarding specialization for mid-market brands with volatile demand patterns.
| Leading Market Players |
|---|
| Flexe |
| Flowspace |
| Stord |
| ShipBob |
| Ware2Go |
| Extensiv |
| Red Stag Fulfillment |
| Cubework |
| Waredock Estonia |
| Others |
Pricing and Supply Chain Analysis
Warehouse undercapacity in the Rhine-Ruhr corridor drives supplier selectivity and pricing power concentration among certified operators. Facility operators with KBA-compliant telematics infrastructure command premium positioning as shippers absorb higher rates to secure compliant capacity during peak seasons.
Pricing Analysis
Configured-to-order API integrations carry substantial premiums over standard cloud-based inventory synchronization tiers. SaaS-tiered subscription models dominate revenue architecture, with price differentiation anchored in certification grade and after-sales service intensity. Cost compression in mid-market onboarding tiers is intensifying because Flowspace and similar rapid-deployment specialists compete aggressively on implementation speed. Startup buyers exhibit highest price sensitivity, while pharmaceutical cold chain operators demonstrate lowest elasticity due to regulatory compliance requirements.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers and supply-chain finance facilities from logistics equipment vendors stabilize operator cash conversion cycles. Platform architecture sourcing concentrates in the United States, Germany, and China, with sensor hardware drawing from Taiwan and South Korea. Single-source vulnerability in specialized cold storage equipment creates operational exposure during certification retrofits. Distribution runs through API-integrated logistics networks that compress deployment timelines from bilateral negotiation to automated procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical inventory destocking as e-commerce fulfillment operators rebuild safety stock positions ahead of seasonal demand peaks.
For Market Incumbents: Entrench network density through backward integration into proprietary warehouse management software. Incumbents must secure KBA certification pre-approval for automated material handling equipment to defend against emerging rapid-onboarding specialists. Capacity addition in the Los Angeles-Inland Empire corridor preserves pricing power in the densest last-mile ecosystem.
For New Entrants and Emerging Players: Mid-market consumer packaged goods brands in India represent the most penetrable entry point given limited incumbent API penetration and fragmented BIS compliance requirements. Cold storage solutions for pharmaceutical distribution in Germany offer certification-barrier protection against price competition. A channel partnership model with established third-party logistics providers accelerates facility network access without capital-intensive real estate acquisition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among inventory management software operators with embedded slot allocation algorithms. Long-term viability over the coming decade rests on regulatory compliance automation capabilities rather than transactional space-matching scale. Acquisition targets should demonstrate pre-certified cold storage networks and established FAA drone delivery corridor partnerships. The signal to watch is MIIT cloud service licensing approval velocity for multinational platform architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| API Partnership Expansion | Real-time ERP connectivity with SAP and Oracle systems locks in enterprise client retention. |
| Proprietary WMS Development | Captive warehouse management software generates recurring subscription revenue distinct from transactional fees. |
| Cold Storage Certification | EU Green Deal compliance enables premium positioning in pharmaceutical and food distribution verticals. |
| Drone Delivery Infrastructure | FAA pilot program participation creates compliant last-mile partnerships with autonomous vehicle operators. |
| Geographic Network Densification | Facility aggregation in the Yangtze River Delta satisfies MIIT data localization requirements for multinational clients. |
Research Methodology
A standing panel of warehouse operations directors, logistics procurement managers, platform engineering leads, and cold chain compliance officers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC filings from publicly traded logistics technology providers, customs data on warehouse equipment imports, and hyperscaler cloud infrastructure capex disclosures. Bottom-up facility capacity modeling and top-down e-commerce fulfillment demand estimation were triangulated to produce volume and value outputs.
Scenario-bracketing around regulatory approval timelines and seasonal demand volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include platform architecture type, service offering bundle, application vertical, and end-user scale tier. CAGRs were derived from weighted capacity utilization trajectories and API integration adoption curves specific to third-party logistics provider procurement patterns.
Practitioners should monitor MIIT licensing rule revisions and FAA autonomous vehicle framework updates for early signals of platform architecture constraint shifts. Forecasts reflect assumptions about e-commerce growth persistence and cold storage equipment lead times that could revise materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.