
 Paleo Food Market | 2026-2036
Paleo Food Market Size, Share, and Industry Trends Forecast 2026-2036
Paleo Food Market Analysis
Precision fermentation and cell-cultured protein processing is rewriting how paleo-compliant meat alternatives achieve texture and nutritional parity with conventional products. EPIC Provisions leverages its supply chain relationships with regenerative ranchers to secure grass-fed beef and bison inputs. Primal Kitchen anchors its portfolio around avocado-oil-based condiments and dressings that eliminate industrial seed oils. Steve's PaleoGoods differentiates through small-batch production of grain-free granola and nutrient-dense snack sticks.
Paleo food comprises edible products formulated without grains, legumes, dairy, refined sugars, or artificial additives, typically emphasizing whole animal proteins, nuts, seeds, vegetables, and fruits processed through minimal thermal or mechanical intervention to preserve micronutrient density. The category serves consumers pursuing metabolic health, autoimmune management, or athletic performance optimization through ancestral dietary patterns. Paleo Snacks currently occupies the largest revenue share within product type segmentation, driven by portable format demand among office workers and travelers. Paleo Meal Kits represent the fastest-expanding segment as subscription logistics improve and consumers seek convenience without compromising ingredient integrity. Online Retail channels capture disproportionate margin pools due to direct customer data access and lower slotting fee burdens compared to brick-and-grocery negotiations.
The FDA oversees label claims and food safety protocols for paleo products sold in the United States, while USDA organic certification requirements influence ingredient sourcing premiums and consumer trust thresholds. The EPA regulates water and land use impacts for the regenerative agriculture operations that supply many paleo brands with core proteins. Stakeholders must monitor how evolving federal definitions of "healthy" reshape shelf placement algorithms and insurance reimbursement eligibility for medically prescribed dietary interventions.
Market Dynamics
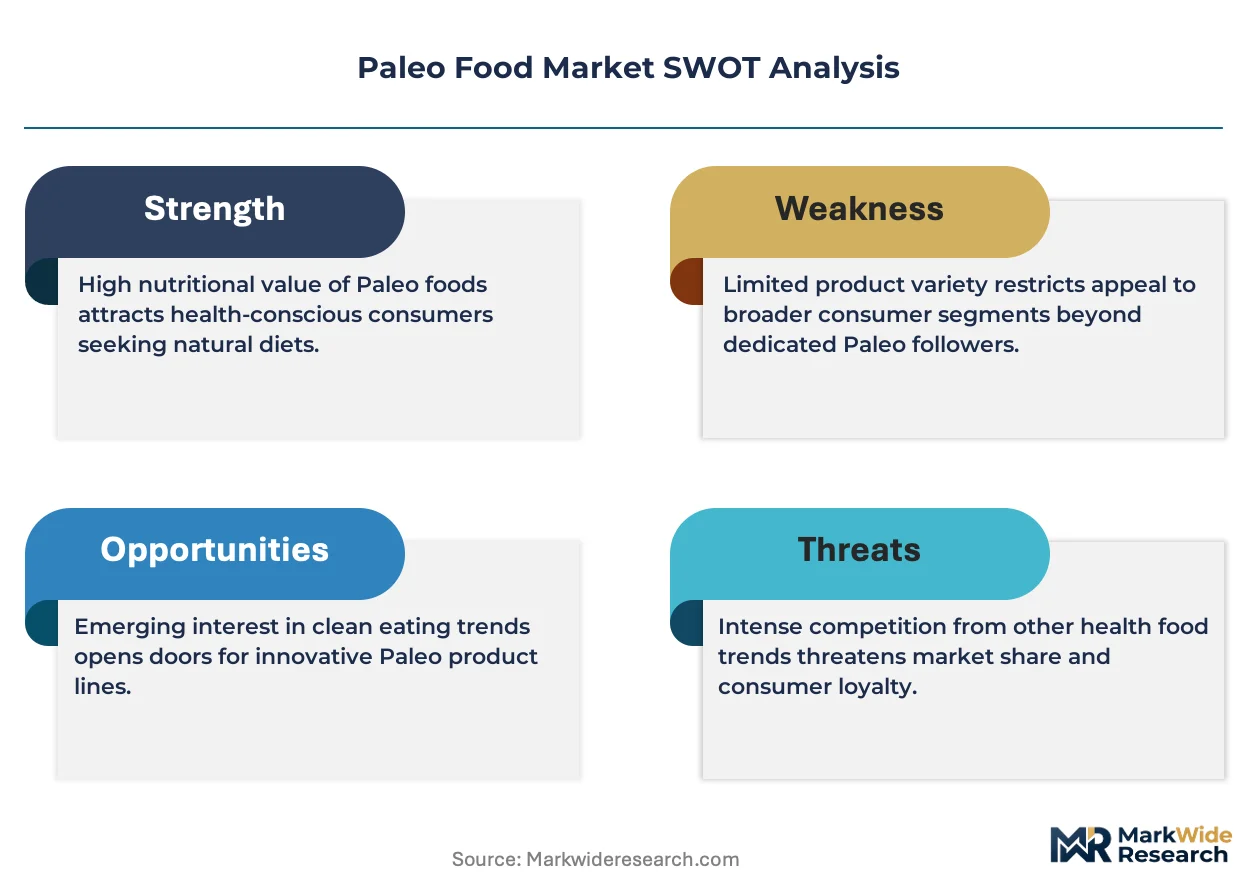
Precision fermentation infrastructure is compressing production timelines for paleo-compliant proteins while the FDA's pending "healthy" definition rewrite forces reformulation across shelf-stable categories. Clean-label verification costs now determine which brands secure placement in specialty retail.
Growth Catalysts
- Cell-cultured protein processing:Startups deploying bioreactor-based meat cultivation achieve texture parity with conventional beef and bison, eliminating feedlot dependencies. Early adopters in athletic nutrition segments drive pilot-scale capacity expansion.
- USDA organic certification thresholds:Grass-fed supply chains meeting pasture-raised standards command premium placement in natural channel resets. Regenerative sourcing protocols now filter distributor selection criteria.
- Direct-to-consumer logistics maturation:Cold-chain subscription networks reduce spoilage rates for fresh paleo meal kits. Urban clusters in Texas and Colorado anchor same-day delivery density.
Market Restraints
- Avocado oil input volatility:Mexican harvest fluctuations and water stress in California growing regions compress margin stability for condiment-focused portfolios. Single-origin dependency creates price spike exposure.
- Grass-fed beef supply concentration:Regenerative ranching operations cluster in Montana, Wyoming, and the Dakotas, limiting geographic diversification against drought or disease events. Processor capacity bottlenecks amplify seasonal constraints.
- Clean-label certification fragmentation:Competing third-party standards from Non-GMO Project, Certified Paleo, and Whole30 create compliance stacking costs without unified consumer recognition.
Strategic Opportunities
- Medically prescribed dietary interventions:Functional medicine practitioners in Arizona and Florida are writing paleo protocols for autoimmune patients. Insurance reimbursement pilot programs create institutional procurement channels.
- Paleo-compliant convenience formats:Shelf-stable protein puffs and collagen-infused beverages target airport and hospital retail. Grab-and-go placement bypasses traditional grocery slotting fee structures.
- Precision fermentation capacity scaling:Biotech infrastructure from pharmaceutical and biofuel sectors migrates into food-grade protein production. Equipment repurposing accelerates capital-efficient market entry.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates in pharma and industrial biotech hubs. Food-sector compensation benchmarks struggle to attract candidates with GMP facility experience.
- Seed-to-shelf traceability system integration:Blockchain and IoT sensor deployments require legacy ERP overhauls. Mid-tier brands face six-figure implementation timelines before retailer data-sharing mandates activate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paleo Food Market |
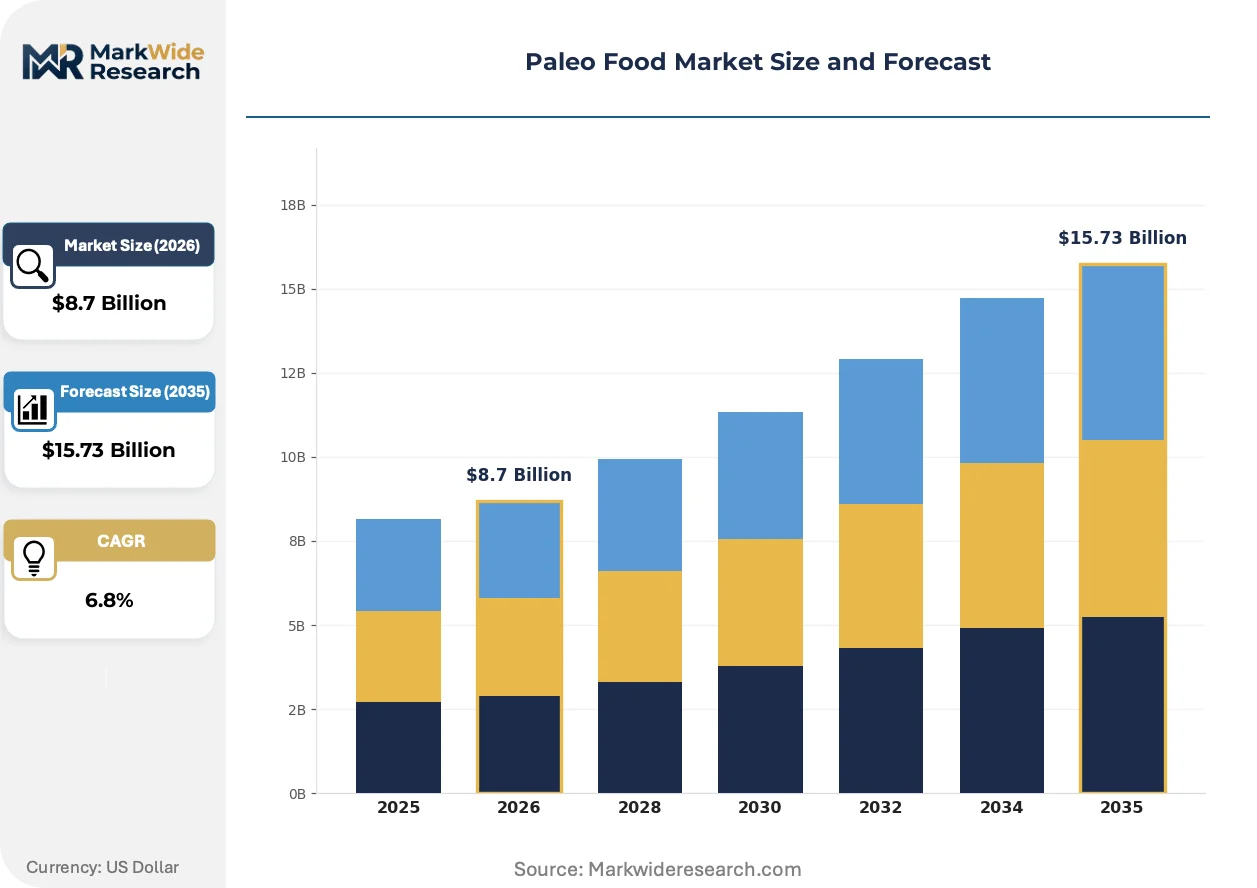
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
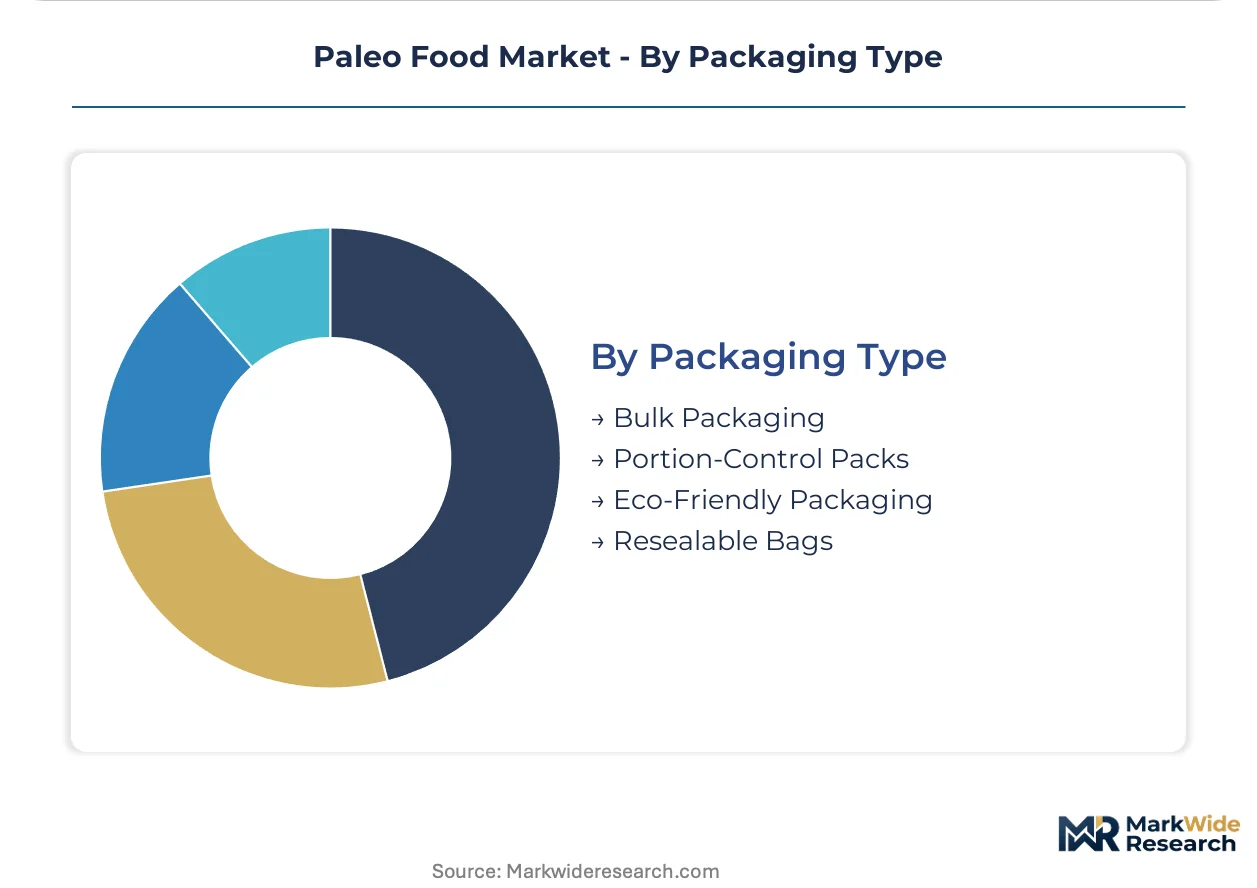
| Segmentation | Product Type: Paleo Snacks, Paleo Meal Kits, Paleo Supplements, Paleo Ingredients Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers' Markets Customer Type: Health Enthusiasts, Athletes, Families, Fitness Professionals Packaging Type: Bulk Packaging, Portion-Control Packs, Eco-Friendly Packaging, Resealable Bags |
| Companies Covered | EPIC Provisions, Caveman Foods, Paleo Treats Inc., Primal Kitchen, The Paleo Foods Co., Blue Mountain Organics, Steve's PaleoGoods, Paleo Baking Company, Kevin's Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paleo Food Market Emerging Trajectories
Formulation science is converging with biomanufacturing to eliminate industrial seed oils while preserving shelf stability. Three developments are compressing competitive timelines and reshaping procurement priorities.
High-pressure processing technology is migrating from beverage sterilization into raw paleo snack preservation. Equipment vendors in Wisconsin and Ohio are retrofitting HPP chambers for nut-based bars and fermented vegetable applications. Athletic nutrition buyers now specify non-thermal treatment protocols in supplier scorecards, compressing conventional pasteurization equipment demand.
The FDA's evolving enforcement posture on "natural" claims is forcing disclosure granularity for flavoring systems and processing aids. Brands must document mechanical versus chemical extraction methods for avocado oil and coconut derivatives. Paleo condiment segments face the steepest compliance burden as retailers demand third-party verification before reset approvals.
Subscription-based meal kit procurement is displacing weekly grocery trips among autoimmune protocol adherents. Direct relationships with regenerative ranchers bypass commodity beef pricing, locking in protein costs for twelve-month windows. Colorado and Utah households show the highest conversion rates from conventional grocery to dedicated paleo subscription services.
Paleo Food Market Segmentation
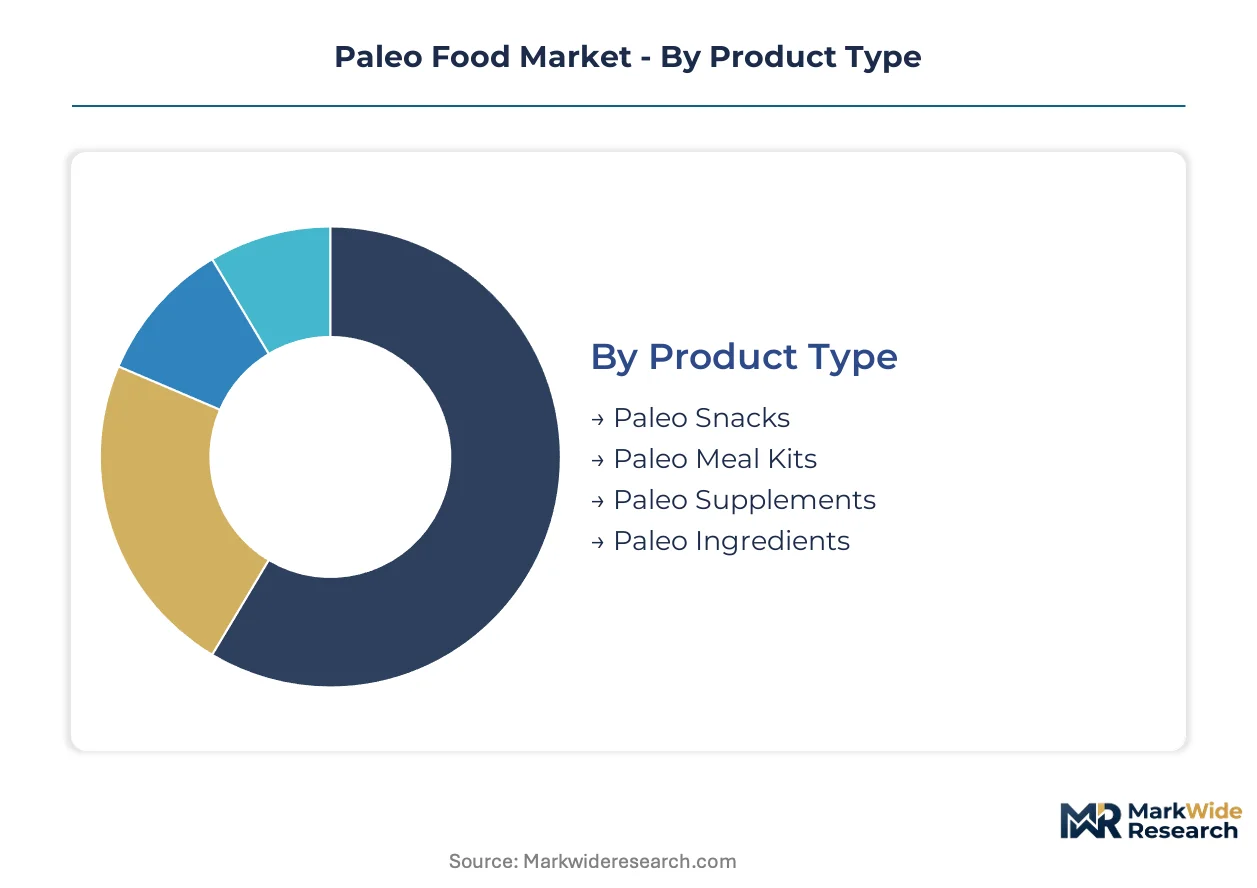
Paleo food segmentation reveals how ancestral dietary principles fragment across consumption occasions, procurement channels, and user readiness levels. Distinct packaging and distribution requirements separate convenience-driven snack buyers from committed meal-kit subscribers pursuing metabolic health protocols.
Product Type:
Volume concentration across this dimension tracks where consumers trade off preparation time against ingredient control.
- Paleo Snacks:Portable formats including meat sticks, grain-free granola, and collagen puffs deliver macronutrient density without kitchen preparation. Office workers in Austin and Denver metro areas drive repeat purchase velocity through direct-to-subscription channels.
- Paleo Meal Kits:Pre-portioned proteins and vegetables with recipe cards target households eliminating meal planning friction. Colorado and Utah households show highest conversion rates from conventional grocery as cold-chain logistics mature.
- Paleo Supplements:Collagen peptides, MCT oil powders, and organ-based desiccated formulations address micronutrient gaps in modern food systems.
- Paleo Ingredients:Almond flour, coconut aminos, and avocado oil supply home cooks and commercial kitchens formulating compliant recipes.
Paleo Snacks holds installed capacity. Paleo Meal Kits is rotating up the share rankings.
Distribution Channel:
Margin capture across this dimension depends on data ownership depth and slotting fee exposure.
- Online Retail:Direct-to-consumer platforms capture customer lifetime value through subscription locks and personalized recommendation engines. Texas and Colorado urban clusters anchor same-day delivery density for fresh meal kits.
- Supermarkets:Conventional grocers in Florida and Arizona dedicate end-cap space to certified paleo lines as autoimmune protocol awareness spreads among functional medicine patients.
- Specialty Stores:Natural channel retailers in California and New York enforce clean-label verification before reset approvals, filtering brand access.
- Farmers' Markets:Direct producer relationships in Montana and Wyoming connect regenerative ranchers with protein buyers seeking provenance transparency.
Online Retail holds installed capacity. Specialty Stores is rotating up the share rankings.
Customer Type:
Application intensity across this dimension separates therapeutic adherence from lifestyle experimentation.
- Health Enthusiasts:Consumers pursuing metabolic optimization through ancestral patterns drive premium positioning for condiment and cooking fat categories. Clean-label verification costs determine which brands secure placement in natural channel resets.
- Athletes:CrossFit affiliates and endurance training facilities in Colorado and California specify non-thermal processing protocols in supplier scorecards for protein products.
- Families:Households managing pediatric autoimmune conditions seek school-lunch-compatible formats with ingredient transparency.
- Fitness Professionals:Personal trainers and nutrition coaches in Florida and Arizona prescribe paleo protocols, creating institutional procurement channels through insurance reimbursement pilot programs.
Health Enthusiasts holds installed capacity. Athletes is rotating up the share rankings.
Packaging Type:
Supply concentration across this dimension reflects sustainability mandates colliding with shelf-life engineering requirements.
- Bulk Packaging:Foodservice quantities of almond flour and coconut oil serve commercial kitchens and high-volume home cooks in Texas and Colorado.
- Portion-Control Packs:Single-serve meat sticks and nut-based bars target airport and hospital retail where grab-and-go placement bypasses traditional grocery slotting fee structures.
- Eco-Friendly Packaging:Compostable films and molded fiber trays respond to ESG procurement criteria from specialty retailers in California and New York.
- Resealable Bags:Multi-serve formats for dried fruits and jerky address pantry stocking behavior among suburban families in Florida and Arizona.
Resealable Bags holds installed capacity. Eco-Friendly Packaging is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health enthusiasts seeking metabolic optimization concentrate in North American and European urban corridors, where specialty retail density and direct-to-consumer cold-chain infrastructure enable subscription-based procurement of grass-fed proteins and clean-label condiments.
United States
Functional medicine practitioners in Arizona and Florida prescribe paleo protocols for autoimmune patients, creating institutional procurement channels through insurance reimbursement pilots. FDA oversight of "healthy" label claims forces reformulation across shelf-stable categories. Austin and Denver anchor direct-to-subscription networks for portable snack formats.
Canada
Athletic nutrition buyers in Calgary and Vancouver specify non-thermal processing protocols for protein products. Health Canada regulations govern clean-label verification for natural channel placement. Prairie provinces concentrate regenerative ranching operations supplying grass-fed beef inputs to cross-border brands.
Germany
Clean-label verification costs determine which brands secure placement in Berlin and Munich specialty retail. EFSA guidance on novel food ingredients shapes precision fermentation protein approvals. Bavaria hosts bioprocessing equipment vendors retrofitting pharmaceutical infrastructure for food-grade applications.
United Kingdom
Autoimmune protocol adherents in London and Manchester displace weekly grocery trips with dedicated paleo subscription services. FSA enforcement on "natural" claims demands mechanical extraction documentation for avocado oil and coconut derivatives. Southeast England clusters cold-chain logistics providers serving fresh meal kit delivery.
Australia
CrossFit affiliates in Sydney and Melbourne drive demand for collagen-infused beverages and shelf-stable protein puffs. TGA oversight of therapeutic claims influences how brands position products for metabolic health applications. Queensland and New South Wales concentrate regenerative agriculture operations supplying certified organic inputs.
Paleo Food Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans vertically integrated ranching operations, condiment-focused portfolios built on single-origin oils, and small-batch snack manufacturers. Three archetypes dominate: regenerative supply chain integrators, clean-label formulation specialists, and direct-to-consumer logistics operators. Competitive moves concentrate on strategic partnerships with functional medicine networks and capacity expansion in precision fermentation infrastructure.
Within the regenerative supply chain tier, EPIC Provisions and Steve's PaleoGoods exemplify archetypes built on producer relationships and small-batch production respectively. Primal Kitchen occupies a position among condiment-focused specialists leveraging avocado-oil-based formulations. These three entities anchor the competitive structure while representing distinct strategic vectors: upstream supply control, artisanal scale, and clean-label portfolio breadth.
| Leading Market Players |
|---|
| EPIC Provisions |
| Caveman Foods |
| Paleo Treats Inc. |
| Primal Kitchen |
| The Paleo Foods Co. |
| Blue Mountain Organics |
| Steve's PaleoGoods |
| Paleo Baking Company |
| Kevin's Natural Foods |
| Others |
Supply Flow & Price Mechanics
Undercapacity in precision fermentation bioreactors across Bavaria and the Netherlands drives supplier pricing power while compressing margin capture for downstream paleo protein brands negotiating offtake terms.
Pricing Analysis
Cost-plus contracts indexed to grass-fed beef futures and organic avocado oil spot markets dominate procurement between regenerative ranchers and condiment manufacturers. Three-tier pricing structure across premium certified-paleo, standard clean-label, and economy conventional tiers separates EPIC Provisions from Primal Kitchen from private-label alternatives. Pricing pressure stems from Mexican harvest volatility and California water stress compressing avocado oil input stability. Subscription-based meal kit buyers exhibit lowest price sensitivity due to locked twelve-month protein contracts, while conventional supermarket shoppers in Florida and Arizona drive volume through promotional elasticity.
Supply Chain Analysis
Supply-chain finance facilities extended by specialty retailers in California and New York allow mid-tier brands to bridge sixty-to-ninety-day payment gaps with regenerative ranchers in Montana and Wyoming. Geographic supply concentration centers on the United States for grass-fed beef and bison, Mexico and California for avocado oil, and Southeast Asia for coconut derivatives and collagen peptides. Raw material dependencies include pasture-raised proteins, single-origin cooking oils, and marine collagen isolates. Single-source vulnerability in Mexican avocado harvests creates margin spike exposure during drought cycles. Distribution runs through direct-to-consumer cold-chain networks in Texas and Colorado urban clusters, with secondary flow through natural channel specialty stores enforcing clean-label verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paleo food procurement is shifting toward platform-economics dynamics as subscription aggregators integrate regenerative rancher APIs with consumer preference engines, creating interoperability lock-in between supply and demand sides.
For Market Incumbents: Build regenerative supply chain moats through exclusive twelve-month protein offtake agreements with Montana and Wyoming ranchers, locking out competitors from grass-fed beef inputs. EPIC Provisions demonstrates upstream control through supply chain relationships that secure priority allocation during drought-constrained seasons. Defensive certification investment in USDA organic and Certified Paleo stacking protects shelf placement against clean-label verification mandates from specialty retailers. Capacity addition in precision fermentation infrastructure insulates against bioprocess engineering talent scarcity threatening scale-up timelines. For New Entrants and Emerging Players: Medically prescribed dietary interventions in Arizona and Florida functional medicine networks represent the most penetrable entry point, bypassing crowded conventional grocery slotting fee structures. Airport and hospital retail channels for shelf-stable protein puffs and collagen-infused beverages offer grab-and-go placement without traditional reset negotiations. Precision fermentation equipment repurposing from pharmaceutical and biofuel sectors enables capital-efficient market entry with reduced bioreactor construction timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation protein production as pharmaceutical infrastructure migrates into food-grade applications. Long-term viability over the coming decade hinges on brands controlling regenerative sourcing protocols rather than formulation IP alone. Acquisition targets should display captive relationships with pasture-raised ranchers and demonstrated cold-chain logistics density in Colorado or Texas. The signal to watch is FDA finalization of "healthy" label definitions reshaping shelf placement algorithms and insurance reimbursement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Rancher Partnership | Exclusive offtake agreements with Montana and Wyoming operations lock in grass-fed protein supply during drought cycles. |
| Precision Fermentation Scale-Up | Bioreactor capacity expansion in Bavaria and the Netherlands achieves texture parity for cell-cultured meat alternatives. |
| Direct-to-Consumer Platform Launch | Subscription logistics in Austin and Denver urban clusters capture customer lifetime value through data ownership. |
| Clean-Label Certification Investment | USDA organic and Certified Paleo stacking secures placement in California and New York specialty retail resets. |
| Medically Prescribed Channel Development | Functional medicine practitioner networks in Arizona and Florida create institutional procurement through insurance pilots. |
Methodological Framework
Initial hypotheses were tested against primary input from brand managers at paleo food manufacturers, category buyers at specialty retailers, supply planners at regenerative ranching cooperatives, and functional medicine practitioners prescribing dietary protocols, then refined through secondary validation. Primary interviews combined with FDA guidance documents, USDA organic certification databases, SEC filings from publicly traded parent companies, and Nielsen retail audit data covering natural channel placement. Bottom-up demand modeling across product type, distribution channel, and customer type segments triangulated against top-down macroeconomic indicators.
Demand-supply balance modeling anchored projections across the analysis window, with volume and value outputs reflecting segmentation across product type, distribution channel, customer application intensity, and packaging sustainability tier. CAGRs were derived from installed base growth rates and replacement cycle analysis rather than simple trend extrapolation. Industry-specific forecast inputs included grass-fed beef supply elasticity, avocado oil harvest volatility coefficients, and cold-chain logistics penetration curves in Texas and Colorado urban clusters.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, freight and logistics costs, or drought severity in pasture-raised regions would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement posture on "natural" claims and precision fermentation approval timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Seaweed Protein Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Artificial Meat Market