
 Venezuela Oil and Gas Market | 2026-2036
Venezuela Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Venezuela Oil and Gas Market Analytics
Petroleum engineering expertise is collapsing across the Venezuelan upstream sector after a decade of emigration and underinvestment in technical training. Petróleos de Venezuela leverages its remaining operational infrastructure to maintain baseline production from legacy fields. Chevron anchors its position through limited joint venture operations permitted under specific U.S. Treasury licenses. Eni competes by navigating European regulatory frameworks to sustain its contractual relationships in offshore gas blocks.
Venezuela oil and gas encompasses the exploration, extraction, refining, and distribution of hydrocarbon resources, primarily extra-heavy crude with API gravities below 10 degrees requiring dilution or upgrading for pipeline transport and commercial use. The sector serves power generation, industrial feedstock, and export markets through integrated upstream-to-downstream systems. Crude oil output dominates current revenue composition, though natural gas development through offshore Perla field partnerships offers structural diversification. Enhanced oil recovery technology adoption in the Orinoco Belt represents the fastest-growing capability investment, while conventional drilling maintains mature basin operations. Petrochemicals processing remains constrained by feedstock supply reliability and equipment degradation.
Venezuela's hydrocarbon sector operates under the oversight of the national hydrocarbons regulator and the Ministry of Petroleum, with foreign operators subject to joint venture structures mandating majority state control. U.S. OFAC sanctions programs restrict dollar-denominated transactions, technology transfers, and secondary market trading, forcing participants toward barter arrangements and non-U.S. financial channels. Stakeholders must monitor the durability of any sanctions relaxation mechanisms and the operational viability of joint venture governance structures before committing long-dated capital to field rehabilitation programs.
Market Dynamics
Sanctions relief protocols under periodic OFAC general licenses are reshaping capital access for upstream operators in the Venezuela oil and gas sector, creating intermittent windows for joint venture rehabilitation while leaving long-term investment planning exposed to policy reversal risk.
Growth Catalysts
- Caribbean Power Generation Demand:Utilities across the Caribbean basin represent the primary demand pull for Venezuelan hydrocarbon exports, with heavy crude purchases from the Orinoco Belt serving baseload electricity needs.
- Orinoco Belt Joint Ventures:Partnership structures targeting mature field rehabilitation are unlocking incremental production capacity through enhanced oil recovery technology deployment.
- European Regulatory Navigation:Eni and other operators leverage European Union frameworks to sustain contractual relationships in offshore gas blocks, maintaining operational continuity despite trans-Atlantic sanctions divergence.
Market Restraints
- Diluent Supply Volatility:Extra-heavy crude with API gravities below 10 degrees requires naphtha or light crude dilution for pipeline transport, and sourcing this input remains constrained by secondary sanctions risk.
- Technical Expertise Collapse:A decade of petroleum engineering emigration and underinvestment in technical training has eroded the skilled workforce needed for complex upstream operations.
- OFAC Transaction Restrictions:U.S. Treasury sanctions programs prohibit dollar-denominated transactions and technology transfers, forcing operators toward barter arrangements with limited financial flexibility.
Strategic Opportunities
- Perla Field Gas Development:Offshore natural gas partnerships offer structural revenue diversification beyond crude oil dependence, with the Perla field representing the most advanced gas production infrastructure.
- Enhanced Recovery Technology Convergence:Thermal and chemical EOR methods combined with digital reservoir monitoring create pathways to rehabilitate mature Orinoco Belt fields previously written down.
- Non-U.S. Financial Channel Expansion:Banking relationships through Chinese and Russian institutions provide alternative settlement mechanisms during sanctions relief windows.
Industry Challenges
- Petroleum Engineering Talent Gap:The exodus of experienced geoscientists and drilling specialists to Colombia, Mexico, and Middle Eastern operators has hollowed out operational decision-making capacity.
- Equipment Degradation and Spare Parts Scarcity:Decades of underinvestment in maintenance and the inability to source OEM components have left refineries and upgraders operating below design specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venezuela Oil and Gas Market |
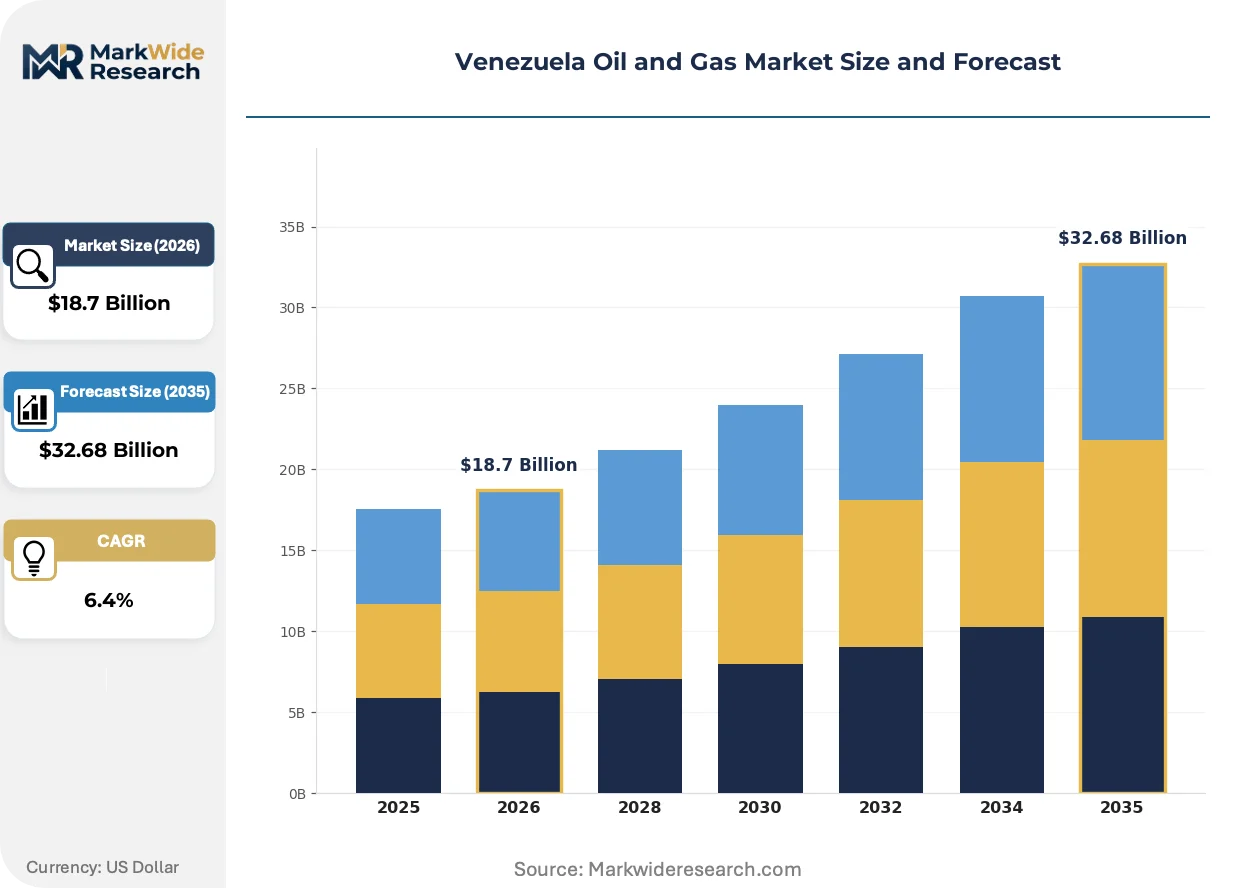
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Liquefied Natural Gas, Petrochemicals End User: Power Generation, Industrial Sector, Transportation, Residential Technology: Exploration, Drilling, Refining, Enhanced Oil Recovery Distribution Channel: Direct Sales, Wholesale, Retail, Export |
| Companies Covered | Petróleos de Venezuela, Chevron, Repsol, Eni, ExxonMobil, Phillips 66, Vitol, Occidental Petroleum, ConocoPhillips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venezuela Oil and Gas Market Evolving Landscape
Technology adoption in Venezuelan hydrocarbon operations is accelerating around enhanced recovery methods and alternative financing structures, driven by the imperative to extract value from depleted assets while circumventing conventional capital constraints.
Thermal enhanced oil recovery using steam-assisted gravity drainage is decomposing the technical barriers to Orinoco Belt heavy crude commercialization. Joint venture operators are deploying SAGD pilots at accelerating pace where diluent shortages constrain conventional production. This thermal approach is decomposing the historical dependence on imported naphtha diluents, enabling standalone field economics.
OFAC general license frameworks are creating episodic regulatory windows for limited U.S. operator participation. Chevron's specific Treasury license demonstrates how sanctioned entities can maintain operational toeholds during political transitions. Upstream joint ventures with minority foreign participation are most affected, structuring governance around license expiration contingencies.
Caribbean utility procurement patterns are rotating toward spot-market flexibility and away from long-term supply contracts. Power generators in the Dominican Republic and Jamaica now favor short-tenor purchases indexed to regional fuel oil benchmarks. This demand-side shift is most visible in the Eastern Caribbean, where independent power producers prioritize working capital preservation over volume commitments.
Venezuela Oil and Gas Market Segmentation
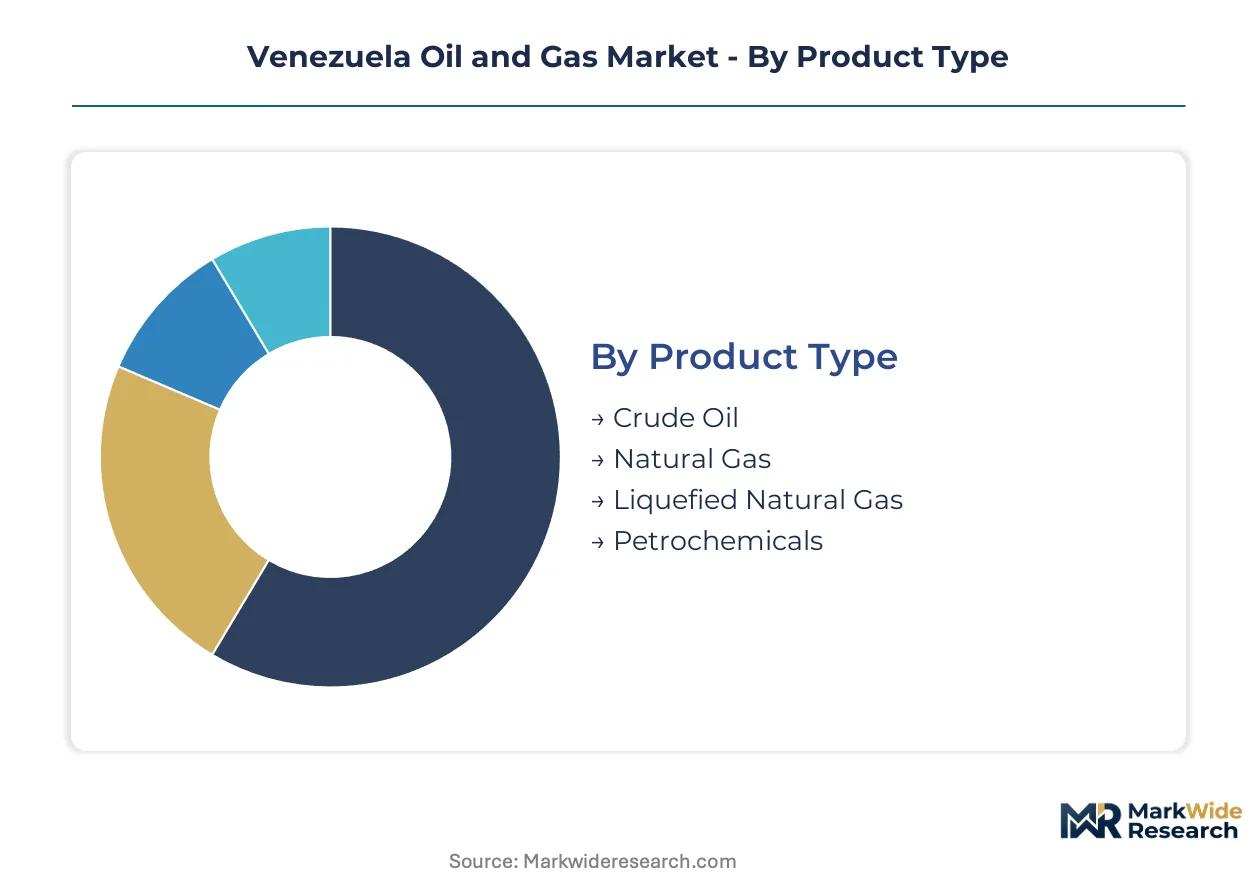
Venezuela's hydrocarbon segmentation reveals stark divides between domestic consumption patterns and export-dependent revenue streams. Product type and distribution channel splits illuminate how sanctions reshape commercial flows, while end-user and technology segments expose infrastructure bottlenecks.
Product Type:
Crude oil dominates export-led revenue, while natural gas and petrochemicals serve primarily domestic and regional markets with distinct regulatory exposure.
- Crude Oil:Extra-heavy Orinoco Belt grades below 10 degrees API require dilution or upgrading for pipeline transport. Caribbean power utilities in the Dominican Republic and Jamaica absorb the heaviest export volumes, though diluent supply volatility constrains production scheduling.
- Natural Gas:Offshore Perla field production and associated gas from mature oil fields feed domestic power generation and industrial feedstock needs. Eni-operated offshore blocks sustain the only material gas export relationships to regional Caribbean markets.
- Liquefied Natural Gas:Minimal operational capacity exists; existing LNG infrastructure remains idled due to feedstock constraints and sanctions-related equipment access limitations.
- Petrochemicals:Methanol, ammonia, and urea production at Morón and El Tablazo complexes serves agricultural and industrial demand within Venezuela and limited regional offtake.
Crude oil holds the largest share; momentum sits with natural gas as offshore partnerships advance Perla field expansion.
End User:
Power generation commands the steepest demand concentration, with industrial and transportation segments exhibiting divergent recovery trajectories post-sanctions relief.
- Power Generation:Domestic grid stabilization and Caribbean utility baseload contracts absorb heavy fuel oil and diluted crude streams. State utility Corpoelec struggles with payment reliability, forcing producers toward barter arrangements.
- Industrial Sector:Steel, aluminum, and chemical manufacturers consume natural gas and naphtha for process heat and feedstock. Operational rates remain depressed by equipment degradation and spare parts scarcity.
- Transportation:Refined product demand concentrates in gasoline and diesel for vehicle fleets, with supply rationing common due to refinery underperformance at Cardón and Amuay complexes.
- Residential:LPG for cooking and heating dominates household energy consumption, with distribution constrained by pipeline integrity failures and cylinder logistics bottlenecks.
Power generation anchors volume commitments; industrial sector recovery is expanding most quickly as joint ventures rehabilitate gas processing infrastructure.
Technology:
Technology segmentation tracks the shift from conventional extraction toward enhanced recovery methods as mature basin depletion accelerates and skilled workforce availability contracts.
- Exploration:Seismic surveying and greenfield drilling have collapsed to minimal levels across the Maracaibo Basin and eastern Venezuela. Capital constraints and sanctions-related equipment prohibitions freeze frontier acreage evaluation.
- Drilling:Conventional vertical and directional drilling maintains legacy field output in Lake Maracaibo and western concessions. Rig availability has cratered; remaining operational units suffer from maintenance backlog and crew inexperience.
- Refining:Downstream processing at Paraguana Refining Center operates below design capacity due to catalyst supply interruptions and corrosion damage. Upgrader complexes in the Orinoco Belt face similar degradation.
- Enhanced Oil Recovery:Thermal methods including steam-assisted gravity drainage and cyclic steam stimulation target Orinoco Belt heavy crude. Joint venture pilots with Chevron demonstrate standalone economics without diluent dependence.
Drilling retains the largest installed base; enhanced oil recovery commands the steepest capability investment trajectory as thermal methods displace diluent-intensive production.
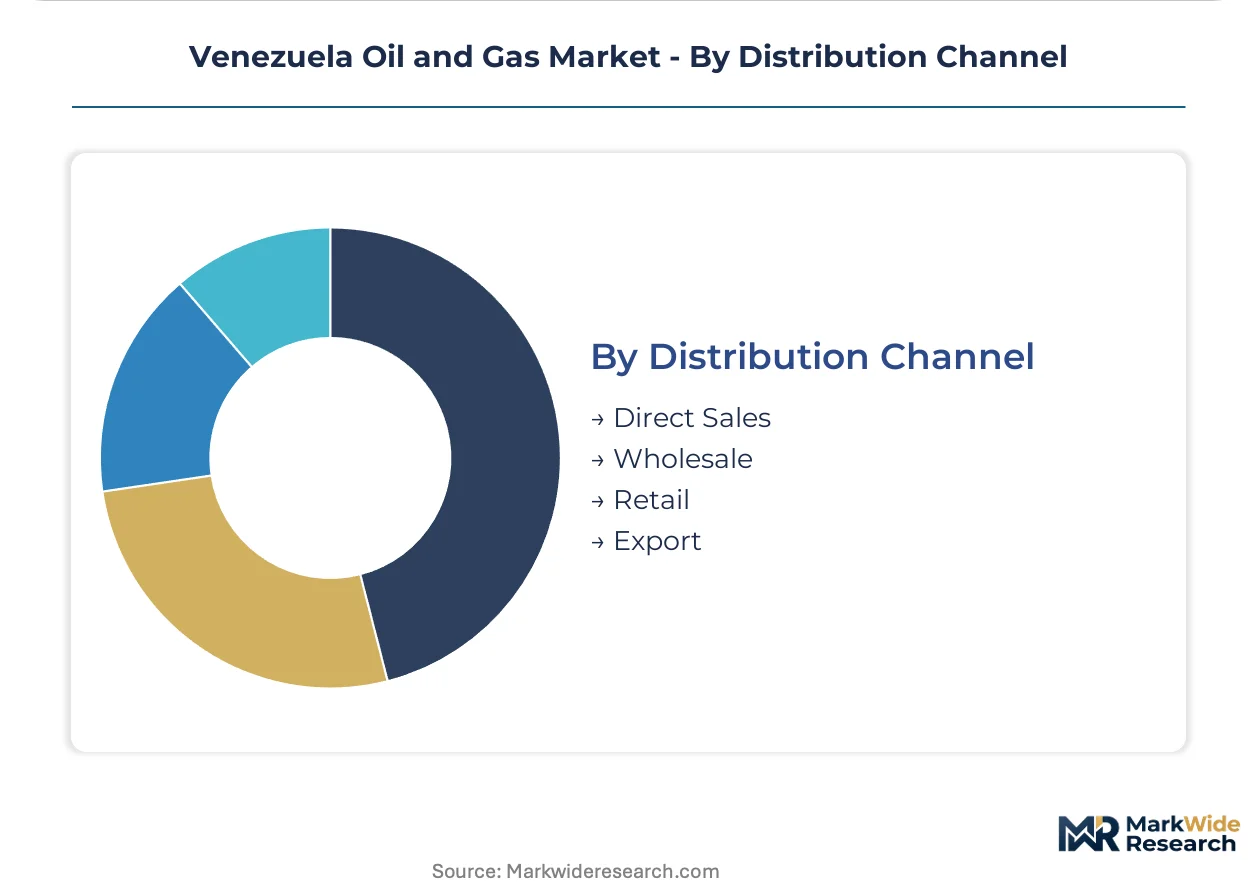
Distribution Channel:
Channel structure reflects sanctions fragmentation, with direct sales and export flows dominating value capture while retail and wholesale networks atrophy domestically.
- Direct Sales:State-to-state crude supply agreements and joint venture offtake contracts bypass conventional trading infrastructure. Chinese and Russian banking channels settle transactions outside dollar denomination.
- Wholesale:Regional fuel oil and diesel distributors in the Caribbean basin source through spot-market arrangements rather than term contracts. Working capital constraints favor short-tenor purchases indexed to regional benchmarks.
- Retail:Domestic gasoline and LPG distribution through PDVSA service stations operates under price controls and rationing protocols. Smuggling to Colombia erodes official channel volumes.
- Export:Maritime crude liftings to India, China, and select European refiners constitute the primary revenue channel. OFAC general license windows periodically restore limited U.S. Gulf Coast access.
Export channels concentrate revenue generation; wholesale distribution is gaining share fastest as Caribbean utilities pivot toward spot-market flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caribbean power utilities consume Venezuelan heavy crude for baseload electricity, while Asian refiners process diluted Orinoco Belt grades for asphalt and fuel oil. European gas operators maintain offshore partnerships despite trans-Atlantic sanctions divergence.
Dominican Republic
State utility Corporación Dominicana de Empresas Eléctricas Estatales purchases fuel oil under short-tenor spot contracts indexed to Caribbean benchmarks. The country's national energy regulator oversees import licensing without OFAC alignment requirements. Santo Domingo anchors regional procurement as independent power producers prioritize working capital flexibility over term commitments.
China
Refiners at Shandong independent processing hubs absorb heavy crude cargoes through non-dollar settlement channels. The Ministry of Commerce administers import quotas through state trading enterprises rather than private license frameworks. Qingdao port infrastructure handles the majority of Venezuelan maritime liftings with dedicated storage for high-sulfur grades.
India
Reliance Industries and state refiners process diluted crude for asphalt and vacuum gasoil production. The Directorate General of Hydrocarbons monitors import diversification without sanctions enforcement jurisdiction. Jamnagar refining complex maintains technical capability for extra-heavy feedstock processing despite intermittent supply interruptions.
Italy
Eni navigates European Union regulatory frameworks to sustain contractual relationships in offshore gas blocks. The Ministry of Economic Development licenses gas field operations without automatic OFAC compliance obligations. Ravenna operational headquarters coordinates Perla field maintenance and Caribbean gas offtake negotiations.
United States
Gulf Coast refiners access limited Venezuelan crude through specific OFAC general license windows for Chevron joint venture offtake. The Treasury Department's Office of Foreign Assets Control structures periodic regulatory relief with expiration contingencies. Houston trading desks manage license-bound cargo scheduling and diluent supply logistics for Orinoco Belt rehabilitation.
Venezuela Oil and Gas Market Competitive Landscape
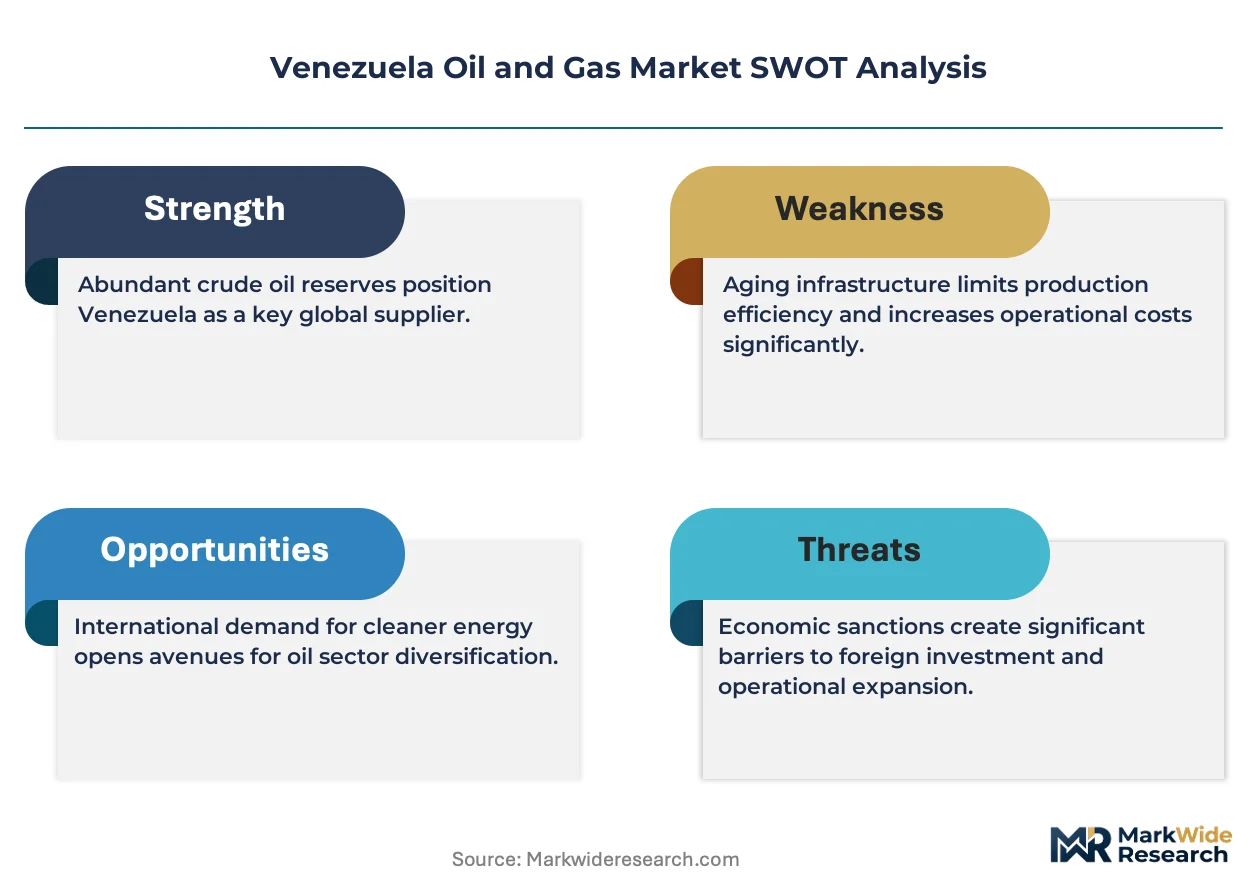
A small set of integrated leaders sits above a broader specialist tier in Venezuela's hydrocarbon sector. State-controlled upstream operators maintain majority positions in all joint venture structures, while international oil companies occupy minority participation roles under license constraints. Strategic archetypes divide between sanctions-adaptive traders, technology-limited field operators, and regulatory-navigating gas specialists. Competitive positioning hinges on OFAC license durability and non-U.S. financial channel access rather than conventional reserve scale or operational efficiency metrics.
Among U.S.-based operators, Chevron Corporation and Occidental Petroleum exemplify the sanctions-adaptive archetype through specific Treasury license holdings. Petróleos de Venezuela anchors the state-controlled tier as the mandatory majority partner in all upstream joint ventures. Eni represents European regulatory navigation capabilities through sustained offshore gas block operations. These three entities occupy distinct competitive positions shaped by geographic regulatory exposure rather than interchangeable operational scale.
| Leading Market Players |
|---|
| Petróleos de Venezuela |
| Chevron |
| Repsol |
| Eni |
| ExxonMobil |
| Phillips 66 |
| Vitol |
| Occidental Petroleum |
| ConocoPhillips |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Caribbean utilities and Orinoco Belt joint ventures lock in both diluent supply access and heavy crude price visibility, insulating producers from spot-market volatility while binding buyers to minimum volume commitments regardless of regional fuel oil benchmark fluctuations.
Pricing Analysis
Spot-market arrangements indexed to Caribbean fuel oil benchmarks dominate commercial flows, with price differentiation driven by crude API gravity and diluent blending ratios. Power generators in the Dominican Republic and Jamaica exhibit the steepest price sensitivity, prioritizing working capital flexibility over term commitments. Cost compression in heavy crude lifts is intensifying because naphtha diluent sourcing remains exposed to secondary sanctions risk, forcing buyers toward shorter-tenor purchases.
Supply Chain Analysis
Strategic stockpiling of naphtha diluents at Caribbean transshipment points anchors inventory strategy, with supply concentration in the United States, China, and Russia for critical inputs. Raw material dependencies center on light crude for blending, specialty catalysts for upgraders, and spare parts for refinery maintenance. Single-source vulnerability pervades OEM component sourcing for Orinoco Belt thermal recovery equipment. Distribution runs through maritime liftings to Asian refiners and direct pipeline flows to Caribbean utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Venezuela's hydrocarbon sector functions as a platform economy where joint venture governance structures and OFAC license interoperability determine capital access, with ecosystem shifts toward non-dollar settlement channels creating new network effects for sanctioned-market operators.
For Market Incumbents: Shield operational toeholds by securing multi-year OFAC general license renewals before political transition windows close, and deepen backward integration into diluent supply through Chinese banking channel partnerships. The exodus of petroleum engineering talent to Colombian and Mexican operators threatens technical decision-making capacity. Joint venture governance control remains the critical lever for protecting field rehabilitation economics.
For New Entrants and Emerging Players: Service-layer gaps in digital reservoir monitoring and thermal EOR technology deployment present white-space opportunities where incumbent operators under-invest due to capital constraints. The most penetrable segment sits with offshore gas block partnerships in the Perla field, where European regulatory navigation offers shelter from trans-Atlantic sanctions divergence. A go-to-market angle anchored in technology licensing rather than equity participation circumvents majority-state-control mandates.
For Investors and Strategic Acquirers: Capital is best deployed toward sanctions-adaptive trading specialists with established non-U.S. financial channel infrastructure and operational toeholds in Orinoco Belt joint ventures. Long-term viability hinges on durable license frameworks spanning multiple political cycles. The signal to watch as inflection indicator is Chevron's Treasury license renewal pattern, which foreshadows broader regulatory relief windows.
| Strategic Initiative | Industry Significance |
|---|---|
| OFAC License Renewal Campaign | Multi-year Treasury approvals stabilize capital planning for Chevron-operated joint ventures. |
| Thermal EOR Technology Licensing | Steam-assisted gravity drainage pilots reduce diluent dependence for Orinoco Belt producers. |
| Non-Dollar Banking Channel Expansion | Chinese and Russian settlement mechanisms bypass secondary sanctions on crude transactions. |
| Caribbean Spot-Market Pivot | Short-tenor procurement contracts align with Dominican and Jamaican utility working capital constraints. |
| Offshore Gas Partnership Deepening | Perla field expansion through Eni-operated blocks diversifies revenue beyond crude dependence. |
Research Methodology
The analysis maps upstream extraction, midstream logistics, and downstream refining segments, each validated through petroleum engineers, joint venture governance officers, Caribbean utility procurement managers, and OFAC compliance specialists. Primary interviews with field operators and refinery maintenance directors combined with secondary validation against EIA production data, OPEC monthly reports, and Treasury Department license filings. Bottom-up field-level production estimates and top-down regional demand projections underwent cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, technology deployment, end-use sector, and distribution channel, with CAGRs derived from production recovery trajectories and rehabilitation investment cycles. Forecast inputs incorporated sanctions relief probability scenarios and diluent supply elasticity assumptions.
Underlying assumptions cover OFAC license durability and Caribbean power demand stability, with deviation risk concentrated in political transition timelines and secondary sanctions enforcement intensity. Forecasts reflect these conditions with explicit sensitivity ranges. Revision becomes warranted when Treasury Department licensing patterns cross material expansion or contraction thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Shale Shakers Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
South America LNG Bunkering Market