
 United States Renewable Energy Market | 2026-2036
United States Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United States Renewable Energy Market Analytics
Utility procurement is decoupling from traditional baseload contracts as corporate offtakers and data center operators enter direct power purchase agreements. NextEra Energy leverages its vertically integrated development platform to control project timelines from origination through grid connection. First Solar anchors thin-film photovoltaic manufacturing with domestic cadmium telluride supply chains that bypass polysilicon price volatility. Invenergy competes across wind, solar, and storage hybrids with a development pipeline concentrated in ERCOT and MISO interconnection zones.
United States renewable energy encompasses electricity generation from solar, wind, biomass, hydropower, and geothermal resources converted through photovoltaic cells, turbine assemblies, or thermal cycles for grid-connected or distributed delivery. Photovoltaic systems dominate capacity additions with module efficiencies now exceeding twenty-one percent in utility-scale installations, while offshore wind technology remains nascent with floating platform demonstrations planned for Pacific depths. Wind and solar product types capture the bulk of capital deployment, yet energy storage co-location with photovoltaic arrays represents the fastest-expanding margin pool as merchant developers seek to capture peak pricing spreads. Utility-scale deployment leads total megawatts installed, though distributed generation accelerates in states with net metering reforms and commercial rooftop mandates.
The Federal Energy Regulatory Commission shapes market access through interconnection queue reforms and transmission cost allocation rules, while the Internal Revenue Service administers Inflation Reduction Act tax credit monetization pathways that determine project finance structures. State public utility commissions in California, Texas, and New York enforce renewable portfolio standards that mandate procurement timelines for investor-owned utilities. Stakeholders must monitor FERC Order 2023 implementation and state-level permitting preemption battles that will determine whether project completion rates match announced development pipelines.
Market Dynamics
Corporate offtakers are bypassing traditional utility procurement channels through direct power purchase agreements, forcing merchant developers to restructure project finance around tax equity partnerships rather than baseload contracts.
Growth Catalysts
- Inflation Reduction Act Tax Credits:The IRA's production tax credits and investment tax credits reduce levelized cost of energy for utility-scale solar and storage hybrids, accelerating project origination in ERCOT and MISO interconnection zones.
- Data Center Load Growth:Hyperscale operators in Northern Virginia, Phoenix, and Dallas-Fort Worth are contracting renewable capacity years ahead of facility energization, creating firm demand anchors for merchant developers.
- Texas:ERCOT's energy-only market design and minimal interconnection study requirements attract developer interest despite transmission congestion, concentrating wind and solar deployment in the Panhandle and West Texas.
Market Restraints
- Polysilicon Price Volatility:Crystalline silicon module costs fluctuate with Chinese ingot and wafer pricing, compressing developer margins when polysilicon spot markets spike.
- Interconnection Queue Backlog:FERC Order 2023 implementation lags behind project submissions, with cluster study timelines extending beyond thirty-six months in SPP and CAISO zones.
- Transmission Buildout:High-voltage line construction requires state siting approvals and federal permitting under NEPA, delaying renewable energy delivery from remote generation sites to coastal load centers.
Strategic Opportunities
- Offshore Wind:Floating platform demonstrations planned for California and Oregon depths could unlock deep-water capacity factors exceeding fifty percent, displacing onshore wind in Pacific Coast procurement.
- Agrivoltaics:Co-location of photovoltaic arrays with agricultural operations in the Midwest addresses land-use conflicts while generating dual revenue streams for rural landowners.
- Green Hydrogen:The IRA's clean hydrogen production tax credit creates offtake certainty for electrolyzer projects sited near Texas and Gulf Coast wind resources.
Industry Challenges
- Electrical Engineering Talent:Project developers face scarcity of interconnection specialists capable of modeling complex hybrid inverter configurations and battery dispatch optimization.
- Supply Chain Reconfiguration:Domestic content bonus credit requirements under the IRA force module procurement shifts from Southeast Asian assembly to thin-film or US-manufactured alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Renewable Energy Market |
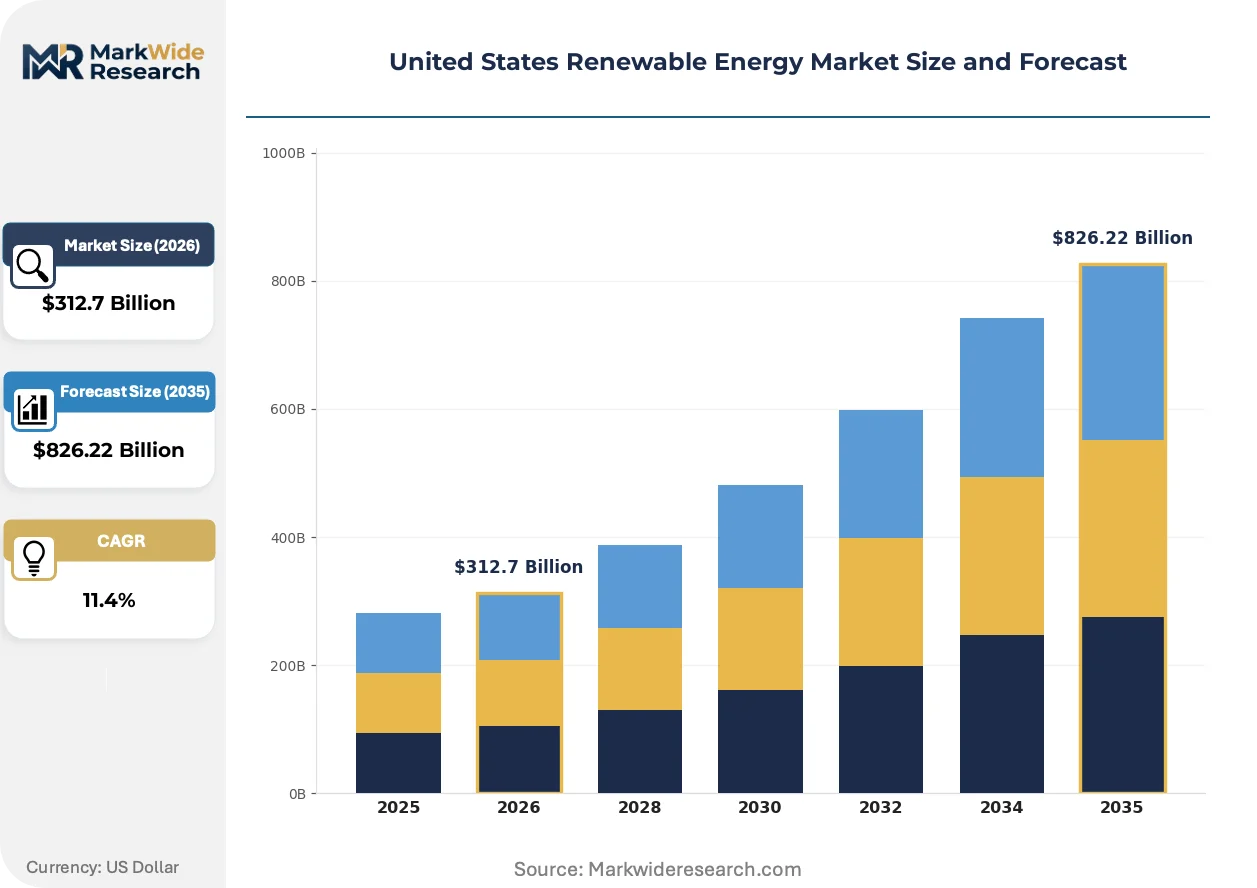
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar, Wind, Biomass, Hydropower Technology: Photovoltaic, Concentrated Solar Power, Offshore Wind, Geothermal End User: Residential, Commercial, Industrial, Government Deployment: Onshore, Offshore, Distributed, Utility-Scale |
| Companies Covered | Apex Clean Energy, LS Power, NextEra Energy, First Solar, Brookfield Renewable Partners, Clearway Energy Group, Cypress Creek Renewables, Recurrent Energy, Invenergy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Renewable Energy Market Evolving Landscape
Battery energy storage systems are converging with solar generation at the project level, enabling merchant operators to capture peak pricing spreads and provide ancillary services to grid operators.
DC-coupled battery architecture is integrating photovoltaic inverters with lithium-ion storage modules at the medium-voltage collection point. Utility-scale developers in Texas and California are deploying this configuration to reduce balance-of-system costs and capture investment tax credit adders. The technology is integrating merchant risk management with grid stability services, compressing developer returns into contracted capacity payments rather than merchant energy sales.
The Internal Revenue Service has clarified partnership flip structures and direct pay election mechanics for municipal utilities under the Inflation Reduction Act. This guidance determines whether tax equity investors or project sponsors monetize production tax credits, reshaping sponsor return thresholds and debt sizing. Rural electric cooperatives in the Midwest are most affected, restructuring procurement to access direct pay rather than traditional tax equity partnerships.
Corporate buyers are compressing contracting timelines from twenty-year power purchase agreements to ten-to-fifteen-year structures with renewal options. This pattern disrupts traditional project finance assumptions around debt tenor and tax equity duration, forcing developers to seek alternative offtake structures. The shift is most visible in data center load growth across Northern Virginia and Phoenix, where hyperscale operators prioritize operational flexibility over cost minimization.
United States Renewable Energy Market Segmentation
Capital allocation across the United States renewable energy market fragments along technology maturity curves and offtake contract structures. Procurement decisions by corporate buyers and electric cooperatives hinge on locational marginal pricing, interconnection queue positions, and tax credit monetization pathways.
Product Type:
Investment committees weight levelized cost of energy against resource availability and permitting timelines when committing capital to generation assets.
- Solar:Photovoltaic systems dominate capacity additions with module efficiencies exceeding twenty-one percent in utility-scale installations. Utility procurement in Texas and California concentrates here as corporate offtakers seek direct power purchase agreements with merchant developers.
- Wind:Turbine assemblies capture capacity factors above thirty-five percent in the Great Plains and Texas Panhandle. ERCOT's energy-only market design attracts developer interest despite transmission congestion limiting delivery to coastal load centers.
- Biomass:Organic matter combustion facilities face feedstock logistics constraints and air quality permitting hurdles.
- Hydropower:Run-of-river and pumped storage installations encounter extended Federal Energy Regulatory Commission licensing timelines.
Volume sits with solar; growth tilts toward wind as interconnection queues clear in MISO and SPP zones.
Technology:
Engineering specifications determine project finance structures and tax credit eligibility under Internal Revenue Service guidance.
- Photovoltaic:Crystalline silicon modules face polysilicon price volatility while thin-film cadmium telluride supply chains bypass Chinese ingot pricing. Domestic content bonus credits under the Inflation Reduction Act favor US-manufactured alternatives.
- Concentrated Solar Power:Thermal storage integration enables dispatchable renewable output for evening peak demand periods. Southwestern states with high direct normal irradiance attract developer interest despite higher capital costs.
- Offshore Wind:Floating platform demonstrations planned for Pacific depths could unlock deep-water capacity factors.
- Geothermal:Binary cycle plants exploit low-to-moderate temperature resources in the Western states.
Photovoltaic captures present deployment; offshore wind holds the steepest expansion trajectory pending Bureau of Ocean Energy Management lease schedules.
End User:
Contract tenor and creditworthiness requirements segment developer origination strategies across customer categories.
- Residential:Rooftop installations accelerate in states with net metering reforms and commercial rooftop mandates. California's NEM 3.0 restructuring compresses export compensation rates.
- Commercial:C&I offtakers prioritize operational flexibility over cost minimization in ten-to-fifteen-year structures with renewal options.
- Industrial:Load growth from data center operators in Northern Virginia and Phoenix creates firm demand anchors.
- Government:Municipal utilities access direct pay election mechanics under Inflation Reduction Act guidance.
Industrial procurement commands project scale; commercial contracting is expanding most quickly as hyperscale operators accelerate renewable matching commitments.
Deployment:
Siting authority and grid connection voltage levels determine development timelines and regulatory exposure.
- Onshore:Land-based wind and solar installations face state permitting preemption battles and local zoning opposition. Texas and Iowa lead megawatts installed.
- Offshore:Atlantic Coast lease areas advance through Bureau of Ocean Energy Management environmental review. Vineyard Wind and South Fork projects anchor initial commercial deployment.
- Distributed:Behind-the-meter generation avoids interconnection queue backlogs but encounters utility standby charge disputes.
- Utility-Scale:Centralized projects dominate capital deployment with battery storage co-location capturing peak pricing spreads.
Utility-scale deployment holds current volume; distributed generation gains share fastest where retail rate structures favor self-consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center load growth concentrates renewable procurement in three distinct US corridors, while state-level interconnection reforms determine project completion rates.
Texas
ERCOT's energy-only market attracts merchant developers with minimal interconnection study requirements, though transmission congestion limits West Texas solar delivery to Dallas-Fort Worth load centers. The Public Utility Commission of Texas oversees interconnection queue reforms that lag behind project submissions. Wind and solar deployment clusters in the Panhandle and Permian Basin where land availability supports gigawatt-scale development.
California
Corporate offtakers in Silicon Valley and Los Angeles Basin drive direct power purchase agreement volumes despite NEM 3.0 restructuring residential export compensation. The California Public Utilities Commission enforces renewable portfolio standards with accelerated procurement timelines for investor-owned utilities. Utility-scale solar with battery co-location dominates the Central Valley and Imperial County where interconnection queues extend thirty-six months.
Midwest
Rural electric cooperatives in Iowa and Illinois restructure procurement to access Inflation Reduction Act direct pay elections rather than traditional tax equity partnerships. The Federal Energy Regulatory Commission shapes MISO interconnection cost allocation rules that determine project finance viability. Wind capacity factors above thirty-five percent concentrate development in the Great Plains corridor from North Dakota through Kansas.
Southeast
Utility-scale solar accelerates in Florida and Georgia where vertically integrated utilities control interconnection timelines through state-regulated integrated resource plans. The North Carolina Utilities Commission and Georgia Public Service Commission enforce renewable procurement mandates with differing compliance mechanisms. Corporate data center expansion in Northern Virginia creates cross-border procurement pressure into Carolinas renewable zones.
Pacific Northwest
Offshore wind lease areas off Oregon and Washington advance through Bureau of Ocean Energy Management environmental review, with floating platform demonstrations planned for deep-water capacity factors exceeding fifty percent. The Bonneville Power Administration transmission access shapes onshore wind and solar dispatch priority. Hydropower-dominated grids in Washington and Oregon create renewable curtailment risk that battery storage developers target for ancillary service contracts.
United States Renewable Energy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue storage hybrid configurations and agrivoltaic land-use models. The vendor base stratifies across three maturity levels: integrated utilities with captive development pipelines, independent power producers reliant on tax equity partnerships, and technology manufacturers controlling module supply chains. Strategic archetypes include vertically integrated developers, merchant project sponsors, and thin-film manufacturers with domestic content advantages. Competitive moves concentrate on interconnection queue positioning and offtake contract tenor compression.
Within the integrated utility tier, NextEra Energy exemplifies vertical control over project timelines from origination through grid connection. First Solar occupies a position as a domestic thin-film manufacturer with supply chains bypassing polysilicon price volatility. Invenergy anchors the independent power producer archetype with development pipelines concentrated in ERCOT and MISO zones. These three entities represent distinct competitive postures: captive infrastructure control, manufacturing supply security, and merchant market agility.
| Leading Market Players |
|---|
| Apex Clean Energy |
| LS Power |
| NextEra Energy |
| First Solar |
| Brookfield Renewable Partners |
| Clearway Energy Group |
| Cypress Creek Renewables |
| Recurrent Energy |
| Invenergy |
| Others |
Value Network & Pricing Analysis
Corporate offtakers and data center operators anchor procurement volumes through long-term power purchase agreements, compressing developer margins into contracted capacity payments rather than merchant energy sales. Pricing power concentrates with vertically integrated developers who control project timelines from origination through grid connection.
Pricing Analysis
Volume concentrates in utility-scale solar and wind projects where thin margins on gigawatt-scale deployments offset development risk, while premium pricing attaches to storage hybrids and offshore wind platforms with higher capital costs and specialized engineering requirements. Price differentiation rests on interconnection queue position and domestic content bonus credit eligibility under IRA guidance, with Texas ERCOT projects commanding lower offtake rates than California CAISO equivalents due to transmission congestion. Cost compression in crystalline silicon modules intensifies because Chinese polysilicon spot market volatility feeds through to developer procurement budgets. Municipal utilities and rural electric cooperatives exhibit highest price sensitivity as direct pay election mechanics reshape their access to tax credit monetization pathways.
Supply Chain Analysis
End-of-life module refurbishment and battery recycling flows remain underdeveloped, constraining circular economy participation as early utility-scale installations reach decommissioning horizons. Manufacturing concentrates in China for crystalline silicon ingots and wafers, in Malaysia and Vietnam for Southeast Asian module assembly, and in the United States for thin-film cadmium telluride production. Raw material dependencies center on polysilicon feedstocks, lithium carbonate for battery storage, and rare earth elements for turbine permanent magnets. Single-source vulnerability in Chinese ingot supply creates tariff exposure under ongoing trade remedy investigations. Distribution runs through EPC contractors and developer procurement teams who negotiate module supply agreements eighteen to twenty-four months ahead of construction mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States renewable energy market sits in a technology-transition phase as DC-coupled battery architecture displaces AC-coupled configurations and floating offshore wind platforms challenge fixed-bottom Atlantic Coast installations.
For Market Incumbents: Hedge against polysilicon price volatility by securing thin-film supply agreements or backward integration into domestic module manufacturing. Reinforce interconnection queue positioning through early-stage site control in ERCOT and MISO zones where cluster study timelines extend beyond thirty-six months. Prioritize storage hybrid development to capture investment tax credit adders and ancillary service revenue streams. For New Entrants and Emerging Players: Capture white-space in agrivoltaic land-use models across Midwest agricultural corridors where dual revenue streams address rural landowner opposition. Target floating offshore wind demonstration projects off Oregon and Washington where Bureau of Ocean Energy Management lease schedules remain open. Pursue green hydrogen offtake agreements with Gulf Coast petrochemical facilities seeking IRA clean hydrogen production tax credit qualification. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent power producers with advanced-stage interconnection queue positions in SPP and CAISO zones where FERC Order 2023 implementation lags behind project submissions. Long-term viability hinges on developer capability to monetize tax credits through partnership flip structures or direct pay elections. Monitor FERC transmission cost allocation rulemakings as inflection indicators for project finance restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Corporate offtakers like Amazon and Google sign direct contracts that bypass traditional utility procurement channels. |
| Capacity Buildout | Texas ERCOT attracts gigawatt-scale wind and solar deployment despite transmission congestion limiting coastal delivery. |
| Vertical Integration into Storage | Developers co-locate lithium-ion batteries with photovoltaic arrays to capture peak pricing spreads and grid services revenue. |
| Technology Licensing | Floating platform demonstrations planned for Pacific depths could unlock capacity factors exceeding fifty percent. |
| Green Certification Program | Domestic content bonus credits under IRA guidance favor thin-film manufacturers with US-based cadmium telluride supply chains. |
Research Methodology
Independent corroboration across Federal Energy Regulatory Commission filings, Energy Information Administration data, and project development databases underwrites the qualitative findings on interconnection queue dynamics and transmission cost allocation. Primary interviews with utility planning officers, independent power producer project developers, EPC contractors, and grid operators combined with secondary validation from SEC filings, IEA reports, and IRA guidance documents. Bottom-up project-level capacity tracking and top-down regional demand modeling triangulate market size estimates.
Rate-of-change decomposition across technology cost curves, policy incentive trajectories, and load growth patterns structures the analytical framework throughout the forecast period. Segmentation dimensions modeled include fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from installed capacity build rates and levelized cost of energy trajectories. Forecast inputs incorporate interconnection queue clearance timelines and corporate renewable procurement commitment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FERC Order 2023 implementation pace and state-level permitting preemption battles. Forecasts reflect documented assumptions around tax credit monetization pathway availability and transmission buildout schedules. Practitioners should monitor Bureau of Ocean Energy Management lease auction results and IRA domestic content bonus credit guidance updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Thailand Renewable Energy Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Solar Floating Pool Lights Market
Renewable Energy
Netherlands Renewable Energy Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
South America Renewable Energy Market