
 North Africa Renewable Energy Market | 2026-2036
North Africa Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
North Africa Renewable Energy Market Analytics
The North Africa renewable energy sector is restructuring around a widening gap between bankable utility-scale projects backed by sovereign guarantees and smaller distributed installations dependent on fragmented local financing. ACWA Power anchors the premium tier through its integrated development model combining Saudi capital with long-term power purchase agreements across Egypt and Morocco. Sun King competes in the off-grid residential segment with pay-as-you-go solar home systems designed for rural households beyond national grid reach. First Solar differentiates through its thin-film photovoltaic technology optimized for high-temperature desert environments prevalent across the region.
North Africa renewable energy encompasses the conversion of solar irradiance, wind kinetic energy, organic matter, and water flow into grid-compatible electricity using photovoltaic panels, horizontal-axis turbines, anaerobic digesters, and run-of-river installations with typical capacity factors ranging from 18% for solar to 35% for onshore wind. Solar Photovoltaic dominates installed capacity due to exceptional direct normal irradiance exceeding 2,200 kWh per square meter annually across the Sahara and Sahel belt. Off-grid Solutions represent the fastest-expanding application category as mini-grid developers target the 15% of regional households lacking centralized electricity access. The Utilities end-user segment captures the deepest margin pools through sovereign-backed procurement tenders with 20-25 year contract tenors.
Egypt's New and Renewable Energy Authority operates under feed-in tariff frameworks approved by the cabinet, while Morocco's Moroccan Agency for Sustainable Energy manages Noor program concessions under law 13-09 enabling private power production. Algeria's Ministry of Energy Transition implements renewable energy auction mechanisms through Sonelgaz subsidiary SKTM to diversify hydrocarbon-dependent generation. Stakeholders must monitor auction price floors and currency convertibility guarantees as sovereign fiscal pressures reshape offtake risk profiles across the Maghreb.
Market Dynamics
North Africa's renewable energy sector is restructuring around sovereign-backed procurement frameworks that concentrate capital in utility-scale solar while fragmenting financing for distributed generation. Morocco's green hydrogen ambitions and Egypt's feed-in tariff revisions are redirecting investment flows toward bankable projects with long-term power purchase agreements.
Growth Catalysts
- Green hydrogen frameworks:Morocco's national hydrogen strategy mandates electrolyzer capacity additions powered by dedicated solar and wind assets, creating anchor demand for renewable generation.
- Feed-in tariff mechanisms:Egypt's revised tariff structures under the New and Renewable Energy Authority provide price certainty for independent power producers developing photovoltaic complexes.
- Desert irradiance concentration:Direct normal irradiance exceeding 2,200 kWh per square meter annually across the Sahara belt delivers capacity factors unmatched in European markets.
Market Restraints
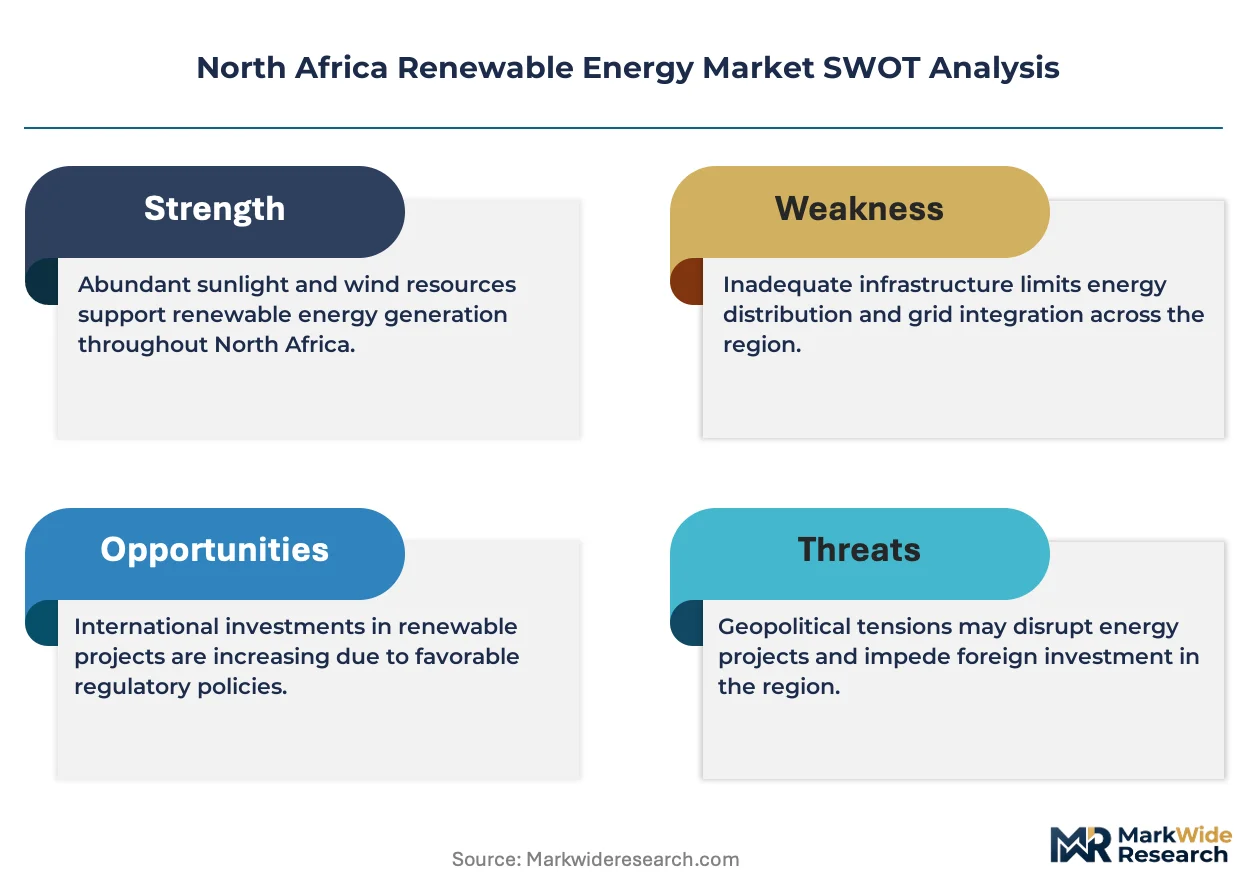
- Currency convertibility risk:Egyptian pound volatility and Algerian dinar non-convertibility complicate foreign debt servicing for equipment imports denominated in euros or dollars.
- Grid interconnection limitations:Transmission infrastructure bottlenecks between Maghreb countries restrict cross-border electricity trade and stranded asset monetization.
- Natural gas price suppression:Algeria's domestically priced hydrocarbon reserves undercut renewable levelized cost of electricity in dispatch order.
Strategic Opportunities
- Mini-grid penetration in rural Sahel:Niger and Chad's unelectrified households represent addressable demand for pay-as-you-go solar home systems beyond national grid reach.
- Concentrated solar power hybridization:Molten salt thermal storage integration with photovoltaic plants enables dispatchable renewable supply for evening peak demand.
- European renewable energy certificate imports:EU Green Deal carbon border adjustments create premium offtake markets for North African green electrons via subsea interconnectors.
Industry Challenges
- Electromechanical technician scarcity:Local vocational training capacity lags behind utility-scale project commissioning schedules, forcing reliance on expatriate commissioning crews.
- Land tenure formalization delays:Renewable energy concessions require navigating customary land rights and state land classification ambiguities that extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Africa Renewable Energy Market |
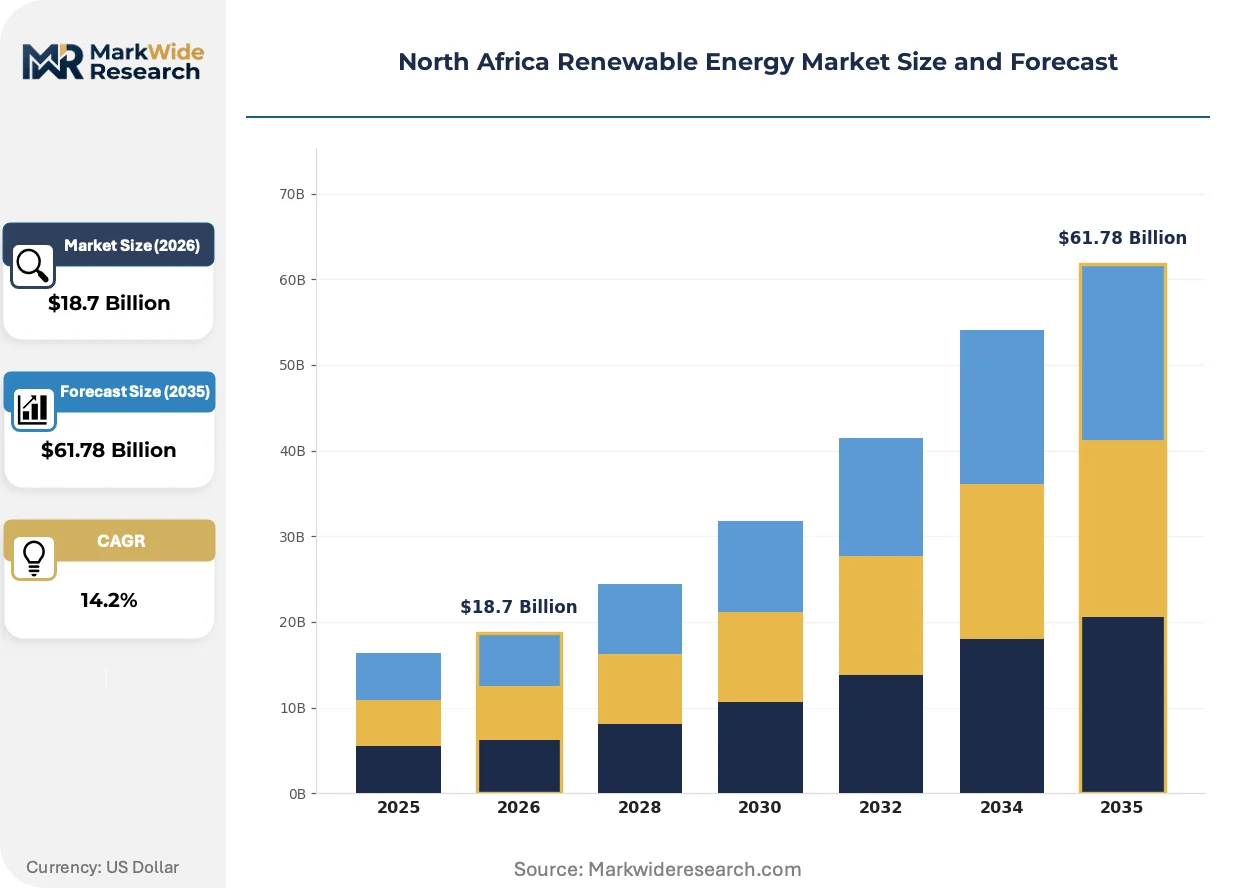
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Photovoltaic, Wind Turbines, Biomass, Hydropower Application: Power Generation, Off-grid Solutions, Urban Development, Industrial Use End User: Utilities, Corporates, Residential, Government Service Type: Installation, Maintenance, Consulting, Financing |
| Companies Covered | Daystar Power, Sun King, ACWA Power, Sungrow Power Supply, GE Vernova, Globeleq, Arnergy, First Solar, Lekela Power, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Africa Renewable Energy Market Evolving Landscape
Technology convergence and procurement model evolution are compressing development cycles across North Africa's renewable energy pipeline. Distributed generation architectures and digital asset management platforms are displacing centralized engineering approaches that dominated early project phases.
Containerized photovoltaic-plus-storage systems are decentralizing rural electrification delivery in Egypt's Western Desert and Morocco's Anti-Atlas regions. Agricultural cooperatives and mining operators are adopting these modular configurations to bypass grid connection queues. The shift is compressing traditional utility-scale development timelines from years to months for commercial and industrial offtakers.
Algeria's Ministry of Energy Transition is implementing competitive auction mechanisms through SKTM to replace administratively set feed-in tariffs. The policy restructure is forcing developers to optimize balance-of-system costs and embrace merchant price exposure. Domestic content requirements embedded in tender criteria are redirecting capital toward local manufacturing partnerships.
Industrial offtakers in Tunisia and Morocco are negotiating synthetic power purchase agreements that blend physical renewable supply with financial hedging instruments. The contractual innovation is fragmenting traditional utility monopoly structures and enabling direct generator-consumer relationships. Cement and phosphate processing facilities with 24-hour load profiles are driving demand for hybrid solar-wind-storage configurations.
North Africa Renewable Energy Market Segmentation
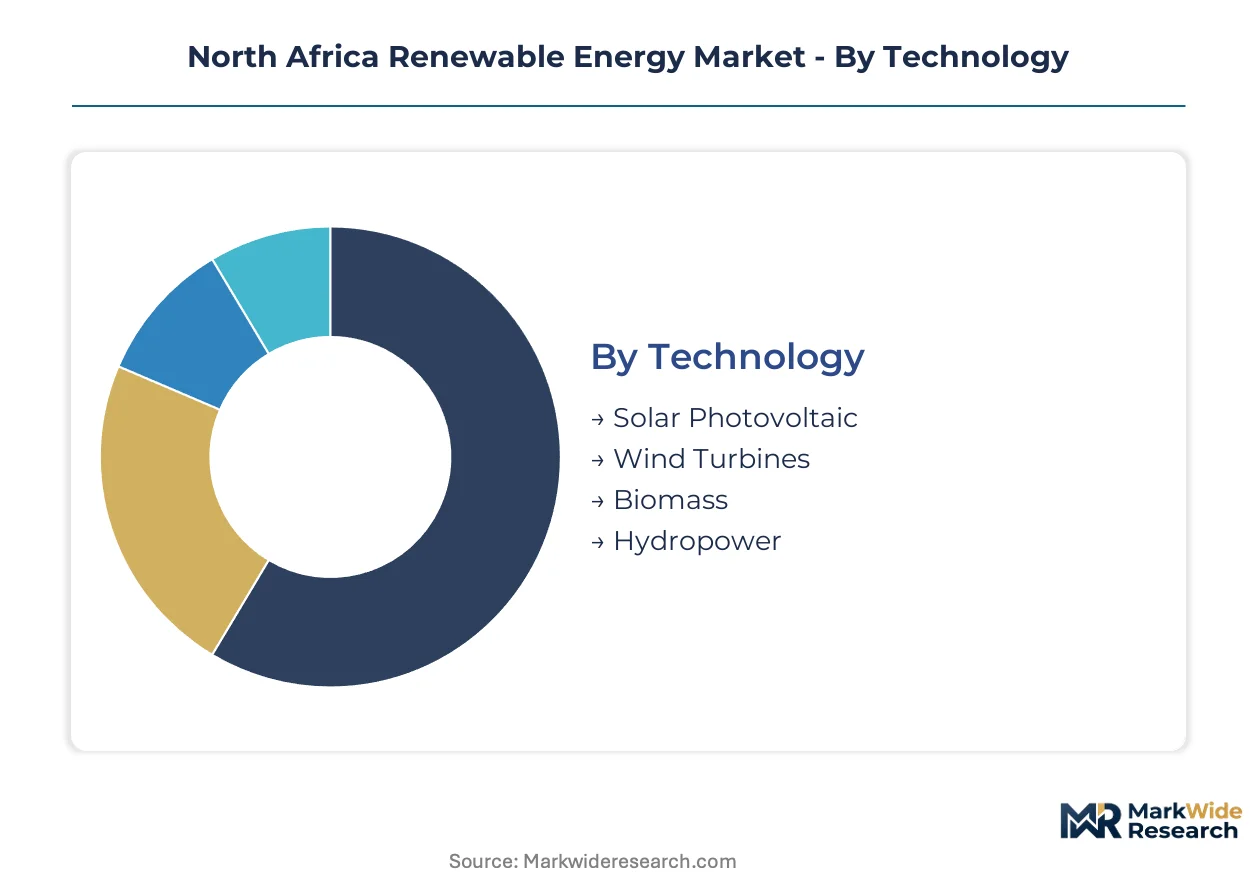
Technology selection in North Africa hinges on irradiance profiles and grid integration costs rather than equipment price alone. Application patterns diverge sharply between sovereign-backed utility procurement and fragmented rural electrification. End-user economics vary by access to long-term power purchase agreements and currency hedging instruments.
Technology:
Capital efficiency and resource availability determine technology selection across Morocco, Egypt, and Algeria.
- Solar Photovoltaic:Crystalline silicon and thin-film modules convert direct normal irradiance exceeding 2,200 kWh per square meter annually into grid-compatible electricity. Egyptian independent power producers concentrate procurement at Benban and Kom Ombo complexes where land concessions and sovereign guarantees de-risk deployment.
- Wind Turbines:Horizontal-axis turbines with hub heights above 80 meters capture Saharan trade winds and coastal breezes across Morocco's Tarfaya and Tangier regions. Morocco's Moroccan Agency for Sustainable Energy channels international competitive bidding toward wind-solar hybrid configurations that firm output variability.
- Biomass:Anaerobic digesters and combustion systems process agricultural residues from Egypt's Nile Delta sugarcane and Morocco's olive oil processing waste.
- Hydropower:Run-of-river installations exploit Morocco's Atlas Mountain watersheds and Algeria's northern river systems with minimal reservoir displacement.
Solar Photovoltaic leads on scale; Wind Turbines lead on momentum as green hydrogen electrolyzer demand anchors new capacity.
Application:
Project scale and offtaker creditworthiness fragment procurement patterns across the Maghreb.
- Power Generation:Utility-scale photovoltaic and concentrated solar power plants feed national grids under 20-25 year power purchase agreements. Morocco's Noor Ouarzazate complex and Egypt's Benban solar park concentrate institutional capital in bankable sovereign-backed projects with multilateral guarantee structures.
- Off-grid Solutions:Pay-as-you-go solar home systems and containerized mini-grids serve unelectrified households beyond centralized infrastructure reach. Niger and Chad's Sahel belt households drive pay-as-you-go solar home system penetration where grid extension remains economically prohibitive.
- Urban Development:Building-integrated photovoltaics and municipal solar streetlight programs reduce distribution losses in dense Moroccan and Tunisian cities.
- Industrial Use:Captive renewable generation for phosphate processing, cement manufacturing, and desalination facilities bypasses utility intermediaries.
Power Generation commands deployment volume; Off-grid Solutions climbs the fastest as rural electrification gaps persist.
End User:
Contract tenor and currency denomination differentiate end-user economics.
- Utilities:State-owned transmission companies procure through competitive auctions and feed-in tariff frameworks. Egypt's New and Renewable Energy Authority and Algeria's SKTM tender long-term capacity with sovereign credit backing.
- Corporates:Industrial offtakers negotiate synthetic power purchase agreements blending physical supply with financial hedges. Moroccan phosphate and cement processors drive demand for 24-hour renewable supply through hybrid solar-wind-storage configurations.
- Residential:Grid-connected rooftop solar and off-grid solar home systems serve income-segmented households.
- Government:Public buildings and military installations deploy captive generation to reduce fiscal exposure to fuel import volatility.
Utilities anchor procurement scale; Corporates gain share fastest as direct generator-consumer contracting fragments traditional monopoly structures.
Service Type:
Local capability gaps reshape service value capture between international and domestic providers.
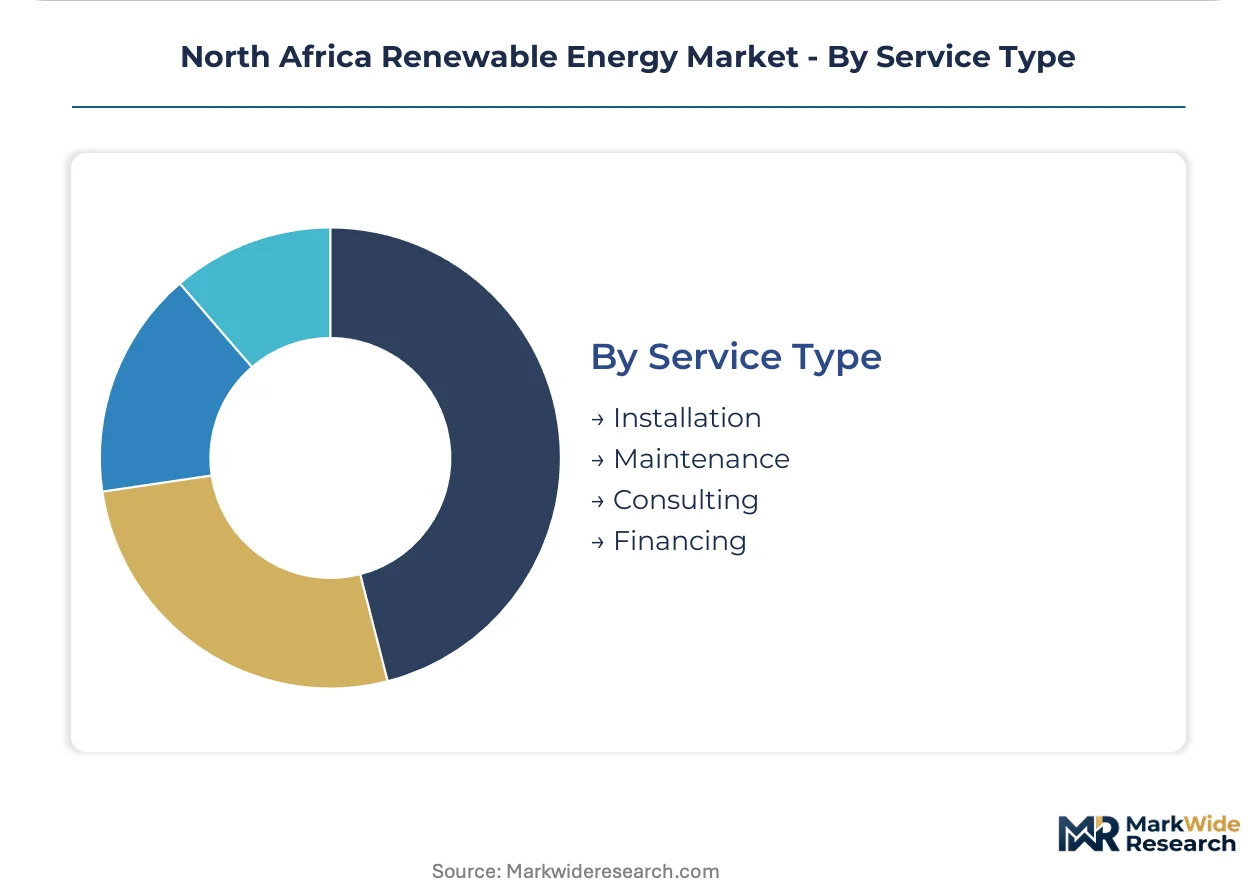
- Installation:Engineering, procurement, and construction contracts for utility-scale projects. ACWA Power and European contractors dominate Morocco and Egypt's premium tier with integrated development models.
- Maintenance:Operations and service agreements covering module cleaning, inverter replacement, and turbine gearbox refurbishment. Electromechanical technician scarcity across Algeria and Tunisia forces reliance on expatriate crews for commissioning and major overhauls.
- Consulting:Feasibility studies, grid integration assessments, and regulatory navigation for greenfield developments.
- Financing:Project debt, currency hedging instruments, and development equity structuring. Egyptian pound volatility and Algerian dinar non-convertibility complicate foreign debt servicing for euro- and dollar-denominated equipment imports.
Installation captures the deepest value pools; Financing represents the fastest-expanding service category as currency risk management demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electromechanical technicians and project finance specialists concentrate development activity across Morocco, Egypt, and Algeria's utility-scale corridors. Workforce mobility between these markets accelerates technology transfer and standardizes procurement practices.
Morocco
Green hydrogen electrolyzer demand and concentrated solar power expansion drive capacity additions. The Moroccan Agency for Sustainable Energy administers Noor program concessions under law 13-09 enabling private power production. Ouarzazate hosts the Noor complex where molten salt thermal storage integration proceeds alongside photovoltaic scaling.
Egypt
Feed-in tariff revisions and sovereign-backed procurement tenders attract independent power producers to utility-scale photovoltaic complexes. The New and Renewable Energy Authority operates cabinet-approved tariff frameworks. Benban solar park anchors institutional capital deployment with multilateral guarantee structures covering euro- and dollar-denominated equipment imports.
Algeria
Competitive auction mechanisms replace administratively set tariffs to diversify hydrocarbon-dependent generation. The Ministry of Energy Transition implements renewable energy auctions through Sonelgaz subsidiary SKTM. Northern coastal zones concentrate early procurement where grid infrastructure accommodates variable renewable injection.
Tunisia
Synthetic power purchase agreements enable direct generator-consumer contracting for industrial offtakers. The national utility regulator oversees distributed generation interconnection standards. Phosphate processing and cement manufacturing clusters drive demand for hybrid solar-wind-storage configurations with 24-hour load profiles.
Libya
Grid reconstruction and institutional capacity building precede renewable energy integration. The General Electricity Company of Libya manages transmission infrastructure recovery. Coastal population centers represent latent demand for building-integrated photovoltaics as stability returns.
North Africa Renewable Energy Market Competitive Landscape
Top-tier vendors anchor sovereign-backed utility procurement, while regional specialists and off-grid residential providers occupy fragmented lower tiers. Market structure concentrates around integrated development models combining Saudi capital with long-term power purchase agreements. Three archetypes dominate: Gulf-based infrastructure developers, Chinese equipment suppliers, and pay-as-you-go solar distributors. Competitive moves center on auction participation and local manufacturing partnerships to satisfy domestic content requirements.
Within the infrastructure developer tier, ACWA Power represents the integrated model combining capital deployment with long-term contracting across Egyptian and Moroccan markets. Sun King exemplifies the off-grid residential archetype through pay-as-you-go solar home systems targeting rural households beyond grid reach. First Solar occupies a position among technology-differentiated manufacturers, with thin-film photovoltaic production optimized for high-temperature desert environments prevalent across the Sahara belt.
| Leading Market Players |
|---|
| Daystar Power |
| Sun King |
| ACWA Power |
| Sungrow Power Supply |
| GE Vernova |
| Globeleq |
| Arnergy |
| First Solar |
| Lekela Power |
| Others |
Value Network & Pricing Analysis
Bankable utility-scale procurement diverges sharply from fragmented distributed generation financing, with sovereign-backed power purchase agreements commanding premium contract tenures while rural electrification developers absorb currency risk and local content costs. This bifurcation concentrates margin capture among integrated developers with multilateral guarantee access, while compressing returns for equipment suppliers serving price-sensitive mini-grid segments.
Pricing Analysis
Long-term offtake bundling dominates pricing architecture, with 20-25 year power purchase agreements from Egypt's New and Renewable Energy Authority and Morocco's Moroccan Agency for Sustainable Energy anchoring developer returns. Price differentiation stems from sovereign credit backing and molten salt thermal storage integration, with ACWA Power's integrated model capturing premium margins against merchant-exposed Algerian auction participants. Cost compression in photovoltaic modules intensifies as Chinese crystalline silicon manufacturers scale desert-optimized production. Industrial offtakers in Tunisia's phosphate processing corridor exhibit lowest price sensitivity due to 24-hour load profiles requiring hybrid firming, while Sahel mini-grid developers face acute budget constraints.
Supply Chain Analysis
Reverse-logistics flows for turbine gearbox refurbishment and inverter replacement remain underdeveloped across North Africa, forcing project operators to maintain costly spare parts inventories or absorb extended downtime. Equipment manufacturing concentrates in China, Germany, and the United States, with thin-film photovoltaic modules from First Solar and European turbine nacelles drawing from specialized production hubs. Polysilicon, rare-earth magnets, and molten salt thermal storage media constitute critical input dependencies. Single-source vulnerability runs through Chinese inverter supply, where tariff exposure and shipping chokepoints at Suez Canal transit points amplify delivery risk. Distribution runs through EPC contractors with integrated logistics capabilities, bypassing fragmented local wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North Africa's renewable energy sector functions as a regulatory compounder, where Morocco's green hydrogen strategy and Egypt's feed-in tariff revisions create successive demand waves that reward early positioning in sovereign-backed procurement frameworks.
For Market Incumbents: Deploy local manufacturing partnerships to satisfy Algeria's SKTM domestic content requirements and Morocco's Noor program localization mandates. Consolidate position by locking long-term polysilicon supply agreements before auction price floors compress further. Chinese equipment suppliers with captive module production represent the most credible substitution threat to European turbine incumbents.
For New Entrants and Emerging Players: The premium-to-economy service gap in rural electrification creates immediate white-space opportunity. Niger and Chad's unelectrified Sahel households offer the most penetrable addressable market, with pay-as-you-go solar home systems bypassing utility interconnection queues. Containerized photovoltaic-plus-storage configurations enable rapid deployment without land tenure formalization delays that stall utility-scale development.
For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid technology developers combining molten salt thermal storage with photovoltaic baseload. Long-term viability over a five-to-ten year horizon favors developers with demonstrated auction execution capability and existing sovereign relationships. Acquisition targets should demonstrate currency hedging infrastructure for euro- and dollar-denominated equipment exposure. Monitor Egyptian pound convertibility guarantees and Algerian dinar repatriation permissions as inflection signals for foreign capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen Electrolyzer Capacity Buildout | Morocco's national hydrogen strategy mandates dedicated renewable supply, anchoring demand for solar-wind hybrid projects. |
| Competitive Auction Mechanism Participation | Algeria's SKTM tender restructuring forces merchant price exposure optimization and balance-of-system cost reduction. |
| Molten Salt Thermal Storage Integration | Concentrated solar power hybridization enables dispatchable evening peak supply for Moroccan and Tunisian industrial offtakers. |
| Pay-as-you-go Solar Home System Distribution | Sun King's rural electrification model bypasses grid extension economics in Niger and Chad's Sahel belt. |
| Subsea European Interconnector Development | EU Green Deal carbon border adjustments create premium offtake markets for North African green electrons via Mediterranean cables. |
Research Methodology
Direct dialogue with utility planning officers, independent power project developers, EPC contractors, and grid operators across Morocco, Egypt, and Algeria grounded qualitative findings. Secondary validation drew from IEA renewable energy reports, FERC-equivalent regulatory filings from Egypt's New and Renewable Energy Authority, multilateral development bank project databases, and customs trade data on photovoltaic module imports. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were triangulated to cross-verify capacity and investment estimates.
Bottom-up analytical lens emphasized individual project economics and auction participation patterns, while top-down assessment tracked national renewable energy target compliance and hydrocarbon substitution trajectories. Segmentation modeling spanned technology type, application scale, end-user contract structure, and regional regulatory framework variations. CAGRs were derived from capacity installation run-rates and tariff evolution assumptions, incorporating electrolyzer demand curves from green hydrogen frameworks and European renewable energy certificate import elasticity.
Caveats apply where sovereign fiscal stress could materially shift offtake guarantee credibility, currency convertibility policies, or auction price floor settings. Forecasts reflect assumptions on multilateral guarantee availability and transmission infrastructure commissioning schedules. Practitioners should monitor Egyptian pound volatility, Algerian dinar repatriation permissions, and EU carbon border adjustment implementation timelines for early signals of capital flow redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
PV Water Heater Market