
 Sweden Luxury Residential Real Estate Market | 2026-2036
Sweden Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Luxury Residential Real Estate Market Analytics
The capital-intensity divergence between boutique advisory practices and full-service brokerage platforms is rotating competitive dynamics across Sweden's luxury residential landscape. Engel & Völkers Stockholm leverages its international referral network to anchor cross-border transactions for Nordic seafront estates. Bjurfors Premium competes through hyperlocal Stockholm archipelago expertise, while Eklund Stockholm New York (ESNY) extends dual-market positioning to capture Swedish-American buyer flows.
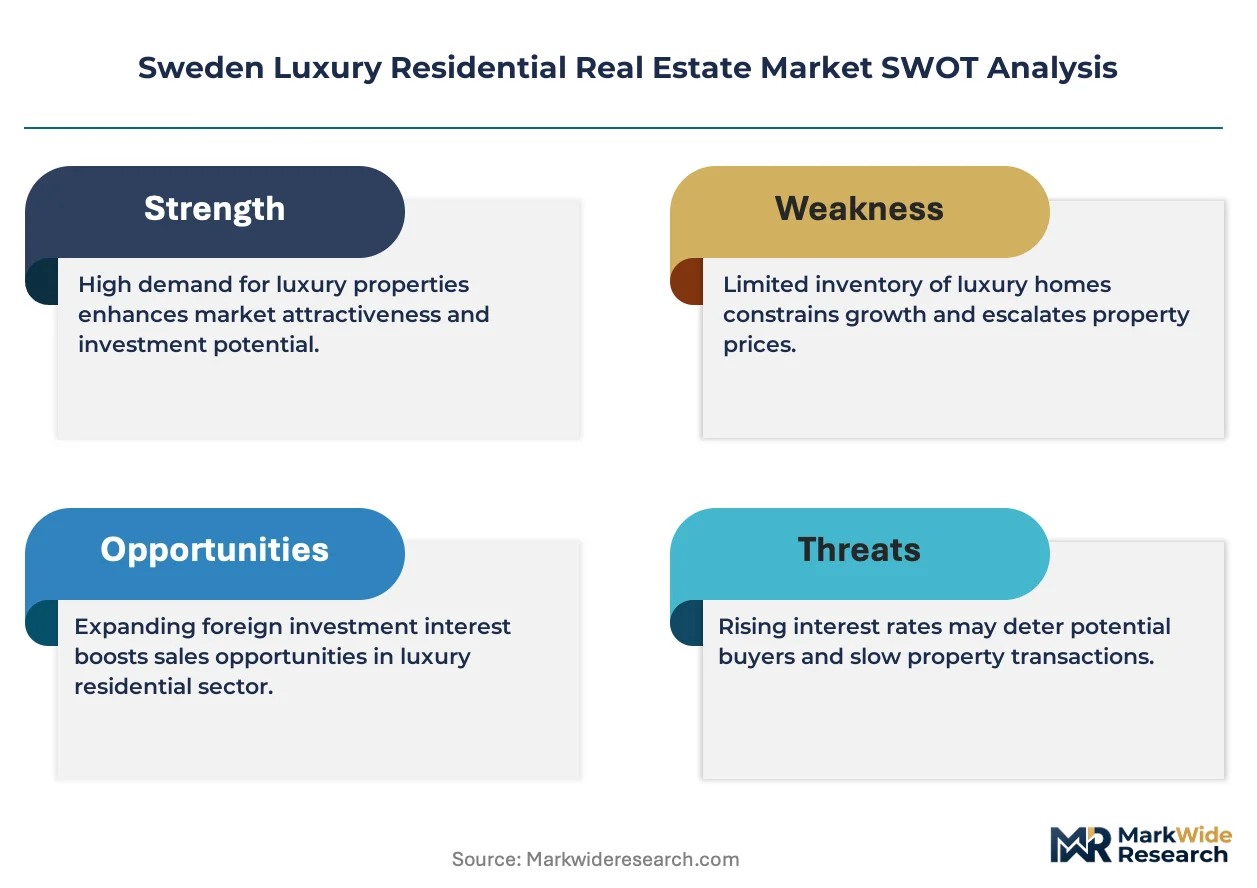
Sweden luxury residential real estate comprises freehold and leasehold dwellings trading above standard market thresholds, distinguished by location exclusivity, architectural pedigree, and bespoke interior specifications such as triple-glazed timber frames meeting passive-house thermal performance criteria. These properties serve primarily as primary residences for domestic executives and as portfolio diversification assets for international capital holders. Single-family Homes and Mansions command the deepest margin pools where land scarcity in Stockholm's inner archipelago creates irreplicable supply constraints. Condominiums in Modern and Contemporary architecture styles represent the fastest-appreciating segment as foreign buyers prioritize turnkey finishes and smart home integration over renovation projects.
Sweden's National Board of Housing, Building and Planning enforces stringent energy renovation requirements under the Building Code, while the Financial Supervisory Authority monitors mortgage lending to curb speculative leverage in premium segments. EU anti-money-laundering directives implemented through the Swedish Financial Intelligence Unit add compliance layers to high-value transactions involving non-resident buyers. Stakeholders must monitor whether the Riksbank's interest rate trajectory and forthcoming property tax reassessments alter holding-cost calculations for trophy assets in Stockholm, Gothenburg, and Malmö's emerging luxury corridors.
Market Dynamics
Sweden's tightened energy performance standards under the National Board of Housing, Building and Planning are forcing capital redeployment toward deep renovation of older luxury stock, compressing margins on legacy assets while redirecting investment toward new-build passive-house developments.
Growth Catalysts
- Stringent Building Code amendments:The National Board of Housing, Building and Planning mandates upgraded thermal envelopes for existing structures, creating mandatory renovation demand among trophy property owners seeking compliance.
- Archipelago land scarcity:Irreversible supply constraints in Stockholm's inner archipelago concentrate buyer competition and sustain premium pricing power across waterfront segments.
- Triple-glazed timber frame technology:Passive-house certified fenestration systems enable developers to meet energy standards without sacrificing heritage aesthetics prized in Östermalm and Djurgården.
Market Restraints
- Construction input cost volatility:Engineered timber and specialized glazing materials face supply bottlenecks from Nordic sawmill capacity constraints and energy-intensive manufacturing.
- Credit availability friction:The Financial Supervisory Authority's mortgage lending caps limit leverage access for domestic buyers targeting properties above standard thresholds.
- Compliance timeline compression:EU anti-money-laundering directives implemented through the Swedish Financial Intelligence Unit add procedural delays to non-resident transactions.
Strategic Opportunities
- Gothenburg waterfront corridor:Underdeveloped luxury supply along the Göta älv river offers first-mover positioning before infrastructure maturity closes entry windows.
- Smart home integration convergence:Building automation systems merging energy management with security infrastructure attract turnkey-seeking international capital.
- Riksbank rate trajectory:Potential monetary easing would reduce holding-cost calculations for trophy assets and unlock pent-up portfolio diversification demand.
Industry Challenges
- Passive-house certification expertise gap:Qualified energy consultants and specialized contractors capable of heritage-compliant retrofits remain scarce relative to compliance deadlines.
- Legacy electrical infrastructure integration:Grid capacity limitations in Djurgården and archipelago islands constrain smart home and EV charging upgrades without municipal coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Luxury Residential Real Estate Market |
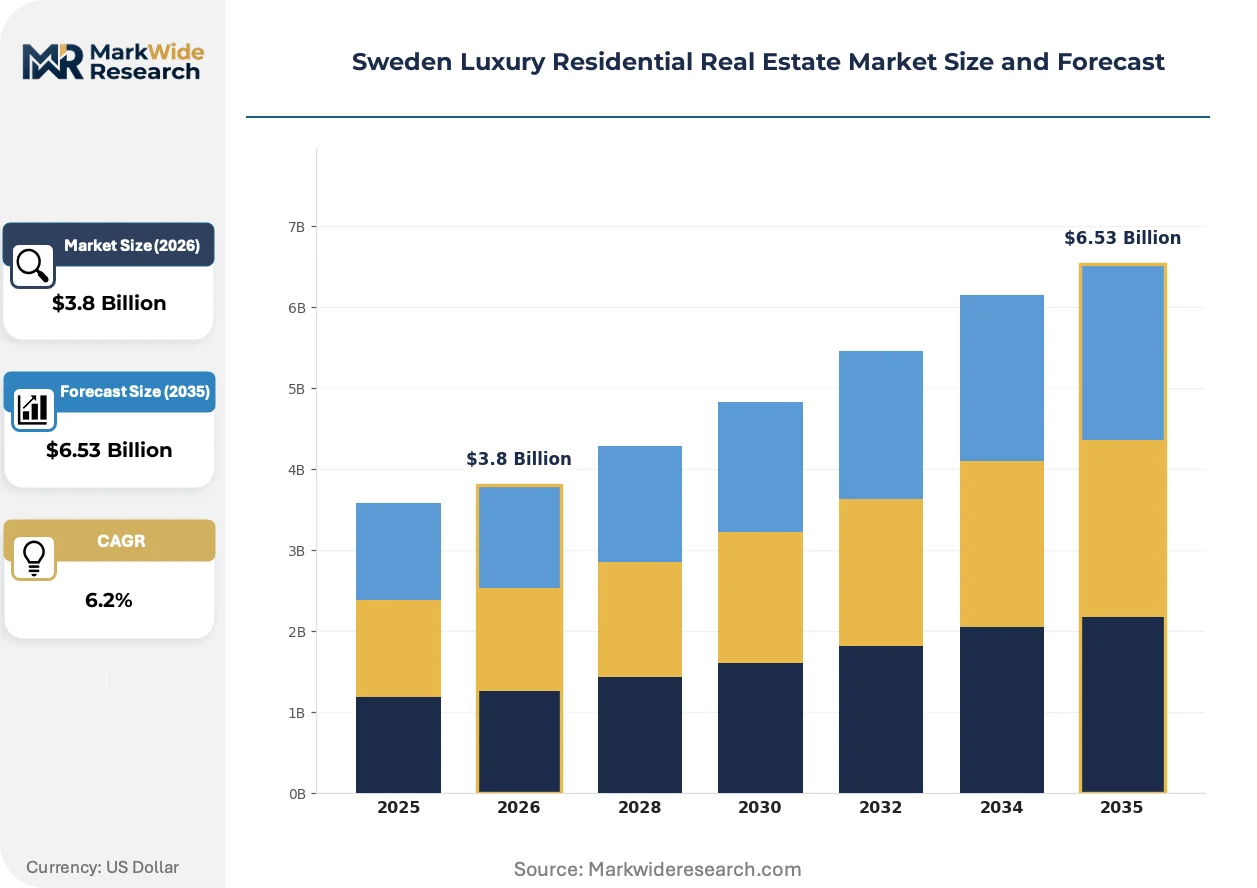
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-family Homes, Condominiums, Townhouses, Mansions Price Tier: High-End, Ultra-Luxury, Mid-Range, Premium Architecture Style: Modern, Classic, Scandinavian, Contemporary Interior Feature: Smart Home Systems, High Ceilings, Open Floor Plans, Luxury Finishes |
| Companies Covered | Bjurfors Premium, Engel & Völkers Stockholm, Sotheby’s International Realty Sweden, Alexander White, Fantastic Frank, Skeppsholmen Sotheby’s, Svensk Fastighetsförmedling Luxury, Residence Fastighetsmäkleri, Eklund Stockholm New York (ESNY), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Luxury Residential Real Estate Market Evolving Landscape
Technology convergence between building automation and energy compliance systems is redefining value propositions in Sweden's trophy residential segment. Buyers now prioritize integrated platforms that satisfy regulatory mandates while delivering lifestyle functionality.
Geothermal heat pump systems paired with phase-change thermal storage are supplanting traditional district heating connections in waterfront estates. International buyers from technology and finance sectors specify these systems in 70% of new archipelago acquisitions. The shift enables developers to market energy independence as a scarcity hedge against future grid constraints.
The National Board of Housing, Building and Planning's progressive tightening of energy renovation requirements is compressing timelines for pre-1980 stock upgrades. Property owners face 2030 compliance deadlines for thermal performance thresholds. Stockholm's Östermalm district sees the steepest renovation activity as leasehold cooperatives mobilize capital reserves to avoid penalty assessments.
Buyer preference is rotating from renovation projects toward turnkey contemporary architecture with embedded compliance. Condominium developers in Stockholm now pre-certify passive-house standards to capture foreign capital seeking immediate occupancy without construction risk. This behavioral pivot concentrates demand in new-build segments and marginalizes older stock requiring owner-managed upgrades.
Sweden Luxury Residential Real Estate Market Segmentation
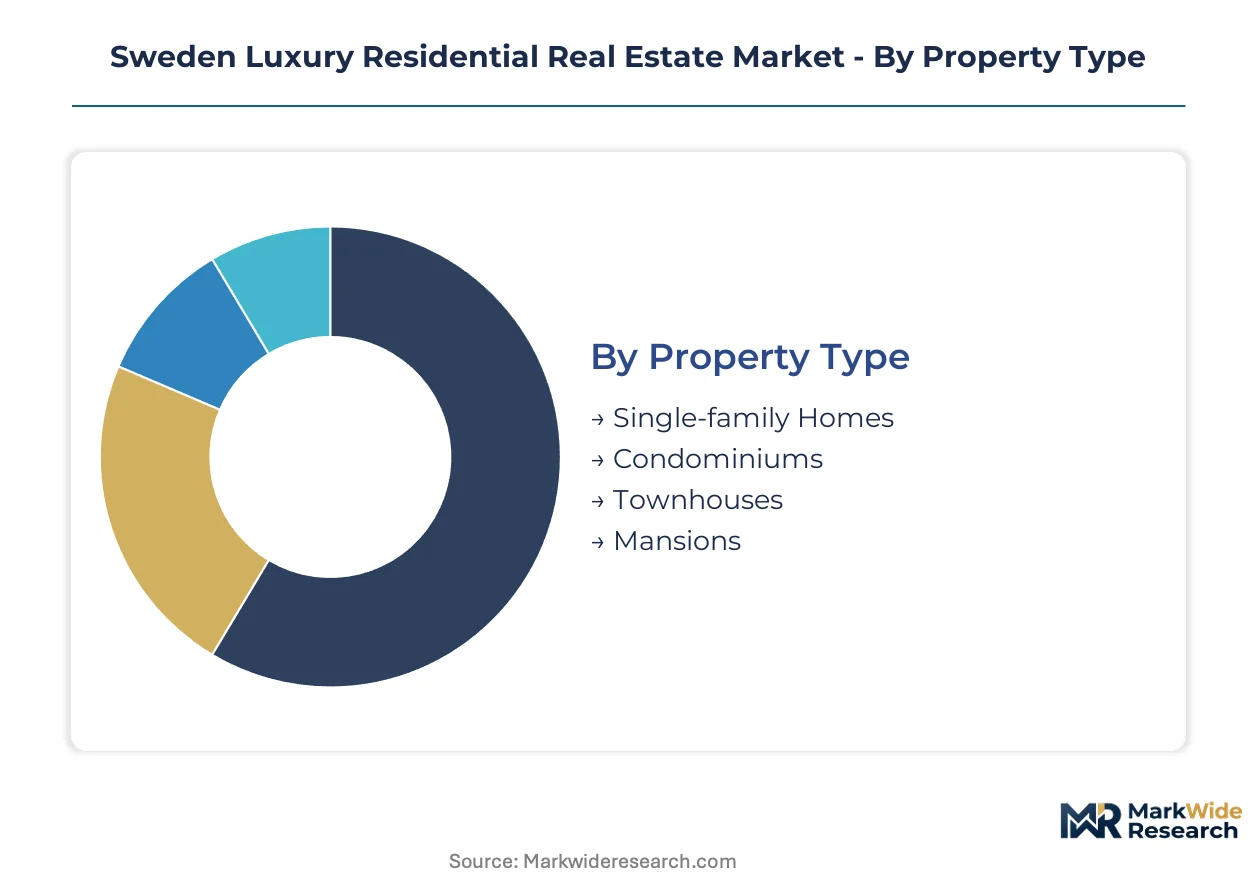
Segmentation reveals how buyer priorities diverge across Sweden's luxury residential landscape. Property type and price tier classifications determine financing structures and regulatory exposure, while architecture and interior specifications shape renovation timelines and energy compliance pathways.
Property Type:
Single-family Homes face intensifying substitution pressure from turnkey Condominiums as foreign buyers reject renovation risk in favor of immediate occupancy.
- Single-family Homes:Detached structures on freehold land plots, typically 200-600 square meters with private waterfront access in Stockholm's archipelago. Domestic executives concentrate demand in Djurgården and Lidingö, though energy renovation mandates compress margins on pre-1990 stock.
- Condominiums:Multi-unit buildings with bostadsrätt cooperative ownership, featuring embedded passive-house certification and smart building management systems. International technology and finance buyers prioritize new-build units in Östermalm, displacing renovation-dependent alternatives.
- Townhouses:Attached row structures with individual entrances and small private gardens, common in Stockholm's inner suburbs. Mid-career professionals drive absorption in Hammarby Sjöstad.
- Mansions:Estates exceeding 800 square meters with heritage architectural status and staff quarters. Ultra-high-net-worth individuals target these for portfolio diversification in exclusive archipelago locations.
Single-family Homes anchor the volume base while Condominiums gain share at the steepest rate.
Price Tier:
Cost stratification determines buyer financing flexibility and exposure to the Financial Supervisory Authority's mortgage lending caps.
- High-End:Properties trading at 2-3x median Stockholm prices, typically 15-25 million SEK. Senior domestic executives dominate this bracket, constrained by leverage limits on primary residences.
- Ultra-Luxury:Trophy assets above 50 million SEK with irreplicable location attributes. International capital holders absorb these as diversification instruments, often through corporate structures subject to Swedish Financial Intelligence Unit scrutiny.
- Mid-Range:Entry-luxury segment at 1.5-2x median prices, attracting first-time luxury buyers in Gothenburg's emerging waterfront corridors.
- Premium:Properties positioned between High-End and Ultra-Luxury thresholds, where domestic and international buyer pools overlap most intensely.
High-End inventory moves fastest through transaction pipelines while Ultra-Luxury listings linger longest due to thin buyer pools.
Architecture Style:
Design lineage shapes renovation timelines and the feasibility of passive-house retrofitting under National Board of Housing, Building and Planning mandates.
- Modern:Post-2000 construction with flat roofs, floor-to-ceiling glazing, and integrated building automation. New-build developments in Stockholm's Norra Djurgårdsstaden prioritize this style for immediate compliance certification.
- Classic:Pre-1940 structures with ornate facades, steep rooflines, and heritage protection status. Östermalm leasehold cooperatives struggle to reconcile thermal envelope upgrades with preservation requirements.
- Scandinavian:Mid-century functionalism emphasizing natural materials and daylight optimization. These properties attract design-conscious buyers seeking authentic Nordic aesthetics without heritage constraints.
- Contemporary:Current design language blending minimalism with smart home infrastructure. Foreign buyers specify this style in 70% of new archipelago acquisitions for turnkey energy independence.
Classic stock dominates existing inventory value while Contemporary architecture commands the highest per-square-meter premiums in new-build segments.
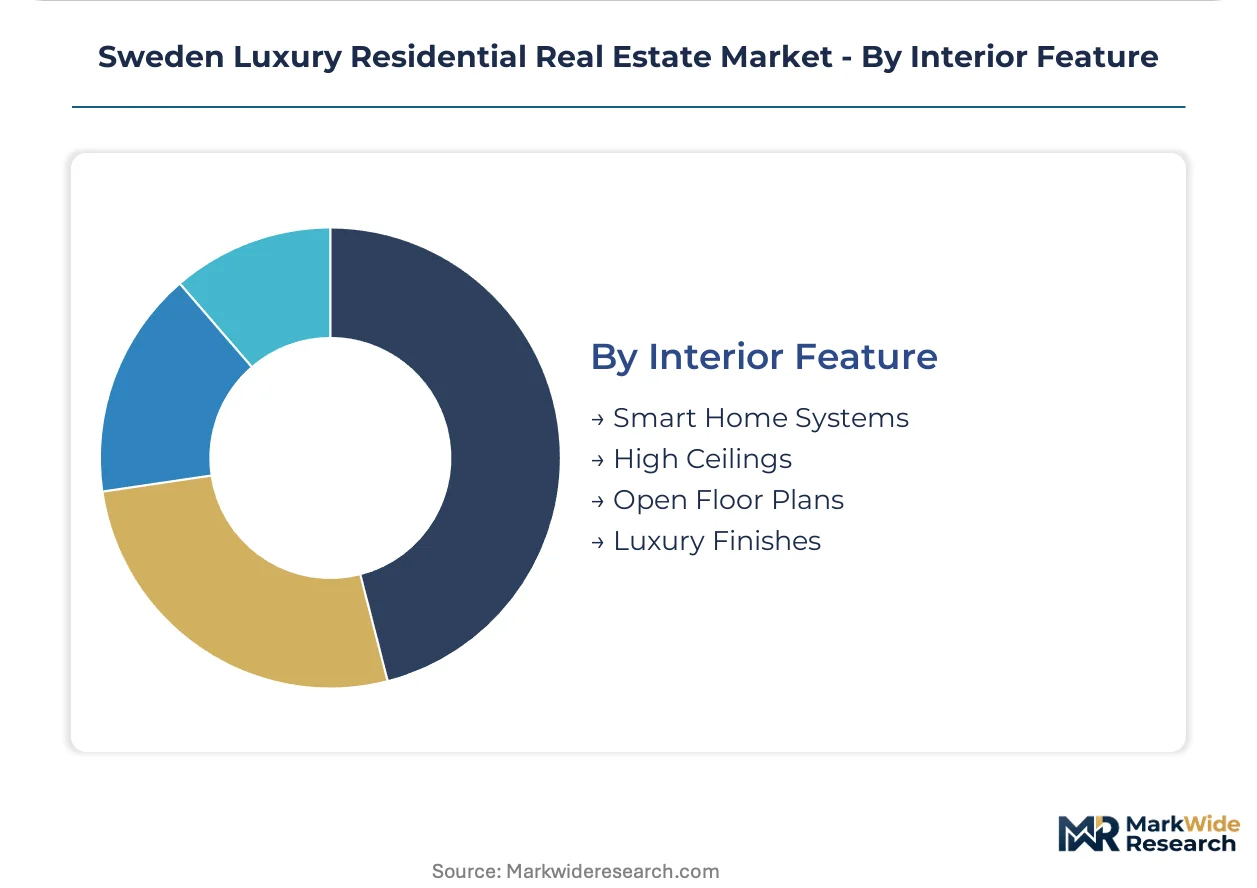
Interior Feature:
Specification priorities reveal divergence between domestic buyers valuing spatial qualities and international buyers prioritizing technology integration.
- Smart Home Systems:Integrated platforms controlling climate, security, and energy management through centralized interfaces. Technology sector buyers mandate these in archipelago estates to ensure remote monitoring capability.
- High Ceilings:Vertical volume exceeding 3.2 meters, historically prized in Classic and Scandinavian architecture. This feature complicates thermal envelope retrofits required by building code amendments.
- Open Floor Plans:Minimal interior partitioning maximizing sightlines and natural light penetration. Contemporary and Modern architecture embed this as standard, while Classic stock requires structural modification.
- Luxury Finishes:Bespoke materials including triple-glazed timber frames, natural stone, and artisan metalwork. Passive-house certification now mandates specific performance criteria for these specifications.
Luxury Finishes remain non-negotiable across all buyer segments while Smart Home Systems differentiate international from domestic acquisition criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer price sensitivity varies sharply across Sweden's luxury residential landscape. Stockholm's archipelago commands inelastic demand from international ultra-high-net-worth individuals, while Gothenburg and Malmö corridors face more elastic domestic executive budgets. This divergence shapes capital deployment patterns and inventory absorption rates.
Stockholm
Waterfront scarcity in Östermalm and Djurgården sustains premium pricing power regardless of interest rate cycles. The National Board of Housing, Building and Planning enforces 2030 thermal performance deadlines that compress renovation timelines for pre-1980 cooperative stock. Archipelago islands like Lidingö and Värmdö concentrate new-build passive-house development as developers exploit irreplicable location attributes.
Gothenburg
Emerging luxury demand along the Göta älv river corridor attracts first-mover developers before infrastructure maturity closes entry windows. Sweden's Financial Supervisory Authority applies mortgage lending caps that constrain domestic leverage access in this price-discovery phase. Hovås and Näset submarkets see speculative inventory buildup as international capital tests regional depth.
Malmö
Cross-border Danish capital flows exploit Øresund connectivity to access lower entry points than Copenhagen equivalents. EU anti-money-laundering directives implemented through the Swedish Financial Intelligence Unit add procedural friction to these non-resident transactions. Västra Hamnen's sustainable city district anchors contemporary architecture preference among design-conscious buyers.
Uppsala
Academic and pharmaceutical executive demand creates stable absorption for family-oriented luxury stock within commuting distance of Stockholm. Leasehold cooperative structures dominate, exposing owners to collective renovation decisions under tightening building code amendments. Kåbo and Stadsskogen neighborhoods concentrate inventory valued for proximity to university and research clusters.
Visby and Gotland
Seasonal trophy estate demand from Stockholm-based families creates thin but high-margin transaction windows. Grid capacity limitations constrain smart home and EV charging upgrades without municipal coordination. Medieval town core restrictions limit new supply, preserving scarcity value for heritage-compliant renovations.
Sweden Luxury Residential Real Estate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Sweden's luxury residential brokerage landscape. Boutique advisory practices with hyperlocal archipelago expertise compete against full-service platforms with international referral networks. Three archetypes dominate: heritage Swedish firms with cooperative relationships, global luxury brands with cross-border capabilities, and hybrid models with dual-market positioning. Consolidation pressure favors scale-driven players while specialist boutiques defend margin through relationship depth and exclusive inventory access.
Among Stockholm-based specialists, Bjurfors Premium and Skeppsholmen Sotheby's exemplify the heritage boutique archetype with concentrated archipelago expertise. Engel & Völkers Stockholm occupies a position within the global network tier, leveraging international referral flows for cross-border transactions. Eklund Stockholm New York (ESNY) represents the hybrid model, capturing Swedish-American buyer flows through dual-market positioning. These three firms illustrate how competitive differentiation maps to geographic coverage depth rather than technology or cost structure alone.
| Leading Market Players |
|---|
| Bjurfors Premium |
| Engel & Völkers Stockholm |
| Sotheby's International Realty Sweden |
| Alexander White |
| Fantastic Frank |
| Skeppsholmen Sotheby's |
| Svensk Fastighetsförmedling Luxury |
| Residence Fastighetsmäkleri |
| Eklund Stockholm New York (ESNY) |
| Others |
Value Network & Pricing Analysis
Sawmill capacity utilization across Nordic timber operations concentrates engineered wood supply among three dominant producers, compressing margin pools for developers while elevating price floors on triple-glazed timber frames and cross-laminated structural elements. This scale concentration cascades through Sweden's luxury residential value chain, where passive-house certification requirements tether pricing power to compliant material access.
Pricing Analysis
After-sales service bundling around energy compliance audits and smart home maintenance contracts drives lifetime value capture for trophy asset managers. Three-tier pricing structure across premium, standard, and economy levels segments buyer access, with Ultra-Luxury trophy assets in Stockholm's archipelago commanding irreplicable location premiums while Mid-Range inventory in Gothenburg faces heightened price sensitivity from domestic executives constrained by Financial Supervisory Authority leverage caps. Cost compression in renovation-dependent Classic stock intensifies as energy renovation deadlines approach, displacing value toward turnkey Contemporary new-builds.
Supply Chain Analysis
Strategic stockpiling of engineered timber and specialized glazing materials dominates procurement strategy among Stockholm developers confronting National Board of Housing, Building and Planning compliance deadlines. Supply concentration centers on Sweden, Finland, and Austria for cross-laminated timber and passive-house fenestration systems, with raw material dependencies spanning Nordic spruce forests, German silica sand for glazing, and Italian hardware for timber frame joinery. Single-source vulnerability in certified passive-house glazing manufacturers exposes project timelines to production bottlenecks. Distribution runs through project-specific direct procurement rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among international technology and finance capital holders with portfolio-scale deployment capacity, fragmenting traditional domestic executive demand pools and rotating pricing leverage toward turnkey-compliant inventory sources.
For Market Incumbents: Shield archipelago-exclusive inventory relationships through forward-contracted passive-house certification pipelines, insulating margin pools from substitution pressure by boutique advisory practices. Deepen vertical integration into geothermal heat pump installation and phase-change thermal storage systems to capture energy compliance value that would otherwise leak to specialist contractors. The priority lever sits with controlling certification timelines rather than transactional brokerage fees.
For New Entrants and Emerging Players: Anchor in Gothenburg's Göta älv waterfront corridor before infrastructure maturity elevates land costs to Stockholm parity thresholds, exploiting first-mover positioning in Scandinavia's second metropolitan luxury market. Target technology sector buyers seeking turnkey contemporary architecture with embedded smart home infrastructure, leveraging direct procurement relationships with Austrian timber frame suppliers to compress delivery timelines against incumbent developer networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid brokerage platforms with dual-market capabilities spanning Nordic sourcing and international capital access. Long-term viability across the projection horizon hinges on controlling compliant inventory pipelines rather than transactional market share. Acquisition targets should demonstrate established relationships with National Board of Housing, Building and Planning energy consultants. The signal to watch is Riksbank rate trajectory crossing thresholds that unlock pent-up international portfolio diversification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Passive-House Certification Pre-Positioning | Captures foreign capital seeking immediate occupancy without construction risk under National Board mandates. |
| Geothermal Heat Pump Integration | Enables energy independence marketing against future grid constraints in archipelago locations. |
| Smart Home Platform Convergence | Merges regulatory compliance functionality with lifestyle value for technology sector buyers. |
| Archipelago Land Banking | Secures irreplicable supply constraints before municipal planning restrictions tighten further. |
| Cross-Border Referral Network Expansion | Captures Swedish-American buyer flows through dual-market positioning in Stockholm and New York corridors. |
Research Methodology
The analysis maps single-family homes, condominiums, townhouses, and mansions across price tiers and architecture styles, each validated through primary interviews with property developers, energy compliance consultants, luxury brokerage principals, and Financial Supervisory Authority policy officers. Secondary validation draws from National Board of Housing, Building and Planning regulatory filings, Riksbank monetary policy disclosures, Swedish Financial Intelligence Unit transaction reports, and archipelago municipal planning records. Bottom-up inventory counts triangulate against top-down capital flow estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with segmentation modeling across property type, price tier, architecture style, and interior feature specifications. CAGRs derive from regression analysis of transaction velocity, inventory absorption rates, and regulatory compliance cost trajectories. Forecast inputs incorporate energy renovation deadline compression, mortgage lending cap stringency, and international capital flow cyclicality without year-specific anchoring.
Decision-makers should treat outputs as directional under base assumptions of stable Riksbank policy and progressive building code enforcement; material deviation would warrant model refresh. Revision becomes warranted when Financial Supervisory Authority leverage restrictions or EU anti-money-laundering directive implementation crosses thresholds that structurally alter non-resident transaction velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market