
 Qatar Luxury Residential Real Estate Market | 2026-2036
Qatar Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Luxury Residential Real Estate Market Analytics
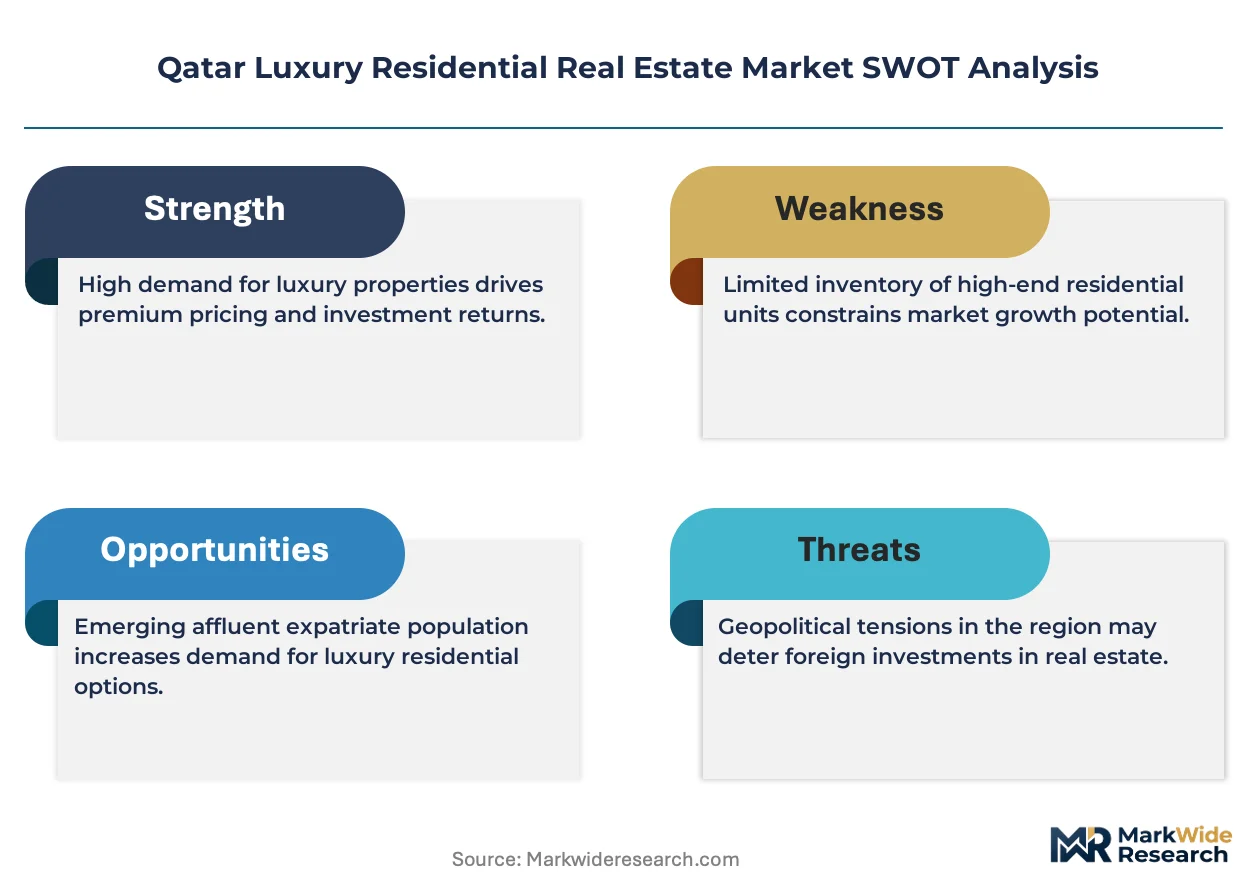
Qatar's foreign property ownership law is pivoting the entry calculus for non-GCC investors, expanding freehold rights in designated zones beyond The Pearl. United Development Company leverages its integrated master-developer model across Lusail City to control land pipelines and infrastructure timing. Qatari Diar anchors prestige positioning through trophy assets in West Bay and Msheireb Downtown. Alfardan Properties differentiates via bespoke villa portfolios targeting ultra-high-net-worth GCC families seeking privacy and concierge services.
Qatar luxury residential real estate comprises freehold and leasehold dwellings exceeding premium quality benchmarks, typically featuring smart home integration, private marina access, and materials sourced from Italian and Turkish suppliers for interior finishes. These properties serve wealth preservation, lifestyle migration, and generational asset transfer for regional and international capital holders. Villas dominate transaction value pools given scarcity of waterfront plots and compound-style layouts preferred by extended families. Penthouses represent the fastest-appreciating property type as vertical density increases in Doha's financial district. The Ultra-Luxury price tier captures disproportionate margin concentration where bespoke architecture and branded residences command significant premiums over standardized premium offerings.
Qatar's Ministry of Justice and Ministry of Municipality enforce building codes and foreign ownership registry requirements that shape developer compliance costs and buyer eligibility pathways. The Qatar Central Bank monitors mortgage lending thresholds for non-resident purchasers, directly influencing leverage availability and transaction velocity. Stakeholders must track evolving freehold zone designations and infrastructure completion timelines as these determine liquidity depth and rental yield sustainability across sub-markets.
Market Dynamics
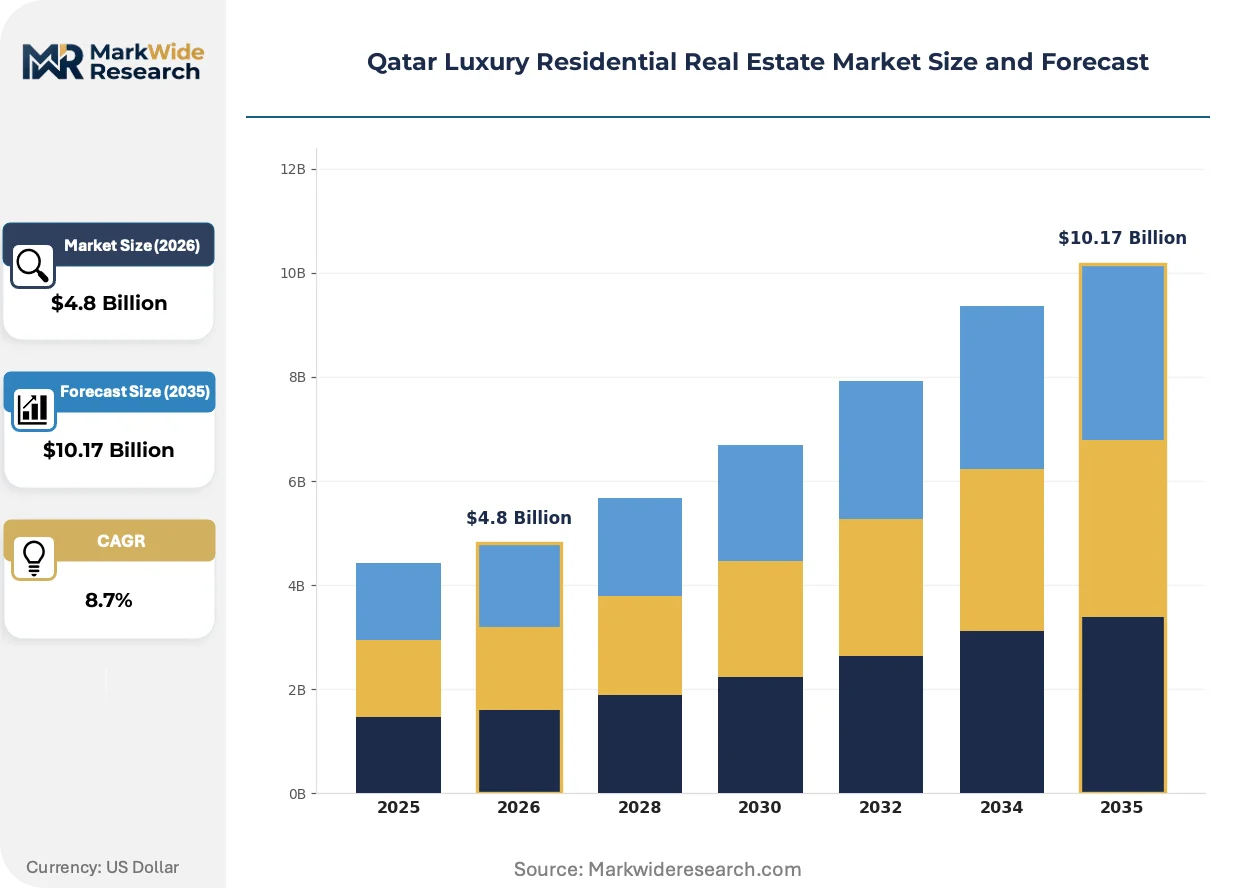
Qatar's updated foreign ownership regulations for designated investment zones are redrawing buyer eligibility maps, expanding freehold rights beyond The Pearl into Lusail and West Bay Lagoon while the Qatar Central Bank recalibrates mortgage leverage thresholds for non-resident purchasers.
Growth Catalysts
- Freehold Zone Expansion:The Ministry of Justice's 2023 circular extending freehold rights to additional master-planned districts is unlocking institutional capital flows from European and Asian HNWIs previously restricted to leasehold structures.
- Infrastructure Completion Timelines:Lusail City's integrated metro connectivity and marina completion are compressing holding-period risk for speculative capital and activating secondary market liquidity.
- Smart Home Integration:IoT-enabled building management systems from Italian and Turkish suppliers are becoming baseline expectations in ultra-luxury specifications, differentiating trophy assets from standardized premium inventory.
Market Restraints
- Waterfront Plot Scarcity:The Ministry of Municipality's strict coastal development buffers are constraining villa supply in Pearl-Qatar and West Bay, inflating land premiums beyond construction cost multiples.
- Mortgage Lending Thresholds:Qatar Central Bank caps on loan-to-value ratios for non-resident purchasers are compressing leverage availability and elongating transaction cycles for international buyers.
- Construction Input Volatility:Premium marble and travertine sourcing from Carrara quarries faces shipping cost fluctuations and extended lead times, pressuring developer margin structures on fixed-price contracts.
Strategic Opportunities
- Branded Residence Convergence:Hospitality-operated residential concepts are penetrating Doha's luxury inventory, capturing yield premiums through concierge service bundling and fractional ownership structures.
- Generational Asset Transfer Services:Family office advisory integration with property acquisition is creating white space for developers offering estate planning, succession structuring, and multi-jurisdictional holding vehicles.
- Msheireb Downtown Activation:Heritage district regeneration policies are opening boutique-scale luxury opportunities outside the Pearl-Lusail corridor, attracting cultural capital seeking differentiated address positioning.
Industry Challenges
- Skilled Project Management Gap:Shortage of bilingual construction supervisors familiar with Qatari building codes and Italian fit-out specifications is delaying handover timelines on bespoke villa developments.
- Registry Compliance Complexity:Foreign buyer eligibility verification across multiple ministry databases is creating transaction friction and earnest money escrow disputes.
- Legacy System Integration:Master-developer ERP platforms for Lusail's phased infrastructure rollout require manual reconciliation with municipal permitting portals, slowing unit release scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Luxury Residential Real Estate Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Luxury Apartments, Villas, Penthouses, Townhouses End User: High-Net-Worth Individuals, Foreign Investors, Expats, Locals Sales Channel: Direct Sales, Real Estate Agencies, Online Listings, Auction Price Tier: Ultra-Luxury, Premium, Mid-Range, Affordable Luxury |
| Companies Covered | Al Mirqab Real Estate, Al Mana Real Estate, Alfardan Properties, Al Asmakh Real Estate, United Development Company, Barwa Real Estate Group, Zukhrof Real Estate, Professional Real Estate Co., Qatari Diar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Luxury Residential Real Estate Market Evolving Landscape
Digital twin technology and predictive maintenance platforms are redefining asset management expectations in Qatar's trophy residential inventory, while sustainability certification pressures from European capital sources are filtering into specification standards.
Building information modeling is converging with IoT sensor networks to create live digital replicas of luxury villa mechanical systems. Alfardan Properties and United Development Company are deploying these platforms for predictive HVAC and marina infrastructure maintenance. This convergence is compressing operational expenditure forecasting horizons from annual to real-time monitoring, enabling premium service charge pricing models.
The Ministry of Municipality's updated green building code alignment with LEED and Estidama Pearl rating systems is mandating solar thermal pre-heating and greywater recycling in new luxury developments. Compliance costs are elevating baseline construction budgets while creating certification-driven price stratification between compliant and legacy inventory. European institutional buyers are now screening assets exclusively against these combined standards.
Direct developer-to-buyer digital transaction platforms are displacing traditional brokerage intermediation for repeat GCC family purchasers. Lusail City and Pearl-Qatar master developers are deploying proprietary CRM portals with virtual staging and contract execution capabilities. This channel shift is most visible among Riyadh and Dubai-based ultra-high-net-worth buyers executing portfolio acquisitions without physical site visits.
Qatar Luxury Residential Real Estate Market Segmentation
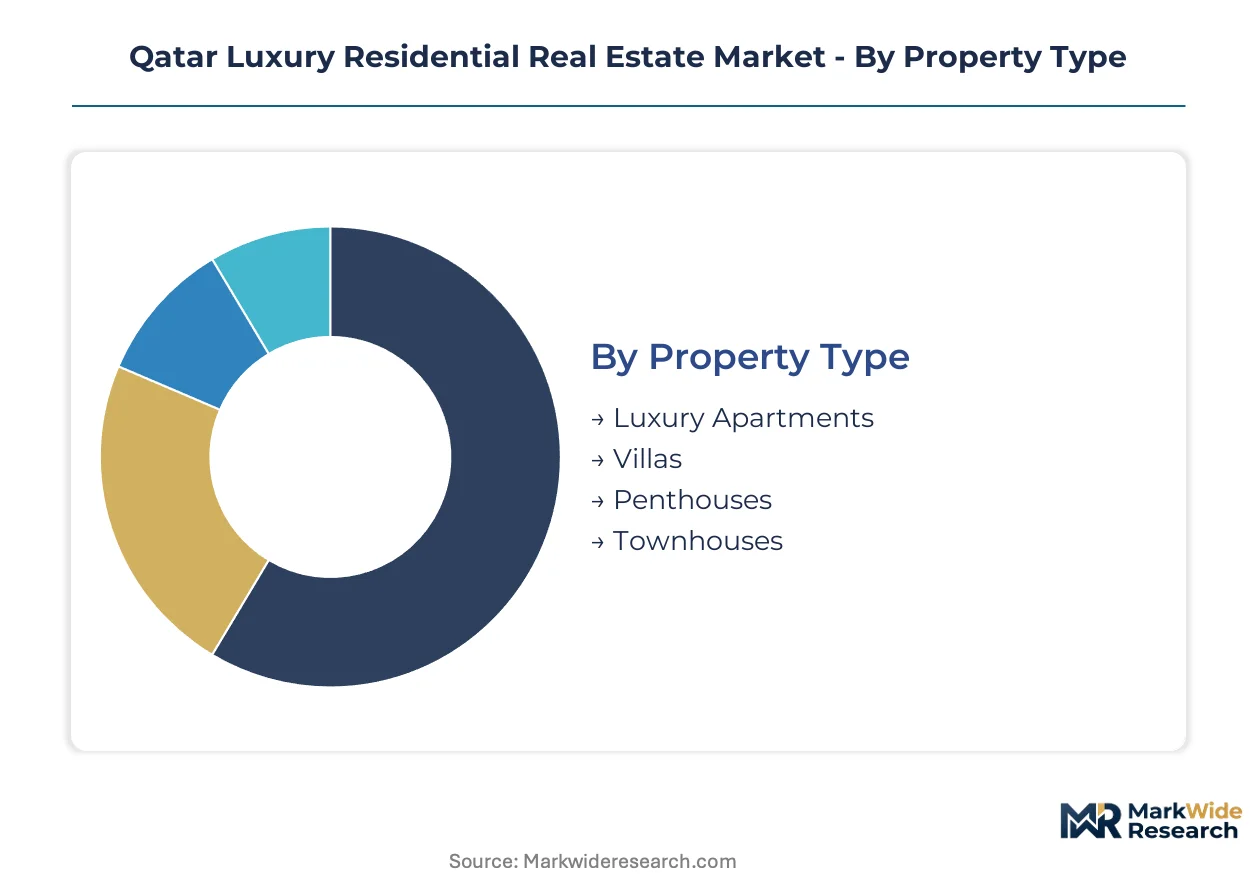
Segmentation in Qatar's luxury residential market reveals how regulatory frameworks, buyer eligibility pathways, and infrastructure completion timelines concentrate value across distinct property categories. Understanding these divisions enables stakeholders to align development pipelines with capital source preferences and ministry compliance requirements.
Property Type:
The Ministry of Municipality's Estidama Pearl certification requirements vary sharply across structural forms, with villas facing stricter coastal buffer compliance than vertical developments.
- Villas:Compound-style layouts with private marina access and extended family accommodations dominate transaction value pools. Waterfront plot scarcity in Pearl-Qatar and West Bay Lagoon inflates land premiums, while Italian marble specifications and smart home integration from Turkish suppliers create differentiation thresholds. Demand concentrates among ultra-high-net-worth GCC families seeking privacy and generational asset transfer vehicles.
- Penthouses:Vertical density in Doha's financial district drives the steepest appreciation trajectory among all property types. Floor-to-ceiling glazing, private elevator access, and rooftop terraces with 360-degree views command premiums over standard luxury apartments. European institutional buyers target these assets for portfolio diversification within designated freehold zones.
- Luxury Apartments:Mid-rise inventory in Lusail City and Msheireb Downtown attracts expatriate professionals seeking metro connectivity and concierge services.
- Townhouses:Hybrid density solutions in master-planned communities offer lower service charges than villas with more space efficiency than apartments.
Leading the category by volume: Villas. Expanding most quickly: Penthouses.
End User:
Buyer composition determines leverage availability, with Qatar Central Bank applying differentiated loan-to-value caps based on residency status and capital origin.
- High-Net-Worth Individuals:European and Asian capital holders drive trophy asset acquisitions in The Pearl and Lusail, prioritizing freehold rights and wealth preservation structures. These buyers execute transactions through family offices with multi-jurisdictional holding vehicles, requiring specialized registry compliance navigation across Ministry of Justice and Ministry of Municipality databases.
- Foreign Investors:Institutional capital from outside GCC regions activates following freehold zone expansions beyond The Pearl. These purchasers face compressed leverage availability under Qatar Central Bank thresholds, elongating transaction cycles but concentrating equity-heavy deals in waterfront developments.
- Expats:Long-term residents in Qatar leverage leasehold-to-freehold conversion pathways in designated investment zones.
- Locals:Qatari nationals prioritize compound-style villas in West Bay and legacy districts for extended family housing.
Volume concentration: High-Net-Worth Individuals. Fastest eligibility expansion: Foreign Investors.
Sales Channel:
Channel selection correlates with buyer sophistication and repeat purchase history, altering commission structures and due diligence timelines.
- Direct Sales:Master-developer CRM portals with virtual staging capabilities displace traditional intermediation for repeat GCC family purchasers. United Development Company and Alfardan Properties deploy proprietary platforms enabling contract execution without physical site visits, compressing transaction cycles for Riyadh and Dubai-based buyers.
- Real Estate Agencies:Boutique advisory firms integrate estate planning and succession structuring for ultra-high-net-worth clients navigating foreign ownership eligibility verification.
- Online Listings:Digital marketplaces aggregate secondary market inventory for price discovery in Lusail's emerging districts.
- Auction:Distressed trophy assets and developer close-out inventory transact through sealed-bid processes.
Dominant by transaction value: Direct Sales. Gaining share fastest: Online Listings.
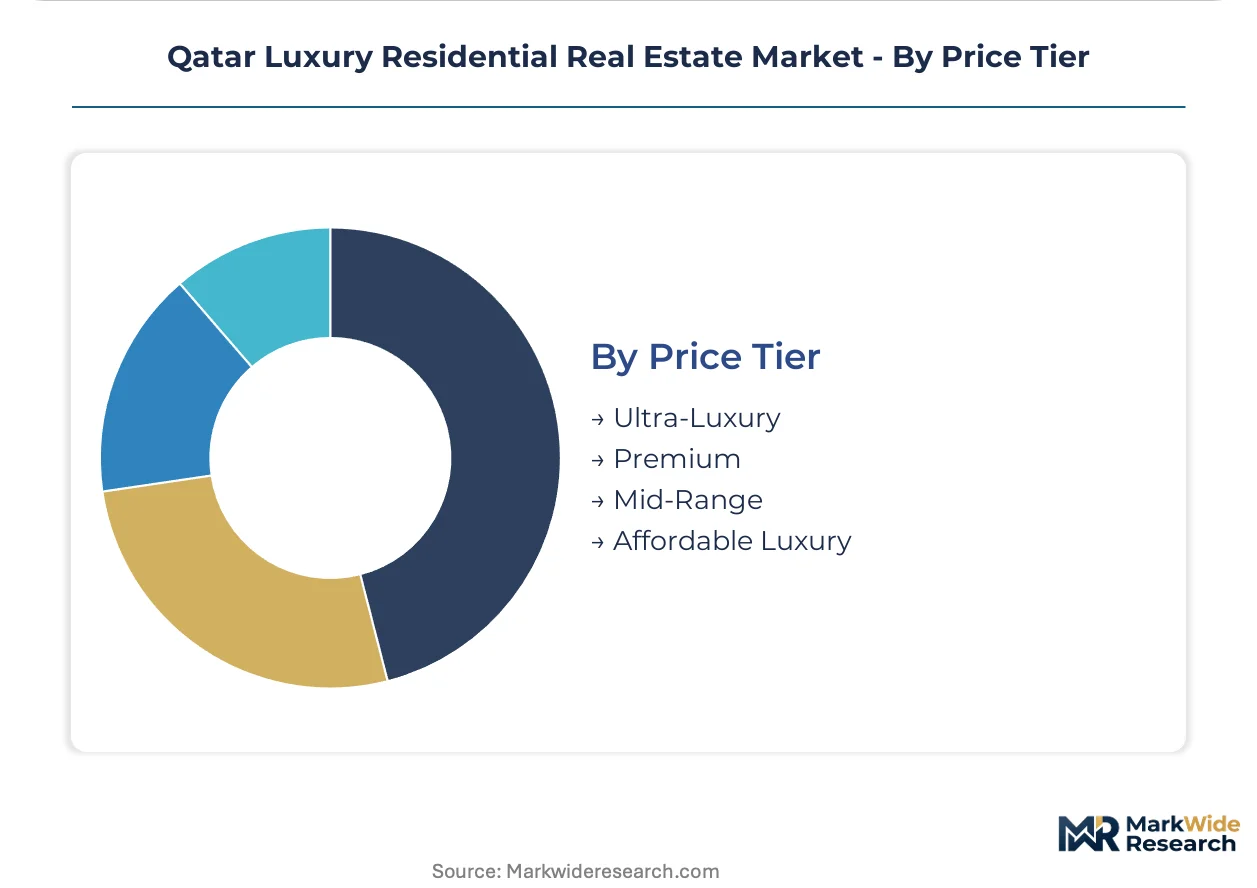
Price Tier:
Margin structures stratify sharply across tiers, with bespoke architecture and branded residence premiums creating non-linear price escalation.
- Ultra-Luxury:Bespoke villa developments with Italian fit-out specifications and private marina infrastructure capture disproportionate margin concentration. These assets require bilingual construction supervisors familiar with Qatari building codes and Carrara quarry sourcing, creating skilled project management bottlenecks that delay handover timelines.
- Premium:Standardized luxury inventory with smart home integration from Turkish suppliers and Estidama Pearl compliance attracts institutional capital seeking yield sustainability.
- Mid-Range:Entry-level luxury in secondary Lusail districts targets first-time expatriate buyers with metro accessibility.
- Affordable Luxury:Compact apartments in emerging freehold zones offer GCC families portfolio diversification entry points.
Highest margin capture: Ultra-Luxury. Steepest volume growth: Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth GCC families concentrate transaction value in waterfront villa developments, while European institutional buyers target penthouses in Doha's financial district for portfolio diversification.
Doha Metropolitan Core
The Pearl-Qatar and West Bay Lagoon districts attract the highest foreign investment flows under expanded freehold rights. The Ministry of Justice's 2023 circular extending freehold eligibility to additional master-planned zones is activating institutional capital previously restricted to leasehold structures. Lusail City's integrated metro connectivity and marina completion are compressing holding-period risk for speculative capital.
Al Wakrah and Mesaieed Corridor
Emerging villa developments south of Doha target Qatari nationals seeking compound-style layouts for extended family housing. The Ministry of Municipality's coastal development buffers constrain waterfront plot supply, inflating land premiums beyond construction cost multiples. Secondary market liquidity remains shallow as infrastructure timelines extend into outer municipalities.
Al Khor and Northern Coast
Heritage district regeneration policies are opening boutique-scale luxury opportunities outside the Pearl-Lusail corridor. Cultural capital from European buyers seeks differentiated address positioning in restored coastal settlements. The Qatar Central Bank's mortgage leverage thresholds for non-resident purchasers compress transaction velocity in these emerging districts.
Al Shamal and Northwest Peninsula
Master-planned communities near the Saudi border attract portfolio diversification from Riyadh-based ultra-high-net-worth families. Direct developer-to-buyer digital platforms enable contract execution without physical site visits for repeat GCC purchasers. Smart home integration from Turkish suppliers is becoming baseline expectation in villa specifications.
Industrial Zone Buffer Districts
Proximity to Ras Laffan energy infrastructure creates premium positioning for executive housing compounds. Italian marble specifications and Estidama Pearl certification compliance elevate construction budgets while attracting European institutional screening. Skilled project management gaps for bilingual construction supervisors familiar with Qatari building codes delay handover timelines.
Qatar Luxury Residential Real Estate Market Competitive Landscape
Qatari master-developers anchor one tier; specialized property managers and boutique advisory firms hold differentiated positions in transaction facilitation and concierge services. Market structure concentrates around integrated land-banking and infrastructure-timing control, with four to six entities dominating pipeline access in designated freehold zones. Strategic archetypes include trophy asset holders, integrated master-developers, and bespoke villa specialists. Competitive moves center on direct digital platform deployment and family office advisory integration.
Within the integrated master-developer tier, United Development Company and Qatari Diar exemplify archetypes of land pipeline control and prestige asset positioning. Alfardan Properties occupies a distinct specialization in bespoke villa portfolios targeting privacy-seeking GCC families. These entities represent the convergence of infrastructure timing, foreign ownership registry navigation, and ultra-luxury specification delivery that defines competitive differentiation in Qatar's designated investment zones.
| Leading Market Players |
|---|
| Al Mirqab Real Estate |
| Al Mana Real Estate |
| Alfardan Properties |
| Al Asmakh Real Estate |
| United Development Company |
| Barwa Real Estate Group |
| Zukhrof Real Estate |
| Professional Real Estate Co. |
| Qatari Diar |
| Others |
Value Network & Pricing Analysis
Sovereign-backed master-developers and family-owned property groups anchor Qatar's luxury residential supply base, concentrating land pipeline control and infrastructure timing discipline that shapes pricing power across freehold zones. Their integrated development models compress margin leakage while foreign ownership registry navigation creates transaction friction premiums that filter into final unit pricing.
Pricing Analysis
Premium pricing for compressed lead times on Italian marble and Turkish smart home systems distinguishes trophy assets from standardized inventory with extended delivery windows. Three-tier pricing structure across ultra-luxury bespoke villas, premium certified apartments, and mid-range metro-accessible units reflects Estidama Pearl compliance grade and waterfront plot scarcity. Pricing pressure stems from Qatar Central Bank mortgage leverage caps elongating transaction cycles for non-resident purchasers. European institutional buyers exhibit lowest price sensitivity while first-time expatriate entrants in Lusail's emerging districts face compressed budgets.
Supply Chain Analysis
Skilled project management gaps for bilingual construction supervisors familiar with Qatari building codes and Italian fit-out specifications constrain delivery velocity in Doha's trophy developments. Carrara quarry marble, Turkish IoT building systems, and Estidama-compliant greywater recycling equipment flow through concentrated Mediterranean and Anatolian manufacturing corridors. Single-source vulnerability in premium travertine sourcing exposes developers to shipping cost fluctuations and extended lead times. Distribution runs through master-developer ERP platforms requiring manual reconciliation with municipal permitting portals, slowing unit release scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's luxury residential sector is transitioning from legacy leasehold structures toward digital twin-enabled asset management and predictive maintenance platforms that redefine operational expenditure forecasting. Smart building infrastructure and IoT sensor networks are displacing conventional property management approaches.
For Market Incumbents: Anticipate regulatory compression in mortgage leverage thresholds by deepening direct digital platform deployment for repeat GCC family purchasers. Integrate family office advisory services with estate planning and succession structuring to defend margin position against emerging boutique advisory competitors. Vertical integration into proprietary CRM portals with virtual staging capabilities creates channel control advantages. For New Entrants and Emerging Players: Cultural capital from European buyers seeking differentiated address positioning outside the Pearl-Lusail corridor represents underserved white space in Msheireb Downtown and Northern Coast heritage districts. Boutique-scale luxury regeneration projects with heritage district activation policies offer the most penetrable entry path. Direct developer-to-buyer digital transaction platforms enable contract execution without physical site visits. For Investors and Strategic Acquirers: Ministry of Justice circulars extending freehold rights to additional master-planned districts are the leading indicator that institutional capital flows from European and Asian HNWIs will accelerate. Long-term viability across the analysis window favors integrated master-developers with captive land pipelines and infrastructure timing control. Watch for Lusail City metro connectivity completion as the signal for secondary market liquidity activation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | United Development Company and Alfardan Properties compress operational expenditure forecasting from annual to real-time monitoring. |
| Freehold Zone Expansion Navigation | Master-developers leveraging Ministry of Justice registry expertise capture institutional capital previously restricted to leasehold structures. |
| Branded Residence Convergence | Hospitality-operated residential concepts penetrate Doha's inventory through concierge service bundling and fractional ownership structures. |
| Generational Asset Transfer Service Integration | Family office advisory bundling with property acquisition creates white space for estate planning and multi-jurisdictional holding vehicles. |
| Estidama Pearl Certification Acceleration | Compliance with Ministry of Municipality green building codes attracts European institutional screening and certification-driven price premiums. |
Research Methodology
Independent corroboration across master-developer pipeline disclosures, Ministry of Municipality permitting databases, and Qatar Central Bank mortgage lending circulars underwrites the qualitative findings in this study. Primary interviews with land acquisition directors, project development executives, foreign buyer registry specialists, and concierge service managers combined with secondary validation from municipal infrastructure timelines and freehold zone designation records. Bottom-up unit absorption tracking and top-down macroeconomic triangulation anchor the analytical framework.
Rate-of-change decomposition across property type, end user residency status, sales channel, and price tier dimensions structures the forecast framework over the projection horizon. CAGRs derive from segmented demand elasticity modeling and infrastructure completion timeline probability weighting. Qatar Central Bank leverage threshold adjustments and Lusail City metro connectivity milestones serve as key forecast sensitivity inputs.
Revisions become necessary when Ministry of Justice freehold zone designations shift, Qatar Central Bank mortgage caps tighten beyond modeled thresholds, or Carrara quarry supply disruptions extend Italian marble lead times materially. Forecasts reflect documented assumptions regarding infrastructure completion schedules and foreign ownership eligibility pathways. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market