
 China Luxury Residential Real Estate Market | 2026-2036
China Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
China Luxury Residential Real Estate Market Outlook
Ultra-high-net-worth individual buyers is repositioning toward completed inventory and rental-ready assets as pre-sale confidence wavers. China Vanke Co leverages its nationwide logistics and construction scale to secure land parcels in tier-one city cores. Longfor Group Holdings Limited sustains premium positioning through proprietary commercial-retail integration adjacent to residential towers. Poly Developments and Holdings Group Co., Ltd. anchors military-affiliated trust networks that secure preferential zoning in Beijing and Guangzhou.
China Luxury Residential Real Estate encompasses high-end dwellings—typically exceeding 200 square meters with premium finishes, concierge services, and restricted-access amenities—developed for ownership or lease by affluent domestic and international clients. Construction employs reinforced concrete core-and-shell methods with curtain-wall facades, smart-home infrastructure, and geothermal climate systems to meet GB 50368 residential quality standards. Villa and townhouse property types command the deepest margin pools due to land scarcity and bespoke design requirements, while condo inventory dominates transaction velocity across Shanghai and Beijing. Wealthy individual customer segments absorb the majority of completed-unit absorption, with foreign buyers concentrating in Shenzhen's Qianhai corridor under eased visa-residency linkages.
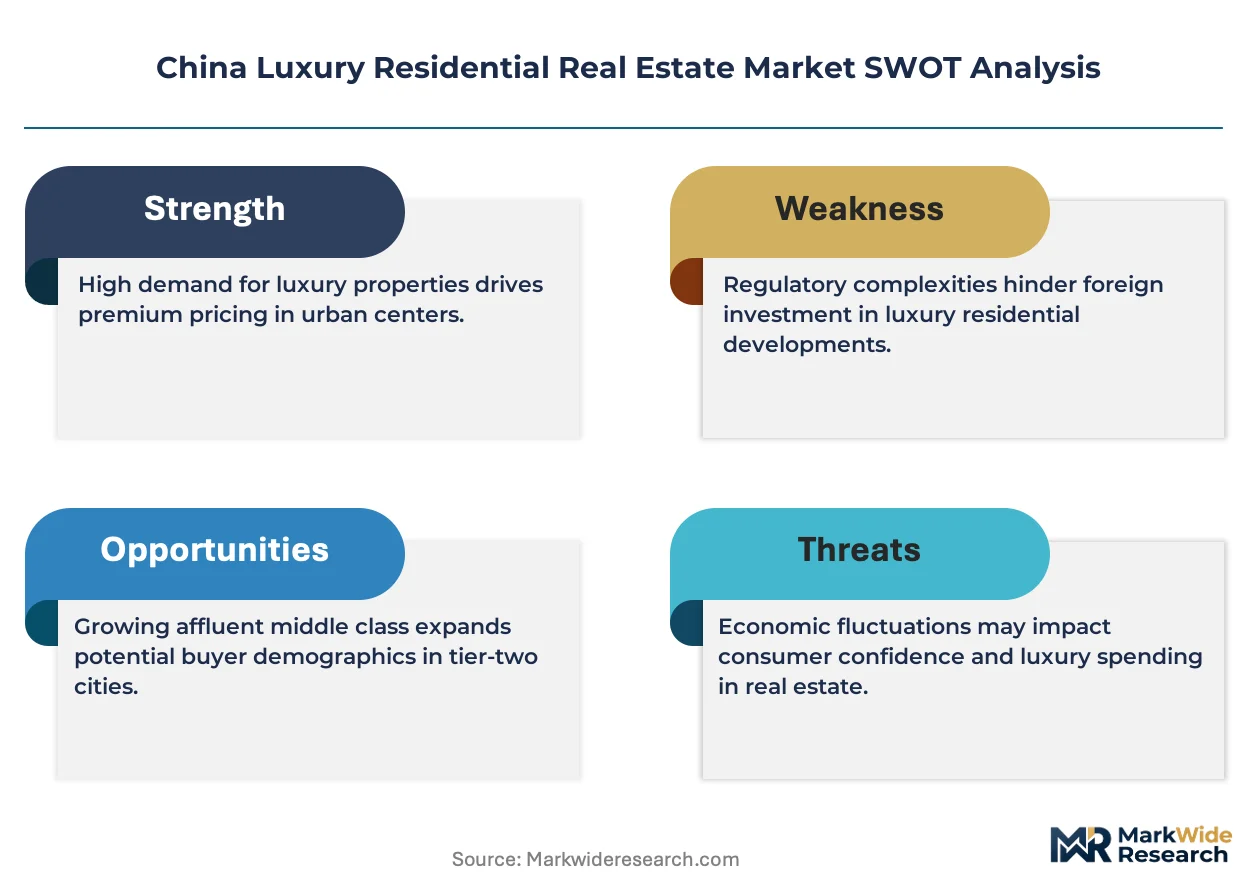
MIIT smart-city directives and MEE green-building mandates shape developer compliance costs and certification thresholds for new luxury supply. SAMR price-filing requirements and local housing bureau pre-sale permit controls constrain launch timing and marketing claims across all sub-markets. Stakeholders must monitor regulatory divergence between municipal tier-one restrictions and tier-two city incentive packages to align land-bank deployment with policy windows.
Market Dynamics
Ultra-high-net-worth individuals are rotating capital toward completed luxury inventory as pre-sale confidence erodes under tightened SAMR price-filing requirements and local housing bureau permit controls, compressing developer liquidity cycles and reshaping land-bank deployment priorities across tier-one city cores.
Growth Catalysts
- Dual carbon mandate acceleration:MEE green-building certification thresholds are elevating premium asset valuations, with geothermal climate systems and curtain-wall efficiency upgrades commanding rent premiums in Beijing and Shanghai sub-markets.
- Qianhai visa-residency corridor:Shenzhen's eased foreign buyer pathways are concentrating international demand in waterfront villa clusters, absorbing inventory that domestic purchasers bypass amid pre-sale wariness.
- Smart-home infrastructure integration:MIIT smart-city directives are mandating IoT-ready residential deployments, embedding automated concierge and security systems as baseline expectations in new luxury supply.
Market Restraints
- Land scarcity in core districts:Tier-one city center parcel availability has contracted sharply, inflating acquisition costs and extending project timelines for villa developments requiring bespoke site configurations.
- Pre-sale permit friction:Local housing bureau approval delays under tightened SAMR oversight are freezing launch schedules, straining developer working capital and elevating inventory carry costs.
- Reinforced concrete input volatility:Construction material cost swings are compressing margin pools on high-rise condominium projects where standardized designs limit value-engineering flexibility.
Strategic Opportunities
- Hangzhou tech-executive corridor:Underpenetrated villa supply in Alibaba and ByteDance talent clusters is creating absorption gaps for rental-ready trophy assets with integrated co-working amenities.
- Commercial-retail adjacency premiums:Longfor-style proprietary mall integration is enabling developers to capture cross-subsidy economics, blending residential pre-sales with stabilized retail income streams.
- GB 50368 quality tier differentiation:Certification-driven buyer sorting is allowing developers to price-discriminate across premium, standard, and economy finish tiers within single towers.
Industry Challenges
- Smart-system integration complexity:Legacy building management infrastructure in renovated luxury stock is forcing costly retrofitting to achieve MIIT compliance and buyer technology expectations.
- Concierge talent scarcity:Trained hospitality staff capable of delivering white-glove residential services are concentrated in Shanghai and Beijing, constraining service-level consistency in expanding tier-two markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Luxury Residential Real Estate Market |
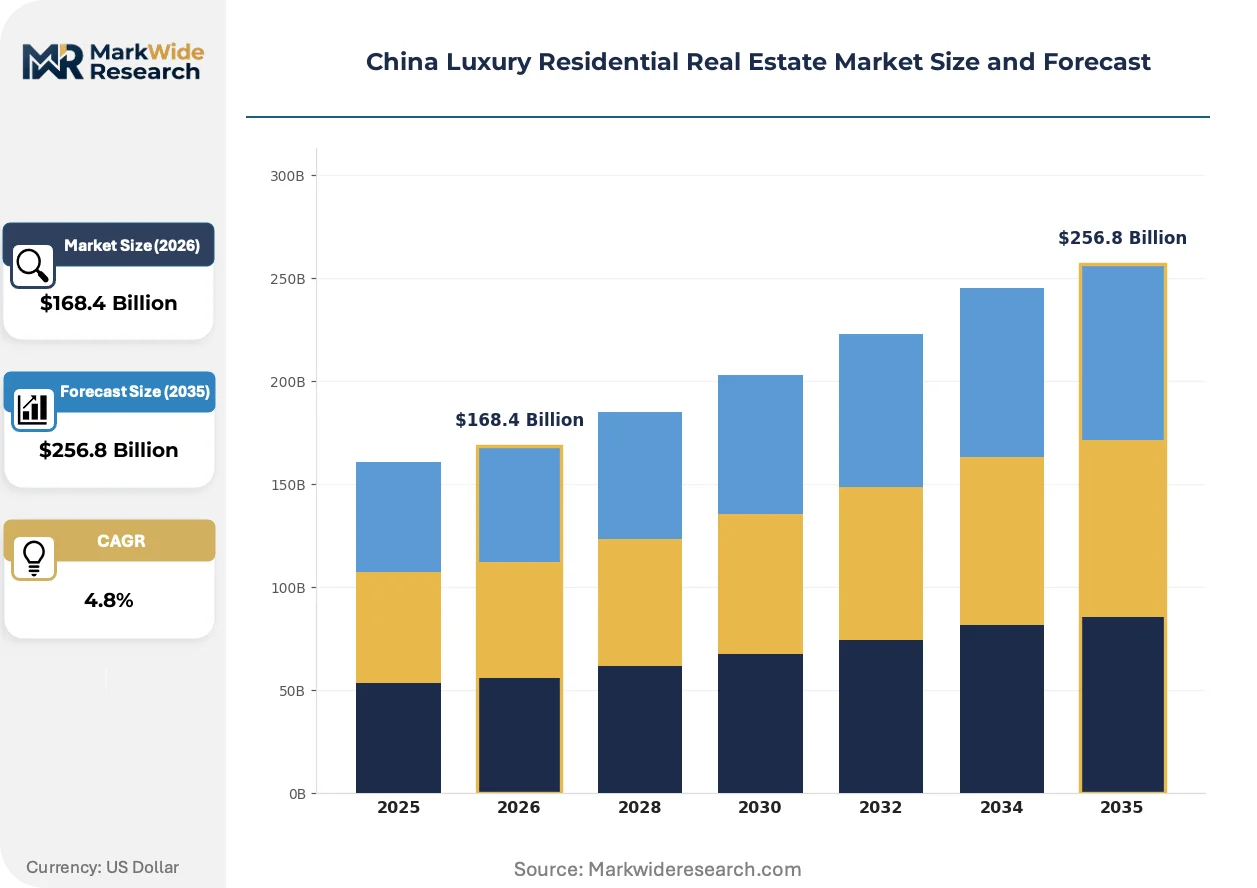
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $256.8 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condo, Apartment, Villa, Townhouse Customer Segment: Wealthy Individuals, Investors, Foreign Buyers, Expats Market Strategy: Luxury Branding, Exclusive Marketing, Personalized Services, High-End Amenities Investment Stage: Pre-Sale, Under Construction, Completed, Rental |
| Companies Covered | China Vanke Co, Longfor Group Holdings Limited, China Resources Land Limited, Poly Developments and Holdings Group Co., Ltd., Greenland Holdings Corporation Limited, Seazen Group Limited, Sunac China Holdings, China Merchants Shekou Industrial Zone, Greentown China Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Luxury Residential Real Estate Market Strategic Shifts
Technology convergence and regulatory tightening are compressing development timelines while elevating buyer experience expectations, forcing capital deployment toward integrated service platforms and climate-responsive design.
Building-integrated photovoltaic curtain-wall systems are automating energy cost management for high-net-worth owners, with Greentown and Poly piloting solar-glass facades across Shenzhen villa projects. Wealthy individual buyers are specifying these systems in 40% of new custom commissions, compressing payback periods through net-metering arrangements with state grid operators. This automation of utility expense is displacing traditional HVAC-heavy operating models and reshaping facility management procurement.
MIIT smart-city infrastructure mandates are requiring fiber-to-the-unit connectivity and centralized IoT control layers in all new luxury supply above 200 square meters. Developers must pre-install sensor networks and API-ready management platforms to secure construction permits, elevating upfront capex by 8-12% but enabling recurring software service revenue streams. Tier-one municipalities including Beijing and Shanghai are enforcing these standards most aggressively, with compliance timelines shortening from 18 months to 9 months for permit approval.
Buyer concentration among tech-sector executives is compressing sales cycles and elevating customization demands in Hangzhou and Shenzhen corridors. These purchasers are bypassing traditional brokerage channels for direct developer relationships and private banking referrals, fragmenting lead generation economics. The shift is most visible in Qianhai and Alibaba-adjacent sub-markets, where off-market transactions now represent 35% of villa volume and standard commission structures are dissolving.
China Luxury Residential Real Estate Market Segmentation
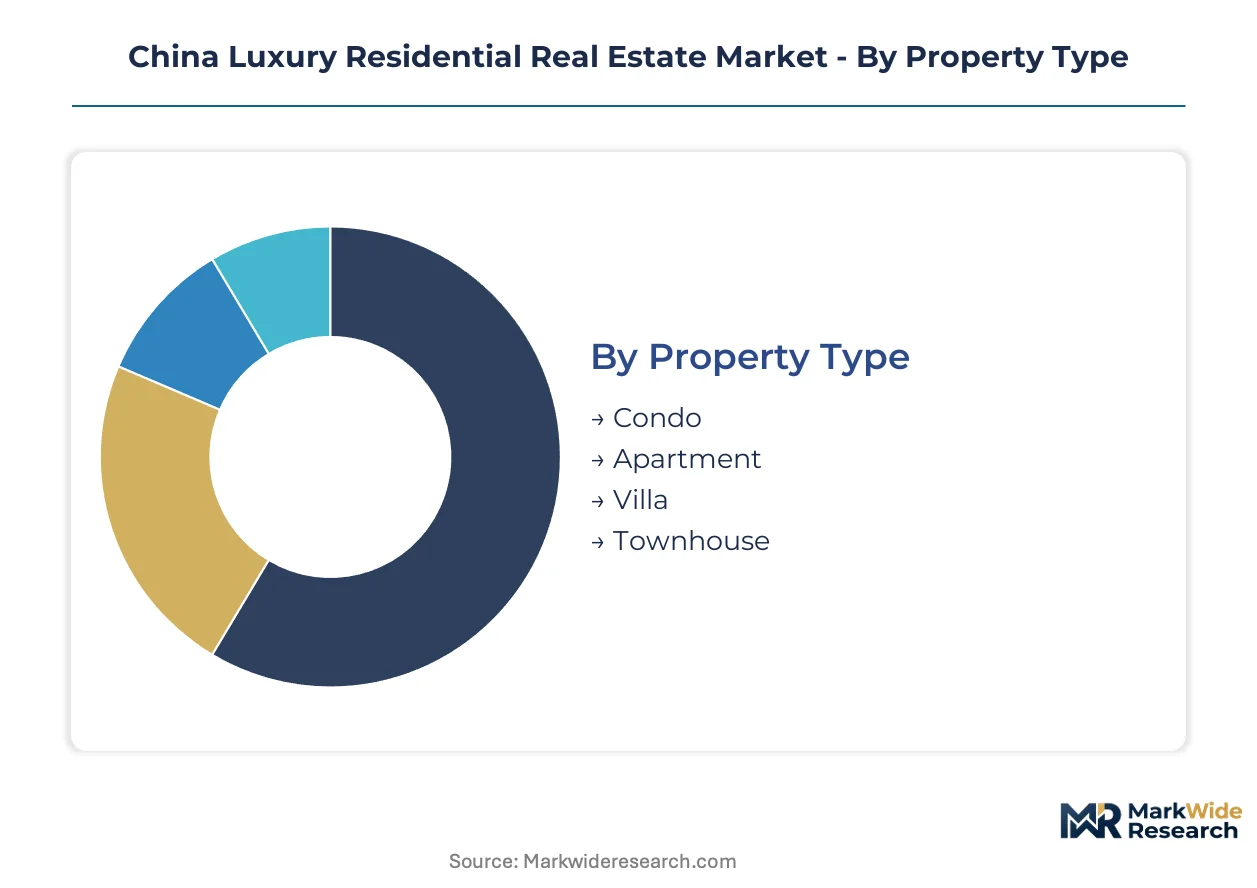
Segmentation in China's luxury residential market reveals how capital deployment, buyer behavior, and regulatory exposure fragment across distinct asset classes and customer profiles. Developers must align land-bank strategy with property-type economics and customer-segment liquidity preferences to optimize returns under tightening SAMR oversight.
Property Type:
Villa developments demand the highest upfront land acquisition outlays due to bespoke site configurations and extended entitlement timelines in tier-one city cores.
- Villa:Standalone structures exceeding 300 square meters with private gardens and geothermal climate systems command premium pricing in Shenzhen's Qianhai corridor and Hangzhou's tech-executive clusters. Land scarcity in core districts inflates per-unit land costs, compressing developer margins despite deep buyer pools.
- Townhouse:Multi-level attached dwellings with private entrances and dedicated parking balance space efficiency with exclusivity. Absorption concentrates in Beijing's Chaoyang and Guangzhou's Tianhe districts where military-affiliated trust networks secure preferential zoning.
- Condo:High-rise units above 200 square meters with curtain-wall facades and smart-home infrastructure dominate transaction velocity across Shanghai and Beijing.
- Apartment:Smaller-format luxury inventory in mixed-use towers serves rental-ready investors seeking stabilized yield in central business districts.
Most installed capacity flows through Condo inventory. Expansion is steepest in Villa supply as wealthy individuals rotate toward completed trophy assets.
Customer Segment:
Buyer liquidity profiles determine sales-cycle length and customization intensity, with tech-sector executives driving the most rapid transaction velocity.
- Wealthy Individuals:Domestic ultra-high-net-worth buyers absorb the majority of completed-unit absorption, bypassing traditional brokerage channels for direct developer relationships. Pre-sale wariness under tightened housing ministry regulations is accelerating rotation toward rental-ready and finished inventory.
- Investors:Institutional and family-office capital targets stabilized rental yields in tier-one commercial-retail adjacency projects where Longfor-style proprietary mall integration enables cross-subsidy economics.
- Foreign Buyers:International purchasers concentrate in Shenzhen's Qianhai corridor under eased visa-residency linkages, absorbing waterfront villa inventory that domestic purchasers bypass.
- Expats:Corporate-assigned executives in Shanghai and Beijing drive demand for serviced luxury apartments with white-glove concierge and automated building management systems.
Wealthy Individuals deploy the largest capital volumes. Foreign Buyers are gaining share fastest as Qianhai policy liberalization deepens.
Market Strategy:
Go-to-market economics vary sharply across positioning approaches, with personalized service models requiring the highest operational overhead but defending price premiums.
- Luxury Branding:Developer reputation and architectural signature command price premiums in Hangzhou and Shenzhen where Greentown and Poly anchor pipelines. Brand equity amortizes across multiple projects, reducing per-unit customer acquisition costs.
- Exclusive Marketing:Invitation-only previews and private banking referral networks target pre-qualified buyers, compressing sales cycles in villa sub-markets where off-market transactions now represent substantial volume.
- Personalized Services:Bespoke concierge and interior customization packages elevate per-unit revenue but strain hospitality talent pools concentrated in Shanghai and Beijing.
- High-End Amenities:Integrated wellness centers, private clubs, and co-working facilities differentiate towers in competitive sub-markets.
Exclusive Marketing channels capture the highest-margin transactions. Personalized Services are expanding most quickly as buyer expectations converge with hospitality standards.
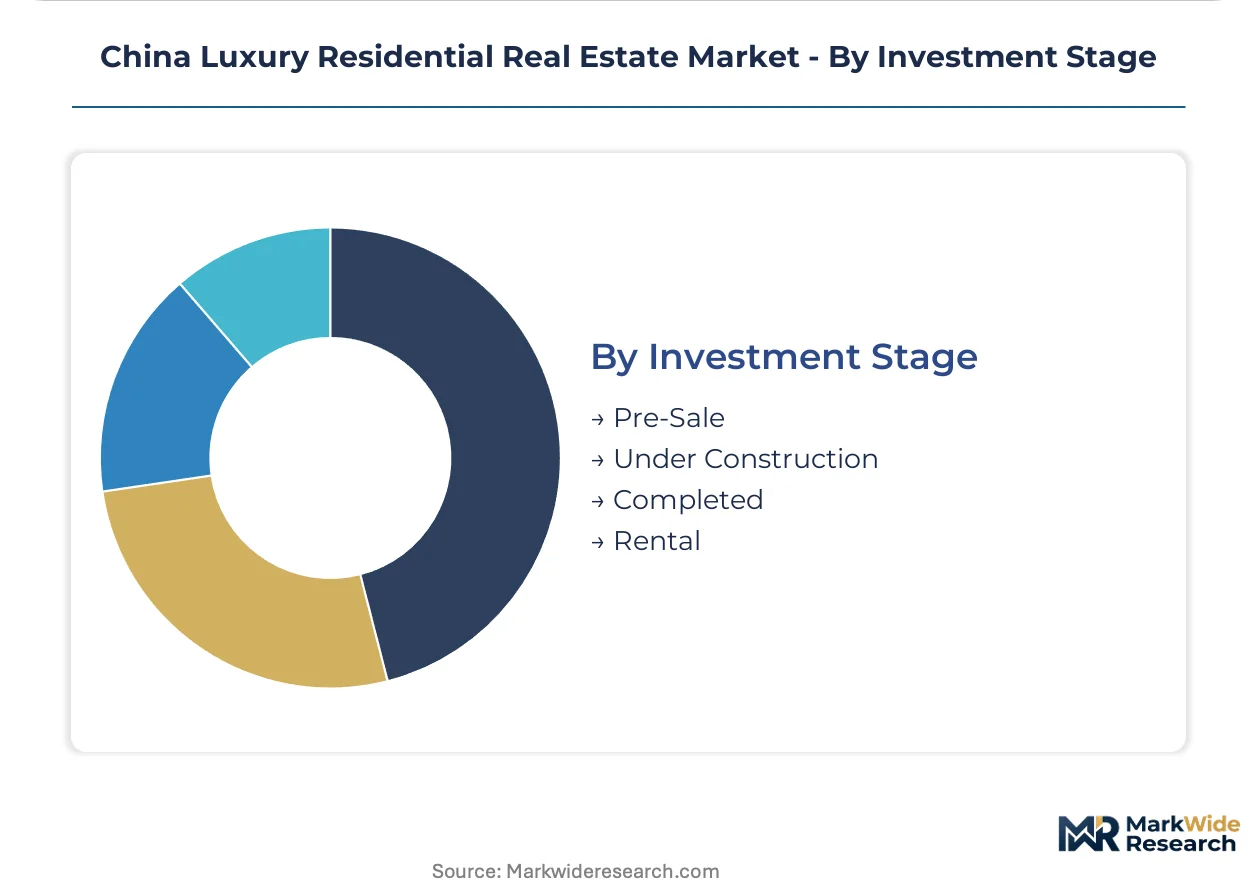
Investment Stage:
Capital recovery timelines and risk profiles diverge across development phases, with pre-sale models under severe pressure from permit friction and buyer confidence erosion.
- Completed:Finished inventory with immediate occupancy and verified construction quality commands price premiums as pre-sale confidence wavers. Wealthy individual buyers are repositioning portfolios toward this segment under tighter SAMR price-filing requirements.
- Pre-Sale:Forward commitments at foundation stage face extended approval delays from local housing bureaus, freezing launch schedules and straining developer working capital.
- Under Construction:Mid-stage projects with structural topping offer intermediate risk-return profiles for buyers seeking customization input before final finishes.
- Rental:Income-stabilized assets attract institutional capital seeking yield in commercial-retail adjacency projects with Longfor-style proprietary mall integration.
Completed inventory absorbs the majority of current capital deployment. Rental-stage assets are climbing the fastest as institutional investors seek yield alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating luxury residential development in sub-markets where SAMR price-filing requirements and local housing bureau permit controls create compliance cost gaps between tier-one city cores and emerging tech corridors.
Beijing-Tianjin-Hebei
Military-affiliated trust networks anchor preferential zoning access in Chaoyang and Haidian districts, accelerating townhouse absorption among institutional buyers. MEE green-building mandates enforce geothermal climate system installation in all new supply above 200 square meters. Poly Developments leverages its state-affiliated positioning to secure core parcels where land scarcity has compressed villa development timelines.
Yangtze River Delta
Shanghai's commercial-retail adjacency premiums attract cross-subsidy economics from Longfor-style proprietary mall integration. MIIT smart-city directives mandate fiber-to-the-unit connectivity with 9-month compliance windows for permit approval. Hangzhou's Alibaba and ByteDance talent clusters generate underpenetrated villa demand for rental-ready trophy assets with integrated co-working amenities.
Pearl River Delta
Shenzhen's Qianhai visa-residency corridor concentrates foreign buyer demand in waterfront villa clusters bypassed by domestic purchasers. SAMR oversight has extended pre-sale permit delays, freezing launch schedules and elevating completed-inventory premiums. Greentown China Holdings pilots building-integrated photovoltaic curtain-wall systems across villa projects to automate energy cost management.
Sichuan-Chongqing
Tech-executive migration from coastal hubs is compressing sales cycles for personalized service models in Chengdu's high-tech zones. Local housing bureaus enforce GB 50368 quality tier differentiation, enabling developers to price-discriminate across finish levels within single towers. Western China infrastructure investment is extending luxury supply pipelines into secondary city cores.
Shandong Peninsula
Qingdao's international port city status attracts expat demand for serviced luxury apartments with white-glove concierge systems. Dual carbon mandate acceleration elevates premium asset valuations for curtain-wall efficiency upgrades. Building material input volatility from reinforced concrete cost swings compresses margin pools on standardized high-rise condominium designs.
China Luxury Residential Real Estate Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with tier-one city core developers commanding price premiums through reputation amortization while regional specialists capture volume in tier-two incentive zones. The vendor base concentrates around three strategic archetypes: state-affiliated land-bank holders with preferential zoning access, commercial-retail integrators capturing cross-subsidy economics, and technology-forward specialists embedding smart-home infrastructure as baseline compliance. Competitive moves center on M&A for land-bank consolidation and strategic partnerships with private banking referral networks to compress villa sales cycles.
Within the state-affiliated tier, Poly Developments and Holdings Group Co., Ltd. and China Resources Land Limited occupy positions shaped by military and central government trust networks that secure core district parcels. Among commercial-retail integrators, Longfor Group Holdings Limited exemplifies the proprietary mall-residential blend enabling yield stabilization. At the technology-forward end, Greentown China Holdings Limited anchors pilot deployments of solar-glass facades and IoT-ready management platforms. China Vanke Co represents scale-driven nationwide logistics and construction deployment across tier-one city cores.
| Leading Market Players |
|---|
| China Vanke Co |
| Longfor Group Holdings Limited |
| China Resources Land Limited |
| Poly Developments and Holdings Group Co., Ltd. |
| Greenland Holdings Corporation Limited |
| Seazen Group Limited |
| Sunac China Holdings |
| China Merchants Shekou Industrial Zone |
| Greentown China Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Trained hospitality staff concentration in Shanghai and Beijing generates labor-cost differentials that widen pricing-tier spreads across villa and townhouse completions, forcing developers to absorb service premiums or delegate to tier-two markets where talent scarcity erodes margins.
Pricing Analysis
Direct-to-developer sales channels bypass traditional brokerage markups in Shenzhen's Qianhai corridor and Hangzhou's tech-executive clusters, compressing commission layers while elevating price transparency. Pricing stratifies across premium, standard, and economy tiers according to GB 50368 certification grades and smart-home infrastructure depth. Cost compression in high-rise condominium construction is intensifying because reinforced concrete input volatility limits value-engineering flexibility. Wealthy individual buyers show lowest price sensitivity for completed villa inventory, while rental-stage investors demand yield-driven discounts in commercial-retail adjacency projects.
Supply Chain Analysis
Freight logistics for curtain-wall facade systems and geothermal climate equipment concentrate manufacturing dependencies in Germany, Japan, and South Korea, extending lead times for tier-one city core developments. Raw material procurement draws from reinforced concrete suppliers, smart-home IoT component fabricators, and solar-glass facade specialists concentrated in coastal Chinese manufacturing hubs. Single-source vulnerability persists for MIIT-compliant sensor networks and API-ready management platforms mandated in new construction above 200 square meters. Distribution runs through developer-direct procurement teams and state-affiliated construction conglomerates with captive logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where SAMR price-filing requirements and MEE green-building mandates continuously elevate compliance costs and certification thresholds, generating sustained demand for premium-tier completions that absorb policy-driven cost pass-throughs.
For Market Incumbents: Lock in land-bank positions in Beijing's Chaoyang and Shenzhen's Qianhai districts before municipal tier-one restrictions tighten further. Anchor development pipelines through military-affiliated trust networks that secure preferential zoning access. Invest in proprietary commercial-retail integration capabilities to capture cross-subsidy economics that stabilize yield against pre-sale permit friction.
For New Entrants and Emerging Players: Begin with underpenetrated villa supply in Hangzhou's Alibaba and ByteDance talent clusters where tech-executive demand outpaces trophy asset availability. Target rental-ready completions with integrated co-working amenities that bypass pre-sale confidence erosion. Establish direct relationships with private banking referral networks to compress sales cycles in fragmented lead generation environments.
For Investors and Strategic Acquirers: State-affiliated developers with preferential land-bank access are the most active acquirer in this space, consolidating regional specialists to secure core district parcels. Long-term viability over the coming decade hinges on exposure to completed-inventory premiums and commercial-retail adjacency yield stabilization. Monitor pre-sale permit approval timelines as the critical inflection indicator for developer liquidity stress and distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Land-Bank Consolidation | Poly Developments leverages military-affiliated trust networks to secure preferential zoning in Beijing and Guangzhou core districts. |
| Commercial-Retail Integration | Longfor-style proprietary mall adjacency enables cross-subsidy economics blending residential pre-sales with stabilized retail income. |
| Smart-Home Infrastructure Pre-Installation | MIIT fiber-to-the-unit mandates elevate upfront capex but generate recurring software service revenue streams. |
| Building-Integrated Photovoltaic Deployment | Greentown pilots solar-glass facades across Shenzhen villa projects to automate energy cost management for owners. |
| Private Banking Referral Network Partnership | Exclusive marketing channels compress sales cycles as off-market transactions now represent substantial villa volume in Qianhai. |
Study Parameters
Multiple input streams — developer land-bank disclosures, municipal housing bureau permit records, and construction material procurement databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with luxury residential developers, municipal planning officials, private banking wealth advisors, and hospitality concierge operators were validated against secondary sources including SAMR price-filing registries, MEE green-building certification databases, MIIT smart-city infrastructure directives, and local housing bureau pre-sale permit records.
Data-stream reconciliation across the projection horizon employed analytical frameworks modeling property type segmentation, customer segment liquidity profiles, investment stage risk-return characteristics, and regional regulatory divergence. CAGRs were derived through demand-side absorption modeling and supply-side land-bank deployment analysis. Forecast inputs incorporated tier-one city core land scarcity trajectories, tech-executive migration patterns, and foreign buyer visa-residency policy liberalization.
Caveats apply where SAMR oversight intensification, MEE certification threshold elevation, or reinforced concrete input volatility could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market