
 Oman Luxury Residential Real Estate Market | 2026-2036
Oman Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Luxury Residential Real Estate Market Analytics
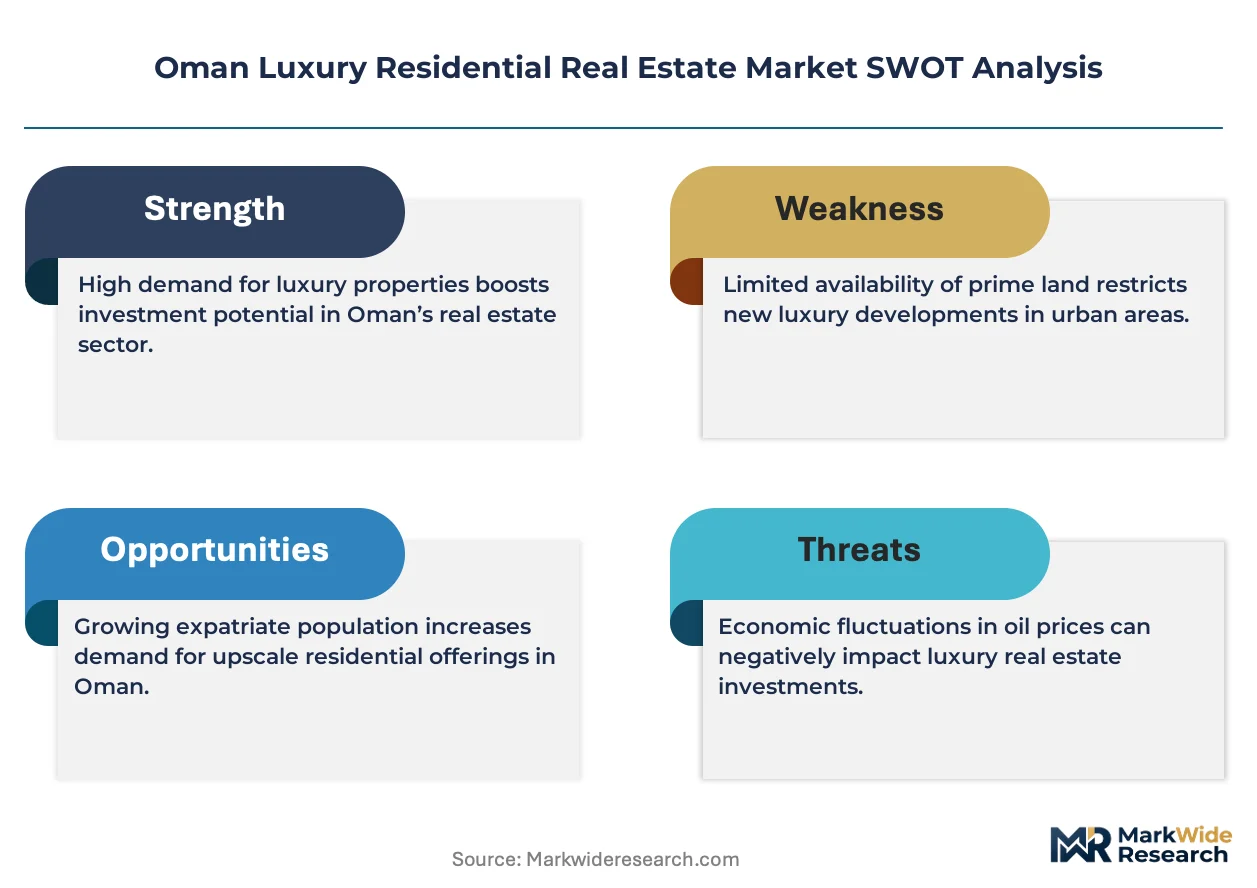
Ministry of Housing and Urban Planning permit streamlining is broadening developer access to premium coastal zones. Tibiaan Properties leverages its integrated master-planning expertise across Muscat's shoreline corridors. Muriya Tourism Development anchors its position through tourism-linked residential offerings in Dhofar and Al Batinah. AL Mouj Muscat dominates the marina-integrated segment with controlled berth access and lifestyle amenity bundling.
Oman luxury residential real estate comprises freehold and long-leasehold dwellings priced above mainstream market thresholds, typically featuring bespoke architectural finishes, smart home infrastructure, and concierge-managed services. These assets function as primary residences, portfolio diversification vehicles, and legacy wealth preservation instruments for domestic and regional buyers. Villas command the deepest buyer pools among property types, while penthouses represent the fastest-appreciating tier on a per-square-meter basis. The ultra-high-net-worth price tier captures disproportionate margin concentration despite lower transaction velocity.
The Ministry of Housing and Urban Planning and Oman Tourism Development Authority jointly shape project viability through zoning overlays and tourism-residency linkage programs. Central Bank of Oman macro-prudential rules on mortgage loan-to-value ratios directly filter eligible buyer cohorts and transaction liquidity. Stakeholders must monitor how evolving freehold zone designations and residency-by-investment criteria redefine competitive positioning across Muscat, Salalah, and Sohar development corridors.
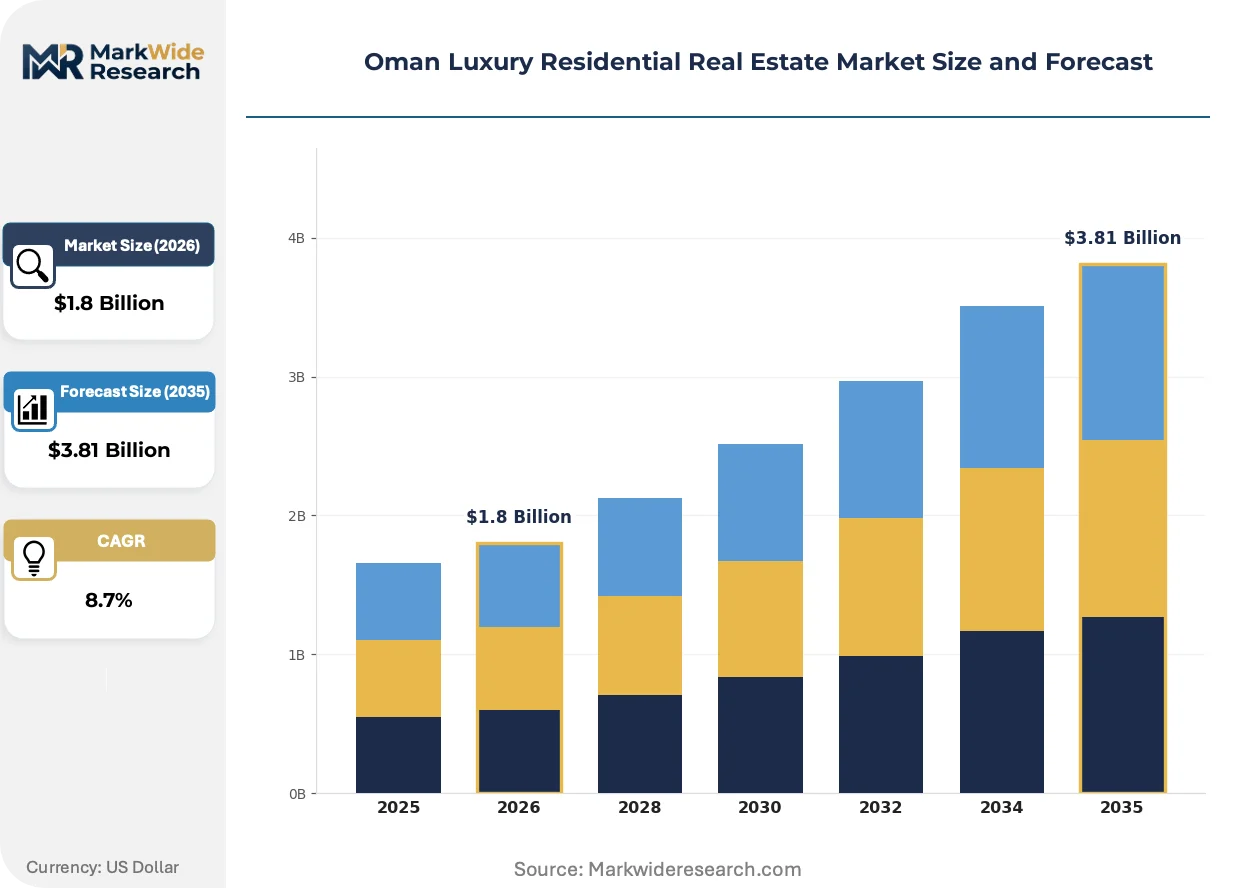
Market Dynamics
The Ministry of Housing and Urban Planning's streamlined building permit frameworks are accelerating project timelines across Muscat's waterfront corridors, compressing developer entry cycles and expanding viable coastal supply zones.
Growth Catalysts
- Freehold Zone Expansion:The Ministry's revised coastal zoning overlays are unlocking premium shoreline parcels for integrated mixed-use developments, attracting Gulf Cooperation Council capital into previously restricted districts.
- Marina-Living Infrastructure:Controlled-berth residential concepts anchor buyer premiums in Al Mouj and Saraya Bandar Jissah, creating scarcity-driven pricing power for developers with waterfront master-planning capabilities.
- Tourism-Residency Linkage:Oman Tourism Development Authority programs are channeling hospitality investment into adjacent residential inventory, particularly in Dhofar and Al Batinah corridors.
Market Restraints
- Labor Skill Concentration:Specialized marine construction and smart-home integration expertise concentrates in Muscat, inflating project costs for developments in Salalah and Sohar.
- Input Cost Volatility:Imported bespoke finishes and concierge-grade appliance packages face freight cost fluctuations that compress developer margins on fixed-price contracts.
- Mortgage Liquidity Filters:Central Bank of Oman loan-to-value macro-prudential rules restrict eligible buyer pools, particularly affecting first-time regional investors seeking leverage.
Strategic Opportunities
- Dhofar Underpenetration:Salalah's tourism-linked residential inventory remains undersupplied relative to visitor growth, creating white space for climate-resilient villa concepts.
- Smart Home Convergence:Integration of IoT infrastructure with concierge service platforms enables subscription revenue streams beyond unit sales.
- Residency-by-Investment Tailwinds:Evolving long-term visa frameworks for property owners are repositioning Oman against competing Gulf jurisdictions for legacy wealth preservation buyers.
Industry Challenges
- Master-Planner Talent Scarcity:Integrated shoreline development expertise resides with a limited cohort of firms, creating bidding competition and timeline risk for new entrants.
- Certification Timeline Compression:Tourism Development Authority hospitality-residential hybrid classifications require extended compliance review, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Luxury Residential Real Estate Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Villas, Apartments, Penthouse, Townhouses Price Tier: Ultra-High-Net-Worth, High-End, Mid-Range, Affluent Architectural Style: Contemporary, Traditional, Modern, Mediterranean End User: First-Time Buyers, Investors, Expats, Retirees |
| Companies Covered | Tibiaan Properties, Muriya Tourism Development, AL Mouj Muscat, ORIS, Wujha Real Estate, Dar Global, Muscat Bay Real Estate Development, Muscat Real Estate Development, Saraya Bandar Jissah, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Luxury Residential Real Estate Market Evolving Landscape
Digital infrastructure and service-layer unbundling are restructuring how luxury residential value is packaged, delivered, and monetized across Oman's coastal development corridors.
Integrated smart-home ecosystems with centralized concierge interfaces are overtaking standalone automation systems in premium villa specifications. Ultra-high-net-worth buyers from Saudi Arabia and the UAE now expect seamless platform control over climate, security, and service ordering as standard. This compression of amenity access into single interfaces is reducing differentiation power for developers without technology partnerships.
The Ministry of Housing and Urban Planning's building permit streamlining mandates are forcing faster design-review cycles, compressing traditional architectural consultation timelines. Developers are responding with pre-approved modular luxury templates that accelerate approvals while maintaining bespoke façade customization. Muscat's Al Mouj corridor has seen the most rapid adaptation to this regulatory velocity.
Direct developer-to-buyer digital channels are fragmenting traditional brokerage concentration in waterfront segments. High-net-worth Gulf buyers now expect virtual reality walkthroughs and blockchain-secured transaction documentation before site visits. This disintermediation is most visible in penthouse sales, where privacy preferences and transaction speed requirements favor platform-mediated relationships over conventional agent networks.
Oman Luxury Residential Real Estate Market Segmentation
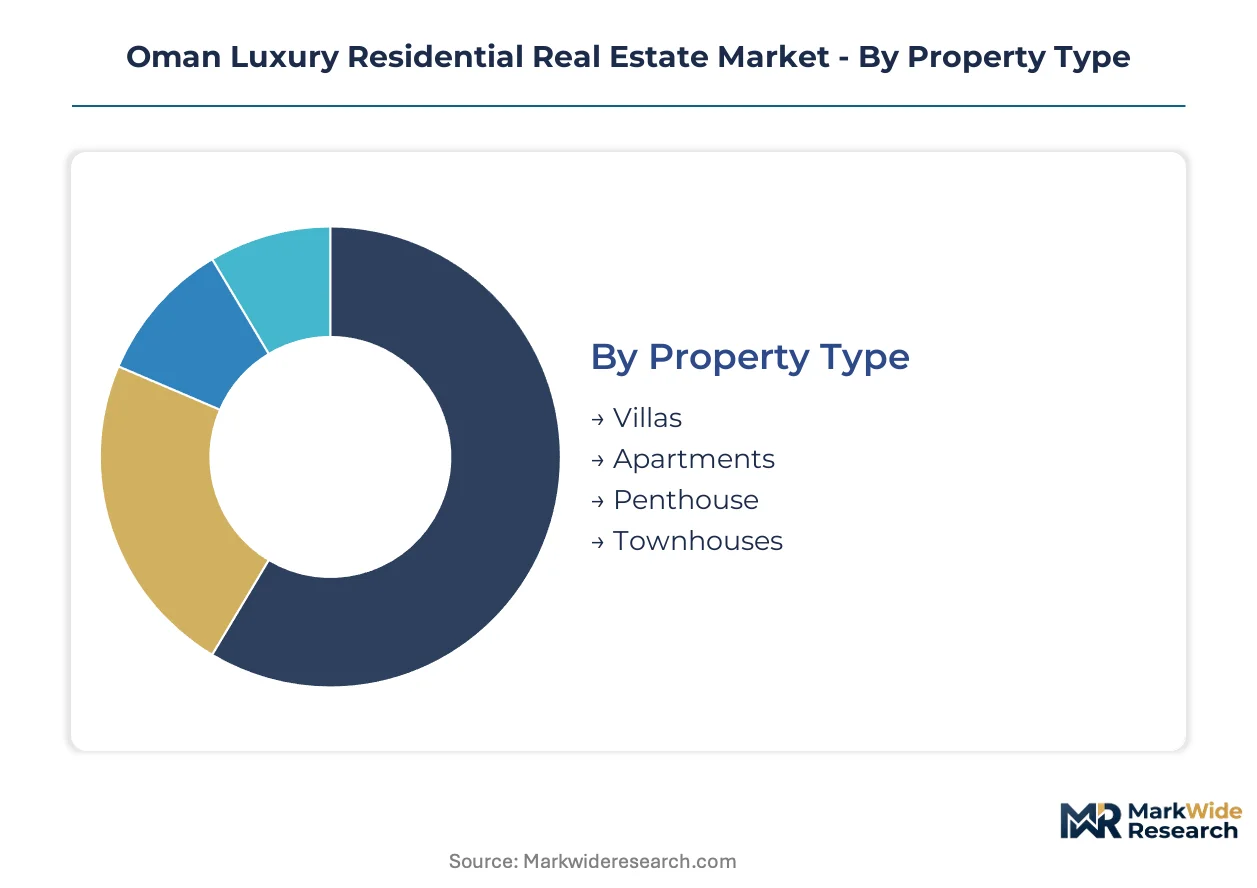
Segmentation in Oman's luxury residential market reveals how buyer priorities diverge across wealth thresholds, lifestyle preferences, and investment horizons. Developers targeting Al Mouj and Saraya Bandar Jissah corridors must align product architecture with specific buyer-decision hierarchies rather than assuming uniform demand curves across coastal zones.
Property Type:
Buyers prioritize spatial configuration and privacy gradients when selecting dwelling formats, with berth access and outdoor amenity ratios driving premiums in marina-integrated districts.
- Villas:Freestanding structures with private gardens and dedicated parking courts dominate family-oriented demand in Al Mouj and Saraya Bandar Jissah. Controlled-berth access and concierge-managed maintenance contracts deepen buyer commitment in waterfront master-plans.
- Penthouses:Top-floor units with panoramic sea views command the steepest per-square-meter appreciation trajectories across Muscat's supply-constrained high-rise inventory. Privacy preferences and platform-mediated transaction channels accelerate sales velocity among Saudi and UAE ultra-high-net-worth buyers.
- Apartments:Mid-rise and high-rise units serve portfolio diversification needs for regional investors seeking rental yield exposure.
- Townhouses:Attached dwellings with shared wall configurations balance space efficiency against community amenity access in price-sensitive tiers.
Villas lead on scale; penthouses lead on momentum.
Price Tier:
Wealth stratification determines access to bespoke finishes, smart-home infrastructure depth, and concierge service bundling across Oman's coastal developments.
- Ultra-High-Net-Worth:Custom-built residences above mainstream thresholds feature imported bespoke materials and dedicated lifestyle management teams. Disproportionate margin concentration rewards developers despite lower transaction frequency.
- High-End:Semi-custom specifications with premium appliance packages and integrated IoT infrastructure attract legacy wealth preservation buyers from Gulf Cooperation Council states.
- Mid-Range:Standardized luxury finishes with limited customization options serve first-time regional investors.
- Affluent:Entry-luxury positioning with modular templates and accelerated approval timelines captures emerging domestic buyer cohorts.
Ultra-High-Net-Worth dominates margin capture; High-End expands most quickly.
Architectural Style:
Aesthetic preferences signal cultural identity and resale liquidity expectations among Oman's geographically dispersed buyer base.
- Contemporary:Clean-lined geometries with extensive glazing and minimal ornamentation align with younger Gulf buyer preferences in Muscat's waterfront corridors.
- Traditional:Mashrabiya screens, courtyard configurations, and regional material palettes preserve cultural resonance for domestic legacy buyers.
- Modern:Mid-century influenced forms with open-plan living spaces serve expatriate professional demand.
- Mediterranean:Stucco exteriors, terracotta roofing, and arched openings appeal to European retiree segments in Dhofar's climate-resilient zones.
Contemporary commands developer attention; Traditional anchors domestic loyalty.
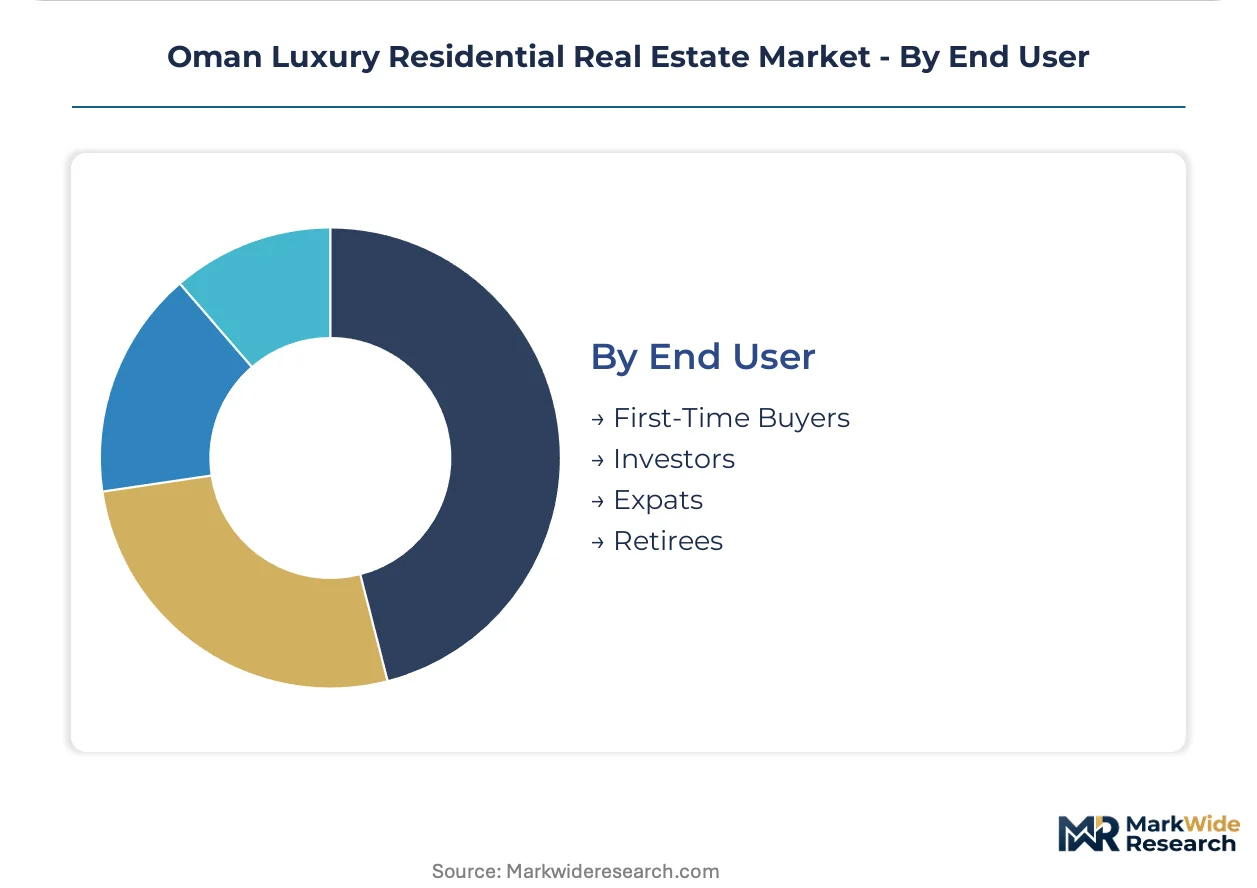
End User:
Occupancy intent shapes financing structure, service tier requirements, and resale horizon calculations across buyer cohorts.
- Investors:Regional capital from Saudi Arabia and UAE targets rental yield and capital appreciation in freehold-designated coastal zones. Central Bank of Oman loan-to-value filters constrain leverage-dependent entrants.
- Expats:Long-term residency visa holders prioritize proximity to international schools and healthcare infrastructure in Muscat's integrated developments.
- First-Time Buyers:Young Omani professionals entering the luxury segment through family wealth transfer or high-income employment.
- Retirees:Climate-seeking European and Gulf nationals targeting Dhofar's monsoon-season amenities and lower operational costs.
Investors drive transaction volume; Expats gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized marine construction and smart-home integration expertise concentrates in Muscat, inflating project costs for developments in Salalah and Sohar. The Ministry of Housing and Urban Planning's permit streamlining mandates are accelerating design-review cycles across coastal zones.
Muscat Governorate
Ultra-high-net-worth buyers from Saudi Arabia and the UAE drive penthouse demand in waterfront corridors. The Ministry of Housing and Urban Planning's revised coastal zoning overlays unlock premium shoreline parcels for integrated mixed-use developments. Al Mouj and Saraya Bandar Jissah anchor the marina-integrated segment with controlled-berth access and lifestyle amenity bundling.
Dhofar Governorate
Salalah's tourism-linked residential inventory remains undersupplied relative to visitor growth, creating white space for climate-resilient villa concepts. Oman Tourism Development Authority programs channel hospitality investment into adjacent residential inventory. The monsoon-season amenities and lower operational costs attract climate-seeking European and Gulf retirees.
Al Batinah Region
First-time regional investors target mid-rise apartments for portfolio diversification and rental yield exposure. Central Bank of Oman loan-to-value macro-prudential rules constrain leverage-dependent entrants. Sohar's industrial corridor expansion supports emerging domestic buyer cohorts entering the luxury segment through high-income employment.
Al Dakhiliyah Governorate
Traditional architectural preferences among domestic legacy buyers preserve demand for mashrabiya screens and courtyard configurations. The Ministry of Housing and Urban Planning's building permit frameworks apply standardized timelines across interior zones. Nizwa's cultural tourism infrastructure supports secondary residence demand from Muscat-based families.
Oman Luxury Residential Real Estate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Oman's luxury residential development pipeline. The market structure concentrates around integrated master-planners with shoreline expertise and tourism-linked residential operators. Three archetypes dominate: waterfront master-planners, hospitality-residential hybrid developers, and regional capital-backed project vehicles. Dominant competitive moves include strategic partnerships with technology providers for smart-home integration and geographic expansion into underserved Dhofar corridors.
Among waterfront master-planners, Tibiaan Properties, AL Mouj Muscat, and Saraya Bandar Jissah occupy positions defined by controlled-berth access and integrated marina-living concepts. Muriya Tourism Development exemplifies the hospitality-residential hybrid archetype through its tourism-linked offerings. These developers represent varying approaches to the scarcity-driven pricing power available in premium coastal zones.
| Leading Market Players |
|---|
| Tibiaan Properties |
| Muriya Tourism Development |
| AL Mouj Muscat |
| ORIS |
| Wujha Real Estate |
| Dar Global |
| Muscat Bay Real Estate Development |
| Muscat Real Estate Development |
| Saraya Bandar Jissah |
| Others |
Value Network & Pricing Analysis
Imported marble and travertine price indices cascade through Oman's luxury residential supply chain, compressing margins on fixed-price villa contracts while amplifying berth-access premiums in waterfront segments. Central Bank of Oman loan-to-value thresholds filter buyer liquidity, forcing developers to absorb freight volatility or pass costs through to cash-rich ultra-high-net-worth purchasers.
Pricing Analysis
Bundled concierge-berth packages versus unbundled unit-only sales define pricing architecture across Muscat's waterfront corridors. Three-tier pricing structure across ultra-high-net-worth, high-end, and mid-range levels separates bespoke finish tiers, with certification depth from the Ministry of Housing and Urban Planning acting as a price gate. Cost compression in mid-range inventory intensifies because freight volatility on Italian stone and German appliance imports outpaces local substitution options. First-time regional investors from Saudi Arabia and the UAE exhibit highest price sensitivity due to leverage constraints, while domestic legacy buyers show lowest sensitivity on legacy wealth preservation purchases.
Supply Chain Analysis
Ministry of Housing and Urban Planning permit qualification timelines gate developer access to premium coastal zones, concentrating viable supply among integrated master-planners with pre-approved template libraries. Geographic supply concentration clusters in Italy for bespoke stone finishes, Germany for concierge-grade appliance packages, and the UAE for smart-home integration expertise. Raw material dependencies span imported travertine, marine-grade aluminum for berth infrastructure, and IoT sensor arrays. Single-source vulnerability runs through Italian quarry networks for specified stone grades. Distribution runs through direct developer-to-buyer digital channels that disintermediate traditional brokerage networks in penthouse segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's luxury residential market offers margin-expansion pathways through smart-home subscription layering and Dhofar corridor first-mover positioning. Permit streamlining by the Ministry of Housing and Urban Planning reduces time-to-revenue for developers with pre-qualified template libraries.
For Market Incumbents: Anchor waterfront pricing power through controlled-berth scarcity in Al Mouj and Saraya Bandar Jissah corridors. Deepen backward integration into marine construction expertise to offset labor skill concentration inflation in Salalah and Sohar. Defend against direct-to-buyer digital channel fragmentation by capturing platform-mediated transaction relationships with Saudi and UAE ultra-high-net-worth buyers. For New Entrants and Emerging Players: Enter via Dhofar Governorate's climate-resilient villa white space, where tourism-linked residential inventory trails visitor growth. Target Salalah's retiree segment with Mediterranean-architecture positioning and lower operational cost structures. Pursue Oman Tourism Development Authority hospitality-residential hybrid classifications to access co-investment structures unavailable in saturated Muscat corridors. For Investors and Strategic Acquirers: Asymmetric upside sits with hospitality-residential hybrid developers possessing Tourism Development Authority certification pipelines and Dhofar land positions. Long-term viability hinges on residency-by-investment framework evolution repositioning Oman against competing Gulf jurisdictions. Monitor Central Bank of Oman macro-prudential rule relaxation as inflection indicator for leveraged buyer pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home Platform Integration | Enables recurring subscription revenue beyond unit sales in Muscat corridors. |
| Dhofar Geographic Expansion | Captures undersupplied tourism-linked inventory in Salalah's monsoon-season zones. |
| Marina Infrastructure Partnership | Secures controlled-berth access scarcity driving pricing power in waterfront segments. |
| Residency-Linked Sales Channel | Aligns with evolving long-term visa frameworks for legacy wealth preservation buyers. |
| Pre-Approved Template Certification | Compresses Ministry of Housing and Urban Planning permit timelines for faster revenue recognition. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with development executives at integrated master-planners, marina infrastructure engineers, hospitality-residential hybrid operators, and Central Bank of Oman regulatory policy specialists with secondary validation. Secondary sources encompassed Ministry of Housing and Urban Planning permit disclosure databases, Oman Tourism Development Authority investment program filings, Central Bank of Oman macro-prudential circulars, and customs records for imported finish materials. Bottom-up project pipeline enumeration and top-down governorate-level demand modeling provided triangulation checks.
Segment-weighting approaches distributed value and volume across property type, price tier, architectural style, and end-user dimensions throughout the forecast period. CAGRs derived from regression analysis against macro drivers including GCC capital flow patterns, residency framework evolution, and coastal zoning overlay expansion. Industry-specific forecast inputs incorporated berth-access scarcity indices and smart-home penetration curves by buyer wealth threshold.
Inputs from Ministry of Housing and Urban Planning permit databases and Oman Tourism Development Authority investment disclosures were available through the study window; gaps in private transaction price transparency introduce uncertainty bands around ultra-high-net-worth segment sizing. Forecasts reflect documented assumptions regarding regulatory velocity and capital flow stability. A model refresh is warranted upon material change in Central Bank of Oman loan-to-value thresholds or freehold zone designation expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market