
 Japan Luxury Residential Real Estate Market | 2026-2036
Japan Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Luxury Residential Real Estate Market Foresight
Brokerage-to-developer direct channels is rewriting how premium inventory reaches buyers in Japan's luxury residential sector. Mori Building Co., Ltd. controls a vertically integrated pipeline from land acquisition to finished units in Tokyo's Toranomon district. Mitsui Fudosan Co., Ltd. leverages its mixed-use development expertise to anchor residential towers within larger urban regeneration zones. Sumitomo Realty & Development Co., Ltd. competes through sustained investment in seismic resilience technologies that differentiate its condominium offerings.
Japan luxury residential real estate comprises high-value dwellings typically exceeding 100 million yen, featuring reinforced concrete or steel-frame construction with advanced seismic damping systems, designed for ownership by affluent domestic and international purchasers seeking capital preservation and lifestyle amenities. Condominiums dominate transaction volume in central Tokyo where floor-area ratios and height restrictions constrain supply, while detached houses command the highest per-square-meter pricing in exclusive hillside neighborhoods of Kobe and Karuizawa. Smart homes and eco-friendly homes represent the fastest-expanding trend categories as METI efficiency mandates and buyer preference for operational cost reduction reshape specification requirements across new developments.
METI enforces building energy efficiency standards that compel luxury developers to integrate solar PV, high-performance insulation, and smart grid connectivity into new construction, while the Ministry of Land, Infrastructure, Transport and Tourism administers the Housing Performance Indication System that grades structural safety and energy metrics visible to purchasers. Local governments in Tokyo and Osaka impose additional landscape and shadowing ordinances that directly constrain design freedom and add compliance layers to central-city projects. Stakeholders must monitor whether METI tightens ZEB-ready timelines and how prefectural governments calibrate relaxation of floor-area ratio incentives against infrastructure capacity limits.
Market Dynamics
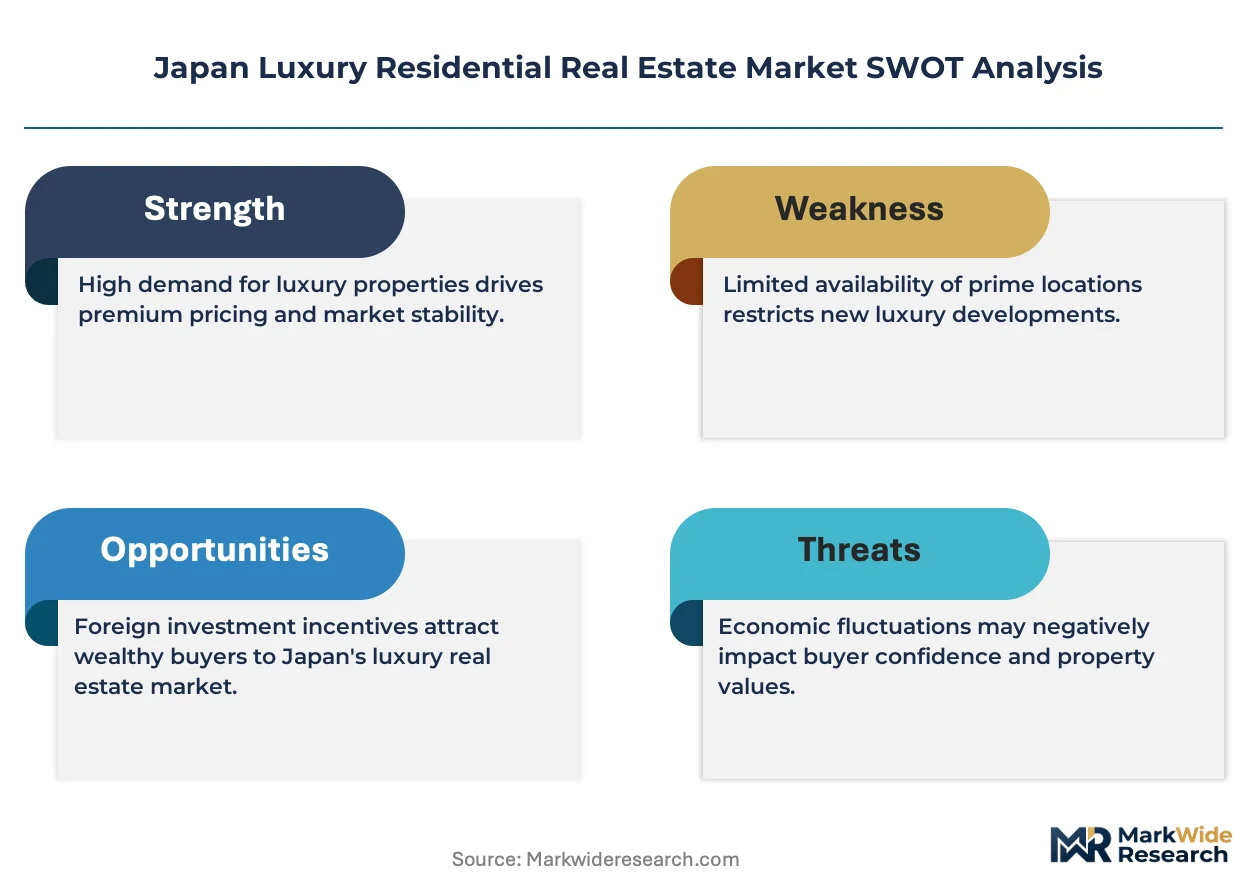
Land scarcity in Tokyo's central five wards is compressing development timelines and intensifying competition for buildable parcels, while METI's ZEB-ready building standards are forcing design-phase integration of energy systems that previously qualified as optional upgrades.
Growth Catalysts
- Ultra-high-net-worth inflows from Singapore and Hong Kong:Cross-border capital seeking yen-denominated safe-haven assets is concentrating transaction activity in Minato and Shibuya wards.
- METI efficiency mandates:Regulatory pressure for net-zero-ready construction is accelerating specification upgrades that command premium pricing in new condominium releases.
- Seismic resilience differentiation:Advanced damping technologies and base-isolation systems are becoming baseline expectations among domestic affluent buyers.
Market Restraints
- Floor-area ratio constraints:Tokyo's strict FAR regulations cap developable density and extend project approval timelines.
- Construction labor scarcity:Specialized trades for high-rise reinforced concrete work face demographic shrinkage that inflates input costs.
- Shadowing ordinances:Local landscape regulations in central wards restrict building envelopes and reduce salable square footage.
Strategic Opportunities
- Karuizawa and Niseko secondary markets:Underpenetrated resort residential segments offer detached house development with lower land competition.
- Smart grid convergence:Integration of home energy management with building-wide systems creates service revenue streams beyond unit sales.
- Brokerage-to-developer direct channels:Bypassing traditional listing platforms reduces commission leakage and accelerates inventory velocity.
Industry Challenges
- Seismic engineering talent pipeline:Shortage of structural designers fluent in performance-based design methods extends pre-construction phases.
- Housing Performance Indication System compliance:Extended certification timelines for structural safety and energy grades delay marketing launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Luxury Residential Real Estate Market |
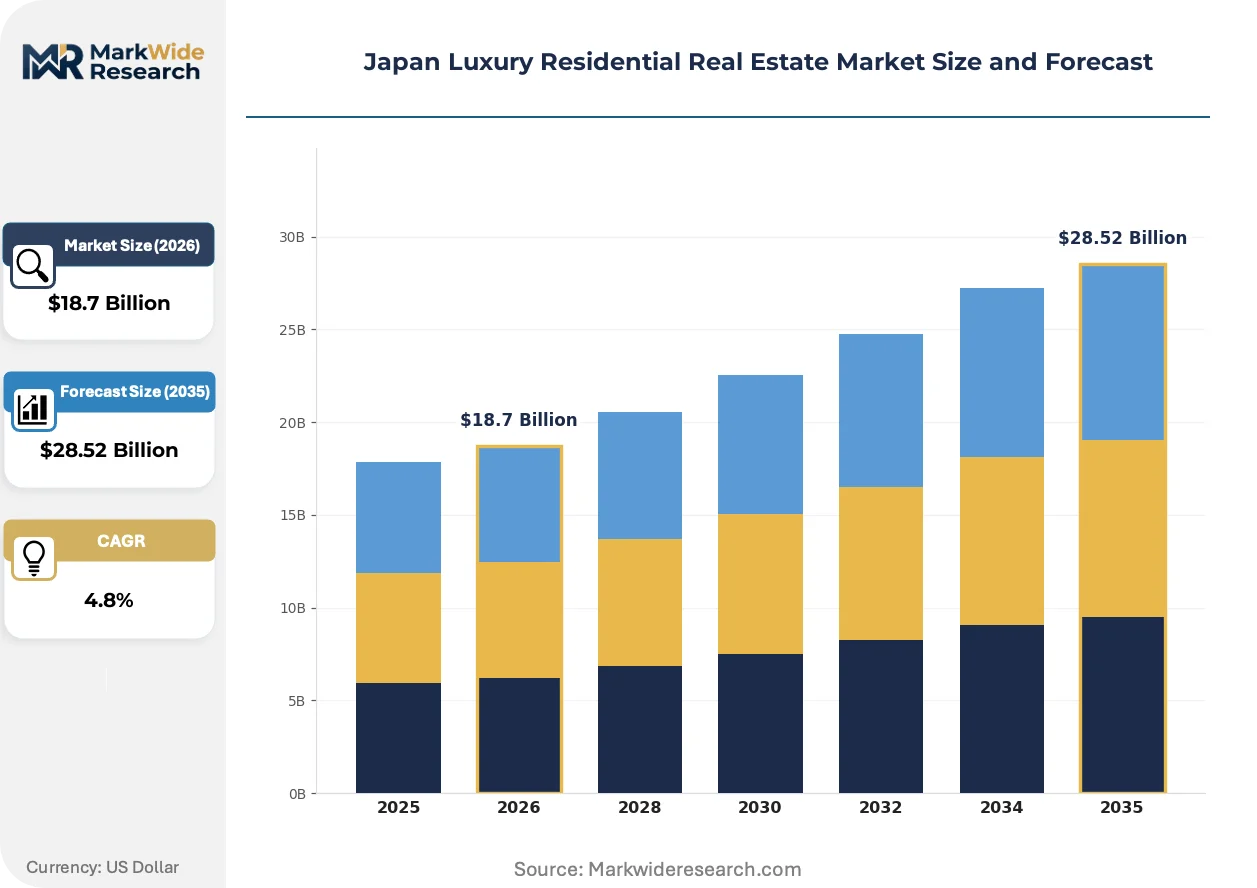
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condominiums, Detached Houses, Townhouses, Villas Buyer Type: Domestic Buyers, International Investors, Luxury Developers, High Net-Worth Individuals Financing Method: Cash Purchases, Mortgage Loans, Investment Funds, Joint Ventures Market Trends: Eco-Friendly Homes, Smart Homes, High-End Renovations, Open Concept Designs |
| Companies Covered | Mori Trust Co., Ltd., Mori Building Co., Ltd., Mitsubishi Estate Co., Ltd., Daiwa House Group, Nomura Real Estate, Mitsui Fudosan Co., Ltd., Tokyu Land Corporation, Tokyo Tatemono, Sumitomo Realty & Development Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Luxury Residential Real Estate Market Shifts & Advancements
Specification requirements across Japan's luxury residential pipeline are pivoting from amenity-driven differentiation toward embedded energy performance and operational cost transparency as primary value signals.
Smart home automation systems are migrating from standalone device ecosystems to integrated building management platforms that coordinate HVAC, lighting, and energy storage. Ultra-affluent buyers in Toranomon and Roppongi developments now expect centralized control interfaces as standard. This technology migration is compressing margins for developers who treat automation as an upgrade tier rather than baseline infrastructure.
METI's ZEB-ready building standards are mandating solar PV, high-performance insulation, and grid-responsive equipment in new construction above specified thresholds. Developers must now engage energy consultants during schematic design rather than value-engineering efficiency features later. Central Tokyo projects face the steepest compliance curves given limited roof area for photovoltaic arrays.
Cross-border buyer behavior is shifting from speculative acquisition toward extended-stay residence planning, with Singaporean and Hong Kong purchasers prioritizing units that qualify for Japan's investor visa pathways. This preference rotation favors larger floor plates with dedicated workspace over compact pied-à-terre formats. The shift is most visible in Azabu and Hiroo submarkets where international school proximity anchors family relocation decisions.
Japan Luxury Residential Real Estate Market Segmentation
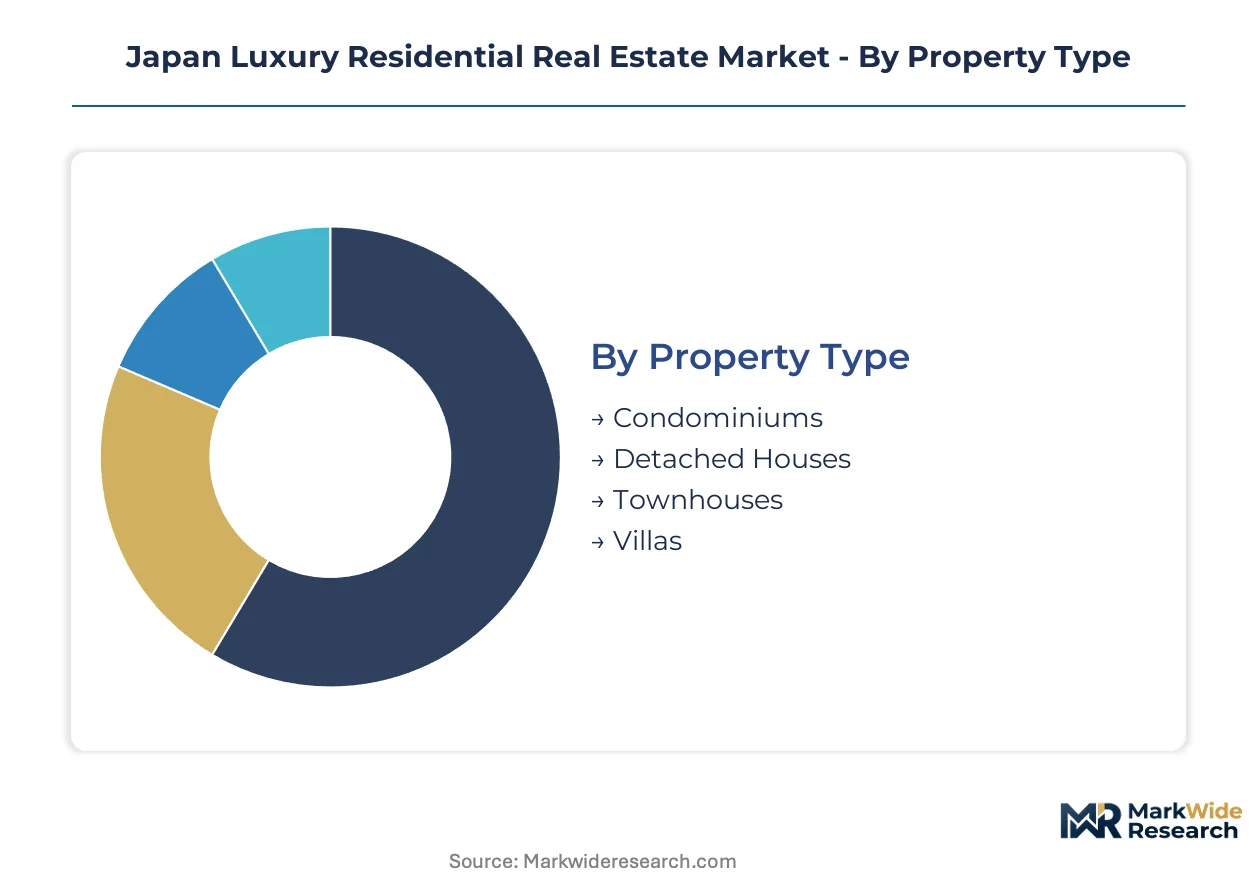
Segmentation in Japan's luxury residential market reveals distinct transaction velocities and buyer motivations across property formats and capital sources. Each dimension carries implications for development timelines, pricing power, and regulatory exposure in Tokyo's constrained central wards.
Property Type:
Condominiums turn inventory fastest in Minato and Shibuya wards, while detached houses in Karuizawa and Kobe hillside districts cycle slowly through bespoke construction timelines.
- Condominiums:Reinforced concrete or steel-frame towers with advanced seismic damping systems dominate transaction volume in central Tokyo. Floor-area ratio constraints and transit proximity in the five central wards sustain premium pricing power for units exceeding 100 million yen.
- Detached Houses:Custom-built residences on freehold land command the highest per-square-meter pricing in exclusive neighborhoods of Kobe and Karuizawa. Extended design and permitting timelines stretch development cycles to 24-36 months versus 18-24 months for comparable condominiums.
- Townhouses:Low-rise attached dwellings in Tokyo's outer wards attract domestic buyers seeking ground-floor access with reduced maintenance burdens.
- Villas:Resort-format properties in Niseko and Okinawa cater to seasonal occupancy patterns with lower liquidity than primary residences.
Condominiums dominate installed base. Detached houses are where expansion concentrates.
Buyer Type:
Domestic purchasers move through due diligence rapidly using established banking relationships, while international investors navigate visa pathways and currency hedging that extend transaction timelines.
- Domestic Buyers:Affluent Japanese households prioritize seismic resilience certifications and proximity to established school districts in Azabu and Hiroo submarkets.
- International Investors:Ultra-high-net-worth individuals from Singapore and Hong Kong concentrate acquisition activity in Minato ward, with investor visa qualification now driving preference toward larger floor plates with dedicated workspace.
- Luxury Developers:Vertically integrated operators like Mori Building and Mitsui Fudosan deploy capital through direct brokerage channels that bypass traditional listing platforms.
- High Net-Worth Individuals:Family office capital targets trophy assets with generational wealth preservation characteristics, accepting extended hold periods for hillside properties in Kobe.
Domestic buyers anchor transaction velocity. International investors are expanding most quickly as yen depreciation accelerates cross-border capital deployment.
Financing Method:
Cash transactions close within 30-45 days, while mortgage-dependent purchases face extended appraisal and documentation phases that stretch timelines to 90-120 days.
- Cash Purchases:Unleveraged acquisitions by international buyers and domestic family offices eliminate financing contingencies and accelerate closing timelines.
- Mortgage Loans:Domestic banks apply conservative loan-to-value ratios against luxury collateral, with METI's financial stability mandates shaping underwriting standards.
- Investment Funds:Institutional capital pools target portfolio-scale exposure across multiple Tokyo wards, accepting illiquidity premiums for concentrated positions.
- Joint Ventures:Developer-landowner structures in land-scarce central wards distribute entitlement risk across multiple capital partners.
Cash purchases dominate transaction speed. Investment funds are where capital formation is concentrating.
Market Trends:
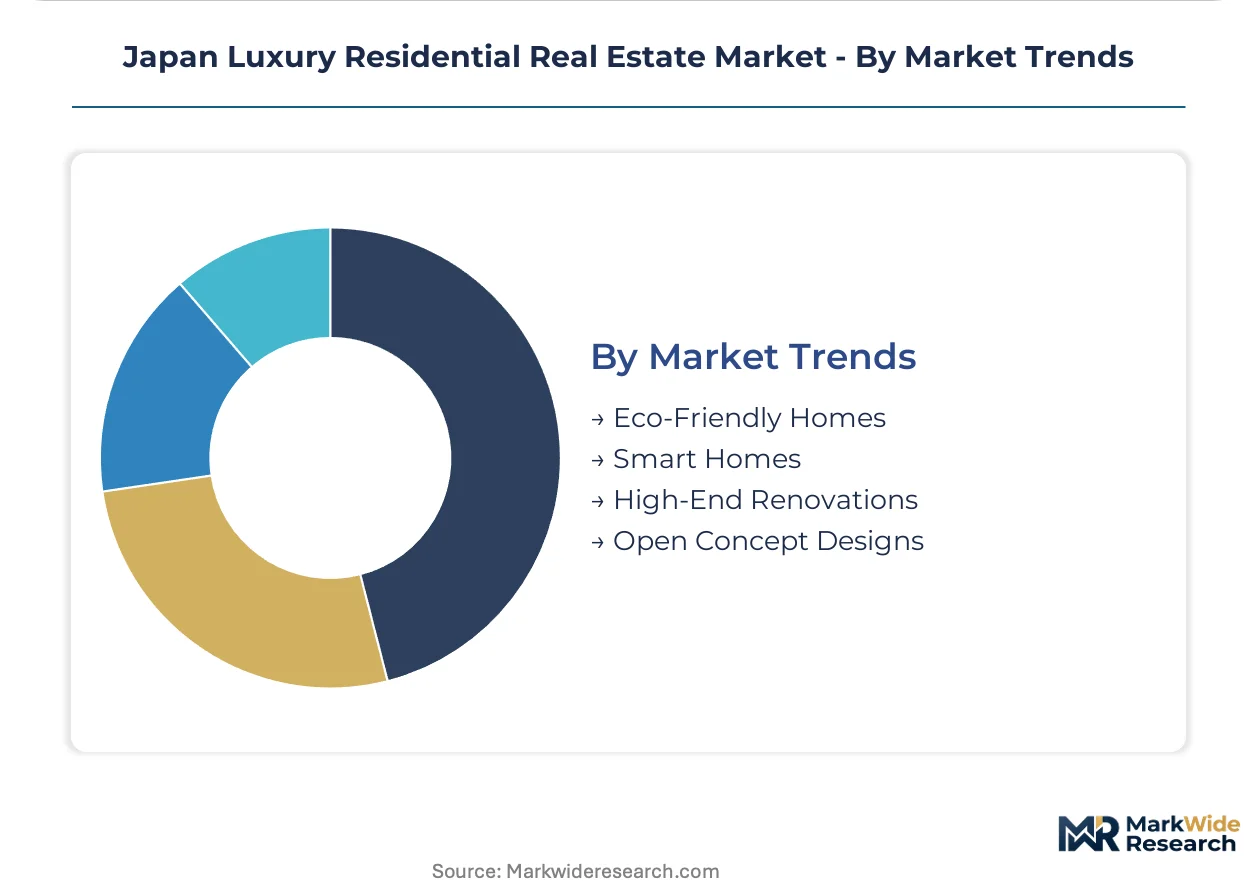
Eco-friendly specifications are becoming baseline requirements rather than upgrade tiers, compressing margins for developers who delay energy consultant engagement until schematic design phases.
- Eco-Friendly Homes:METI's ZEB-ready building standards mandate solar PV, high-performance insulation, and grid-responsive equipment in new construction above specified thresholds.
- Smart Homes:Integrated building management platforms coordinating HVAC, lighting, and energy storage have migrated from upgrade tiers to baseline expectations in Toranomon and Roppongi developments.
- High-End Renovations:Existing stock retrofitting in central Tokyo addresses seismic resilience gaps and energy efficiency shortfalls in pre-2010 construction.
- Open Concept Designs:Flexible floor plates accommodating remote work requirements attract extended-stay international buyers prioritizing visa pathway qualification.
Smart homes dominate new development specifications. Eco-friendly homes are where regulatory pressure is driving steepest specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shinkansen high-speed rail network underwrites Tokyo's gravitational pull on luxury residential capital, compressing travel times to secondary markets and reinforcing Kanto's dominance in premium stock transactions.
Kanto/Tokyo
Ultra-high-net-worth individuals from Singapore and Hong Kong concentrate acquisition activity in Minato and Shibuya wards, drawn by yen depreciation and transit proximity. METI enforces ZEB-ready building standards that mandate solar PV integration and high-performance insulation in new developments above specified thresholds. The Toranomon and Roppongi submarkets anchor vertical integration strategies, with developers controlling pipelines from land acquisition to finished units.
Kansai/Osaka
Domestic affluent households prioritize seismic resilience certifications and established school district proximity in Osaka's northern wards. The Ministry of Land, Infrastructure, Transport and Tourism administers the Housing Performance Indication System that grades structural safety metrics visible to purchasers. Umeda and Nakanoshima districts concentrate mixed-use regeneration projects where residential towers anchor larger urban renewal zones.
Chubu/Nagoya
Manufacturing-derived wealth sustains demand for detached houses in hillside districts with extended hold periods for generational wealth preservation. Local governments impose landscape and shadowing ordinances that constrain building envelopes and reduce salable square footage. The Sakae and Marunouchi submarkets attract family office capital targeting trophy assets with lower liquidity than Tokyo equivalents.
Hokkaido
Seasonal occupancy patterns dominate Niseko's resort-format villa market, with international buyers accepting extended hold periods for recreational use. Prefectural governments calibrate relaxation of floor-area ratio incentives against infrastructure capacity limits in ski-accessible zones. Hirafu and Hanazono clusters concentrate development activity where land competition remains below central ward levels.
Nagano/Karuizawa
Extended-stay residence planning from cross-border buyers prioritizes units with dedicated workspace and international school proximity. Construction labor scarcity for specialized high-rise reinforced concrete trades inflates input costs in remote locations. The Kyu-Karuizawa and Naka-Karuizawa districts command the highest per-square-meter pricing for custom-built residences on freehold land.
Japan Luxury Residential Real Estate Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated developers with captive land pipelines and direct brokerage channels that bypass traditional listing platforms. Three strategic archetypes dominate: tower specialists controlling urban regeneration zones, seismic technology differentiators, and resort-format developers in secondary markets. Competitive moves concentrate on backward integration into land banking and portfolio diversification across property formats.
Among Tokyo-based integrated developers, Mori Building Co., Ltd., Mitsui Fudosan Co., Ltd., and Sumitomo Realty & Development Co., Ltd. occupy positions that exemplify distinct competitive vectors. Mori Building represents the tower-specialist archetype with concentrated exposure to Toranomon district pipelines. Mitsui Fudosan sits within the mixed-use regeneration tier, anchoring residential components within larger urban zones. Sumitomo Realty exemplifies the technology-differentiation path, with positioning derived from sustained investment in seismic resilience systems.
| Leading Market Players |
|---|
| Mori Trust Co., Ltd. |
| Mori Building Co., Ltd. |
| Mitsubishi Estate Co., Ltd. |
| Daiwa House Group |
| Nomura Real Estate |
| Mitsui Fudosan Co., Ltd. |
| Tokyu Land Corporation |
| Tokyo Tatemono |
| Sumitomo Realty & Development Co., Ltd. |
| Others |
Supply & Pricing Matrix
Undercapacity in specialized seismic engineering talent across Tokyo's central five wards is compressing pre-construction timelines and elevating input costs for reinforced concrete high-rise work, forcing developers to front-load consultant engagement and pass through premiums to buyers in Minato and Shibuya condominium releases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates trophy assets in Toranomon from mid-tier Shibuya stock and outer-ward townhouses. Price differentiation rests on seismic certification grade under the Housing Performance Indication System and proximity to Ginza subway connectivity. Cost compression in mid-tier condominiums is intensifying because METI's ZEB-ready mandates accelerate energy consultant spend without corresponding buyer willingness-to-pay expansion. Domestic family offices demonstrate lowest price sensitivity for hillside Karuizawa detached houses, while international investors negotiating visa-pathway units in Azabu exhibit moderate elasticity on floor-plate premiums.
Supply Chain Analysis
Export-control regimes on advanced damping technologies from Germany and Switzerland limit domestic access to performance-based seismic systems, forcing Japanese developers toward licensed production partnerships with European specialists. Geographic supply concentration centers on domestic steel-frame fabrication, Chinese solar PV module assembly, and South Korean smart-grid component manufacturing. Raw material dependencies include high-strength concrete admixtures, base-isolation rubber bearings, and lithium-ion storage cells. Single-source vulnerability runs through German damping technology licensors. Distribution runs through vertically integrated developer channels that bypass traditional brokerage platforms and accelerate inventory velocity in Toranomon district releases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: METI's ZEB-ready mandates and the Housing Performance Indication System create certification barriers that entrench incumbent developers with established compliance infrastructure.
For Market Incumbents: Insulate core Minato and Shibuya positions through backward integration into captive land banking and direct brokerage channel control that eliminates commission leakage. Seismic engineering talent scarcity threatens project timelines; secure exclusive consulting relationships with performance-based design specialists. Prioritize certification investment in net-zero-ready building standards ahead of METI timeline tightening.
For New Entrants and Emerging Players: Pursue white-space development in Niseko and Karuizawa resort residential segments where land competition remains below central ward intensity and international buyer inflows are accelerating. Target detached house formats in hillside districts with bespoke construction timelines that incumbent tower specialists disfavor. Deploy family-office relationship networks as the primary go-to-market angle for trophy asset placement.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mixed-use regeneration projects as METI mandates and shadowing ordinances compound compliance spend. Long-term viability over a multi-year horizon favors vertically integrated developers with Toranomon or Roppongi pipeline depth and established METI pre-approval relationships. Monitor METI ZEB-ready timeline acceleration as the primary inflection signal for margin compression across non-compliant stock.
| Strategic Initiative | Industry Significance |
|---|---|
| Land Banking Expansion | Captive parcel control in Minato ward secures pipeline visibility against FAR-constrained competition. |
| Direct Brokerage Channel Development | Bypassing traditional listing platforms reduces commission leakage and accelerates inventory velocity. |
| Seismic Technology Licensing | Partnerships with German damping specialists differentiate condominium offerings in Roppongi submarket. |
| ZEB-Ready Certification Pre-Investment | Early compliance with METI energy mandates commands premium pricing in new Toranomon releases. |
| Resort Market Diversification | Niseko and Karuizawa detached house development reduces concentration risk in central Tokyo towers. |
Research Methodology
Initial hypotheses were tested against primary input from luxury development executives, seismic engineering consultants, international buyer agents, and METI policy officers and refined through secondary validation. Primary stakeholder engagement combined structured interviews with project directors at integrated developers and acquisition specialists at Singapore and Hong Kong family offices. Secondary sources encompassed METI building energy efficiency filings, Ministry of Land, Infrastructure, Transport and Tourism Housing Performance Indication System certifications, and Tokyo metropolitan land transaction registries. Bottom-up unit inventory counts were triangulated against top-down ward-level absorption estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass property format, buyer capital source, financing method, and specification tier. CAGRs were derived through cohort-based trajectory analysis incorporating land scarcity intensity, cross-border capital flow velocity, and regulatory compliance cost escalation. Industry-specific forecast inputs included Shinkansen accessibility indices and international school proximity premiums.
Sensitivities concentrate around yen depreciation velocity, METI ZEB-ready timeline acceleration, and construction labor demographic shrinkage. Forecasts reflect assumptions regarding sustained ultra-high-net-worth inflows from Singapore and Hong Kong and stable Floor-Area Ratio enforcement in Tokyo's central five wards. Material shifts in cross-border capital controls or METI mandate tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market