
 Luxury-Minded Retirement Residences Market | 2026-2036
Luxury-Minded Retirement Residences Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury-Minded Retirement Residences Market Analysis
Aftermarket wellness programming revenue is reshaping competitive economics in luxury senior housing, shifting margin pools from upfront real estate sales toward recurring lifestyle subscriptions. Atria Senior Living leverages its national footprint to standardize concierge service tiers across dozens of markets. Brookdale Senior Living anchors its repositioning strategy around premium memory care wings with specialized staffing ratios. Sunrise Senior Living differentiates through chef-driven dining programs that command entrance fee premiums.
Luxury-minded retirement residences are age-qualified residential communities offering hospitality-grade amenities integrated with graduated care services, typically featuring square footage exceeding 1,000 square feet per unit, spa facilities, and on-site medical clinics. Their primary commercial purpose is to capture lifetime value from wealthy seniors through entrance fees and monthly service charges while delaying nursing home transitions. Independent living commands the largest share of new construction starts, while memory care segments generate the highest per-unit margins due to specialized staffing requirements. Concierge services represent the fastest-growing revenue line as operators bundle transportation, personal shopping, and travel coordination into tiered packages.
Federal oversight through the Department of Housing and Urban Development shapes fair housing accessibility standards, while state health departments regulate assisted living licensure and staffing mandates that directly affect operating costs. The U.S. Securities and Exchange Commission monitors entrance fee structures when operators market continuing care contracts as investment-like products. Stakeholders must track how pending state Medicaid expansion decisions could bifurcate the market between purely private-pay luxury operators and hybrid models accepting limited subsidized residents.
Market Dynamics
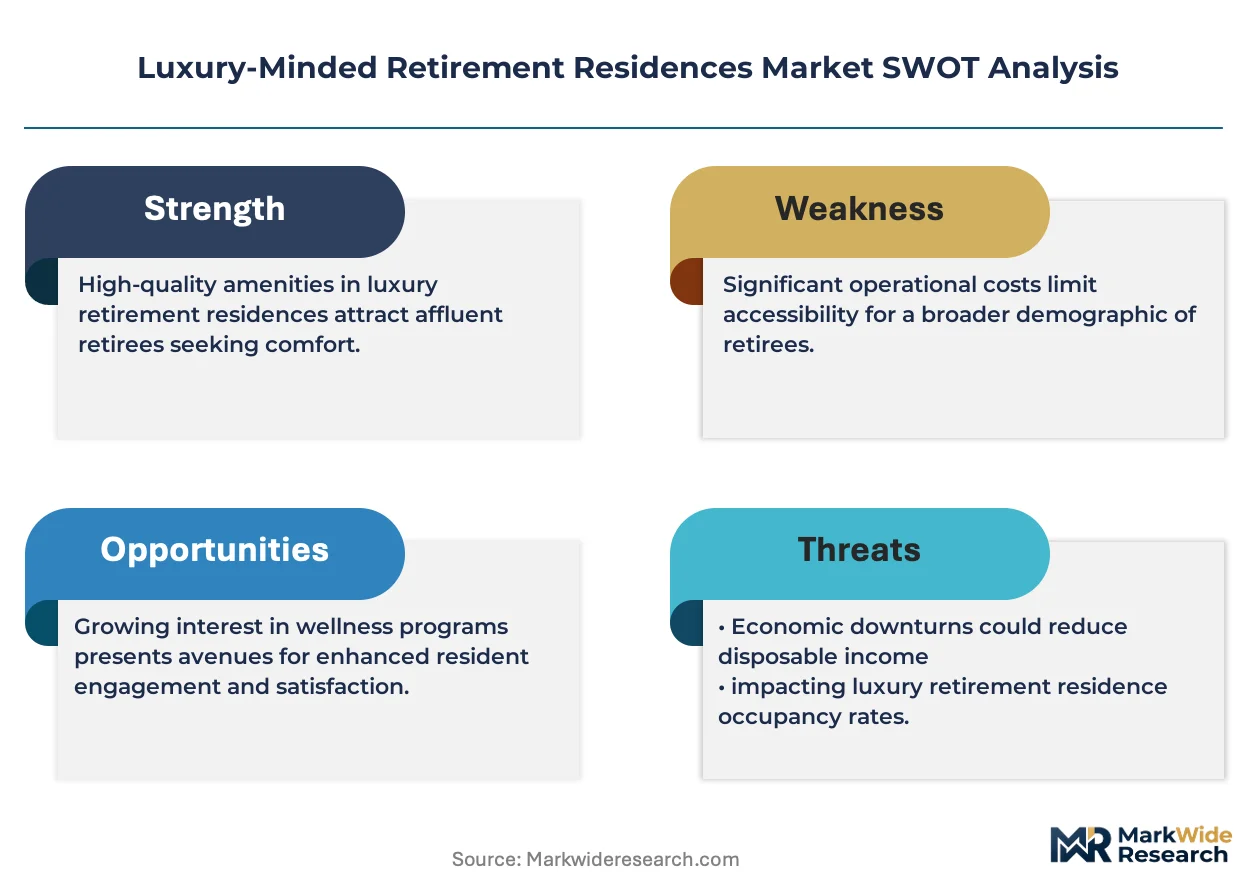
Affluent baby boomers are compressing traditional retirement housing timelines, demanding integrated wellness infrastructure before acute care needs emerge. This demographic pull is restructuring operator capital allocation toward preventive amenities rather than reactive medical facilities.
Growth Catalysts
- Sun Belt Migration Clusters:Naples, Scottsdale, and Austin are concentrating wealthy retiree inflows, accelerating land acquisition for continuing care communities ahead of demand curves.
- HUD Fair Housing Accessibility Mandates:Federal enforcement of universal design standards is legitimizing premium pricing for compliant units that exceed baseline requirements.
- Concierge Service Tiering:Bundled transportation, travel coordination, and personal shopping packages are expanding addressable spend per resident beyond core housing fees.
Market Restraints
- Construction Input Volatility:Specialized medical-grade finishes and smart building systems face price instability from concentrated semiconductor and sensor suppliers.
- State Staffing Ratio Mandates:Memory care licensure requirements in jurisdictions like California and New York directly inflate per-unit labor costs.
- Entrance Fee Regulatory Scrutiny:SEC oversight of continuing care contracts as investment-like products constrains marketing language and sales velocity.
Strategic Opportunities
- Hybrid Medicaid-Private Models:Pending state expansion decisions create white space for operators to segment campuses between purely private-pay towers and limited subsidized wings.
- Chef-Driven Dining Differentiation:Culinary program premiums represent underexploited pricing power as residents prioritize restaurant-quality experiences over institutional food service.
- Aftermarket Wellness Subscriptions:Recurring lifestyle revenue streams are displacing one-time real estate margin dependence across independent living segments.
Industry Challenges
- Specialized Care Talent Scarcity:Memory care staffing ratios require certified geriatric nursing specialists that command wage premiums and experience high turnover.
- Legacy System Integration Friction:Smart building infrastructure deployment conflicts with existing property management platforms and resident technology comfort thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury-Minded Retirement Residences Market |
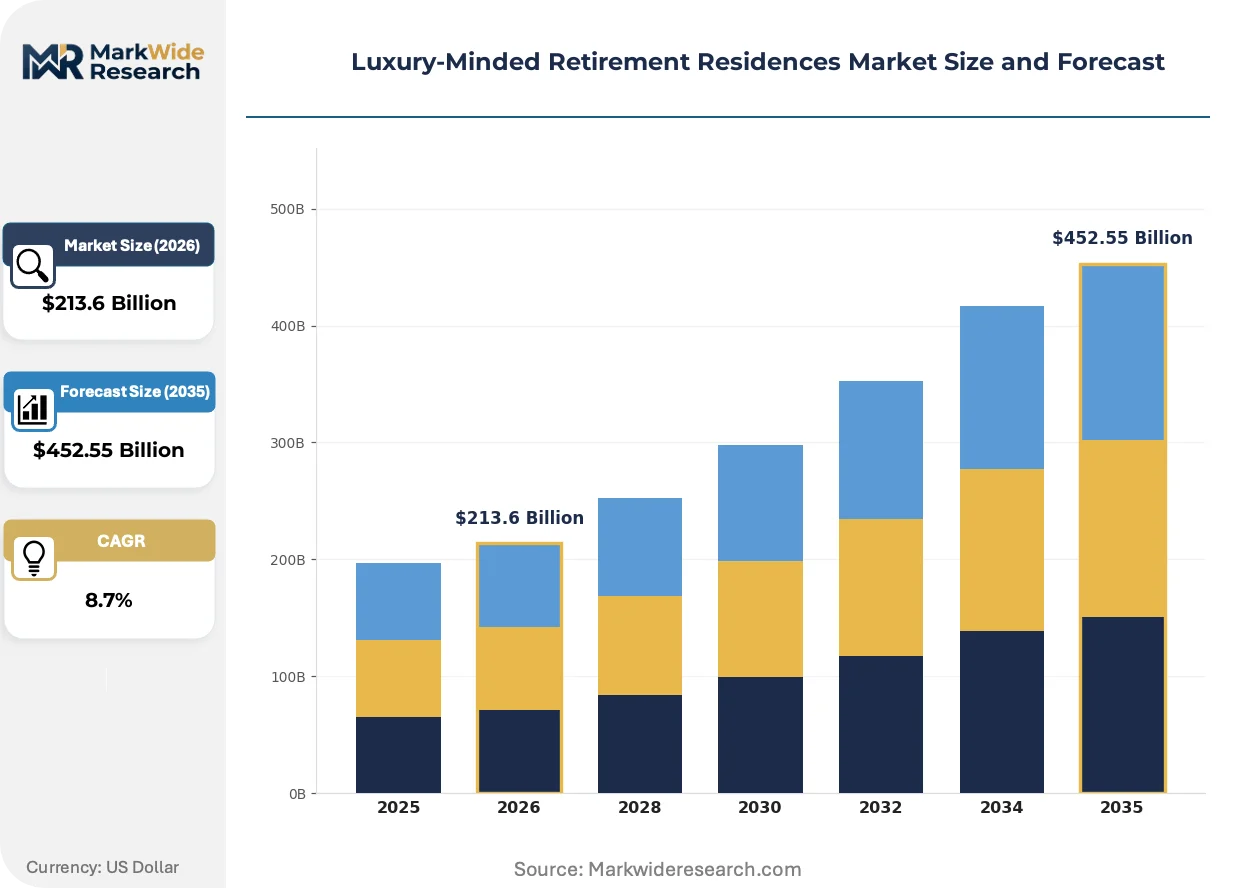
| Market Size in 2026 | $213.6 Billion |
| Market Size in 2035 | $452.55 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Independent Living, Assisted Living, Memory Care, Continuing Care Service Type: Health Services, Concierge Services, Recreational Activities, Transportation Facility Size: Small Scale, Medium Scale, Large Scale, Comprehensive Pricing Model: Monthly Fee, Entrance Fee, Rent-For-Life, Service Package |
| Companies Covered | Atria Senior Living, HumanGood, Sunrise Senior Living, Leisure Care, MorningStar Senior Living, Brookdale Senior Living, Emeritus Corporation, The Palace at Coral Gables, Five Star Senior Living, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury-Minded Retirement Residences Market Emerging Trajectories
Technology-enabled wellness monitoring and predictive care coordination are restructuring how operators capture lifetime resident value. These shifts compress traditional care transitions while expanding service addressability.
Passive sensor arrays and AI-driven fall detection systems are rendering obsolete scheduled wellness checks and reactive emergency response protocols. Independent living operators in Florida and Arizona are deploying these systems at scale, reducing nursing staff touchpoints while maintaining liability coverage. The structural consequence is margin expansion through labor substitution without service degradation.
State-level assisted living licensure tightening, particularly in California and New York, is mandating specialized dementia care training hours and staffing floors. This regulatory compression is forcing smaller operators to exit or sell to scaled platforms that can absorb compliance overhead. Memory care wings in these jurisdictions now require dedicated clinical directors, reshaping development pro formas.
Wealthy seniors are unbundling traditional entrance fee structures, negotiating à la carte amenity packages rather than accepting standardized tier offerings. This procurement fragmentation pressures operators to modularize service catalogs and expose line-item pricing. The pattern is most pronounced in Texas and Arizona markets where competitive supply density empowers buyer negotiation leverage.
Luxury-Minded Retirement Residences Market Segmentation
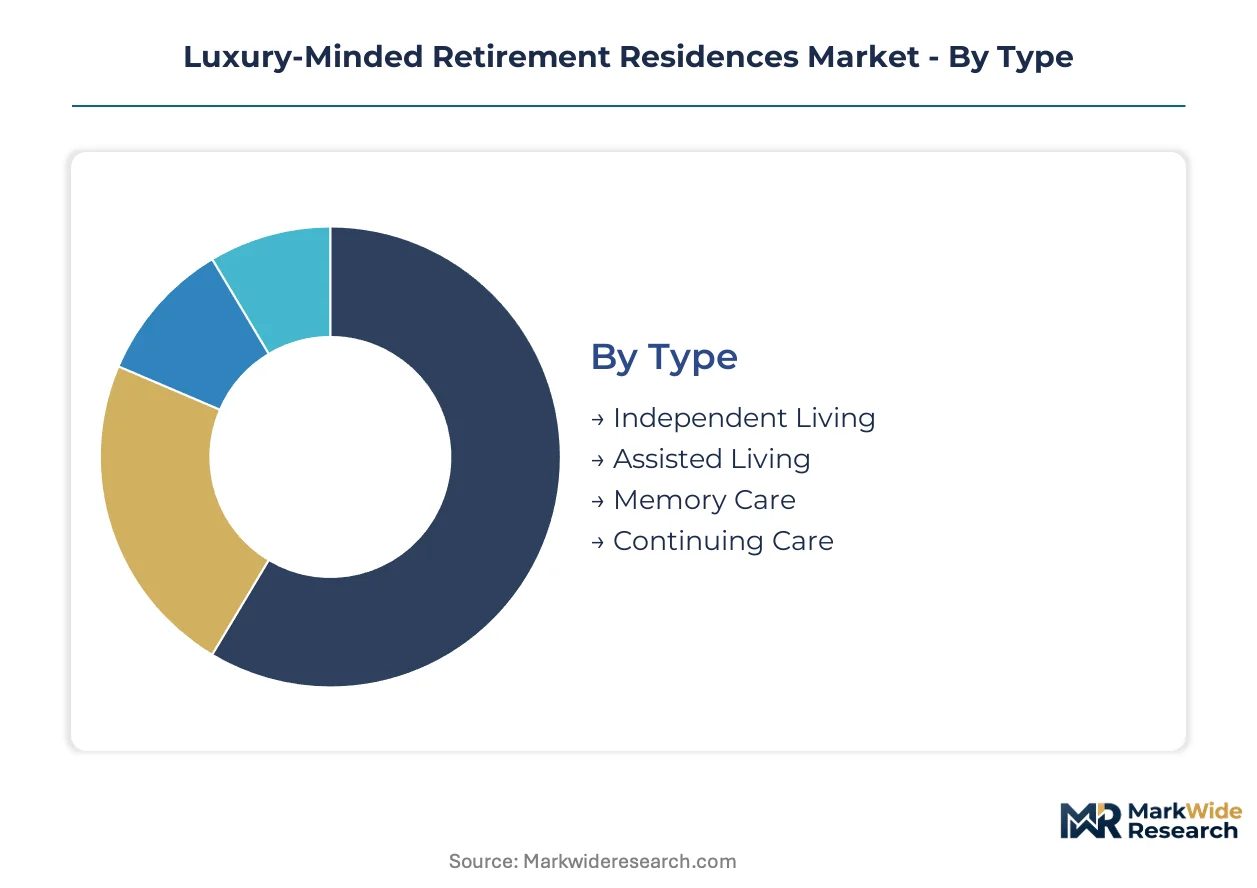
Segmentation in luxury retirement housing reveals how operators align physical infrastructure, service depth, and financial structures to capture lifetime value from affluent seniors. Each dimension exposes distinct margin pools and capital intensity requirements that shape competitive positioning across Sun Belt metropolitan clusters.
Type:
Mature segments dominate current construction pipelines while emerging care tiers reshape development economics.
- Independent Living:Age-qualified residential units exceeding 1,000 square feet with hospitality-grade amenities but no licensed medical care. Demand concentrates in Naples, Florida and Scottsdale, Arizona where wealthy retirees prioritize lifestyle flexibility over preemptive care infrastructure.
- Memory Care:Secured environments with specialized staffing ratios and dementia-specific programming. California and New York state licensure mandates drive per-unit labor costs highest in this segment, creating margin pressure that only scaled operators can absorb.
- Assisted Living:Licensed personal care support with medication management and activities of daily living assistance.
- Continuing Care:Campus-based tiered contracts guaranteeing access to elevated care levels without relocation.
Independent Living handles the majority of throughput; Memory Care is the fastest mover on share.
Service Type:
Cost tier stratification separates essential clinical offerings from discretionary lifestyle subscriptions that expand addressable spend per resident.
- Concierge Services:Bundled transportation, travel coordination, personal shopping, and appointment management delivered through tiered subscription packages. Austin, Texas operators report the highest attach rates for premium concierge tiers among tech-industry retirees.
- Health Services:On-site medical clinics, wellness programming, and preventive care coordination integrated with graduated care transitions. HUD fair housing accessibility mandates legitimize premium pricing for compliant clinical infrastructure.
- Recreational Activities:Chef-driven dining, spa facilities, fitness programming, and cultural excursions.
- Transportation:Scheduled and on-demand mobility services including medical appointments and retail access.
Health Services anchors base contract pricing; Concierge Services delivers the steepest expansion trajectory as operators unbundle amenity catalogs.
Facility Size:
Volume concentration favors scaled developments that amortize fixed compliance costs across larger resident bases.
- Large Scale:Communities exceeding 200 units with dedicated clinical directors, multiple dining venues, and comprehensive amenity programming. State staffing ratio mandates in California and New York force minimum scale thresholds for economic viability.
- Comprehensive:Campus-style developments integrating independent living, assisted living, and skilled nursing with centralized infrastructure.
- Medium Scale:75-200 unit developments balancing amenity breadth with operational agility.
- Small Scale:Under 75 units with limited service scope and higher per-resident overhead burden.
Large Scale handles the majority of throughput; Comprehensive developments are gaining share fastest through entrance fee monetization.
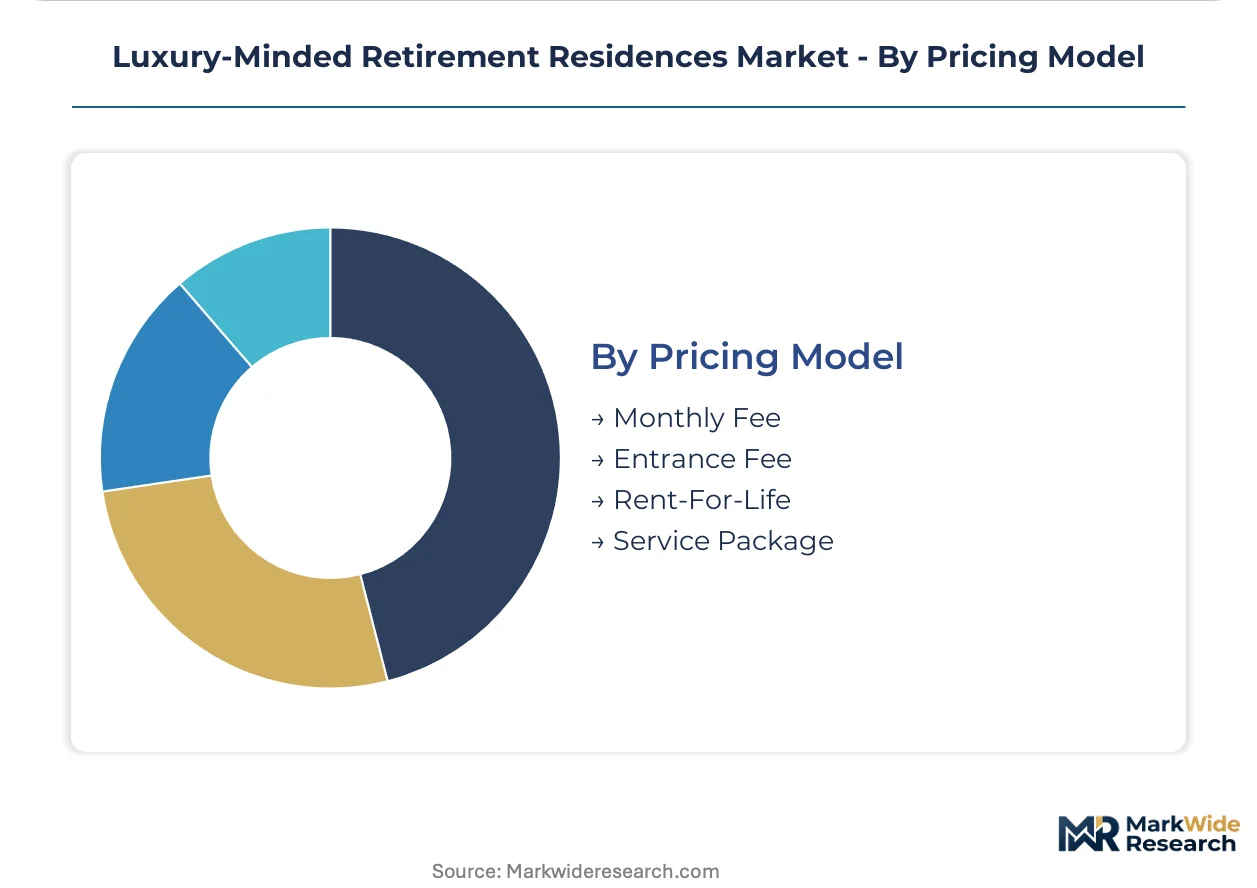
Pricing Model:
Customer type differentiation separates asset-light renters from capital-committed entrance fee purchasers with divergent lifetime value profiles.
- Entrance Fee:Upfront capital contributions typically ranging from substantial six-figure commitments, with partial refundability provisions and priority access to care transitions. SEC oversight of continuing care contract marketing constrains sales velocity in Texas and Arizona markets.
- Monthly Fee:All-inclusive service charges without upfront capital commitment, attracting liquidity-conscious retirees.
- Rent-For-Life:Guaranteed occupancy contracts with inflation-adjusted monthly obligations and no refundability.
- Service Package:Modular à la carte pricing exposing line-item amenity costs to resident negotiation.
Entrance Fee structures dominate asset-heavy development pro formas; Service Package unbundling is expanding most quickly as buyer leverage intensifies in competitive Sun Belt markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer price sensitivity varies sharply across geographies. Sun Belt metropolitan clusters command premium entrance fees with minimal negotiation leverage, while Northeast and Midwest markets face compressed margins from Medicaid-exposed competitors and aging housing stock.
United States
Affluent baby boomers concentrate in Naples, Scottsdale, and Austin, compressing traditional retirement timelines with preventive wellness demands. HUD fair housing accessibility mandates legitimize premium pricing for compliant units exceeding baseline requirements. Florida's Gulf Coast anchors the nation's densest cluster of continuing care community construction starts.
Canada
Wealthy retirees in Vancouver and Toronto drive demand for hotel-style amenities integrated with graduated care services. Provincial health authorities regulate assisted living licensure with staffing floors that inflate per-unit labor costs. British Columbia's Lower Mainland sees accelerated land acquisition for large-scale developments ahead of demographic curves.
United Kingdom
London and Southeast England concentrate demand for concierge-tier services among financial services retirees. Care Quality Commission oversight of dementia care training hours forces minimum scale thresholds for economic viability. The Home Counties corridor attracts entrance fee-funded campus developments targeting lifetime value capture.
Australia
Sydney and Melbourne retirees prioritize chef-driven dining and spa facilities over preemptive medical infrastructure. Aged Care Quality and Safety Commission regulations mandate specialized staffing ratios for memory care wings. Queensland's Gold Coast emerges as the fastest-growing sub-region for independent living construction starts.
Germany
Bavaria and Baden-Württemberg house wealthy retirees demanding modular service catalogs with exposed line-item pricing. Federal Ministry of Health regulations on assisted living licensure create compliance overhead that favors scaled operators. Munich's metropolitan periphery concentrates premium development activity targeting liquidity-conscious monthly fee structures.
Luxury-Minded Retirement Residences Market Vendor Landscape
Capability concentration sits with specialized memory care operators; scale advantage sits with national footprint platforms that amortize fixed compliance costs. The vendor base organizes into three tiers: scaled multi-state operators with standardized service tiers, regional specialists with localized amenity differentiation, and emerging hybrid models testing Medicaid-private segmentation. Consolidation pressure intensifies as state staffing mandates force smaller operators toward exit or acquisition. Portfolio diversification into aftermarket wellness subscriptions and tiered concierge packages represents the dominant competitive move alongside geographic clustering in Sun Belt migration corridors.
Within the scaled operator tier, Atria Senior Living and Brookdale Senior Living exemplify national footprint strategies that standardize service delivery across dozens of markets. Sunrise Senior Living occupies a position emphasizing culinary program differentiation. These three entities represent the archetype of platform scale absorbing regulatory compliance overhead while capturing lifetime resident value through entrance fee structures and recurring lifestyle subscriptions.
| Leading Market Players |
|---|
| Atria Senior Living |
| HumanGood |
| Sunrise Senior Living |
| Leisure Care |
| MorningStar Senior Living |
| Brookdale Senior Living |
| Emeritus Corporation |
| The Palace at Coral Gables |
| Five Star Senior Living |
| Others |
Supply Flow & Price Mechanics
Semiconductor and sensor supplier concentration determines both entrance fee tier spreads and supply chain configuration for smart building systems in luxury senior housing developments. This single-source dependency in medical-grade finishes and predictive care infrastructure compresses margins at the mid-market tier while amplifying premium pricing power for compliant operators.
Pricing Analysis
Long-term entrance fee contracts dominate asset-heavy development pro formas, with partial refundability provisions and priority care access anchoring lifetime value capture. Three-tier pricing structure across premium, standard, and economy levels separates concierge-inclusive bundles from bare-bones housing fees. Cost compression in mid-tier independent living intensifies because wealthy retirees negotiate à la carte service unbundling in competitive Sun Belt markets. Monthly fee structures attract the most price-sensitive liquidity-conscious buyers, while entrance fee purchasers demonstrate minimal sensitivity to six-figure upfront commitments.
Supply Chain Analysis
Export-control restrictions on advanced sensor arrays and AI-driven fall detection components limit flows from specialized technology suppliers into domestic smart building integrators. Manufacturing concentrates in the United States, Germany, and Japan for medical-grade finishes and predictive care hardware. Component dependencies span semiconductor chips, passive sensor arrays, and specialized dementia-care monitoring equipment. Single-source vulnerability in concentrated semiconductor suppliers creates procurement risk for operators deploying at scale. Distribution runs through national facility management platforms and regional construction contractors serving Sun Belt metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Luxury-minded retirement residences sit in early-cycle expansion as affluent baby boomer migration into Sun Belt clusters accelerates ahead of supply response. Preventive wellness infrastructure adoption compresses traditional care transition timelines and expands service addressability.
For Market Incumbents: Entrench scale advantage by absorbing state staffing ratio mandates through centralized clinical director programs across large-scale campuses. Pursue backward integration into proprietary wellness subscription platforms to displace one-time real estate margin dependence. Consolidate regional specialists facing compliance cost pressure in California and New York jurisdictions. For New Entrants and Emerging Players: Pursue white-space opportunities in hybrid Medicaid-private segmentation as pending state expansion decisions bifurcate addressable demand. Target medium-scale developments in Austin and Nashville where competitive density remains below saturation thresholds. Lead with chef-driven dining program differentiation to command entrance fee premiums in undersupplied culinary-forward segments. For Investors and Strategic Acquirers: SEC oversight of continuing care contract marketing reshapes the acquisition landscape toward operators with compliant sales infrastructure and standardized disclosure protocols. Five-to-ten year viability favors scaled platforms with national footprint amortization of fixed compliance costs. Monitor state Medicaid expansion decisions as the critical signal for portfolio segmentation between purely private-pay and hybrid model exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Concierge Service Tiering | Bundled lifestyle subscriptions expand addressable spend per resident beyond core housing fees in competitive Sun Belt markets. |
| Memory Care Wing Expansion | Specialized staffing ratios command highest per-unit margins and absorb regulatory compliance overhead through scale. |
| Smart Building Integration | AI-driven fall detection systems reduce nursing staff touchpoints while maintaining liability coverage for margin expansion. |
| Chef-Driven Dining Differentiation | Culinary program premiums capture unexploited pricing power as residents prioritize restaurant-quality experiences. |
| Hybrid Medicaid-Private Segmentation | Pending state expansion decisions create white space for operators to segment campuses between private-pay towers and subsidized wings. |
Methodological Framework
Initial hypotheses were tested against primary input from senior housing development executives, state regulatory affairs directors, entrance fee contract specialists, and concierge service operations managers and refined through secondary validation. Bottom-up modeling triangulated against top-down demand sizing combined facility construction permit databases, HUD fair housing enforcement records, state assisted living licensure filings, and SEC continuing care contract disclosure archives.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across care type, service tier, facility scale, and pricing structure dimensions. CAGRs derived from resident demographic flow projections, land acquisition velocity in Sun Belt clusters, and entrance fee monetization rates across independent living and memory care segments. Forecast inputs incorporated state staffing ratio mandate trajectories and smart building technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, construction input costs, or wealthy retiree liquidity preferences would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology deployment scalability. Material shifts in state Medicaid expansion timing or HUD accessibility mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market