
 Bahrain Luxury Residential Real Estate Market | 2026-2036
Bahrain Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Luxury Residential Real Estate Market Outlook
Concierge property management and embedded lifestyle services is pivoting how developers package luxury residences in Bahrain. Diyar Al Muharraq leverages its integrated island infrastructure to anchor premium waterfront villa demand across its master-planned communities. Eagle Hills competes through large-scale mixed-use developments that combine residential units with hospitality and retail components. Seef Properties dominates the capital's core district through controlled commercial-residential zoning that sustains rental yields for investor buyers.
Bahrain luxury residential real estate comprises high-end dwellings typically exceeding 250 square meters with premium finishes, smart home integration, and dedicated amenities designed for affluent owner-occupiers and yield-focused investors. Villa developments command the deepest buyer pools among property types due to scarcity of waterfront land and preference for privacy among Gulf family buyers. Expatriate professionals and foreign investors represent the fastest-growing client segments as Bahrain's visa reforms and absence of property taxes attract regional capital away from Dubai and Riyadh. Pre-construction sales concentrate margin capture for developers while completed inventory trades at liquidity premiums in Manama's secondary market.
Bahrain's Central Bank governs mortgage lending ratios and foreign currency financing rules that directly shape expatriate purchasing power. The Survey and Land Registration Bureau enforces title transparency standards that bolster foreign investor confidence in off-plan acquisitions. The Economic Development Board's residency-by-investment program links property thresholds to visa eligibility, channeling demand toward qualifying price tiers. Stakeholders must monitor how Saudi Vision 2030 diversion of regional capital and potential Central Bank interest rate adjustments reshape cross-border investment flows into Bahrain's luxury stock.
Market Dynamics
Bahrain's Central Bank mortgage regulations and the Economic Development Board's foreign ownership incentives are compressing buyer access windows while redirecting regional capital flows from Dubai and Riyadh into Manama's waterfront developments.
Growth Catalysts
- Residency-by-Investment Thresholds:The Economic Development Board's visa-linked property tiers channel Gulf family capital toward qualifying developments in Diyar Al Muharraq and Seef District.
- Waterfront Land Scarcity:Limited coastal availability in the Northern Governorate concentrates buyer competition for master-planned island communities with private marina access.
- Saudi Capital Diversion:High-net-worth individuals from Riyadh and Dammam are reallocating residential investment portfolios away from UAE oversupply into Bahrain's yield-focused villa stock.
Market Restraints
- Central Bank LTV Caps:Bahrain's Central Bank restricts mortgage lending ratios for non-resident buyers, compressing leverage capacity for expatriate professionals.
- Foreign Currency Financing Rules:The Central Bank's currency hedging requirements add transaction friction for Kuwaiti and Saudi purchasers using offshore liquidity.
- Construction Input Volatility:Premium finishing materials and smart home systems face supply lead time extensions from European and East Asian component manufacturers.
Strategic Opportunities
- Concierge Service Integration:Embedded lifestyle management and property stewardship packages are commanding price premiums in Seef District high-rise inventory.
- Secondary Market Liquidity:Completed villa stock in Manama's established neighborhoods trades at velocity premiums versus off-plan developments, attracting yield-focused institutional capital.
- Smart Home Convergence:Integrated building management systems and IoT-enabled security infrastructure are differentiating premium developments from standard luxury completions.
Industry Challenges
- Title Transparency Verification:The Survey and Land Registration Bureau's documentation standards create due diligence timelines that delay foreign investor closing cycles.
- Specialized Property Management Talent:Shortages of bilingual concierge operators and hospitality-trained facility managers constrain service-level execution in master-planned communities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Luxury Residential Real Estate Market |
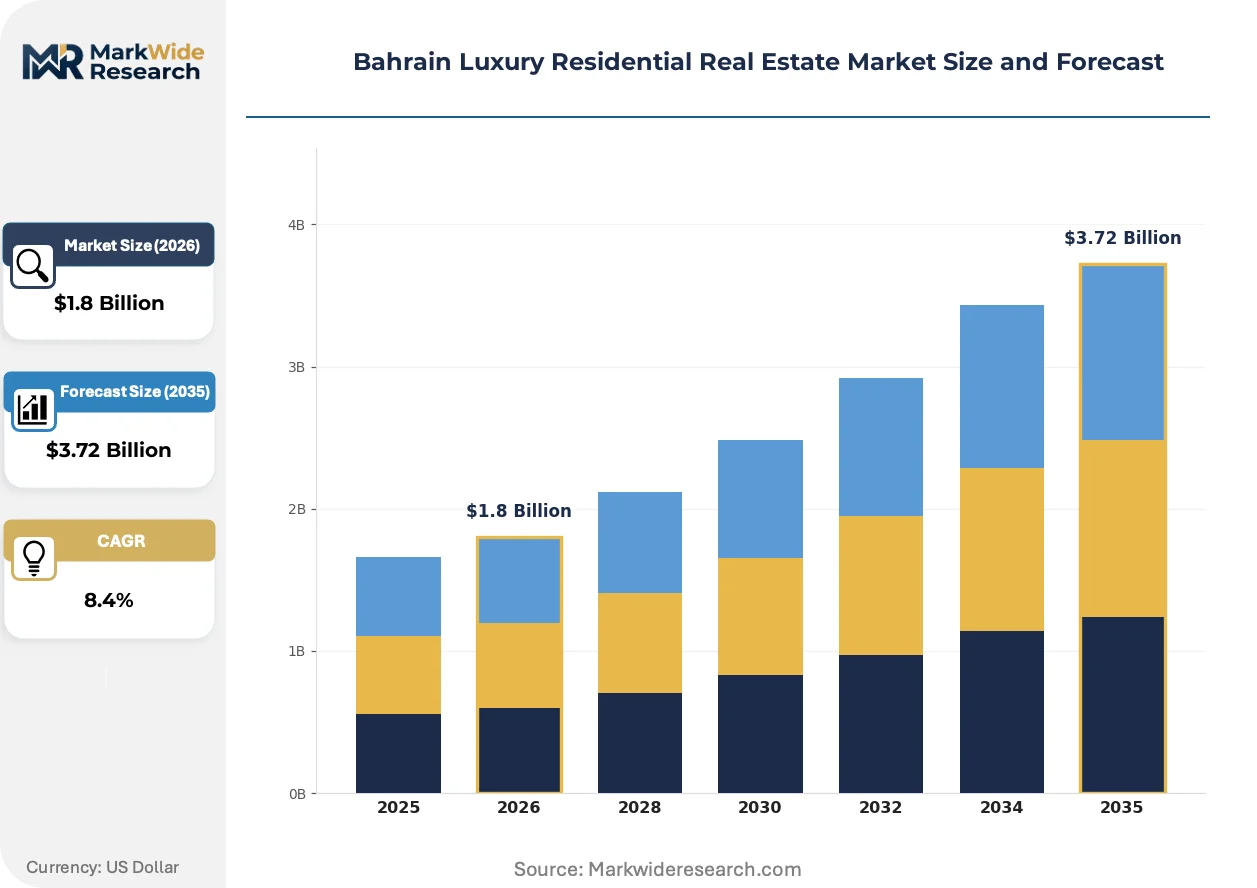
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Villa, Apartment, Penthouse, Duplex Client Type: Expatriate, Local Investor, Foreign Investor, High-Net-Worth Individual Development Stage: Pre-Construction, Under Construction, Completed, Renovation Financing Option: Cash Purchase, Mortgage, Installment Plan, Lease Purchase |
| Companies Covered | Manara Developments, Carlton Real Estate, Diyar Al Muharraq, Bin Faqeeh, Golden Gate, Naseej B.S.C, Seef Properties, Eagle Hills, Durrat Khaleej Al Bahrain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Luxury Residential Real Estate Market Strategic Shifts
Technology integration and regulatory recalibration are compressing traditional development cycles while elevating service-layer expectations among Gulf family buyers.
Smart home automation systems are converging with building-wide energy management platforms in Diyar Al Muharraq's newest phases. Saudi and Kuwaiti family buyers are specifying integrated IoT infrastructure as a baseline requirement rather than upgrade option. This convergence is compressing the feature gap between hospitality-grade serviced residences and traditional owner-occupied villas.
Bahrain's Central Bank has tightened foreign currency exposure rules for mortgage providers serving non-resident purchasers. The regulation compresses financing flexibility for cross-border buyers while pushing demand toward cash-dominant transactions. Expatriate professionals from India and the United Kingdom are responding by concentrating searches in completed inventory with immediate title transfer capacity.
Buyer preference is rotating toward embedded lifestyle services that bundle property management with hospitality access. Traditional brokerage channels are ceding ground to developer-direct sales teams offering concierge onboarding and leaseback arrangements. This behavioral pivot is most visible in Seef District, where Eagle Hills and Seef Properties compete through service-layer differentiation rather than unit specifications alone.
Bahrain Luxury Residential Real Estate Market Segmentation
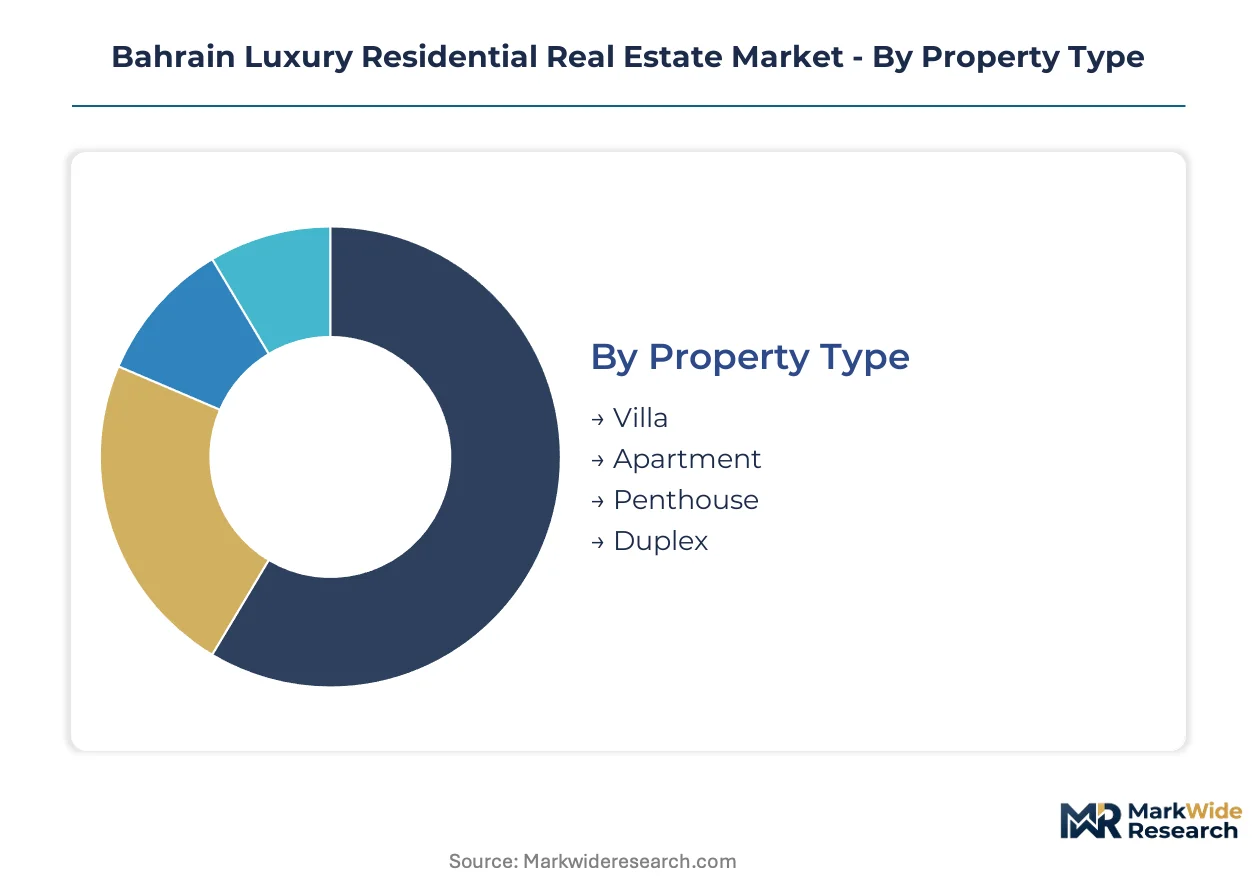
Segmentation in Bahrain's luxury residential market exposes divergent buyer priorities across property formats and capital sources. Developers calibrate product specifications and sales channel strategies to match distinct purchasing behaviors and financing capacities within each segment cluster.
Property Type:
Customization intensity varies sharply across this category, from bespoke villa architecture to standardized high-rise apartment configurations.
- Villa:Standalone structures typically exceeding 400 square meters with private gardens, pools, and marina access. Demand concentrates in Diyar Al Muharraq's waterfront phases where Saudi family buyers prioritize privacy and multi-generational living configurations. Scarcity of developable coastal land amplifies price premiums for completed stock.
- Apartment:High-rise units ranging from 120 to 300 square meters within mixed-use towers. Expatriate professionals from India and the United Kingdom dominate acquisition in Seef District developments where immediate title transfer bypasses Central Bank financing restrictions for non-residents.
- Penthouse:Top-floor configurations with dedicated elevator access and panoramic terrace space. Kuwaiti investors target these units for yield-focused portfolios in Manama's established secondary market.
- Duplex:Two-level units bridging apartment density with villa-style spatial separation. Local Bahraini families favor these for urban proximity without full high-rise living.
Leading the category by volume: Villa. Expanding most quickly: Apartment.
Client Type:
Capital origin and residency status determine access to financing instruments and qualifying developments under Economic Development Board regulations.
- Expatriate:Salaried professionals from South Asia, Europe, and other Gulf states seeking primary residences or rental yield assets. Bahrain's absence of property taxes and streamlined visa pathways attracts this segment away from Dubai's saturated supply.
- Local Investor:Bahraini nationals leveraging domestic banking relationships and higher Central Bank LTV ratios for portfolio expansion. This segment concentrates in pre-construction acquisitions for margin capture.
- Foreign Investor:Non-Gulf international buyers utilizing cash-dominant transactions to circumvent currency hedging requirements. Immediate title transfer capacity in completed inventory drives search behavior.
- High-Net-Worth Individual:Ultra-affluent buyers from Saudi Arabia and Kuwait purchasing multiple units for family compound arrangements. Residency-by-investment thresholds channel demand toward qualifying price tiers in master-planned communities.
Dominant by transaction value: High-Net-Worth Individual. Steepest expansion trajectory: Expatriate.
Development Stage:
Risk-return profiles and liquidity timelines diverge across construction maturity phases.
- Pre-Construction:Off-plan sales enabling developers to secure construction financing while offering buyers entry pricing. Foreign investors face extended due diligence timelines under Survey and Land Registration Bureau documentation standards.
- Under Construction:Partially completed developments with visible progress reducing execution risk. Local investors favor this stage for payment plan flexibility.
- Completed:Finished inventory with immediate occupancy and rental income potential. Institutional capital targets this segment for yield certainty in Manama's secondary market.
- Renovation:Existing stock requiring modernization of systems and finishes. Limited pipeline due to scarcity of appropriately zoned vintage properties.
Highest transaction velocity: Completed. Gaining share fastest: Pre-Construction.
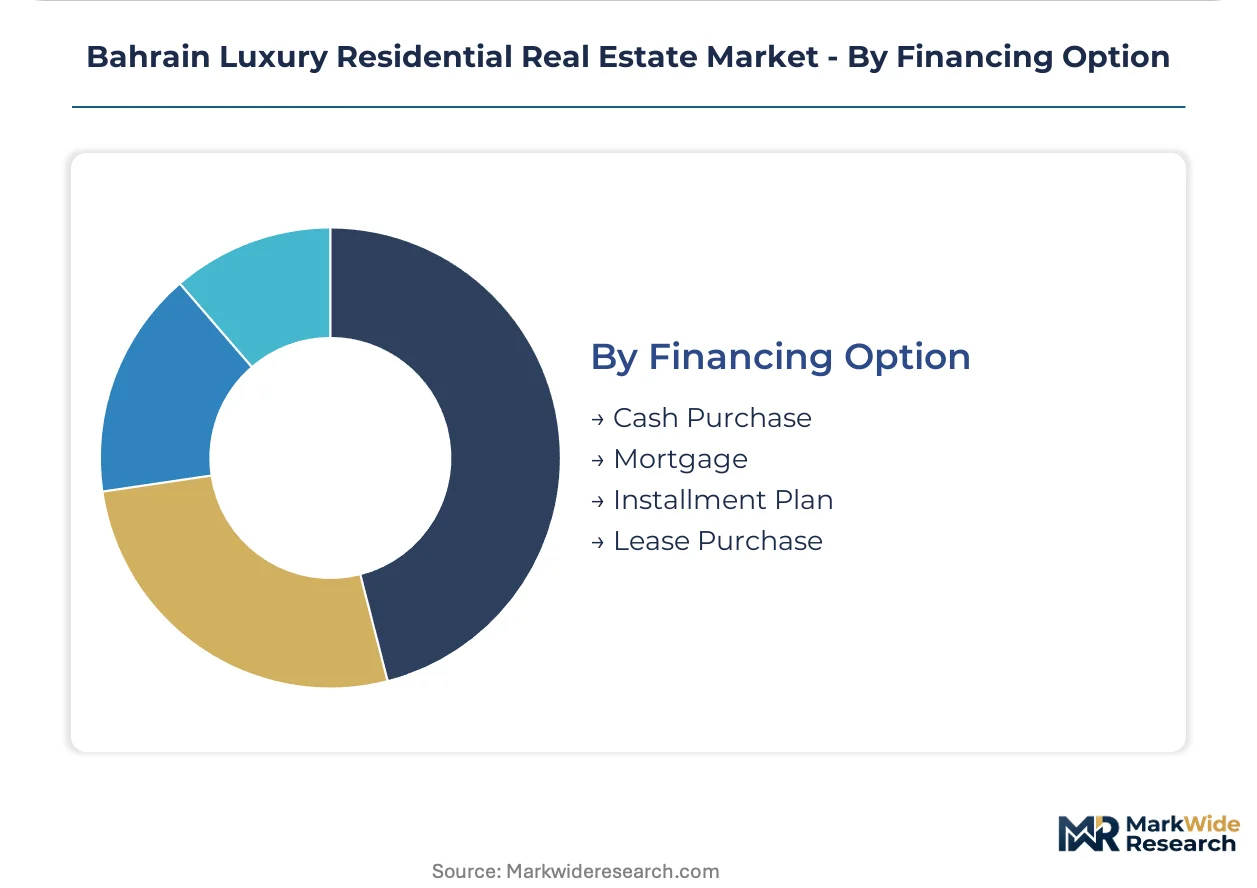
Financing Option:
Instrument selection reflects buyer residency status and exposure to Central Bank regulatory constraints.
- Cash Purchase:Full upfront settlement eliminating financing friction and currency hedging requirements. Saudi and Kuwaiti buyers dominate this instrument for speed and negotiating leverage.
- Mortgage:Bahraini dinar-denominated lending subject to Central Bank LTV caps and foreign currency exposure rules. Accessible primarily to resident buyers and citizens.
- Installment Plan:Developer-extended payment schedules tied to construction milestones. Expatriate professionals utilize this structure when mortgage eligibility is restricted.
- Lease Purchase:Rent-to-own arrangements with purchase option clauses. Limited availability in luxury segments due to developer preference for outright sales.
Prevalent by transaction count: Cash Purchase. Climbing the fastest: Installment Plan.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of luxury residential inventory concentrates in Bahrain's Northern Governorate while consumption draws capital from across the Gulf Cooperation Council. The kingdom's island geography constrains developable waterfront land, amplifying competition for master-planned communities. Cross-border investment flows from Saudi Arabia and Kuwait now exceed domestic Bahraini purchasing power in premium villa segments.
Saudi Arabia
High-net-worth families from Riyadh and Dammam are reallocating residential investment portfolios toward Bahrain's yield-focused villa stock. The Saudi Central Bank's stricter mortgage qualification rules for second homes are channeling discretionary capital offshore. Eastern Province buyers concentrate acquisition activity in Diyar Al Muharraq's waterfront phases for multi-generational compound arrangements.
Kuwait
Kuwaiti investors target penthouse configurations and completed secondary market inventory for rental yield portfolios. The Central Bank of Kuwait's foreign currency exposure limits on domestic real estate lending are pushing capital toward Bahrain's dinar-denominated assets. Hawally and Salmiya-based family offices are establishing direct developer relationships in Manama's Seef District.
United Arab Emirates
Emirati buyers historically dominant in Gulf property markets are reducing Bahrain exposure amid Dubai's oversupply correction and price compression. The Dubai Land Department's transaction fee increases are redirecting some institutional capital toward Bahrain's lower-friction acquisition environment. Abu Dhabi-based sovereign wealth vehicles are evaluating master-planned community stakes in Diyar Al Muharraq.
Qatar
Qatari family capital is emerging as a new demand source following FIFA 2022 infrastructure completion and domestic market saturation. The Qatar Central Bank's real estate lending caps are encouraging offshore diversification into Bahrain's residency-linked property tiers. Doha-based buyers are concentrating searches in completed inventory with immediate title transfer capacity.
United Kingdom
British expatriate professionals are expanding search activity in Bahrain's luxury apartment segment following UK tax residency changes and sterling weakness. The absence of property taxes and capital gains levies is attracting London-based diaspora capital. British buyers cluster in Seef District high-rises where Eagle Hills and Seef Properties compete through service-layer differentiation.
Bahrain Luxury Residential Real Estate Market Competitive Environment
Capital-heavy developers with land bank control compete with asset-light operators focused on sales velocity and concierge service packaging. The market structures around three tiers: sovereign-linked master-planned community developers, district-dominant mixed-use specialists, and boutique villa fabricators serving family compound demand. Strategic moves center on vertical integration into property management and embedded lifestyle services rather than pure unit specification competition.
Among the master-planned community developers, Diyar Al Muharraq anchors the waterfront villa segment through integrated island infrastructure, while Eagle Hills occupies a position exemplifying large-scale mixed-use development across hospitality and retail adjacencies. Seef Properties represents the district-dominant archetype, controlling commercial-residential zoning that sustains rental yields for investor buyers in the capital's core. These three developers collectively illustrate how Bahrain's competitive dynamics have shifted toward service-layer differentiation and residency-program integration rather than standalone residential product competition.
| Leading Market Players |
|---|
| Manara Developments |
| Carlton Real Estate |
| Diyar Al Muharraq |
| Bin Faqeeh |
| Golden Gate |
| Naseej B.S.C |
| Seef Properties |
| Eagle Hills |
| Durrat Khaleej Al Bahrain |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration into captive property management services anchors developer pricing power while compressing third-party service margins across Bahrain's waterfront villa developments. This structural choice concentrates value capture upstream with master-planned community operators like Diyar Al Muharraq and Eagle Hills, insulating realized prices from construction input volatility while embedding recurring revenue streams that sustain premium valuations.
Pricing Analysis
Margin tightening in pre-construction villa inventory reflects Central Bank LTV caps constraining expatriate leverage capacity. Pricing stratifies across concierge-enabled premium tiers, standard specification levels, and entry-level waterfront positions, with differentiation driven by embedded lifestyle service bundling and immediate title transfer eligibility. Cost-down pressure on mid-tier apartments accelerates as Indian and British expatriates concentrate searches in completed Seef District stock. High-net-worth Saudi buyers exhibit lowest price sensitivity, prioritizing privacy and multi-generational configurations over per-square-meter economics.
Supply Chain Analysis
Specialized concierge operator shortages in the Philippines and Eastern European hospitality labor markets constrain service-level execution in Diyar Al Muharraq's newest phases. Premium finishing materials draw from Italian marble quarries, German smart home component manufacturers, and South Korean IoT security systems, creating multi-source dependencies with extended lead times. Single-source vulnerability concentrates in European building management system providers facing energy cost volatility. Distribution runs through developer-direct sales teams with embedded leaseback arrangements, bypassing traditional brokerage channels in Seef District and Manama's secondary market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of developable waterfront land in Bahrain's Northern Governorate props pricing across all villa segments, creating structural supply constraints that favor incumbent land bank holders and compress new entrant access windows.
For Market Incumbents: To counter emerging competition from Qatar-based family offices entering post-FIFA 2022, Diyar Al Muharraq and Eagle Hills should deepen backward integration into bilingual concierge training academies and secure captive smart home installation capabilities. This upstream control over service-layer execution preserves pricing premiums as differentiation shifts from unit specifications to lifestyle packaging. For New Entrants and Emerging Players: Launch via direct-to-investor sales platforms targeting British expatriate professionals in Seef District's completed apartment inventory, where immediate title transfer bypasses Central Bank financing friction. The most penetrable white-space sits in renovation-grade vintage properties requiring smart home modernization, with leaseback arrangements offering yield certainty to London-based diaspora capital seeking tax-efficient Gulf exposure. For Investors and Strategic Acquirers: Exit pathways concentrate in institutional acquisition of stabilized rental yield portfolios by Kuwaiti family offices and Saudi sovereign-linked vehicles. Long-term viability hinges on Bahrain's residency-by-investment program continuity and Central Bank regulatory stability. The signal to watch is Saudi Vision 2030 capital repatriation intensity, which would compress cross-border investment flows and trigger yield expansion in secondary market villa stock.| Strategic Initiative | Industry Significance |
|---|---|
| Concierge Service Integration | Embedded lifestyle management commands price premiums in Seef District high-rise inventory. |
| Smart Home Convergence | IoT-enabled security infrastructure differentiates premium Diyar Al Muharraq phases from standard completions. |
| Residency-Linked Development | Economic Development Board visa tiers channel Saudi and Kuwaiti capital toward qualifying price thresholds. |
| Secondary Market Liquidity Buildout | Completed villa stock in Manama trades at velocity premiums attracting institutional yield-focused capital. |
| Backward Integration into Property Management | In-house concierge operations address specialized talent shortages constraining master-planned community execution. |
Study Parameters
Central Bank regulatory filings, Economic Development Board investment promotion disclosures, and Survey and Land Registration Bureau transaction records formed the secondary backbone for this analysis. Primary interviews with property development executives, hospitality-trained facility managers, mortgage lending officers at Bahraini retail banks, and concierge service operators validated demand-side assumptions. Developer sales directors and expatriate buyer representatives supplied ground-level pricing intelligence. Bottom-up unit absorption estimates triangulated against top-down construction permit data across the analysis window.
Historical transaction velocity patterns in Manama's secondary market and pre-construction sales cycles in Diyar Al Muharraq established baseline trendlines for forward projection. The analytical framework modeled segmentation across property type, client residency status, development stage maturity, and financing instrument selection throughout the forecast period. CAGRs derived from compound growth trajectory analysis of waterfront villa premiums and apartment rental yield compression. Forecast inputs incorporated Saudi capital diversion intensity, Central Bank interest rate sensitivity, and European smart home component lead time variability.
Saudi Vision 2030 capital repatriation acceleration, Central Bank foreign currency exposure rule tightening, and construction input cost volatility from European energy markets are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions around residency program continuity and regional geopolitical stability. Material deviation in Gulf Cooperation Council cross-border investment flows or Bahraini monetary policy trajectory warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market