
 Canada Luxury Residential Real Estate Market | 2026-2036
Canada Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Luxury Residential Real Estate Market Outlook
Private equity co-investment structures is tilting capital formation toward institutional-grade trophy assets in Toronto and Vancouver. Brookfield Residential leverages its asset management heritage to structure institutional partnerships that lower individual capital commitment thresholds. Concord Pacific anchors its competitive stance through integrated master-planned communities that combine residential towers with hospitality and retail components. Tridel differentiates via in-house construction management that compresses delivery timelines for concrete high-rise condominiums.
Canada luxury residential real estate encompasses freehold and strata-titled properties trading above regional median thresholds, typically featuring premium materials, bespoke architectural design, concierge services, and integrated smart-home infrastructure. The asset class functions as both a consumption good for owner-occupiers and a store of capital for domestic and offshore wealth preservation. Single-family estates and ultra-luxury condominiums command the deepest margin pools, while townhouse product faces compressed spreads from land assembly costs in supply-constrained municipalities. Cash purchases and private equity financing models attract the fastest-growing buyer cohort, as affluent individuals seek to circumvent OSFI-regulated mortgage qualification constraints.
Health Canada and the Canada Mortgage and Housing Corporation (CMHC) shape environmental and affordability standards that indirectly filter luxury development feasibility, while provincial land use tribunals in Ontario and British Columbia govern density permissions and community amenity contributions. The Financial Transactions and Reports Analysis Centre of Canada (FINTRAC) anti-money laundering disclosure requirements add compliance layers to high-value closings. Stakeholders must monitor how municipal inclusionary zoning bylaws and provincial foreign-buyer tax regimes redistribute transaction velocity across sub-markets.
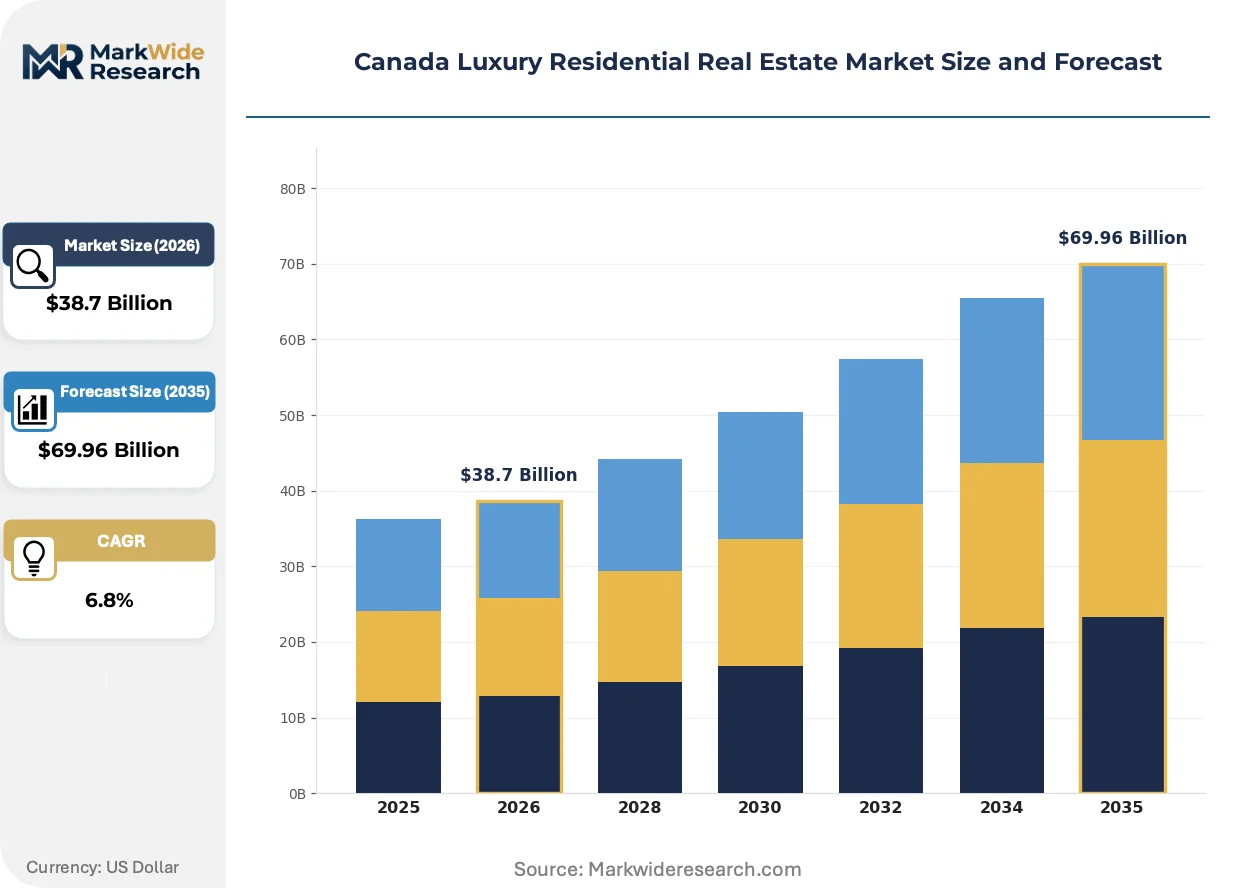
Market Dynamics
Private equity co-investment structures are tilting capital formation toward institutional-grade trophy assets in Toronto and Vancouver, compressing individual capital commitment thresholds while amplifying deal velocity for ultra-luxury condominiums and single-family estates.
Growth Catalysts
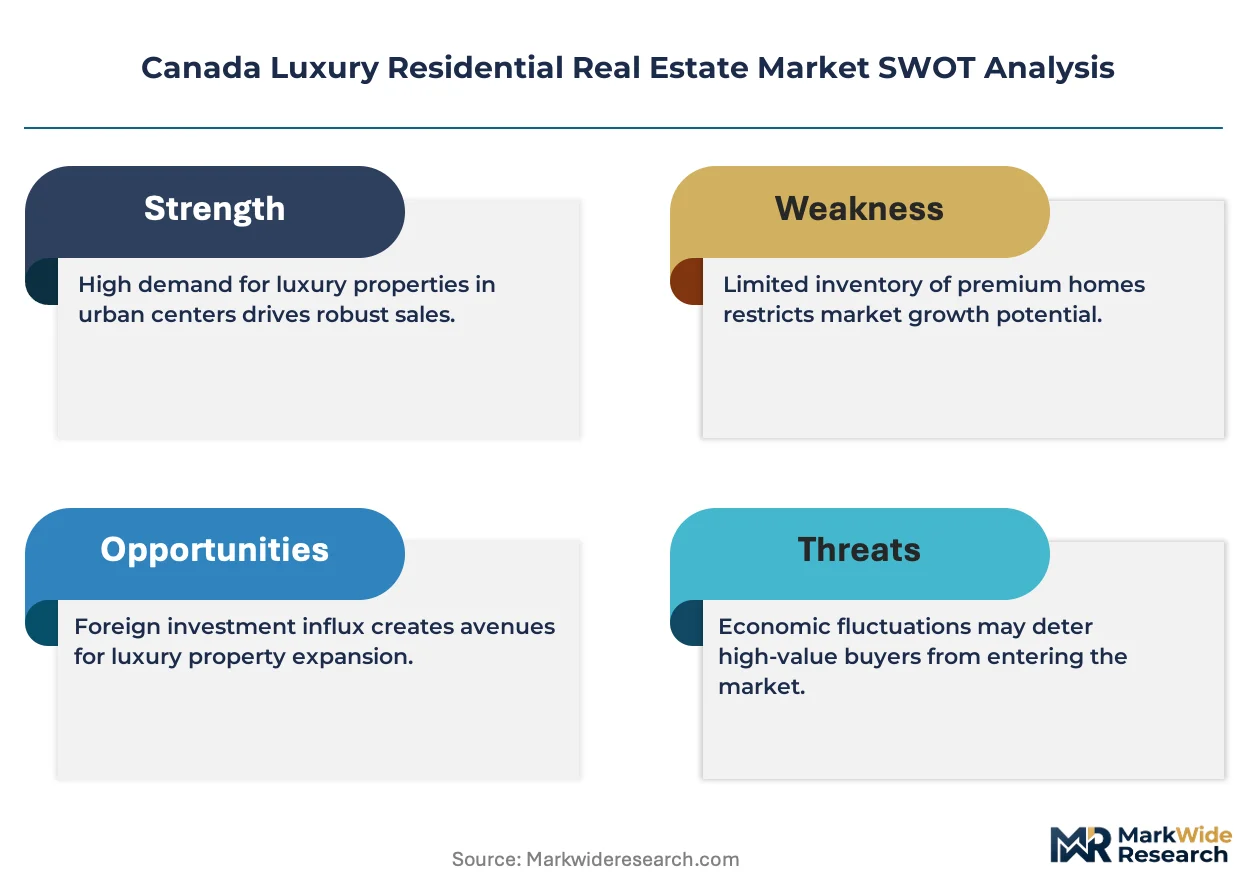
- OSFI Stress Test Arbitrage:Cash purchasers and private equity financing models circumvent mortgage qualification constraints, accelerating transaction velocity for trophy assets above conventional lending thresholds.
- Technology Sector Wealth Formation:Ultra-high-net-worth individuals from software and fintech verticals are expanding footprint in west-side Vancouver and Yorkville corridors, concentrating demand in sub-markets with concierge infrastructure.
- Master-Planned Density Bonuses:Municipal community amenity contribution frameworks in Ontario and British Columbia reward integrated hospitality-retail-residential assemblies with additional floor-area ratio entitlements.
Market Restraints
- Land Assembly Cost Escalation:Supply-constrained municipalities in the Greater Toronto Area face compressed development spreads as fragmented ownership patterns inflate site aggregation premiums for townhouse product.
- FINTRAC Compliance Layering:Anti-money laundering disclosure requirements for high-value closings add transactional friction, extending due diligence timelines for offshore capital sources.
- Concrete and Steel Input Volatility:High-rise construction faces margin pressure from fluctuating commodity pricing for structural materials, compressing feasibility for concrete condominium towers.
Strategic Opportunities
- Calgary-Edmonton Corridor Expansion:Underpenetrated Alberta markets present white space for luxury product as energy sector wealth seeks diversified domestic holdings beyond traditional Vancouver-Toronto axis.
- Smart-Home Infrastructure Convergence:Integration of building automation with wellness monitoring systems creates differentiation premium for new construction targeting health-conscious owner-occupiers.
- Inclusionary Zoning Arbitrage:Municipal bylaws in Ontario redistribute density permissions toward mixed-income assemblies, enabling luxury developers to secure larger footprints through affordable component integration.
Industry Challenges
- Skilled Trades Scarcity:Specialized concrete forming and curtain-wall installation expertise faces acute shortage, extending delivery timelines for high-rise condominiums and compressing developer carry costs.
- Provincial Tribunal Delays:Ontario Land Tribunal and British Columbia's Environmental Assessment Office backlog extends entitlement timelines, freezing capital in pre-construction phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Luxury Residential Real Estate Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Townhouses, Estates Price Tier: High-End, Ultra-Luxury, Premium, Mid-Range Buyer Profile: Affluent Individuals, Investors, Vacation Home Buyers, Expats Financing Model: Cash Purchases, Mortgages, Investment Loans, Private Equity |
| Companies Covered | Brookfield Residential, Concord Pacific, Westbank Corp, Tridel, Daniels Corporation, Onni Group, Valencia Residential, Sotheby's International Realty Canada, Mattamy Homes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Luxury Residential Real Estate Market Strategic Shifts
Digital twin technology and building information modeling are compressing pre-construction marketing cycles while regulatory pressure on embodied carbon reshapes material specifications for trophy assets.
Virtual staging platforms are virtualizing buyer engagement for pre-construction condominiums. Ultra-high-net-worth purchasers now evaluate floor plans through immersive renderings before physical site visits. This compression of the decision timeline is virtualizing traditional brokerage relationships and shifting commission structures toward digital lead-generation platforms.
Health Canada and CMHC energy efficiency standards are tightening thermal performance requirements for new construction. Developers face incremental capital costs for high-performance envelope assemblies. Vancouver's west-side corridor and Toronto's waterfront sub-markets are responding with Passive House-certified product commanding measurable price premiums.
Wealth preservation motives are displacing lifestyle-driven purchasing in offshore buyer segments. FINTRAC disclosure thresholds and provincial foreign-buyer tax regimes have redirected transaction velocity toward domestic holding structures and nominee arrangements. British Columbia's speculation and vacancy tax enforcement is most visible in downtown Vancouver condominium sub-markets.
Canada Luxury Residential Real Estate Market Segmentation
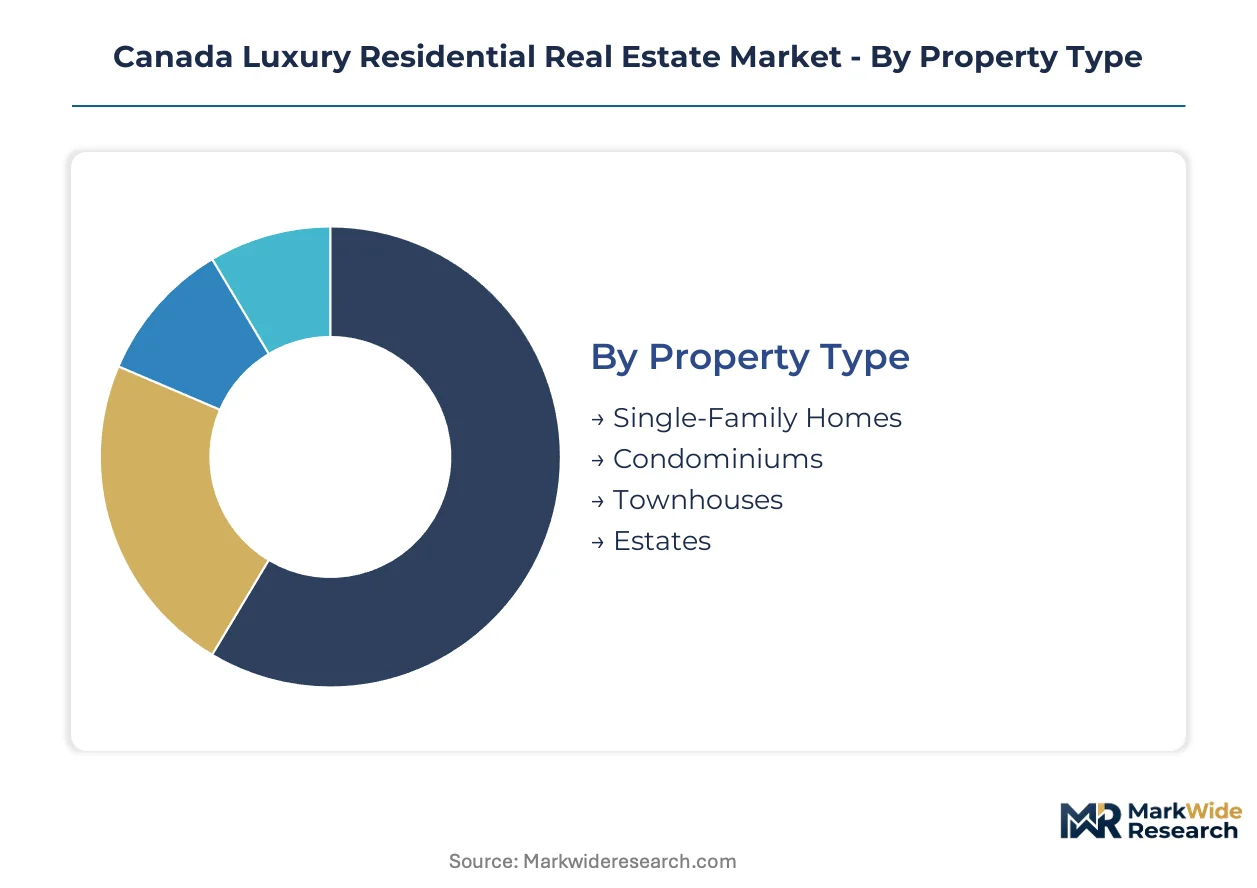
Segmentation in Canadian luxury residential real estate reveals how capital formation, buyer motivation, and regulatory constraints fragment across distinct product and financing categories. Understanding these divisions exposes where margin pools concentrate and where transaction velocity faces friction from OSFI qualification thresholds or FINTRAC compliance layering.
Property Type:
Mature product formats dominate transaction volume while emerging typologies reshape development feasibility in supply-constrained municipalities.
- Single-Family Homes:Freehold detached structures on assembled land parcels in Vancouver's west-side corridors and Toronto's Bridle Path district. Demand concentrates among technology-sector wealth seeking privacy and land scarcity premiums, though land assembly costs compress developer margins in the Greater Toronto Area.
- Condominiums:Strata-titled vertical residences in concrete high-rise towers featuring concierge infrastructure and smart-home integration. Yorkville and downtown Vancouver sub-markets absorb the deepest institutional capital pools as private equity co-investment structures lower individual commitment thresholds for trophy assets.
- Townhouses:Medium-density attached dwellings facing compressed spreads from fragmented ownership patterns in supply-constrained municipalities. Site aggregation premiums inflate land costs disproportionately relative to achievable pricing.
- Estates:Large-format rural and waterfront properties functioning as primary wealth preservation vehicles for offshore capital. FINTRAC disclosure requirements and provincial speculation taxes redirect transaction velocity toward domestic holding structures.
Condominiums handle the majority of throughput; estates are expanding most quickly on share as wealth preservation motives displace lifestyle-driven purchasing.
Price Tier:
Cost stratification determines buyer qualification pathways and exposure to mortgage stress test arbitrage opportunities.
- High-End:Properties trading significantly above regional medians with premium materials and bespoke architectural design. Toronto and Vancouver corridors concentrate demand from affluent domestic buyers navigating OSFI-regulated financing.
- Ultra-Luxury:Trophy assets commanding the deepest margin pools with integrated hospitality components and wellness infrastructure. Cash purchasers and private equity financing circumvent conventional lending constraints entirely.
- Premium:Entry-luxury segment where buyer qualification thresholds filter demand most acutely. Municipal inclusionary zoning frameworks in Ontario redistribute density permissions toward mixed-income assemblies at this tier.
- Mid-Range:Transitional luxury product facing compression from construction input volatility and skilled trades scarcity. Concrete and steel price fluctuations disproportionately impact feasibility for this segment.
Ultra-Luxury commands the steepest price premiums; Premium is climbing the fastest as municipal density bonuses enable larger footprints through affordable component integration.
Buyer Profile:
Customer motivation shapes transaction velocity and holding period expectations across domestic and offshore capital sources.
- Affluent Individuals:Domestic owner-occupiers prioritizing lifestyle amenities and concierge services in master-planned communities. Concord Pacific's integrated hospitality-retail-residential assemblies target this cohort in Vancouver.
- Investors:Capital preservation-focused purchasers utilizing nominee arrangements to navigate foreign-buyer tax regimes. British Columbia's speculation and vacancy tax enforcement is most visible in downtown Vancouver condominium sub-markets.
- Vacation Home Buyers:Seasonal occupants seeking recreational properties in underpenetrated Alberta markets. Energy sector wealth drives diversification beyond traditional Vancouver-Toronto axis.
- Expats:Offshore capital sources facing extended due diligence timelines from FINTRAC anti-money laundering disclosure requirements. Compliance layering redirects transaction structures toward domestic holding vehicles.
Affluent Individuals anchor transaction volume; Vacation Home Buyers are gaining share fastest as Calgary-Edmonton corridor expansion creates white space for luxury product.
Financing Model:
Capital structure determines transaction velocity and exposure to regulatory qualification constraints.
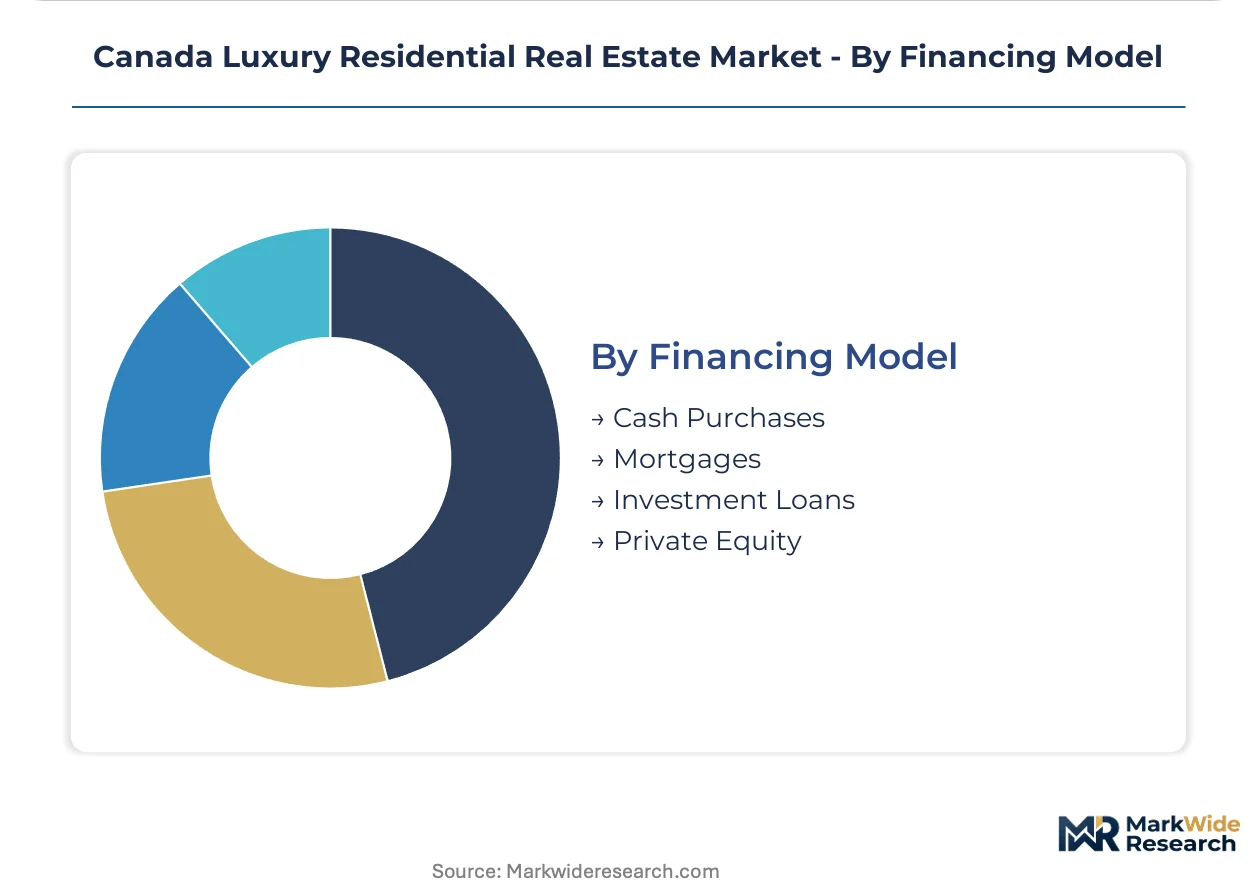
- Cash Purchases:Unencumbered acquisitions eliminating OSFI mortgage stress test exposure entirely. This model attracts the fastest-growing buyer cohort seeking to circumvent regulated qualification thresholds.
- Mortgages:Conventional financing subject to OSFI qualification rules filtering buyer access above regional median thresholds. Stress test arbitrage disadvantages this structure for trophy asset acquisition.
- Investment Loans:Purpose-built credit facilities for portfolio acquisition with asset-backed security structures. Terms tighten disproportionately for offshore capital sources facing enhanced due diligence.
- Private Equity:Institutional co-investment structures compressing individual capital commitment thresholds while amplifying deal velocity. Brookfield Residential leverages asset management heritage to structure these partnerships.
Cash Purchases dominate transaction value; Private Equity is expanding most quickly as institutional capital tilts toward trophy assets in Toronto and Vancouver.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's luxury residential real estate market exhibits pronounced regional concentration, with capital flows and transaction velocity clustering in specific metropolitan corridors rather than distributing evenly across provinces. Domestic wealth preservation motives and offshore capital deployment patterns create distinct demand signatures across sub-markets.
Ontario
Technology sector wealth formation concentrates demand in Toronto's Yorkville corridor and the Bridle Path district, where ultra-high-net-worth individuals seek privacy and concierge infrastructure. The Ontario Land Tribunal governs density permissions and community amenity contributions that reward integrated hospitality-retail-residential assemblies. Tridel anchors development activity in Toronto's concrete high-rise condominium sub-market through in-house construction management capabilities.
British Columbia
West-side Vancouver corridors absorb the deepest institutional capital pools as private equity co-investment structures lower individual commitment thresholds for trophy assets. British Columbia's speculation and vacancy tax enforcement redirects transaction velocity toward domestic holding structures and nominee arrangements. Concord Pacific leverages integrated master-planned communities combining residential towers with hospitality and retail components to secure competitive positioning.
Alberta
Energy sector wealth drives diversification into underpenetrated Calgary-Edmonton corridor markets, creating white space for luxury product beyond the traditional Vancouver-Toronto axis. Provincial land use frameworks in Alberta present fewer density permission constraints than Ontario or British Columbia counterparts. Calgary's emerging luxury sub-markets attract vacation home buyers seeking recreational properties with lower regulatory friction than coastal alternatives.
Quebec
Montreal's luxury condominium market attracts affluent domestic buyers navigating more permissive municipal zoning frameworks than Toronto or Vancouver equivalents. Quebec's provincial environmental assessment processes create distinct entitlement timelines compared to Ontario Land Tribunal backlogs. Limited offshore capital penetration distinguishes Montreal's buyer profile from west-side Vancouver or Yorkville corridors.
Canada Luxury Residential Real Estate Market Competitive Environment
On the supply side, the industry is consolidating around asset management heritage and integrated development capabilities rather than pure construction scale. Tiered competitive positioning separates institutional-grade trophy asset specialists from regional master-planned community developers. Strategic archetypes include private equity partnership structures, vertical integration through in-house construction management, and hospitality-retail-residential assembly platforms. Dominant competitive moves encompass municipal density bonus capture through affordable component integration and geographic expansion into underpenetrated Alberta corridors.
Within the institutional partnership tier, Brookfield Residential exemplifies asset management heritage applied to residential development through co-investment structures that compress individual capital commitment thresholds. Concord Pacific occupies a position anchored in integrated master-planned communities, while Tridel represents the vertical integration archetype through captive construction management capabilities that compress delivery timelines for concrete high-rise product.
| Leading Market Players |
|---|
| Brookfield Residential |
| Concord Pacific |
| Westbank Corp |
| Tridel |
| Daniels Corporation |
| Onni Group |
| Valencia Residential |
| Sotheby's International Realty Canada |
| Mattamy Homes |
| Others |
Value Chain & Pricing Dynamics
Concrete and steel input markets in China and South Korea anchor cost structures for Canadian trophy assets, compressing feasibility margins for high-rise condominiums while concentrating developer pricing power in single-family estates where land scarcity premiums dominate.
Pricing Analysis
Ultra-high-net-worth cash purchasers anchor pricing stratification across premium, standard, and mid-range tiers in Toronto and Vancouver corridors. Price differentiation hinges on concierge infrastructure density and smart-home integration depth, with wellness-certified product commanding measurable premiums. Pricing pressure stems from OSFI-regulated mortgage qualification constraints filtering demand at entry-luxury thresholds. Domestic owner-occupiers exhibit highest price sensitivity, while offshore wealth preservation buyers demonstrate lowest elasticity.
Supply Chain Analysis
Specialized curtain-wall manufacturers and concrete forming contractors in Ontario and British Columbia hold concentrated capacity for high-rise luxury product. Raw material dependencies center on structural steel, architectural glass, and high-performance envelope assemblies. Supply chain risk manifests through skilled trades scarcity extending delivery timelines and inflating developer carry costs. Distribution runs through in-house construction management platforms and institutional co-investment partnerships rather than traditional general contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private equity co-investment platforms are reshaping capital formation economics, with interoperability between asset management heritage and development execution creating winner-take-most dynamics in trophy asset deployment.
For Market Incumbents: Insulate margin pools by deepening in-house construction management capabilities to compress delivery timelines, while securing density permissions through municipal inclusionary zoning arbitrage before regulatory frameworks tighten. Threat vectors include skilled trades scarcity inflating input costs and provincial tribunal delays freezing pre-construction capital. For New Entrants and Emerging Players: Pursue white space in Calgary-Edmonton corridor sub-markets where energy sector wealth seeks diversified domestic holdings beyond traditional Vancouver-Toronto concentration. Master-planned community formats with integrated hospitality-retail components represent the most penetrable segment. Go-to-market positioning should emphasize lower regulatory friction and faster entitlement timelines relative to coastal alternatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ultra-luxury condominiums as private equity structures compress individual commitment thresholds while amplifying deal velocity. Long-term viability favors asset management heritage platforms with captive construction capabilities over pure development scale. Acquisition target archetype: vertically integrated operators with municipal density bonus capture track records. Signal to monitor: OSFI stress test threshold adjustments filtering transaction velocity at entry-luxury tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Private Equity Co-Investment Structuring | Brookfield Residential leverages asset management heritage to lower individual capital commitment thresholds for trophy assets. |
| Integrated Master-Planned Community Development | Concord Pacific secures competitive positioning through hospitality-retail-residential assemblies with density bonus entitlements. |
| In-House Construction Management Investment | Tridel compresses delivery timelines for concrete high-rise product through captive vertical integration. |
| Smart-Home Infrastructure Convergence | Wellness monitoring integration creates differentiation premium targeting health-conscious owner-occupiers in Yorkville. |
| Calgary-Edmonton Geographic Expansion | Underpenetrated Alberta markets present white space for luxury product as energy wealth diversifies holdings. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of municipal planning records, FINTRAC disclosure filings, and CMHC construction data. Primary interviews engaged luxury developers, asset management executives, municipal planning officers, and high-net-worth buyer representatives. Secondary validation drew from Ontario Land Tribunal decisions, British Columbia speculation tax enforcement reports, and OSFI regulatory guidance. Bottom-up transaction analysis triangulates against top-down capital flow estimates across the analysis window.
Forecast inputs incorporate property type segmentation, price tier stratification, buyer profile motivation shifts, and financing model evolution. Modeled dimensions span single-family estates, condominiums, townhouses, and rural waterfront product across high-end, ultra-luxury, premium, and mid-range tiers. CAGRs derive from historical transaction velocity patterns projected through regulatory scenario modeling and capital formation trend analysis. Construction input cost trajectories and skilled labor availability curves inform feasibility-adjusted supply forecasts.
Sensitivities concentrate around OSFI stress test threshold revisions, provincial foreign-buyer tax regime adjustments, and concrete-steel commodity price volatility. Forecasts reflect documented assumptions regarding technology sector wealth formation persistence and offshore capital flow redirection patterns. Quarterly review of municipal inclusionary zoning bylaw amendments and provincial tribunal backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market