
 Ready-To-Move-In Luxury Homes Market | 2026-2036
Ready-To-Move-In Luxury Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Move-In Luxury Homes Market Analysis
The gap between bespoke luxury finishes and mass-market standardization is shifting as ready-to-move-in inventory commands premium velocity. DLF Ltd anchors its position through captive land banking across Delhi NCR, while Emaar Properties dominates Dubai's waterfront corridor with integrated lifestyle infrastructure. Toll Brothers differentiates through design studios that compress customization cycles without delaying occupancy.
Ready-to-move-in luxury homes denote fully constructed, immediately occupiable residential assets where developers retain control over architectural specification, interior fit-out, and amenity provisioning until handover; these properties typically feature engineered flooring systems, climate-controlled environments, and integrated building management interfaces serving buyers who prioritize time-value over bespoke construction timelines. Villa and penthouse inventory within the property type dimension captures the deepest margin pools, as waterfront and skyline positioning sustains price premiums independent of broader residential cycles. The customer type split reveals high-net-worth individuals and foreign nationals as the fastest-growing cohorts, with cross-border capital flows concentrating in tax-advantaged or visa-linked jurisdictions.
EMA's building energy codes across Europe, Dubai's RERA escrow mandates, and SEC disclosure requirements for US real estate investment vehicles collectively elevate compliance costs while filtering speculative development. India's RERA framework and BIS structural safety standards similarly tighten delivery accountability, compressing timelines between completion and occupancy certification. Stakeholders must monitor how evolving carbon performance benchmarks reshape material specifications and capital deployment priorities across development pipelines.
Market Dynamics
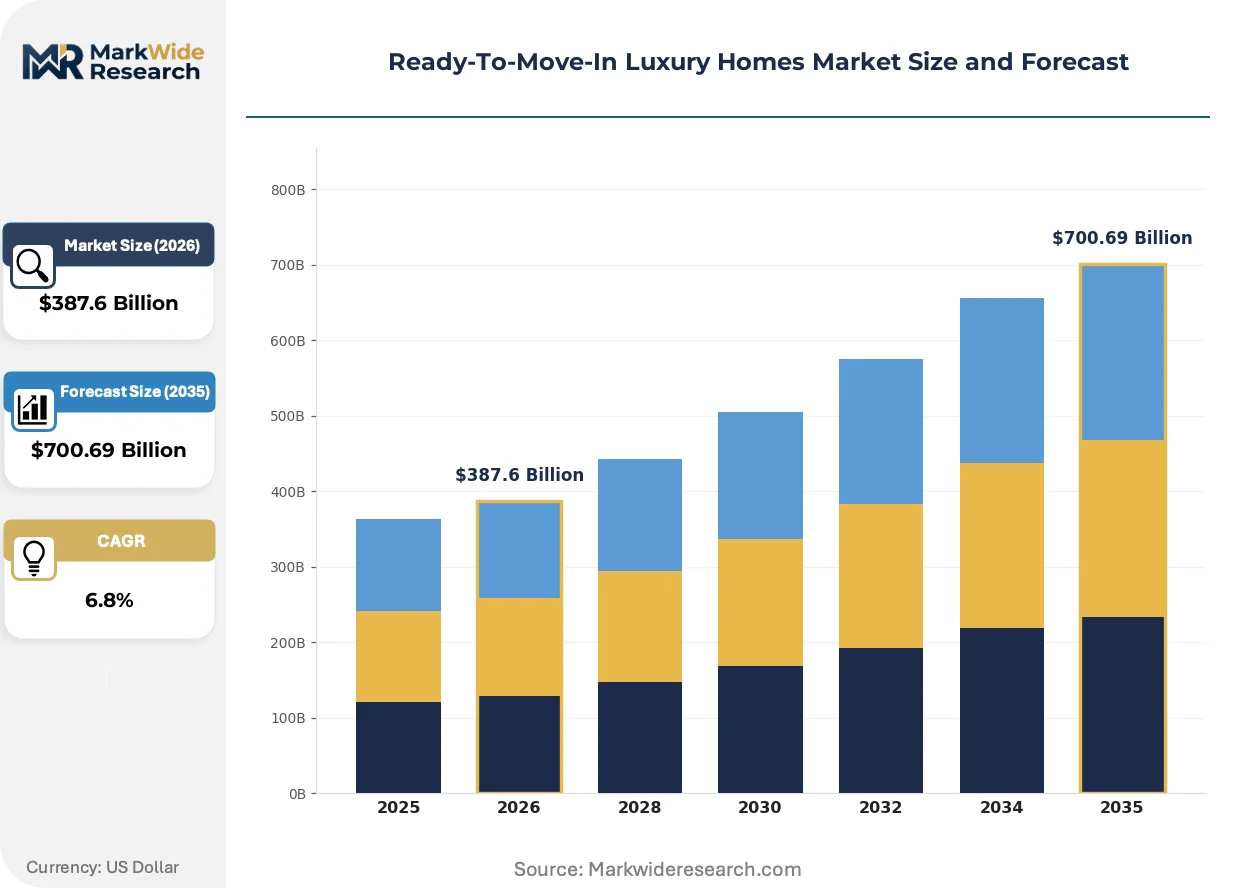
Ready-to-move-in luxury inventory commands velocity premiums as ultra-high-net-worth buyers compress decision timelines and developers internalize specification control to eliminate construction-phase friction. This structural shift from bespoke commissioning to developer-curated delivery concentrates margin capture upstream while compressing buyer agency.
Growth Catalysts
- Dubai RERA escrow mandates:The regulator's capital protection frameworks attract cross-border capital by eliminating completion risk, accelerating foreign national participation in waterfront corridors.
- Smart home integration:Pre-installed building management interfaces and IoT infrastructure reduce post-occupancy upgrade cycles, aligning with time-value priorities of executive buyers.
- Singapore:Visa-linked property investment pathways concentrate demand in penthouse inventory, with foreign ownership quotas channeling capital into certified luxury completions.
Market Restraints
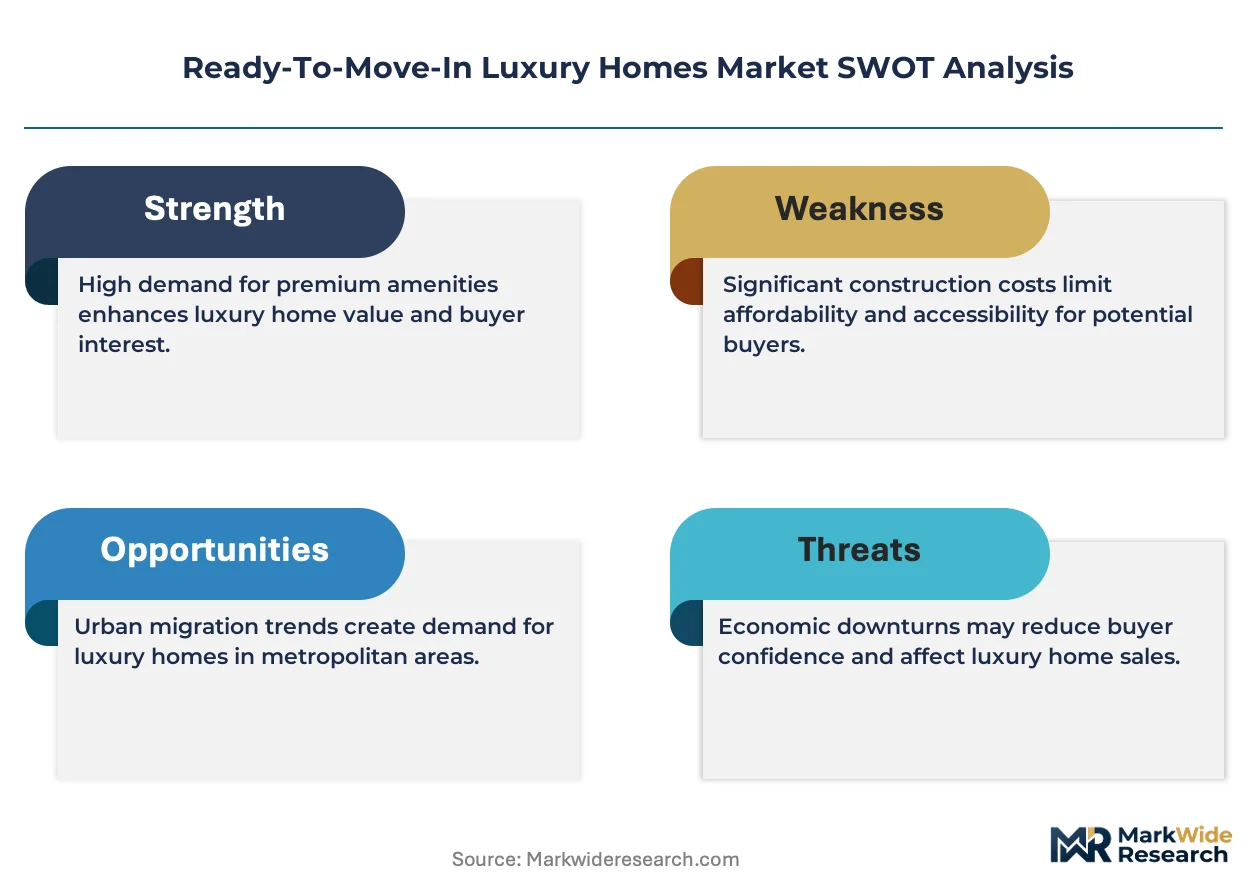
- Input cost volatility:Engineered stone, climate-control systems, and imported fixture packages expose developers to currency and commodity swings that compress margin buffers on fixed-price contracts.
- Supply concentration risk:Italian and German specialty manufacturers dominate premium flooring and kitchen systems, creating single-source vulnerability for projects targeting certification benchmarks.
- Technical limitation:Seismic and wind-load engineering constraints in coastal Miami and Dubai restrict floor-to-ceiling glazing spans, limiting design differentiation in waterfront clusters.
Strategic Opportunities
- India secondary cities:Underpenetrated demand in Hyderabad and Pune offers first-mover positioning as RERA compliance matures and HNWI density spreads beyond Mumbai and Delhi NCR.
- EU Green Deal building performance standards:Regulatory tailwinds for near-zero energy buildings create premium positioning for developers who pre-certify inventory above national minimums.
- Fractional ownership platforms:Technology-enabled co-ownership models expand addressable demand for penthouse inventory among sub-HNWI segments seeking trophy exposure.
Industry Challenges
- Project management talent scarcity:Developers struggle to source professionals capable of orchestrating compressed handover timelines across interior fit-out, MEP commissioning, and smart system integration.
- Green certification timelines:LEED Platinum and BREEAM Outstanding verification cycles often extend beyond marketing commitments, creating occupancy-permit friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Move-In Luxury Homes Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Penthouse, Bungalow, Villa, Townhouse Customer Type: Aspirational Buyers, High-Net-Worth Individuals, Investors, Foreign Nationals Price Tier: Mid-Range, Premium, Ultra-Premium, Affordable Luxury Development Stage: New Developments, Resale Properties, Custom Builds, Renovated Homes |
| Companies Covered | DLF Ltd, Emaar Properties, DAMAC Properties, Godrej Properties, Lodha Group, Sobha, Toll Brothers, Sun Hung Kai Properties, Aldar Properties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Move-In Luxury Homes Market Emerging Trajectories
Digital twin technology and predictive maintenance systems are redefining post-handover value propositions, while regulatory pressure on embodied carbon forces material specification changes upstream. Buyer expectations now encompass operational transparency from day one.
Building information modeling (BIM) is consolidating developer control over specification, scheduling, and cost forecasting across multi-tower projects. Emaar Properties and comparable developers deploy BIM to compress design-to-handover cycles without sacrificing finish quality. The technology is consolidating coordination authority within developer organizations, reducing architect and contractor autonomy while accelerating inventory velocity.
EU Green Deal carbon performance benchmarks and EMA building energy codes are mandating lifecycle emissions disclosure for residential assets above specified thresholds. Developers must now document embodied carbon in concrete, steel, and glass selections to secure financing and marketing authorization. Premium inventory in Frankfurt and Amsterdam faces the steepest compliance ramps, with projects retrofitting specifications to avoid stranding risk.
Cross-border buyers increasingly demand immediate occupancy without customization delays, displacing traditional pre-sale and bespoke construction models. This pattern concentrates in Dubai's waterfront villa clusters and Miami's Brickell corridor, where foreign nationals prioritize visa-linked security over design input. Singapore's restricted land release policy amplifies the effect, channeling demand into certified ready inventory with guaranteed completion dates.
Ready-To-Move-In Luxury Homes Market Segmentation
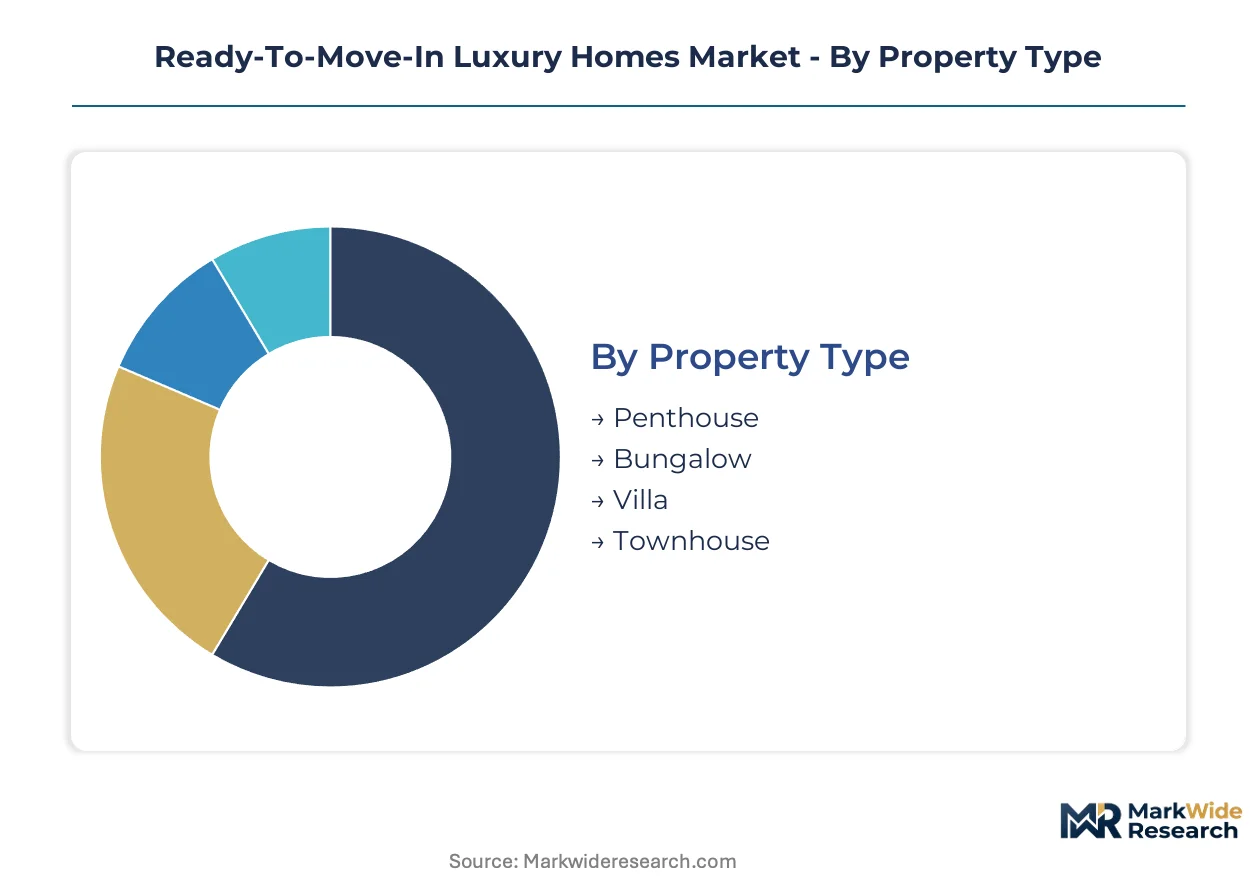
Segmentation in ready-to-move-in luxury homes reveals how developer control over specification intersects with buyer urgency and capital deployment patterns. Each dimension—property configuration, buyer profile, price positioning, and completion status—creates distinct velocity and margin profiles that reshape inventory strategy across metropolitan corridors.
Property Type:
Standalone structures command premium velocity against embedded units within larger developments, with waterfront positioning and vertical elevation driving differential pricing power.
- Villa:Detached single-family residences featuring private outdoor space and direct ground-level access. Waterfront clusters in Dubai and Miami absorb the deepest foreign capital pools, constrained only by seismic engineering limits on coastal glazing spans.
- Penthouse:Top-floor units occupying entire levels or double-height configurations with panoramic skyline exposure. Singapore's visa-linked investment pathways concentrate demand here, with foreign ownership quotas channeling capital into certified completions with guaranteed handover dates.
- Bungalow:Low-rise detached homes typically spanning single or split levels with dedicated garden plots. Hyderabad and Pune developers target this format for first-mover positioning as HNWI density spreads beyond established metros.
- Townhouse:Multi-level attached residences sharing structural walls while maintaining private entrances and outdoor zones. Delhi NCR land banking strategies favor this typology for density optimization within captive parcel holdings.
Villa inventory leads volumes today; penthouse units are gaining share fastest across cross-border buyer cohorts.
Customer Type:
Capital source and residency status determine decision velocity, with regulatory frameworks in host jurisdictions accelerating or constraining participation by foreign capital.
- High-Net-Worth Individuals:Domestic buyers with liquid assets exceeding conventional mortgage thresholds, prioritizing immediate occupancy over customization input. RERA escrow mandates in Dubai and BIS structural certifications in India compress their due diligence cycles.
- Foreign Nationals:Cross-border buyers seeking visa-linked security or tax-advantaged holding structures. Singapore's restricted land release and Dubai's RERA capital protection frameworks concentrate their demand in certified ready inventory.
- Investors:Institutional and family office capital deploying into trophy assets for yield or capital preservation. Fractional ownership platforms are expanding their addressable exposure to penthouse inventory previously gated by whole-asset price thresholds.
- Aspirational Buyers:Sub-HNWI segments accessing luxury positioning through compressed square footage or secondary location trade-offs. EU Green Deal building performance standards create premium positioning for their target inventory among near-zero energy certified completions.
High-net-worth individuals dominate transaction velocity currently; foreign nationals are expanding most quickly as regulatory certainty improves across host markets.
Price Tier:
Margin structure stratifies sharply across certification benchmarks, with green building credentials and smart system integration commanding discrete premiums independent of base construction costs.
- Ultra-Premium:Inventory exceeding institutional thresholds for trophy asset classification, typically featuring bespoke interior packages and integrated building management interfaces. Embodied carbon documentation requirements under EU Green Deal frameworks are reshaping material specifications upstream.
- Premium:Developer-curated finishes with LEED Platinum or BREEAM Outstanding pre-certification, positioned between mass luxury and bespoke commissioning. Verification cycle extensions often create friction between marketing commitments and occupancy permits.
- Mid-Range:Standardized luxury specifications targeting time-value buyers who prioritize immediate handover over customization agency. Input cost volatility in engineered stone and climate-control systems compresses margin buffers on fixed-price contracts.
- Affordable Luxury:Entry-point positioning within luxury-branded developments, trading square footage or location proximity for access to amenity infrastructure and address cachet. Secondary Indian cities offer first-mover positioning as RERA compliance matures.
Premium tier leads developer pipeline commitments today; ultra-premium inventory is climbing the fastest as carbon performance benchmarks reshape capital deployment priorities.
Development Stage:
Completion certainty and specification control vary inversely, with developer-retained authority over fit-out and commissioning accelerating velocity at the cost of buyer design input.
- New Developments:Ground-up construction with developer-controlled specification from structural systems through interior finish. BIM coordination consolidates scheduling authority within developer organizations, reducing architect and contractor autonomy.
- Resale Properties:Previously occupied units re-entering inventory with varying degrees of finish modernization. Singapore's restricted supply channels demand into this segment when certified new completions face foreign ownership quota constraints.
- Renovated Homes:Existing structures with comprehensive interior and MEP system replacement, positioned between new development velocity and custom build personalization. EU Green Deal retrofit mandates are accelerating capital flows here.
- Custom Builds:Buyer-commissioned construction with bespoke architectural and finish specification, displaced by ready-to-move-in velocity preferences in cross-border corridors. Miami's Brickell corridor and Dubai's waterfront clusters show declining share for this format.
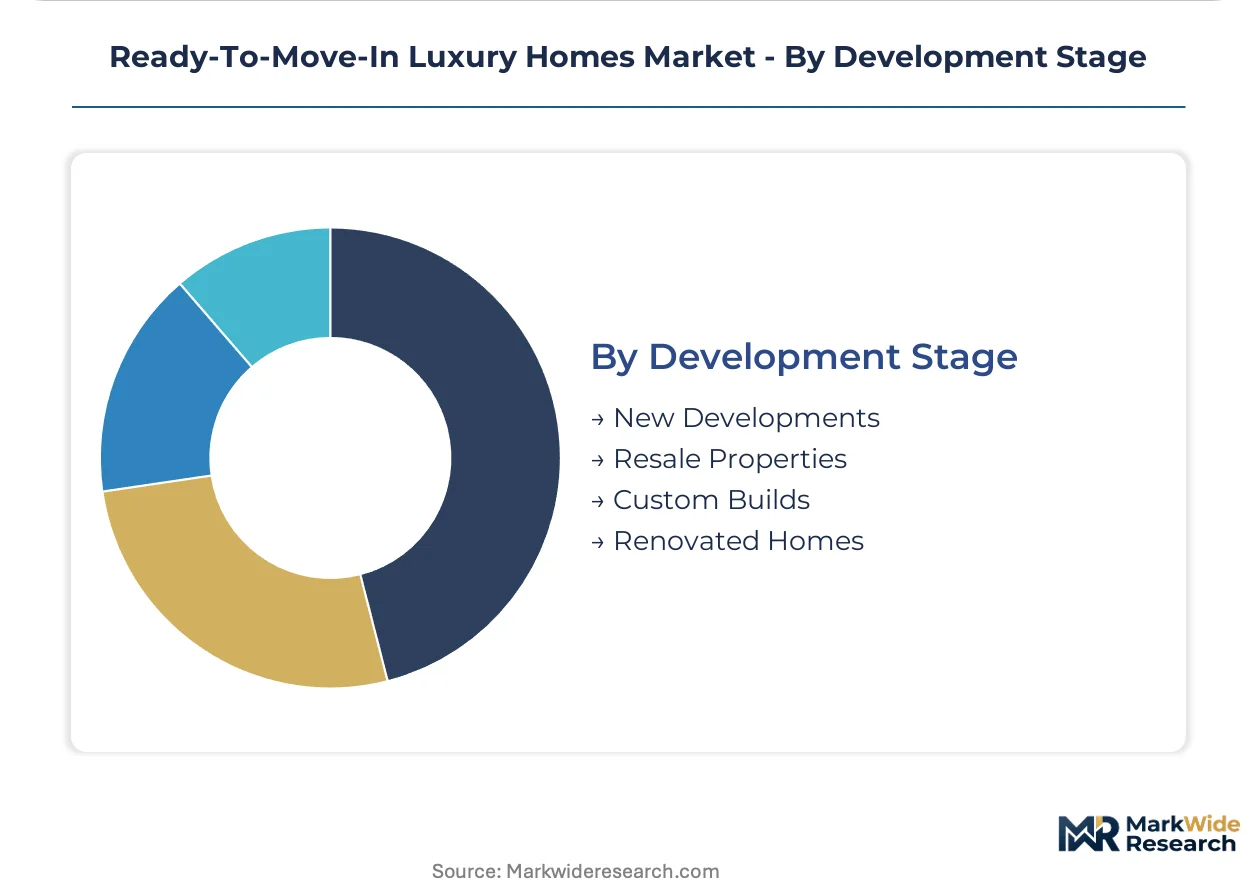
New developments anchor supply volume today; renovated homes are gaining share fastest as carbon retrofit mandates expand addressable inventory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Project management talent concentrates in Dubai, Miami, and Singapore, where compressed handover timelines demand specialized coordination across interior fit-out, MEP commissioning, and smart system integration.
United Arab Emirates
Dubai's waterfront corridors attract foreign nationals seeking visa-linked security and immediate occupancy. RERA escrow mandates eliminate completion risk for cross-border capital. The Palm Jumeirah and Downtown Dubai clusters absorb the deepest foreign investment pools.
United States
Miami's Brickell corridor channels Latin American capital into certified ready inventory with guaranteed handover dates. SEC disclosure requirements for real estate investment vehicles elevate compliance costs while filtering speculative development. Coastal seismic engineering constraints restrict floor-to-ceiling glazing spans.
Singapore
Restricted land release policy concentrates demand in penthouse inventory with foreign ownership quotas. Visa-linked property investment pathways accelerate transaction velocity for certified completions. The Marina Bay and Orchard Road corridors dominate trophy asset classification.
India
Secondary cities Hyderabad and Pune offer first-mover positioning as HNWI density spreads beyond Mumbai and Delhi NCR. BIS structural safety standards and RERA compliance frameworks tighten delivery accountability. DLF Ltd's captive land banking across Delhi NCR anchors supply concentration.
Germany
Frankfurt and Amsterdam face steep compliance ramps under EU Green Deal carbon performance benchmarks. EMA building energy codes mandate lifecycle emissions disclosure for residential assets above specified thresholds. Developers retrofit specifications to avoid stranding risk.
Ready-To-Move-In Luxury Homes Market Vendor Landscape
Capital-heavy developers compete with asset-light design studios across the ready-to-move-in luxury segment. The vendor base consolidates around integrated lifestyle infrastructure providers and captive land bankers. Three archetypes dominate: waterfront specialists with RERA-compliant escrow frameworks, secondary-city first-movers leveraging RERA maturation, and BIM-coordinated multi-tower operators compressing design-to-handover cycles. M&A activity concentrates on land banking accumulation and smart home technology integration.
Within the waterfront-specialist tier, Emaar Properties and DAMAC Properties exemplify developer-curated delivery models that internalize specification control. Among India-based developers with captive land positions, DLF Ltd and Lodha Group occupy positions shaped by RERA compliance timelines and HNWI density migration. Toll Brothers represents the design-studio archetype that compresses customization cycles without delaying occupancy.
| Leading Market Players |
|---|
| DLF Ltd |
| Emaar Properties |
| DAMAC Properties |
| Godrej Properties |
| Lodha Group |
| Sobha |
| Toll Brothers |
| Sun Hung Kai Properties |
| Aldar Properties |
| Others |
Supply Flow & Price Mechanics
Project management talent clustering in Dubai and Singapore compresses labor-cost differentials into narrower pricing-tier spreads than secondary markets like Hyderabad or Pune, where RERA-mature compliance costs widen the gap between mid-range and ultra-premium inventory.
Pricing Analysis
Bundled interior fit-out and smart home integration versus unbundled base-shell delivery defines the dominant pricing split across ready-to-move-in luxury inventory. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and waterfront positioning, with LEED Platinum and BREEAM Outstanding commanding discrete premiums. Pricing pressure stems from input cost volatility in Italian-engineered stone and German climate-control systems that erode margin buffers on fixed-price contracts. Foreign nationals demonstrate the lowest price sensitivity due to visa-linked security priorities, while aspirational buyers in secondary Indian cities exhibit the highest elasticity.
Supply Chain Analysis
Direct-to-developer procurement channels handle hyperscale fit-out demand across multi-tower projects, bypassing traditional distributor markups. Manufacturing concentration in Italy and Germany supplies premium flooring and kitchen systems, while China and India source structural steel and concrete. Raw material dependencies on imported fixture packages, engineered glazing, and MEP components expose developers to currency fluctuation risks. Single-source vulnerability from German specialty manufacturers creates supply chain fragility for projects targeting certification benchmarks. Distribution runs through captive logistics networks controlled by Emaar Properties and comparable integrated developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Dubai's RERA escrow certainty attracts capital at compressed yields versus India's maturing compliance frameworks that widen risk-adjusted return differentials.
For Market Incumbents: Anticipate margin compression from input cost volatility by securing long-term offtake agreements with Italian and German specialty manufacturers before currency swings accelerate. Backward integration into captive land banking across Delhi NCR and Hyderabad defends positioning against emerging BIM-coordinated competitors. Certification investment in EU Green Deal pre-certification above national minimums creates defensive moats as carbon performance benchmarks tighten. For New Entrants and Emerging Players: A mid-range pricing gap between premium LEED-certified inventory and affordable luxury entry-points offers white-space positioning in Pune and Hyderabad as RERA compliance matures and HNWI density spreads. Fractional ownership platforms targeting sub-HNWI penthouse exposure represent the most penetrable segment. Go-to-market execution should leverage technology-enabled co-ownership models that expand addressable demand without whole-asset price thresholds. For Investors and Strategic Acquirers: Integrated lifestyle infrastructure providers are the most active acquirer in this space, consolidating land banking and smart home technology capabilities. Long-term viability centers on developers who internalize specification control through BIM coordination and carbon documentation systems. Acquisition targets should display captive land positions in waterfront corridors or secondary-city first-mover footprints. The signal to monitor is regulatory acceleration of embodied carbon disclosure requirements that could strand non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Land Banking Accumulation | DLF Ltd's Delhi NCR positioning demonstrates density optimization within restricted supply corridors. |
| BIM Coordination Deployment | Emaar Properties compresses design-to-handover cycles while consolidating specification authority internally. |
| Smart Home Technology Integration | Pre-installed IoT infrastructure aligns with executive buyer time-value priorities across Dubai and Miami. |
| EU Green Deal Pre-Certification | Frankfurt developers retrofit specifications to avoid stranding risk under EMA building energy codes. |
| Fractional Ownership Platform Launch | Technology-enabled co-ownership expands penthouse demand among sub-HNWI segments seeking trophy exposure. |
Methodological Framework
Direct dialogue with project development executives, interior fit-out contractors, RERA compliance officers, and cross-border buyer agents anchored qualitative grounding across primary fieldwork. Secondary validation drew from Dubai RERA escrow filings, BIS structural certification databases, EU Green Deal building performance disclosures, and SEC real estate investment vehicle registrations. Bottom-up inventory tracking across metropolitan corridors triangulated with top-down capital flow analysis from foreign national investment patterns.
Bottom-up project pipeline assessment across villa, penthouse, bungalow, and townhouse configurations integrated with top-down HNWI density migration modeling. Segmentation dimensions spanned property type, customer archetype, price tier, and completion status across the analysis window. CAGRs were derived from velocity-premium capture rates in waterfront corridors versus secondary-city penetration curves. Forecast inputs incorporated RERA compliance maturation timelines and carbon performance benchmark escalation pathways.
Caveats apply where regulatory acceleration of embodied carbon disclosure or seismic engineering constraint revisions could materially shift the outlook. Forecasts reflect assumptions about cross-border capital flow stability and specialty manufacturer supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market