
 North America Luxury Residential Real Estate Market | 2026-2036
North America Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Luxury Residential Real Estate Market Analytics
Concierge property management subscriptions is recalibrating how developers package ongoing services alongside unit sales. Toll Brothers City Living leverages vertical integration across design, build, and service phases to capture recurring revenue streams. Related Companies anchors its competitive stance through dominance in mixed-use trophy assets across Manhattan and Hudson Yards. Sotheby's International Realty differentiates through curated global buyer networks and white-glove transaction orchestration.
North America luxury residential real estate encompasses high-value dwellings typically exceeding one million dollars in transaction price, constructed with premium materials such as imported stone, smart climate systems, and custom millwork, serving as primary residences, investment vehicles, or portfolio diversification instruments for wealthy households. Single-family homes command the largest share of transaction volume across the price spectrum, while condominiums represent the fastest-growing structural category in dense urban cores where land scarcity elevates vertical development economics. The above $10M price band concentrates disproportionate margin pools despite representing the smallest unit count, as broker commissions and ancillary service fees scale with absolute transaction value.
The US Department of Housing and Urban Development coordinates fair housing enforcement that shapes marketing practices and buyer qualification protocols, while the US Securities and Exchange Commission governs real estate investment vehicle disclosures affecting institutional participation in luxury development projects. State-level transfer tax regimes in New York, Florida, and California directly alter net acquisition costs and timing decisions for cross-border purchasers. Stakeholders must monitor evolving beneficial ownership disclosure requirements and climate risk disclosure mandates that will reshape due diligence intensity and capital allocation frameworks.
Market Dynamics
The US Inflation Reduction Act's green building incentives are compressing developer timelines and redirecting capital toward electrification-ready assets, while Miami's emergence as a migration magnet concentrates transaction velocity in a single metro corridor.
Growth Catalysts
- IRA Tax Credits:Federal incentives for energy-efficient construction are accelerating retrofit investments and new-build certifications across the Sun Belt.
- Tech Sector Liquidity:Ultra-high-net-worth technology executives are deploying accumulated equity into trophy single-family homes as portfolio diversification instruments.
- Climate Migration:Domestic population flows toward Florida and Texas are elevating demand for hurricane-resilient luxury inventory in coastal submarkets.
Market Restraints
- Labor Concentration:Skilled artisan availability for custom millwork and imported stone installation concentrates in legacy Northeast and California construction corridors.
- Transfer Tax Friction:New York State's mansion tax regime and Florida's documentary stamp obligations compress net yields for cross-border purchasers.
- Interest Rate Sensitivity:Floating-rate construction debt exposure leaves speculative development exposed to Federal Reserve policy oscillations.
Strategic Opportunities
- Concierge Service Integration:Subscription property management models create recurring revenue streams alongside unit sales in primary and secondary home markets.
- Beneficial Ownership Disclosure Gaps:Early compliance infrastructure for pending federal transparency mandates offers first-mover positioning with institutional capital sources.
- Smart Climate Convergence:Integration of geothermal systems with AI-driven energy optimization is opening differentiation in the above-$10M price band.
Industry Challenges
- Climate Risk Valuation:Insurance carriers are withdrawing from flood-prone coastal zones, forcing developers to absorb unpriced catastrophe exposure.
- Artisan Pipeline Depletion:Master craftspeople capable of executing heritage-grade millwork are aging out without structured apprenticeship succession.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Luxury Residential Real Estate Market |
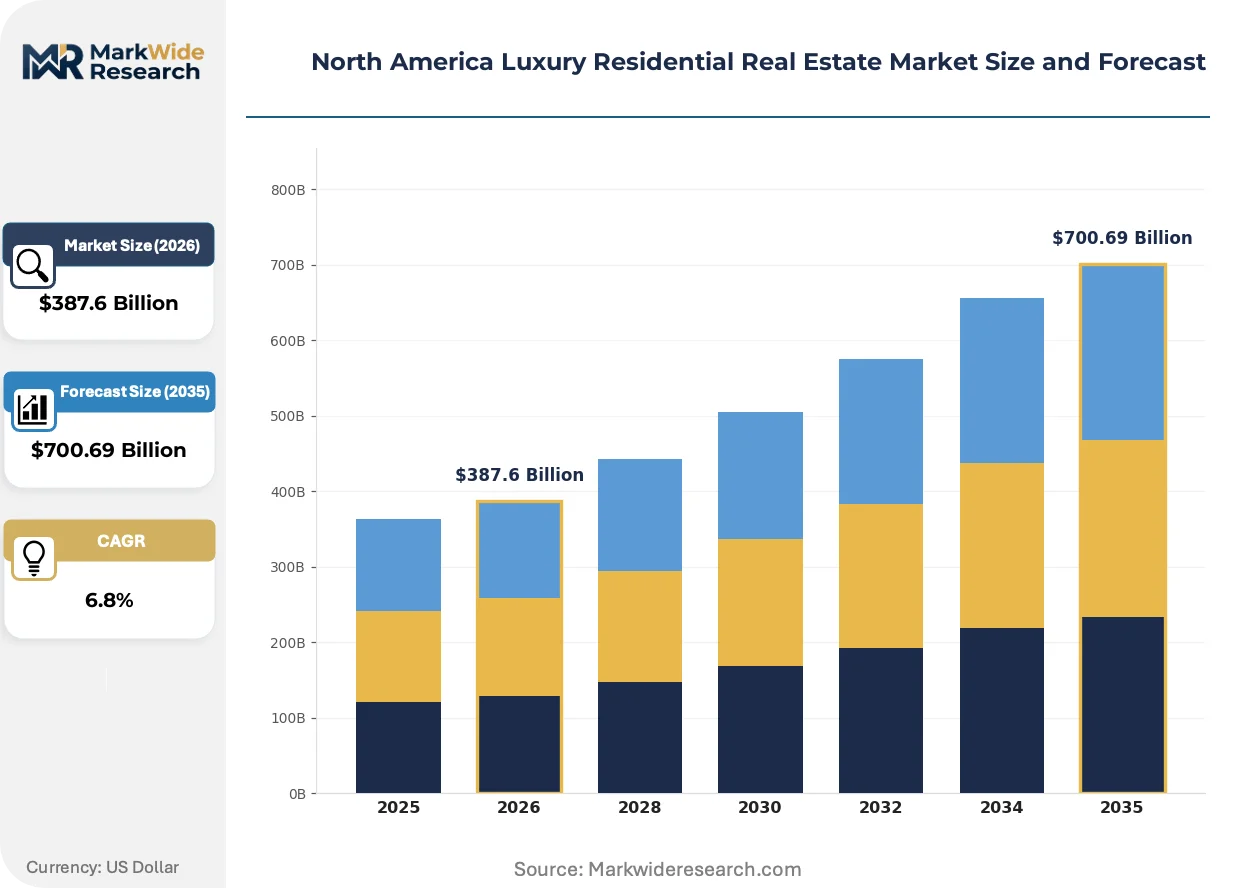
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Townhouses, Villas Buyer Type: Affluent Individuals, Investors, Second-Home Buyers, Foreign Nationals Price Range: Above $1M, $2M-$5M, $5M-$10M, Above $10M Sales Channel: Traditional Brokerage, Online Platforms, Auction Services, Others |
| Companies Covered | Toll Brothers City Living, Lennar Corp, Howard Hughes Corp, Related Companies, Extell Development, Compass, Sotheby's International Realty, Coldwell Banker Global Luxury, Anywhere Advisors, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Luxury Residential Real Estate Market Evolving Landscape
Three intersecting forces are compressing traditional development cycles and elevating service-layer monetization: embedded intelligence in building systems, federal climate policy integration, and the unbundling of transaction orchestration from physical asset delivery.
Geothermal and AI-optimized climate systems are rewriting energy performance benchmarks in trophy assets. Ultra-high-net-worth buyers from technology backgrounds are specifying these installations at specification stage rather than retrofit. The technology is compressing operating cost differentials between new construction and legacy inventory, forcing accelerated obsolescence in pre-2020 stock.
The US Inflation Reduction Act's residential clean energy credit structure is mandating electrification readiness as a baseline entitlement. Developers in Florida and Texas are pre-wiring for solar and battery storage to qualify for federal offset stacking. The above-$5M single-family segment is responding fastest, treating certification as a transaction velocity tool rather than cost center.
White-glove transaction orchestration is unbundling from traditional brokerage commissions. Buyers are engaging curated global networks for property identification, then separating due diligence and closing services into discrete fee structures. This pattern is most visible in Miami, where international capital placement demands multilingual documentation and cross-border tax coordination that legacy broker models underprice.
North America Luxury Residential Real Estate Market Segmentation
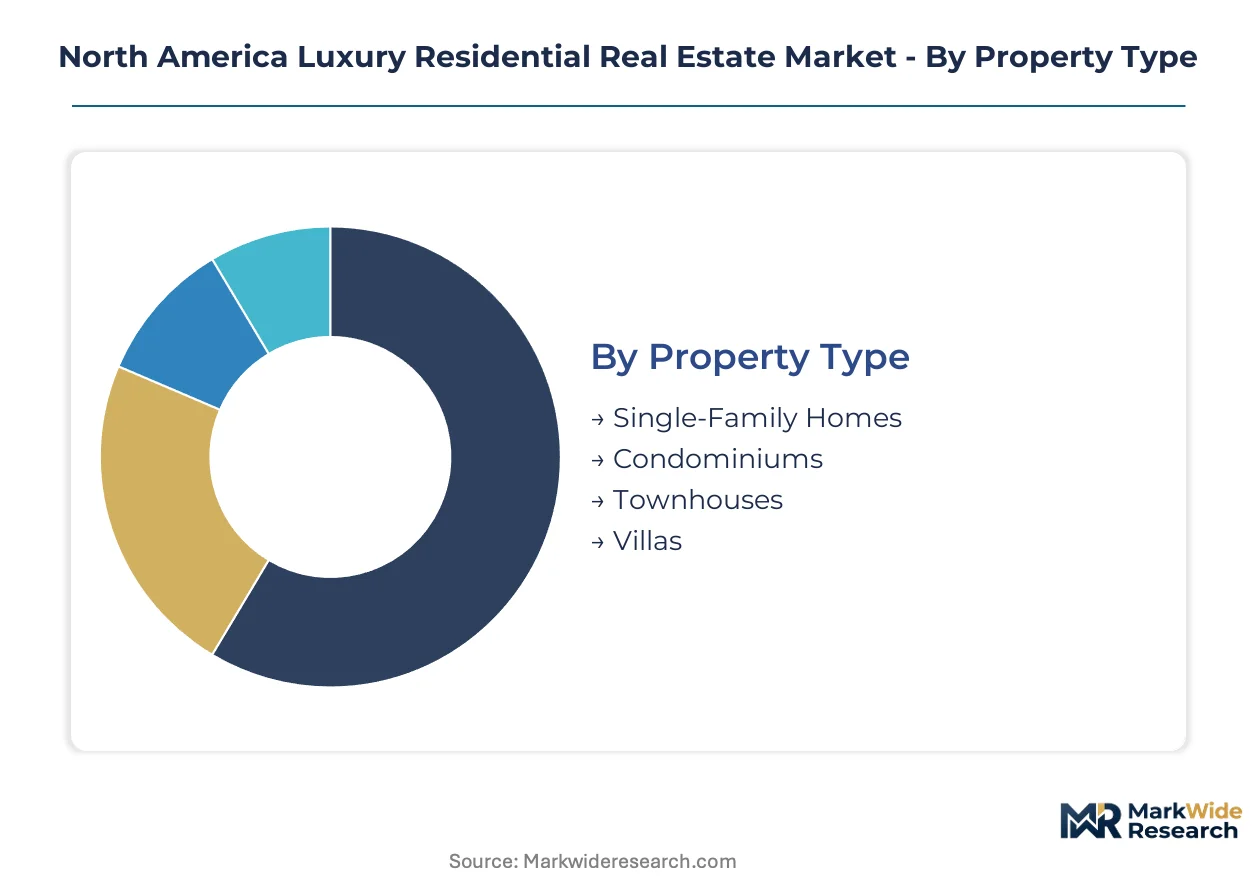
Luxury residential real estate segmentation reveals divergent capital deployment patterns across structural categories, buyer profiles, and transaction mechanisms. Each axis carries distinct margin profiles, regulatory exposure, and service-layer monetization potential that reshape developer and broker strategies.
Property Type:
Structural specifications dictate land use intensity, construction cost curves, and buyer qualification protocols across the four primary dwelling formats.
- Single-Family Homes:Detached structures on dedicated parcels command the largest transaction volume share across all price bands. Demand concentrates in Miami, Florida and Austin, Texas submarkets where technology sector liquidity flows into trophy assets with private outdoor amenities and home office infrastructure.
- Condominiums:Vertical ownership units in dense urban cores represent the fastest-climbing structural category where land scarcity elevates development economics. Miami's Brickell and Manhattan's Hudson Yards corridors absorb disproportionate international capital placement seeking low-maintenance pied-à-terre exposure.
- Townhouses:Multi-floor attached dwellings bridge density and privacy preferences in supply-constrained urban districts. Brooklyn Heights and Georgetown submarkets favor these formats for family-sized footprints without single-family land premiums.
- Villas:Estate-scale compounds with dedicated grounds and guest accommodations target ultra-high-net-worth households seeking compound-style privacy. Palm Beach and Malibu coastal zones concentrate this inventory where hurricane resilience specifications add construction complexity.
Single-family homes lead on scale; condominiums lead on momentum.
Buyer Type:
Purchaser motivation and capital source alter transaction velocity, negotiation leverage, and post-sale service requirements.
- Affluent Individuals:Primary residence seekers with liquid net worth exceeding $5 million drive above-$2M transaction flow. These buyers prioritize school district quality, commute optimization, and legacy asset preservation in purchase decisions.
- Investors:Portfolio allocators treat luxury residential as inflation hedge and currency diversification vehicle. Miami and Scottsdale submarkets attract this cohort where rental yield potential and appreciation trajectories align with institutional return thresholds.
- Second-Home Buyers:Seasonal or weekend residence purchasers concentrate in ski and coastal corridors. Aspen, Colorado and the Hamptons, New York sustain elevated transaction velocity from this segment despite interest rate sensitivity.
- Foreign Nationals:Cross-border purchasers navigate beneficial ownership disclosure requirements and transfer tax regimes. Florida's absence of state income tax and homestead protections attracts Latin American and Canadian capital.
Affluent individuals anchor transaction volume; foreign nationals show steepest expansion trajectory where currency depreciation drives capital flight into dollar-denominated assets.
Price Range:
Absolute transaction value determines commission structures, due diligence intensity, and competitive set composition.
- Above $1M:Entry-luxury threshold where premium materials and location premiums separate from mass-market inventory. Sun Belt metro corridors concentrate this band's velocity.
- $2M-$5M:Established luxury segment where custom millwork and smart home systems become baseline expectations. Austin and Nashville submarkets expand fastest in this tier.
- $5M-$10M:Ultra-luxury entry point where architectural pedigree and view premiums dominate valuation. Manhattan and Los Angeles coastal zones concentrate this inventory.
- Above $10M:Trophy asset tier generating disproportionate margin pools despite smallest unit count. Broker commissions and ancillary service fees scale with absolute transaction value in this band.
Above-$1M transactions dominate unit volume; above-$10M assets command margin concentration.
Sales Channel:
Transaction orchestration mechanisms are unbundling from traditional commission structures as buyer sophistication increases.
- Traditional Brokerage:Full-service representation with localized market expertise and negotiation leverage. Legacy models retain dominance in above-$5M transactions where relationship depth matters.
- Online Platforms:Digital listing aggregation and virtual tour technology compress search friction. These channels gain share fastest in below-$3M segments where buyer self-direction is highest.
- Auction Services:Accelerated price discovery for distressed or unique trophy assets. Miami and New York markets utilize this channel for estate sales and developer closeouts.
- Others:Direct developer sales, private networks, and referral-based transactions outside formal brokerage structures. Ultra-high-net-worth circles favor these channels for privacy preservation.
Traditional brokerage retains volume leadership; online platforms gain share fastest where millennial and technology-sector buyers self-direct search behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between state-level transfer tax regimes and homestead protections is redistributing development capital across sub-markets. Developers and purchasers migrate toward jurisdictions where disclosure burdens and tax friction compress net acquisition costs.
United States
Ultra-high-net-worth technology executives deploy accumulated equity into trophy single-family homes across Miami and Austin submarkets. The US Inflation Reduction Act's residential clean energy credits mandate electrification readiness as baseline entitlement for federal offset qualification. Florida's Miami-Dade County concentrates transaction velocity where hurricane-resilient specifications attract domestic migration and Latin American capital flight.
Canada
Foreign national purchasers from Asia-Pacific source dollar-denominated stability through Vancouver and Toronto luxury inventory. The country's national housing regulator coordinates beneficial ownership disclosure requirements that reshape due diligence protocols for cross-border transactions. British Columbia's Vancouver metro anchors western concentration where provincial foreign buyer taxes have redirected capital toward Montreal and Calgary corridors.
Mexico
Second-home buyers from the United States seek coastal compound privacy in Los Cabos and Riviera Maya submarkets. The country's federal banking regulator governs real estate investment vehicle disclosures affecting institutional participation in resort development. Quintana Roo's Tulum corridor absorbs development attention where environmental compliance timelines compress project delivery schedules.
California
Affluent individuals prioritize legacy asset preservation in Pacific Palisades and Atherton submarkets where school district quality anchors purchase decisions. The California Energy Commission enforces Title 24 building standards that elevate smart climate system specifications above five-million-dollar thresholds. Los Angeles County's coastal zones concentrate above-ten-million-dollar trophy assets generating disproportionate broker commission pools.
New York
Investors treat Manhattan condominiums as inflation hedge and currency diversification vehicle amid volatile equity markets. The New York State Department of Taxation and Finance administers mansion tax regimes that compress net yields for cross-border purchasers. Hudson Yards and Tribeca submarkets absorb international capital placement seeking low-maintenance pied-à-terre exposure with architectural pedigree premiums.
North America Luxury Residential Real Estate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated developers capturing recurring revenue through service-layer monetization while transaction orchestrators compete on global buyer network depth. Market structure tilts toward consolidation among trophy asset developers with captive land positions in supply-constrained urban cores. Three archetypes dominate: vertically integrated design-build-service operators, curated global brokerage networks, and mixed-use trophy asset specialists. Dominant competitive moves include concierge service integration alongside unit sales and pre-wiring for federal green building certification to accelerate transaction velocity.
Within the integrated developer tier, Toll Brothers City Living and Related Companies exemplify archetypes capturing recurring revenue streams through vertical control across design, build, and service phases. Sotheby's International Realty anchors the white-glove transaction orchestration segment, representing the unbundling of curated global buyer networks from traditional commission structures. These three entities occupy positions where brand equity and relationship depth defend margin concentration in above-five-million-dollar transaction bands.
| Leading Market Players |
|---|
| Toll Brothers City Living |
| Lennar Corp |
| Howard Hughes Corp |
| Related Companies |
| Extell Development |
| Compass |
| Sotheby's International Realty |
| Coldwell Banker Global Luxury |
| Anywhere Advisors |
| Others |
Value Network & Pricing Analysis
Trophy asset premiums above ten million dollars diverge sharply from entry-luxury inventory below two million, with the former commanding scaled commissions and white-glove service bundling while the latter competes on velocity and financing accessibility. This bifurcation manifests in supply chain configurations where custom millwork and imported stone concentrate in Northeast artisan corridors for trophy assets, while production homebuilders deploy standardized materials across Sun Belt markets to compress delivery timelines and maintain margin.
Pricing Analysis
Broker commission markups dominate transaction economics, scaling from flat percentage structures in entry-luxury tiers to negotiated fee arrangements with ancillary service bundling in trophy assets. Price differentiation rests on architectural pedigree and climate resilience certification, with hurricane-rated specifications in Florida commanding material premiums over comparable California inventory. Pricing pressure stems from interest rate sensitivity in floating-rate construction debt, compressing speculative developer yields. Investors show highest price sensitivity due to yield threshold requirements, while ultra-high-net-worth primary residence seekers demonstrate lowest elasticity.
Supply Chain Analysis
LEED and Energy Star certification gating restricts supplier pools for electrification-ready components, concentrating qualified vendors in California, Texas, and Florida construction corridors. Raw material dependencies span Italian marble, Brazilian hardwood, and lithium-ion battery systems for smart climate installations. Supply chain risk centers on single-source vulnerability for master craftspeople capable of heritage-grade millwork, with aging artisan populations lacking structured apprenticeship succession. Distribution runs through vertically integrated developers controlling design, build, and service phases alongside traditional brokerage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in service-layer monetization and green certification premiums, as federal IRA incentives compress capital costs for electrification-ready construction while concierge subscriptions generate recurring revenue alongside unit sales.
For Market Incumbents: Anchor competitive position through captive land positions in supply-constrained urban cores and pre-wiring for federal green building certification to accelerate transaction velocity. Defend against unbundled transaction orchestrators by deepening relationship infrastructure with ultra-high-net-worth networks. Vertical integration across design, build, and concierge service phases captures recurring revenue streams that pure-play developers cannot replicate. For New Entrants and Emerging Players: Boutique property management firms represent the most penetrable channel partner type for service-layer integration, offering white-label concierge infrastructure to developers lacking in-house capabilities. Target secondary home markets in Aspen and the Hamptons where seasonal demand creates subscription service gaps. Pursue direct-to-developer sales of climate resilience consulting and certification navigation to bypass entrenched brokerage relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented local developers lack capital reserves to pre-wire for IRA compliance and absorb floating-rate debt exposure. Long-term viability favors integrated operators with trophy asset pipelines and recurring service revenue anchoring cash flow stability. Acquisition target archetype: vertically integrated Sun Belt developers with captive land positions and established concierge infrastructure. Watch federal beneficial ownership disclosure mandates as inflection indicator for due diligence intensity and institutional capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Concierge Service Integration | Subscription property management creates recurring revenue streams alongside unit sales for Toll Brothers and Related Companies. |
| Green Certification Pre-Wiring | IRA tax credit qualification accelerates transaction velocity in Miami and Austin single-family developments. |
| Captive Land Positioning | Supply-constrained urban core sites in Manhattan and Hudson Yards defend margin concentration for trophy assets. |
| Global Buyer Network Curation | Sotheby's International Realty leverages multilingual documentation for Latin American capital placement in Florida. |
| Climate Resilience Specification | Hurricane-rated construction premiums attract domestic migration and insurance carrier retention in coastal submarkets. |
Research Methodology
Direct dialogue with luxury residential developers, brokerage principals, mortgage specialists, and concierge service operators grounded qualitative findings in operational reality across primary markets. Secondary validation drew from HUD fair housing enforcement records, SEC real estate investment vehicle disclosures, state-level transfer tax regime documentation, and climate risk disclosure mandate filings. Bottom-up transaction volume modeling triangulated against top-down macroeconomic indicators to ensure consistency.
Bottom-up segmentation analysis tracked property type, buyer motivation, price band, and sales channel dynamics across the projection horizon. The analytical framework modeled structural category growth rates, regional migration patterns, and federal incentive program uptake without specifying discrete year boundaries. CAGRs derived from regression analysis of historical transaction velocity against demographic and capital flow drivers, incorporating IRA credit phase-out schedules and interest rate scenario sensitivity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Federal Reserve policy oscillations, climate catastrophe frequency, and beneficial ownership disclosure implementation timelines. Deviation in tech sector liquidity events or Florida hurricane insurance market contraction would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market