
 UAE Luxury Residential Real Estate Market | 2026-2036
UAE Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Luxury Residential Real Estate Market Analytics
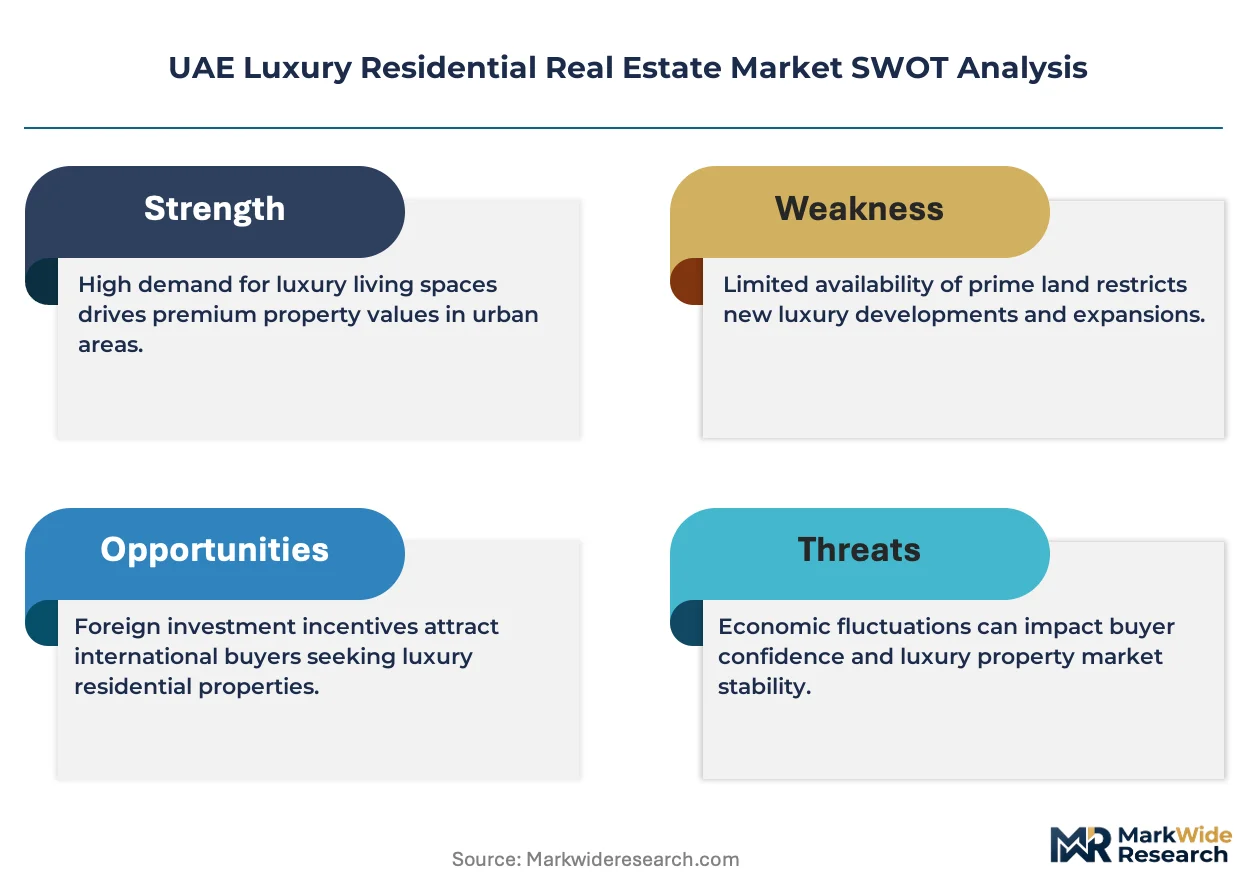
Buyer concentration among ultra-high-net-worth individuals and family offices is realigning project pipelines toward ultra-luxury inventory. Emaar Properties leverages its master-planned community expertise to anchor premium supply in Dubai Hills and Downtown corridors. DAMAC Properties competes through branded residence partnerships that sustain price premiums above comparable unbranded stock. Nakheel dominates waterfront development with its Palm portfolio, controlling some of the emirate's most constrained land banks.
UAE luxury residential real estate comprises high-value dwellings exceeding 3,000 square feet, typically featuring bespoke interiors, smart home infrastructure, and concierge services, designed primarily for wealth preservation and lifestyle elevation. Villas and penthouses lead transaction volumes, though above-AED 10 million mansions capture disproportionate margin pools due to scarcity of waterfront plots and custom architectural mandates. The investor segment drives liquidity, while end-user demand among relocating family offices is accelerating fastest in the 5,000 to 7,000 square foot bracket.
MOHAP oversees health and safety standards for residential construction quality, while the UAE Central Bank enforces loan-to-value caps that directly constrain foreign buyer leverage and shape payment-plan structures. Dubai's Real Estate Regulatory Agency mandates escrow account compliance, protecting off-plan purchasers and reinforcing developer accountability. Stakeholders must monitor how evolving golden visa criteria and corporate tax residency rules reshape buyer nationality mix and holding-period expectations.
Market Dynamics
Ultra-high-net-worth buyer concentration from India and Russia is compressing development timelines toward ultra-luxury inventory, forcing developers to front-load amenity spend and secure waterfront land positions before regulatory caps tighten further.
Growth Catalysts
- Golden Visa Program:The UAE's residency-by-investment framework attracts family offices seeking tax-efficient domiciles, directly stimulating demand for above-AED 10 million trophy assets.
- Branded Residence Partnerships:Hospitality operators lend cachet to residential towers, enabling developers to command sustained price premiums over comparable unbranded stock in Palm Jumeirah and Downtown Dubai corridors.
- Escrow Account Mandates:Dubai's Real Estate Regulatory Agency protects off-plan purchasers through developer fund segregation, reinforcing foreign buyer confidence and transaction velocity.
Market Restraints
- Loan-to-Value Caps:The UAE Central Bank's mortgage limits constrain leverage for non-resident purchasers, compressing accessible buyer pools and elongating payment-plan structures.
- Waterfront Land Scarcity:Nakheel's control of Palm portfolio plots creates supply concentration, limiting developable frontage and inflating land acquisition costs for competing developers.
- Construction Input Volatility:Specialized smart home infrastructure and bespoke interior materials face procurement bottlenecks, squeezing project margins on custom architectural mandates.
Strategic Opportunities
- Family Office Relocation Wave:End-user demand among relocating family offices accelerates fastest in the 5,000 to 7,000 square foot bracket, creating white space for mid-mansion inventory in Dubai Hills.
- Corporate Tax Residency Alignment:Evolving holding-period expectations and substance requirements reshape buyer nationality mix, favoring long-horizon wealth preservation plays over speculative flipping.
- Concierge Service Unbundling:Technology-enabled lifestyle management platforms displace traditional in-house staffing, opening margin recovery paths for developers willing to partner with specialized operators.
Industry Challenges
- Skilled Project Management Gap:Custom architectural mandates for above-AED 10 million mansions require scarce coordination expertise between international design houses and local contractors.
- Compliance Timeline Compression:MOHAP health and safety standards for residential construction quality impose inspection bottlenecks that delay handovers on complex smart home integrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Luxury Residential Real Estate Market |
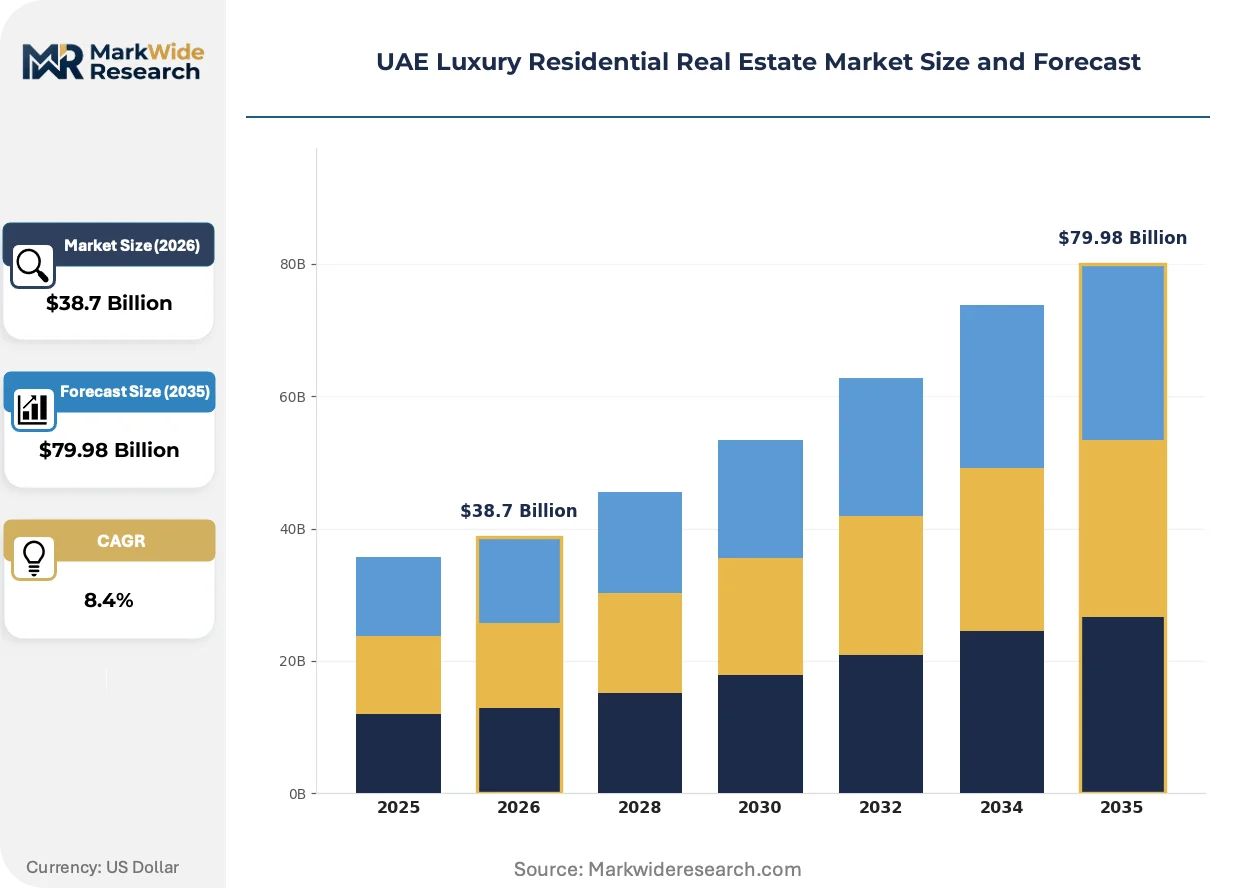
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Villas, Penthouses, Mansions, Townhouses Size: 3000 sq ft, 5000 sq ft, 7000 sq ft, Above 10000 sq ft Price Tier: Below AED 3M, AED 3M - AED 5M, AED 5M - AED 10M, Above AED 10M Buyer Type: Investors, End Users, Expats, High-Net-Worth Individuals |
| Companies Covered | OMNIYAT, Nakheel, Emaar Properties, Ellington Properties, Meraas, DAMAC Properties, H&H Development, Mira Developments, Sobha Realty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Luxury Residential Real Estate Market Evolving Landscape
Technology convergence and regulatory recalibration are compressing traditional development cycles while elevating buyer expectations for seamless digital-physical living environments across Dubai's premium corridors.
Integrated building management systems is electrifying energy and security orchestration in trophy assets. Ultra-high-net-worth purchasers from Moscow and Mumbai are specifying these platforms as baseline requirements. This compression of technical standards is forcing mid-tier developers to partner or exit the premium segment entirely.
The UAE Central Bank's evolving macroprudential framework tightens foreign buyer leverage through dynamic loan-to-value adjustments. Developers respond by lengthening post-handover payment plans and front-loading equity requirements. Non-resident purchasers in the AED 5-15 million bracket face the steepest financing friction.
Direct-to-developer digital channels are displacing traditional brokerage intermediaries for repeat family office buyers. Branded residence operators build proprietary CRM ecosystems to capture this relationship value. This channel shift concentrates most visibly among Russian and Indian purchasers with established Dubai footprints.
UAE Luxury Residential Real Estate Market Segmentation
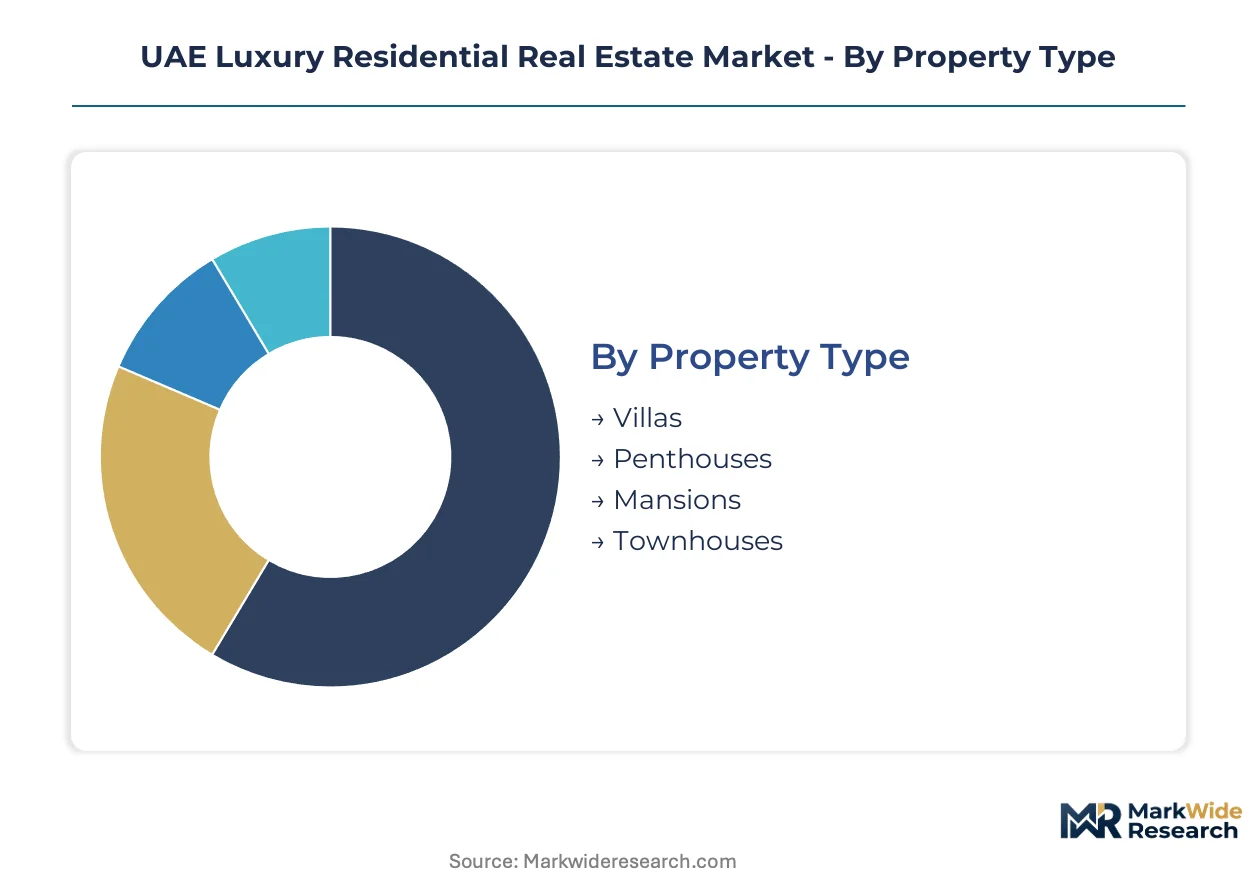
Segmentation in UAE luxury residential real estate exposes how buyer profiles, scale thresholds, and asset specifications determine pricing power and development focus across Dubai's premium corridors. Each axis reveals distinct margin structures and financing constraints that reshape project pipelines.
Property Type:
Architectural form dictates land efficiency, customization depth, and the feasibility of branded residence partnerships that sustain price premiums.
- Villas:Detached structures on individually titled plots enable bespoke exterior architecture and private amenity integration. Demand concentrates in Dubai Hills and Emirates Hills where Indian family offices seek 5,000 to 7,000 square foot footprints for multi-generational occupancy. MOHAP construction quality standards and smart home infrastructure mandates compress delivery timelines for custom specifications.
- Penthouses:Top-floor units in high-rise towers capture panoramic views and command the highest per-square-foot pricing in Downtown Dubai. Russian ultra-high-net-worth buyers dominate transactions above AED 15 million, prioritizing integrated building management systems and concierge services as baseline requirements. Branded residence operators extract partnership fees that sustain developer margins despite elevated construction costs.
- Mansions:Ultra-large estates exceeding 10,000 square feet occupy scarce waterfront plots controlled by Nakheel's Palm portfolio. Custom architectural mandates require coordination between international design houses and local contractors.
- Townhouses:Attached multi-story units offer fractional land ownership with reduced maintenance burdens. Entry-level luxury positioning attracts expat professionals seeking golden visa eligibility through sub-AED 5 million entry points.
Mature deployment sits with Villas. Newer deployment is concentrated in Penthouses.
Size:
Square footage thresholds align with buyer migration patterns, financing constraints, and the granularity of Dubai's land parcel allocation system.
- 3000 sq ft:Compact luxury entry point targeting single professionals and small families. Indian investors favor this bracket in Jumeirah Village Circle for rental yield optimization.
- 5000 sq ft:Mid-mansion category experiencing fastest demand acceleration from relocating family offices. Dubai Hills developers front-load amenity spend to capture this relocating segment seeking space for home offices and staff quarters.
- 7000 sq ft:Standard trophy asset size for multi-generational Russian and Indian buyers establishing Dubai tax residency. UAE Central Bank loan-to-value caps bite hardest here for non-resident purchasers, elongating payment-plan structures.
- Above 10000 sq ft:Ultra-luxury estates on Palm Jumeirah and Emirates Hills facing acute land scarcity. Custom mandates and waterfront positioning create the market's deepest margin pools despite extended construction timelines.
Volume concentration rests with 5000 sq ft. Margin expansion is steepest in Above 10000 sq ft.
Price Tier:
Cost thresholds segment buyer pools by leverage access, golden visa eligibility, and wealth preservation objectives.
- Below AED 3M:Accessible luxury segment where expat professionals cluster in off-plan townhouses. Escrow account mandates from Dubai's Real Estate Regulatory Agency protect this risk-sensitive buyer pool.
- AED 3M - AED 5M:Golden visa threshold segment attracting end-user demand from European and South Asian buyers seeking ten-year residency certainty. Townhouses and compact villas dominate transaction flow.
- AED 5M - AED 10M:Mid-luxury bracket where non-resident purchasers face steepest UAE Central Bank financing friction. Developers respond with extended post-handover payment plans.
- Above AED 10M:Trophy asset category where branded residence premiums and waterfront scarcity sustain price elevation. Russian and Indian ultra-high-net-worth individuals drive liquidity with minimal leverage dependency.
Transaction velocity peaks in AED 3M - AED 5M. Price appreciation is most pronounced in Above AED 10M.
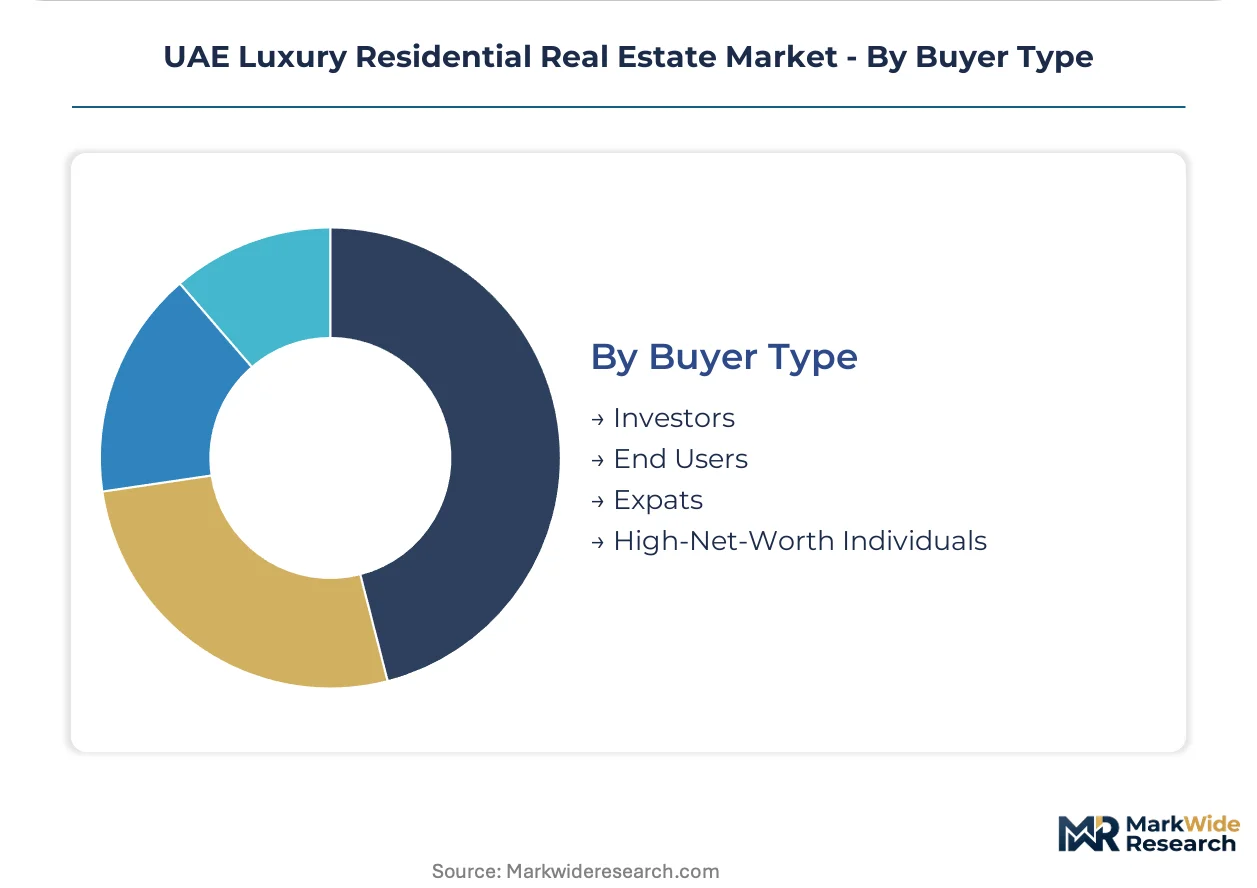
Buyer Type:
Purchaser classification determines holding-period expectations, customization demands, and sensitivity to macroprudential leverage constraints.
- Investors:Yield-focused purchasers targeting rental income and capital appreciation in established corridors. Indian nationals dominate this segment, prioritizing Dubai Hills and Downtown Dubai for liquidity depth.
- End Users:Occupier-buyers seeking primary or secondary residences with bespoke interior specifications. Relocating family offices represent the fastest-expanding sub-segment in the 5,000 to 7,000 square foot bracket.
- Expats:Professionally mobile buyers leveraging golden visa pathways for long-term residency stability. Sub-AED 5 million townhouses and compact villas align with their financing constraints.
- High-Net-Worth Individuals:Ultra-wealthy purchasers treating Dubai real estate as wealth preservation and lifestyle elevation vehicles. Minimal mortgage dependency insulates this segment from UAE Central Bank leverage caps.
Market liquidity depends on Investors. Demand trajectory is climbing the fastest among End Users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth buyers from India and Russia concentrate transaction velocity in Dubai's waterfront districts, while Abu Dhabi attracts institutional capital seeking portfolio diversification. The UAE Central Bank's macroprudential framework shapes leverage access across emirates, compressing non-resident buyer pools and elongating payment structures.
Dubai
Indian family offices and Russian wealth preservation seekers drive demand in Palm Jumeirah and Downtown Dubai corridors. The Dubai Real Estate Regulatory Agency mandates escrow account compliance for off-plan sales, protecting foreign purchaser capital. Branded residence partnerships in Business Bay and Dubai Hills command sustained price premiums above comparable unbranded inventory.
Abu Dhabi
Institutional investors and GCC nationals prioritize trophy assets on Saadiyat Island and Al Reem Island for long-horizon wealth storage. The Abu Dhabi Department of Economic Development coordinates golden visa eligibility criteria with federal residency frameworks. Al Raha Beach and Yas Island clusters attract end-user demand from relocating family offices seeking cultural proximity.
Sharjah
Mid-luxury expat professionals target sub-AED 5 million townhouses for golden visa accessibility at lower entry thresholds. The Sharjah Real Estate Registration Directorate enforces title deed transparency standards that bolster foreign buyer confidence. Aljada and Tilal City developments capture spillover demand from Dubai's price compression.
Northern Emirates
Ajman and Ras Al Khaimah attract yield-focused investors from South Asia seeking rental income optimization at compressed land costs. Federal mortgage caps administered by the UAE Central Bank apply uniformly, constraining leverage equally across these secondary markets. Al Marjan Island and Ajman Corniche corridors concentrate new supply targeting budget-conscious luxury entrants.
UAE Luxury Residential Real Estate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue branded residence partnerships and technology-enabled concierge unbundling. The market structure concentrates around three developer archetypes: master-planned community specialists, waterfront land bank controllers, and hospitality-branded residence operators. Competitive moves center on waterfront land acquisition races and extended post-handover payment plan structures that circumvent Central Bank leverage constraints.
Among Dubai-based master developers, Emaar Properties and Nakheel exemplify contrasting land strategies—Emaar anchors premium supply in inland corridor communities while Nakheel controls scarce waterfront plots through its Palm portfolio. DAMAC Properties occupies the branded residence tier, leveraging hospitality operator partnerships to sustain price premiums. These three developers represent the market's dominant competitive archetypes without exhausting its participant base.
| Leading Market Players |
|---|
| OMNIYAT |
| Nakheel |
| Emaar Properties |
| Ellington Properties |
| Meraas |
| DAMAC Properties |
| H&H Development |
| Mira Developments |
| Sobha Realty |
| Others |
Value Network & Pricing Analysis
Ultra-high-net-worth buyers from Moscow and Mumbai anchor the UAE luxury residential market's value-based pricing model, where scarcity premiums on waterfront plots override conventional cost-plus calculations. Their minimal leverage dependency insulates trophy asset pricing from UAE Central Bank mortgage caps that compress mid-tier brackets.
Pricing Analysis
Volume concentrates in the AED 3-5 million golden visa threshold segment while margin pools deepen above AED 10 million. Price differentiation rests on waterfront positioning and branded residence partnerships, with Palm Jumeirah plots commanding sustained premiums over Dubai Hills inventory. Pricing pressure intensifies in the AED 5-15 million bracket where non-resident purchasers face steepest loan-to-value friction, elongating payment-plan structures. Indian family offices exhibit highest price sensitivity in mid-mansion categories; Russian ultra-high-net-worth individuals show least sensitivity in penthouse transactions.
Supply Chain Analysis
Specialized smart home infrastructure rests on European and East Asian technology suppliers, with bespoke interior materials drawing from Italian and Turkish manufacturing clusters. Raw material dependencies center on premium marble, engineered timber, and integrated building management system components. Supply chain risk concentrates in single-source vulnerability for custom architectural coordination between international design houses and local contractors. Distribution runs through direct-to-developer digital channels that displace traditional brokerage for repeat family office buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE luxury residential market sits at a technology-transition inflection, with integrated building management systems displacing legacy in-house staffing models and concierge service unbundling reshaping operational cost structures.
For Market Incumbents: Deepen waterfront land bank control before regulatory caps tighten further, prioritizing Palm portfolio adjacent positions and Dubai Hills corridor expansion. Secure exclusive partnerships with hospitality operators for branded residence cachet that sustains price premiums above unbranded stock. Invest in proprietary CRM ecosystems to capture direct-to-developer channel value from Russian and Indian repeat buyers. For New Entrants and Emerging Players: Enter via mid-mansion white space in the 5,000 to 7,000 square foot bracket, where relocating family office demand accelerates fastest and Emaar-Nakheel concentration leaves room for differentiated amenity programming. Target Sharjah and Northern Emirates sub-AED 5 million corridors for golden visa accessibility at compressed entry thresholds. Pursue technology-enabled concierge unbundling partnerships as primary go-to-market differentiation. For Investors and Strategic Acquirers: The window for entry favors developers with captive waterfront land positions and established branded residence operator relationships. Long-term viability hinges on holding-period extension as corporate tax residency rules reshape buyer nationality mix. Watch UAE Central Bank macroprudential adjustments and evolving golden visa criteria as primary inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Waterfront Land Bank Acquisition | Nakheel's Palm portfolio control demonstrates scarcity value capture in constrained developable frontage. |
| Branded Residence Partnership | DAMAC's hospitality operator alliances sustain price premiums above comparable unbranded inventory in Downtown Dubai. |
| Direct-to-Developer Channel Buildout | Proprietary CRM ecosystems capture relationship value from Russian and Indian repeat family office purchasers. |
| Smart Home Infrastructure Integration | European and East Asian technology partnerships meet baseline requirements from Moscow and Mumbai buyers. |
| Extended Post-Handover Payment Plans | Lengthened structures circumvent UAE Central Bank loan-to-value caps constraining non-resident leverage access. |
Research Methodology
Document review covered Dubai Real Estate Regulatory Agency escrow filings, UAE Central Bank macroprudential disclosures, and developer project registration data, complemented by interviews with master-planned community development executives, branded residence hospitality operators, family office relocation advisors, and mortgage lending specialists at UAE financial institutions. Secondary validation drew from RERA transaction records, MOHAP construction quality filings, and federal residency framework publications. Bottom-up unit-level demand modeling triangulated against top-down emirate-level supply pipeline assessments.
Market sizing outputs segment across property type, square footage threshold, price tier, and buyer archetype dimensions, with annual growth trajectories derived from historical transaction velocity patterns and pipeline completion schedules. Forecast inputs incorporate golden visa eligibility evolution, corporate tax residency alignment, and waterfront land scarcity progression throughout the projection horizon. CAGRs reflect compounding assumptions anchored to verified 2026 baseline valuation and supply-constrained demand elasticity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt UAE Central Bank leverage restriction tightening or golden visa threshold modification. Projections reflect assumptions around sustained Russian and Indian ultra-high-net-worth migration, construction input cost stability, and regulatory framework continuity. A small set of named triggers—escrow mandate expansion, mortgage cap adjustment, and corporate substance requirement evolution—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market