
 Saudi Arabia Luxury Market | 2026-2036
Saudi Arabia Luxury Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Luxury Market Intelligence
Young affluent nationals is collapsing the historical dominance of expatriate and tourist buyers in Saudi Arabia's luxury landscape. L'azurde Company for Jewelry anchors its position through captive manufacturing of 18-karat and 21-karat gold collections tailored to Gulf aesthetic preferences. Four Seasons competes by controlling premium hospitality assets aligned with the Kingdom's tourism transformation. Fitaihi Holding Group leverages its multi-brand retail footprint to extend reach across emerging secondary cities.
Saudi Arabia luxury encompasses high-value goods and experiential services characterized by scarcity positioning, artisanal craftsmanship, and premium materials such as ethically sourced gemstones and bespoke textiles. Fashion and jewelry segments lead current revenue pools, with fragrances capturing outsized margin contribution through localized oud-based formulations. Ultra-luxury price tiers sustain the fastest trajectory, propelled by limited-edition releases and private clienteling programs targeting high-net-worth individuals. Online retail channels are displacing traditional department store dominance as digital-native affluent shoppers demand seamless omnichannel fulfillment.
SFDA governs cosmetic and fragrance safety standards, while the Ministry of Tourism enforces hospitality classification protocols that directly shape market access for international luxury operators. MOHAP licensing requirements for commercial establishments further structure how foreign brands establish physical presence. Stakeholders must monitor evolving local content mandates and Saudization targets that increasingly condition operating licenses and procurement preferences.
Market Dynamics
The Saudi Arabia luxury market pivots on a generational demand rotation where young affluent nationals now dominate purchasing volume, displacing historical reliance on expatriate and tourist buyers through localized experiential offerings and digital-native engagement models.
Growth Catalysts
- Quality of Life Program:Government investment in entertainment infrastructure and cultural venues creates new experiential luxury consumption occasions. Riyadh Season and Jeddah events draw domestic high-net-worth spending.
- Tourism visa liberalization:Streamlined entry protocols expand the addressable market for hospitality and retail operators. International visitors supplement domestic demand during peak consumption periods.
- Secondary city expansion:Mega-development projects in NEOM, the Red Sea Project, and Qiddiya extend luxury access beyond traditional Riyadh-Jeddah concentration zones.
Market Restraints
- Import dependency for precious metals:Limited domestic gold mining and refining capacity exposes jewelry manufacturers to London Bullion Market Association price volatility and currency fluctuation.
- Saudization workforce mandates:Nitaqat program requirements constrain talent acquisition for specialized retail and hospitality roles, extending recruitment timelines.
- Commercial establishment licensing:MOHAP and municipal permitting processes create procedural friction for foreign brand market entry, delaying physical storefront launches.
Strategic Opportunities
- Eastern Province penetration:Khobar and Dammam present underdeveloped luxury retail density relative to household wealth concentration, offering first-mover positioning.
- Omnichannel integration:Digital-native affluent shoppers demand seamless online-to-offline fulfillment, rewarding operators who unify inventory and clienteling systems.
- Local content procurement preferences:Evolving government incentives for domestic manufacturing partnerships create structural advantages for brands with regional production capabilities.
Industry Challenges
- Artisanal craftsmanship scarcity:Limited pipeline of trained goldsmiths and bespoke textile specialists constrains expansion of limited-edition and made-to-order product lines.
- SFDA fragrance compliance timelines:Extended safety assessment periods for new oud-based formulations delay product launches and compress seasonal marketing windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Luxury Market |
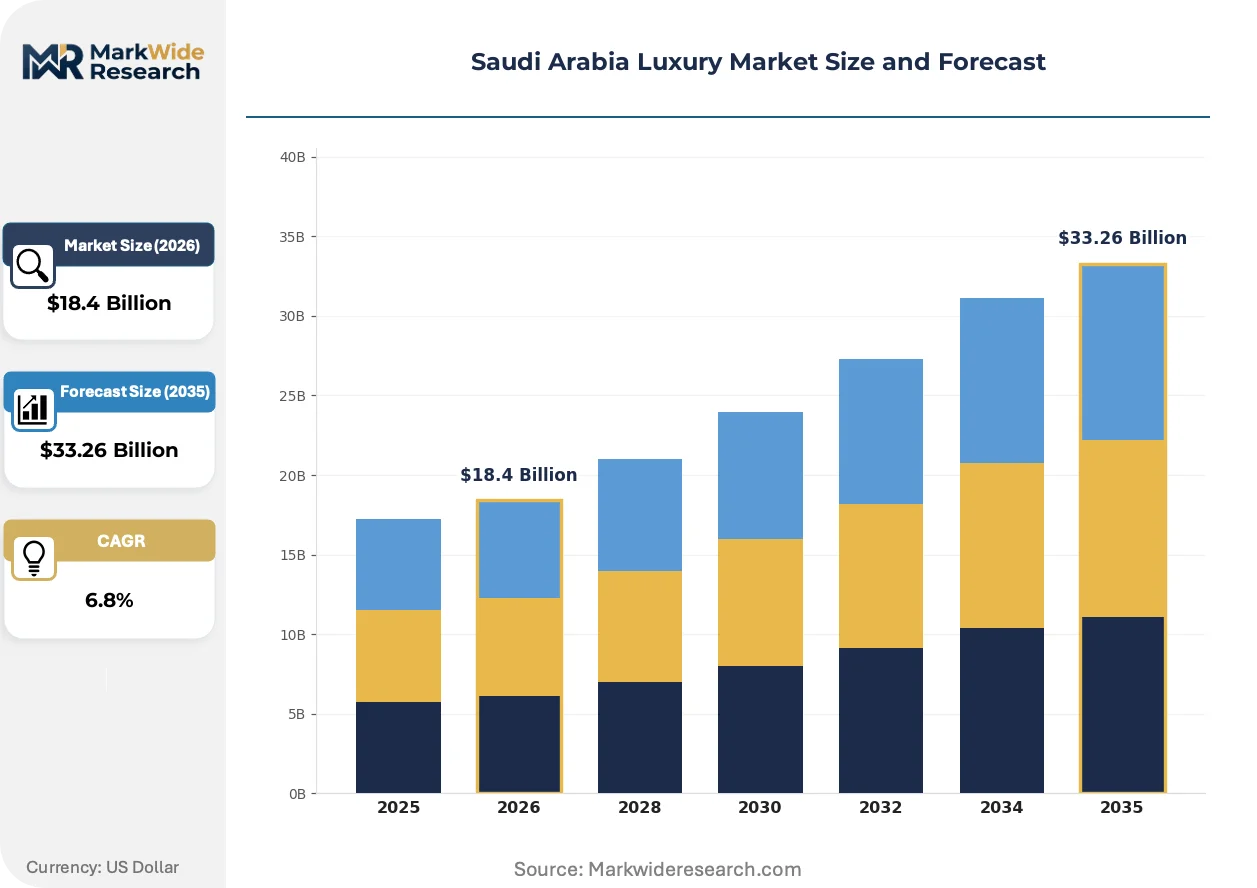
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Accessories, Jewelry, Fragrances Customer Type: High-net-worth Individuals, Affluent Shoppers, Luxury Tourists, Celebrities Distribution Channel: Online Retail, Luxury Boutiques, Department Stores, Duty-Free Price Tier: Premium, Super Premium, Ultra-luxury, Exclusive Collections |
| Companies Covered | Raffles, The Red Palace, Fitaihi Holding Group, SRMG Labs, Landor Middle East, L'azurde Company for Jewelry, Hyatt, Takyeez, Four Seasons, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Luxury Market Strategic Shifts & Innovations
Digital infrastructure investment and regulatory modernization are compressing traditional luxury distribution hierarchies while elevating experiential and personalized service models as primary competitive differentiators.
Artificial intelligence-powered clienteling platforms is displacing traditional personal shopper relationships in high-value jewelry and fashion segments. Affluent Saudi consumers under age 35 adopt these tools at accelerating rates. The technology compresses customer acquisition costs while enabling predictive inventory positioning.
SFDA cosmetic and fragrance safety standards are tightening ingredient disclosure and testing protocols. International operators must adapt formulation documentation and supply chain traceability systems. Fragrance houses with oud-specialized portfolios face the steepest compliance recalibration requirements.
Experiential hospitality integration now dominates luxury purchasing journeys, with fine dining and cultural programming bundled into retail and jewelry consultations. Traditional department store formats lose traffic to destination venues combining multiple touchpoints. Riyadh and Jeddah property developers actively court hybrid concept operators.
Saudi Arabia Luxury Market Segmentation
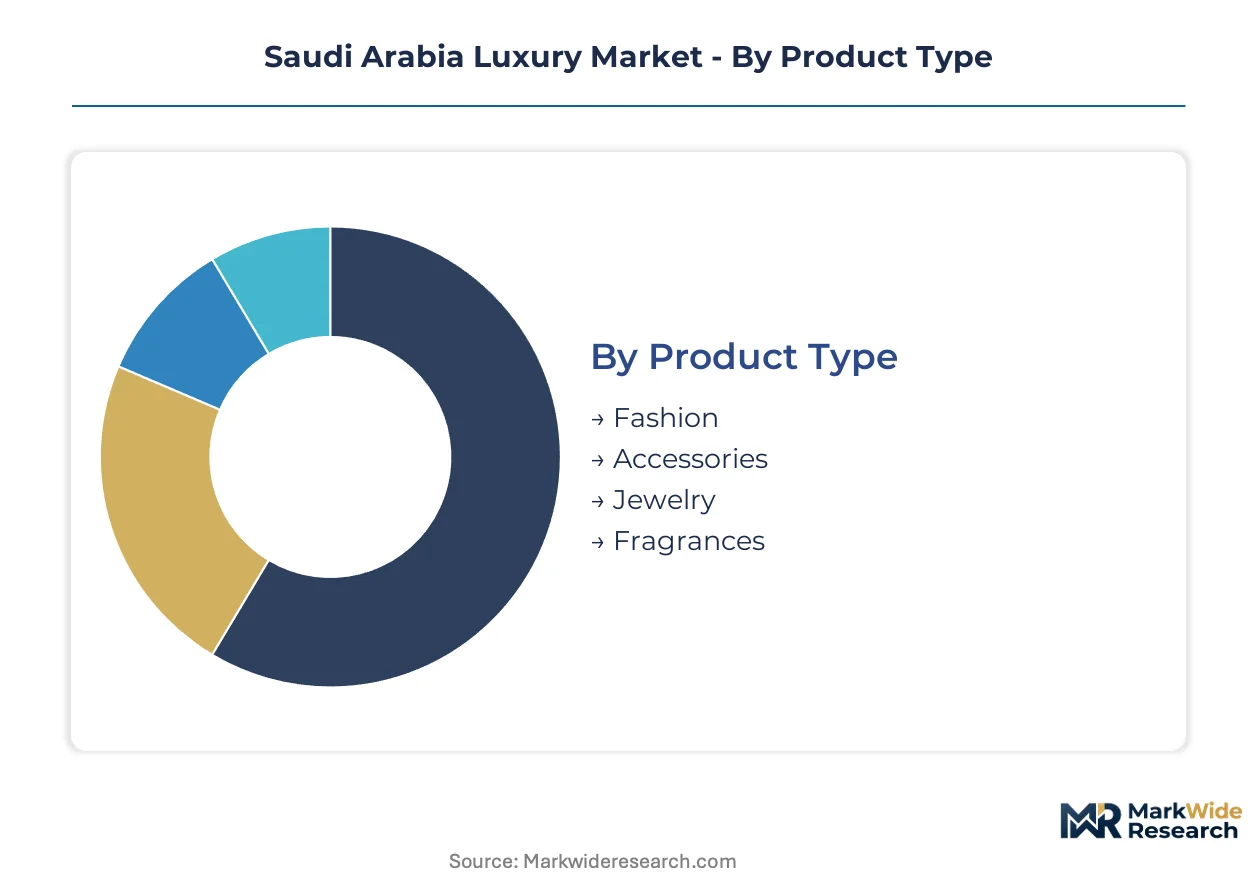
Segmentation in the Saudi Arabia luxury market reveals how regulatory frameworks, generational wealth shifts, and infrastructure investments reshape competitive positioning across distinct buyer profiles and access channels. Understanding these divisions enables operators to align product portfolios with localized compliance requirements and evolving consumption patterns.
Product Type:
SFDA cosmetic and fragrance safety standards create divergent compliance burdens across material categories, with natural ingredient disclosure requirements varying significantly between precious metals and formulated products.
- Fashion:Bespoke tailoring and abaya collections incorporate regionally sourced textiles with artisanal embroidery. Riyadh and Jeddah developers anchor mixed-use retail concepts around fashion flagships, with experiential hospitality integration driving foot traffic beyond traditional department store formats.
- Jewelry:18-karat and 21-karat gold fabrication dominates local manufacturing, with Gulf aesthetic preferences shaping design motifs. Domestic goldsmith capacity constraints limit expansion of made-to-order lines, exposing operators to London Bullion Market Association price volatility for imported raw materials.
- Accessories:Leather goods and small leather articles face escalating Saudization mandates in retail staffing.
- Fragrances:Oud-based formulations command outsized margin contribution but face extended SFDA safety assessment timelines.
Established volume favors jewelry; emerging adoption favors fragrances.
Customer Type:
Generational wealth transfer concentrates purchasing power among digitally native demographics under age 35, collapsing historical reliance on expatriate and tourist buyer segments.
- High-net-worth Individuals:Private clienteling programs and limited-edition releases sustain ultra-luxury price tier viability. NEOM and Red Sea Project developments target this segment with exclusive residential and hospitality inventory.
- Affluent Shoppers:Young Saudi nationals drive omnichannel fulfillment expectations, with seamless online-to-offline integration becoming a baseline competitive requirement. This segment expands most quickly as domestic entertainment infrastructure matures under the Quality of Life Program.
- Luxury Tourists:Tourism visa liberalization supplements peak consumption periods but remains secondary to domestic demand rotation.
- Celebrities:Influencer partnerships accelerate fragrance and fashion visibility, particularly during Riyadh Season programming.
Domestic affluent shoppers dominate current volume; high-net-worth individuals concentrate margin capture.
Distribution Channel:
Digital infrastructure investment compresses traditional hierarchies, with inventory unification and predictive positioning becoming primary differentiators against legacy department store formats.
- Online Retail:AI-powered clienteling platforms displace traditional personal shopper relationships in high-value segments. Predictive analytics enable inventory positioning that reduces customer acquisition costs for digitally native affluent consumers.
- Luxury Boutiques:Hybrid concepts combining retail with fine dining and cultural programming capture destination-oriented spending. Property developers in Riyadh and Jeddah actively court operators with experiential integration capabilities.
- Department Stores:Traditional formats lose traffic to hybrid venues, with secondary city expansion offering limited offset.
- Duty-Free:Airport retail remains constrained by tourist volume dependency relative to domestic demand growth.
Boutique expansion favors experiential operators; online retail rewards unified inventory systems.
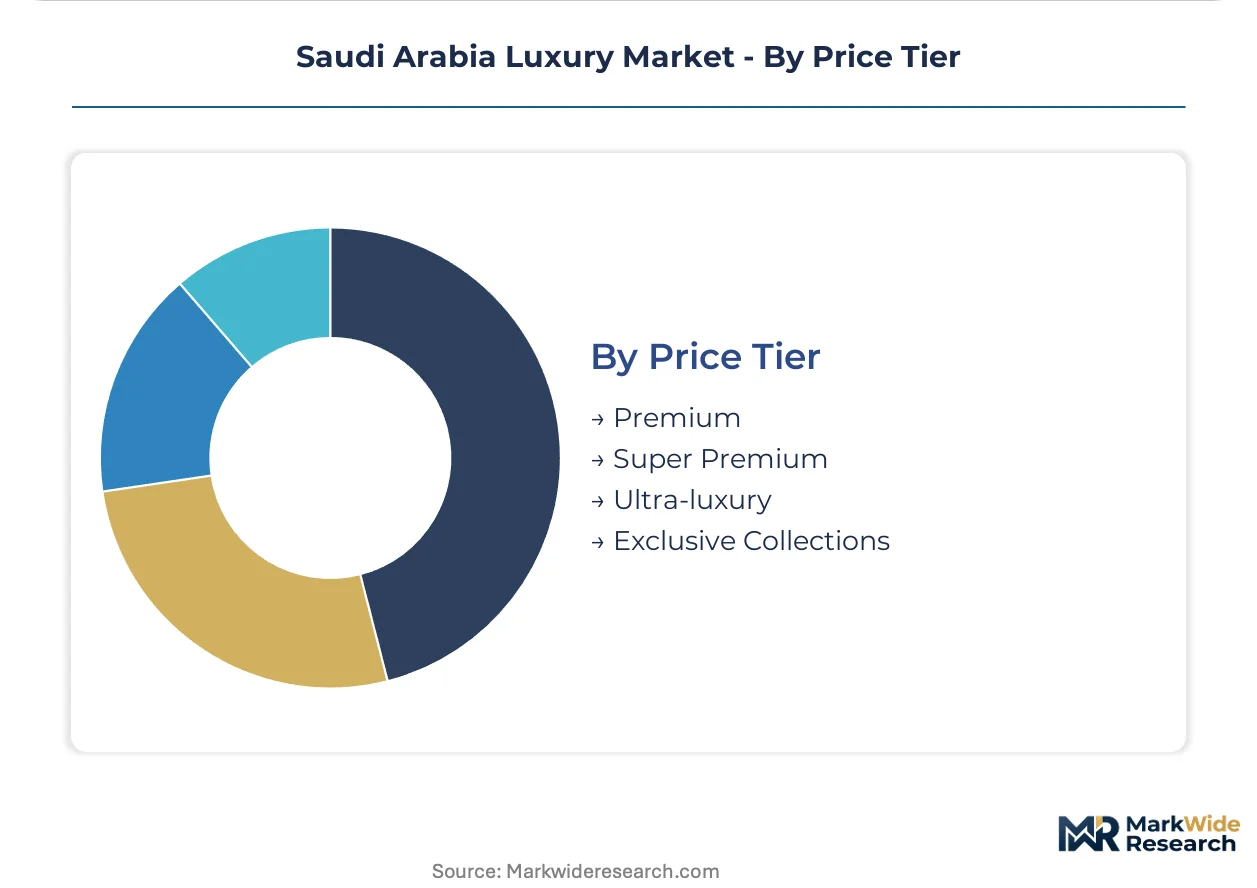
Price Tier:
Margin structures stratify across scarcity positioning and craftsmanship intensity, with local content procurement preferences increasingly conditioning access to government-linked contracts and licensing advantages.
- Ultra-luxury:Limited-edition releases and bespoke services sustain steepest expansion trajectory through private clienteling. Artisanal craftsmanship scarcity constrains supply expansion, protecting margin structures.
- Exclusive Collections:Collaborations with regional artists and heritage motifs capture domestic cultural programming visibility. MOHAP licensing requirements for commercial establishments create procedural friction that favors established operators with regulatory navigation capabilities.
- Super Premium:Accessible entry point for young affluent nationals rotating into luxury consumption.
- Premium:Volume foundation with compressed margins relative to scarcity-positioned tiers.
Ultra-luxury concentrates margin expansion; super premium captures generational entry demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury consumption concentrates in Saudi Arabia's principal urban agglomerations and emerging mega-developments, with domestic affluent demand displacing historical reliance on expatriate and tourist purchasing. Riyadh and Jeddah anchor current volume, while giga-projects extend geographic reach.
Riyadh
Domestic high-net-worth households and government administrative concentration drive demand for ultra-luxury hospitality and fine jewelry. The Quality of Life Program funds entertainment infrastructure including Riyadh Season, creating seasonal consumption peaks. The King Abdullah Financial District and Diriyah Gate developments host hybrid retail-hospitality concepts targeting young affluent nationals.
Jeddah
Red Sea proximity and historic merchant wealth sustain premium fashion and fragrance purchasing, with oud-based formulations capturing outsized margins. Tourism visa liberalization expands addressable market for hospitality operators during pilgrimage periods. The Jeddah Central Project and waterfront redevelopment attract destination retail concepts with experiential programming.
Eastern Province
Khobar and Dammam present underdeveloped luxury retail density relative to household wealth concentration from petroleum sector employment. Saudization mandates under Nitaqat constrain specialized retail staffing, extending recruitment timelines for international brand entry. The Dhahran Expo and King Fahd Causeway corridor offer first-mover positioning for operators with regulatory navigation capabilities.
NEOM Northwest
The Line and Sindalah island developments target exclusive residential and hospitality inventory for ultra-high-net-worth individuals. MOHAP licensing requirements for commercial establishments create procedural friction that favors established operators with government relationship infrastructure. Local content procurement preferences increasingly condition access to project-linked contracts.
Makkah and Madinah
Pilgrimage traffic sustains seasonal demand spikes for fragrances and accessories, though religious sensitivities constrain certain fashion categories. SFDA cosmetic safety standards govern oud-based product distribution through duty-free and hotel retail channels. Secondary infrastructure investment lags primary cities, limiting year-round luxury retail presence.
Saudi Arabia Luxury Market Key Industry Players
Concentration sits with hospitality operators and jewelry fabricators controlling captive assets and localized manufacturing capabilities. The competitive structure divides between integrated mega-project developers, multi-brand retail conglomerates, and specialized heritage houses. Two strategic archetypes dominate: experiential hospitality providers bundling retail and fine dining, and captive manufacturers with Gulf-aesthetic design control. Dominant competitive moves include strategic partnerships with property developers for hybrid venue access, and portfolio diversification into secondary city expansion.
Among hospitality-anchored operators, Four Seasons and Hyatt exemplify the experiential integration archetype through premium asset control aligned with tourism transformation. Within jewelry manufacturing, L'azurde Company for Jewelry occupies a position representing captive production capabilities for 18-karat and 21-karat gold collections. Fitaihi Holding Group sits within the multi-brand retail tier, extending reach across emerging secondary cities through established regulatory navigation. Raffles and The Red Palace represent heritage hospitality positioning within the ultra-luxury tier.
| Leading Market Players |
|---|
| Raffles |
| The Red Palace |
| Fitaihi Holding Group |
| SRMG Labs |
| Landor Middle East |
| L'azurde Company for Jewelry |
| Hyatt |
| Takyeez |
| Four Seasons |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for oud-based fragrance formulations tie pricing power directly to SFDA compliance timelines and raw material sourcing concentration in Southeast Asian agarwood plantations. This lead-time structure forces operators to pre-position stock ahead of seasonal demand windows, compressing margin flexibility when London Bullion Market Association gold price volatility intersects with extended safety assessment periods.
Pricing Analysis
SFDA cosmetic and fragrance safety standards dictate the pricing tier structure across the Saudi Arabia luxury market, with extended testing timelines for natural oud formulations creating scarcity premiums at the ultra-luxury level. Price differentiation stems from certification grade (halal compliance tier) and vertical integration depth in captive gold manufacturing. Pricing pressure stems from import dependency for precious metals, with 21-karat gold collections exposed to currency fluctuation. Affluent shoppers under age 35 demonstrate lowest price sensitivity, while premium-tier fashion accessories face compression from Saudization-mandated staffing costs.
Supply Chain Analysis
Strait of Hormuz transit underwrites precious metals and agarwood resin flows into Saudi fabrication facilities, with downstream distribution resting on Riyadh-Jeddah retail corridor concentration. Raw material dependencies include Indian gold bullion, Thai agarwood, and Italian leather hides. Supply chain risk centers on single-source vulnerability for trained goldsmith capacity. Distribution feeds from captive manufacturing through hybrid boutique concepts and unified online-offline inventory systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia luxury market demands substitution defense against experiential hospitality operators capturing share from traditional retail formats through bundled fine dining and cultural programming. Digital-native clienteling platforms present parallel substitution pressure on legacy personal shopper relationships.
For Market Incumbents: Compound defensive positioning through captive manufacturing partnerships with domestic goldsmith training programs, countering artisanal craftsmanship scarcity that constrains limited-edition expansion. Deepen hybrid venue control by securing preferred operator status with NEOM and Red Sea Project developers before competitor entry. Prioritize SFDA regulatory navigation capabilities as a licensing moat against delayed foreign brand launches.
For New Entrants and Emerging Players: Anchor in Eastern Province white space, where Khobar and Dammam household wealth concentration outpaces luxury retail density. Target super-premium fragrance as the most penetrable tier, given oud-based margin structures and lower capital requirements versus jewelry fabrication. Pursue omnichannel-first go-to-market positioning to bypass legacy department store gatekeeping.
For Investors and Strategic Acquirers: Carve-out targets emerge from multi-brand retail conglomerates seeking portfolio rationalization, particularly operators with secondary city footprints but limited experiential integration capabilities. Long-term viability hinges on regulatory navigation infrastructure and local content procurement relationships. Watch Nitaqat program enforcement intensity as the signal for operating cost inflection and competitive consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Manufacturing Partnership | Secures 18-karat and 21-karat gold supply against London Bullion Market Association price volatility. |
| Hybrid Venue Development | Captures destination-oriented spending through fine dining integration with jewelry consultations. |
| AI-Powered Clienteling Platform | Displaces traditional personal shopper relationships for digitally native affluent consumers under 35. |
| Eastern Province Retail Expansion | Exploits underdeveloped luxury density relative to petroleum sector household wealth concentration. |
| SFDA Compliance Infrastructure | Accelerates oud-based fragrance launch timelines against competitors facing extended safety assessments. |
Research Approach
A standing panel of luxury retail operations directors, hospitality asset managers, fragrance regulatory affairs specialists, and jewelry manufacturing procurement leads provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SFDA cosmetic safety filings, Ministry of Tourism hospitality classification databases, and London Bullion Market Association price records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators from Quality of Life Program investment disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, customer archetype, distribution channel, and price tier, with regional development project phasing as an additional industry-specific variable. CAGRs derived from trend extrapolation anchored in documented infrastructure investment schedules and visa liberalization policy trajectories.
Underlying assumptions cover tourism visa volume elasticity, Saudization enforcement intensity, and precious metals price correlation patterns, with deviation risk concentrated in SFDA regulatory timeline shifts and mega-project construction delays. Practitioners should keep alternative scenarios live as government entertainment infrastructure spending commitments and Nitaqat program modifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market