
 Bagasse Tableware Products Market | 2026-2036
Bagasse Tableware Products Market Size, Share, and Industry Trends Forecast 2026-2036
Bagasse Tableware Products Market Analysis
Aftermarket composting infrastructure revenue is fragmenting across municipal and private operators, complicating end-of-life value capture for manufacturers. Huhtamaki leverages its European regulatory expertise to secure food-contact certifications ahead of regional compliance deadlines. Xiamen Environmental Protection Technology Co., Ltd. anchors production in Fujian Province with integrated pulp molding and thermal pressing capacity. Vegware Ltd. differentiates through closed-loop collection partnerships with UK waste management firms.
Bagasse tableware comprises molded fiber products manufactured from sugarcane pulp residue, typically processed through mechanical pulping, vacuum forming, and hot pressing at temperatures exceeding 180°C to achieve oil and water resistance. The resulting items serve as compostable alternatives to conventional plastic disposables in food service and takeaway applications. Plates and bowls command the largest volume share due to standardized sizing across restaurant chains, while cutlery experiences accelerated growth as operators pursue complete serviceware replacement. The takeaway application segment attracts premium pricing relative to dine-in disposable solutions, reflecting logistical durability requirements and branded packaging demands.
The EU F-Gas Regulation and REACH compliance frameworks govern chemical additives in molded fiber coatings, while India's BIS certification mandates heat-resistance thresholds for food-contact materials. US FDA food-contact substance notifications and state-level extended producer responsibility laws in California and New York shape product formulation and labeling requirements. Stakeholders must monitor compostability certification fragmentation across ASTM D6400, EN 13432, and home-composting standards to avoid market access barriers.
Market Dynamics
Single-use plastic bans across the European Union, India, and multiple US states are forcing food service operators toward compostable alternatives, while China's concentrated sugarcane bagasse supply base locks in manufacturing advantages that reshape competitive positioning.
Growth Catalysts
- EU Single-Use Plastics Directive:Quick-service restaurants across France, Germany, and Italy must eliminate plastic serviceware by mandated deadlines, creating immediate substitution demand for molded fiber plates and containers.
- Sugarcane processing clusters:Guangxi and Yunnan provinces in China host integrated pulp molding infrastructure that compresses raw material-to-finished-product cycle times.
- Quick-service restaurant chains:Burger King, McDonald's, and regional operators in India are specifying bagasse alternatives in corporate sustainability procurement mandates.
Market Restraints
- Composting infrastructure gaps:Municipal facilities in the US and UK lack industrial composting capacity, causing certified products to enter landfill streams and undermining value propositions.
- Bagasse fiber concentration:Over 60% of global sugarcane pulp supply concentrates in Chinese provinces, exposing manufacturers to logistics disruptions and input cost volatility.
- PLA and PHA substitutes:Bioplastic alternatives from NatureWorks and TotalEnergies Corbion threaten bagasse tableware in cold-food applications where heat resistance is unnecessary.
Strategic Opportunities
- Home-composting certification:TÜV Austria's OK compost HOME standard opens premium positioning in German and Austrian retail channels where backyard composting rates exceed 40%.
- India BIS heat-resistance mandates:The Bureau of Indian Standards certification creates barrier-to-entry protection for compliant manufacturers serving the subcontinent's 1.4 billion consumer base.
- Closed-loop collection partnerships:UK waste management firms are piloting return schemes with food service operators that capture end-of-life value and secure feedstock for circular production.
Industry Challenges
- ASTM D6400 versus EN 13432 divergence:Manufacturers must maintain dual certification pathways for US and European market access, doubling testing costs and timeline complexity.
- Thermal pressing equipment scarcity:Vacuum forming and hot pressing machinery above 180°C operational thresholds faces 12-18 month lead times from European and Japanese suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bagasse Tableware Products Market |
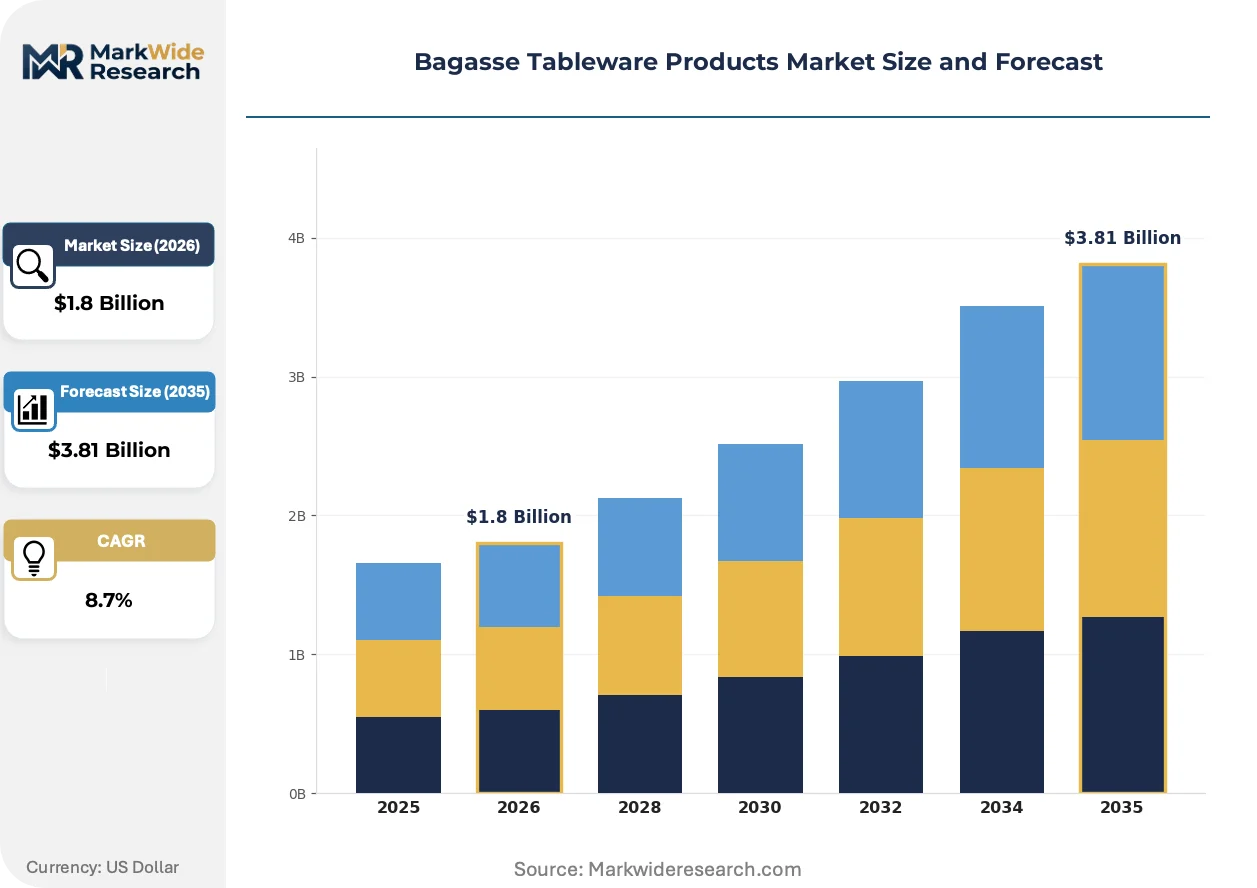
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Trays, Cutlery End User: Restaurants, Catering Services, Households, Events Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Direct Sales Application: Food Service, Takeaway, Eco-Friendly Events, Disposable Solutions |
| Companies Covered | Vegware Ltd., Xiamen Environmental Protection Technology Co., Ltd., Hangzhou Mana Technology Co., Ltd (ZX PACKING), Dart Container, Huhtamaki, GangXuan Eco-Pack, Hefei Craft Tableware Co., Ltd., BioPak Pty Ltd, Hefei Sumkoka Environmental Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bagasse Tableware Products Market Emerging Trajectories
Barrier coating chemistry and forming automation are compressing unit economics while regulatory fragmentation across compostability standards forces product architecture decisions that lock in geographic market access.
Per- and polyfluoroalkyl substance-free oil barriers are migrating from laboratory-scale alkyl ketene dimer treatments to commercial silicone and bio-wax formulations. Quick-service chains in California and New York are specifying PFAS-free alternatives ahead of state-level bans taking effect. The technology shift is compressing coating cost premiums from 35% above conventional to under 15%, enabling mass-market penetration.
REACH compliance frameworks are tightening chemical additive disclosure requirements for molded fiber food-contact materials. ECHA's expanded authorization list is forcing reformulation of water-resistant coatings across European supply chains. Manufacturers serving Germany and France are responding with third-party certified additive-free product lines that command 20% shelf price premiums in retail channels.
Centralized procurement by multinational food service operators is consolidating supplier relationships around vertically integrated molders with in-house pulp production. Aramark, Compass Group, and Sodexo are reducing vendor counts from 15-20 to 3-5 per category, favoring partners with guaranteed supply volumes and multi-continent certification coverage. This concentration is most visible in UK and US contract catering where sustainability scorecards determine vendor selection.
Bagasse Tableware Products Market Segmentation
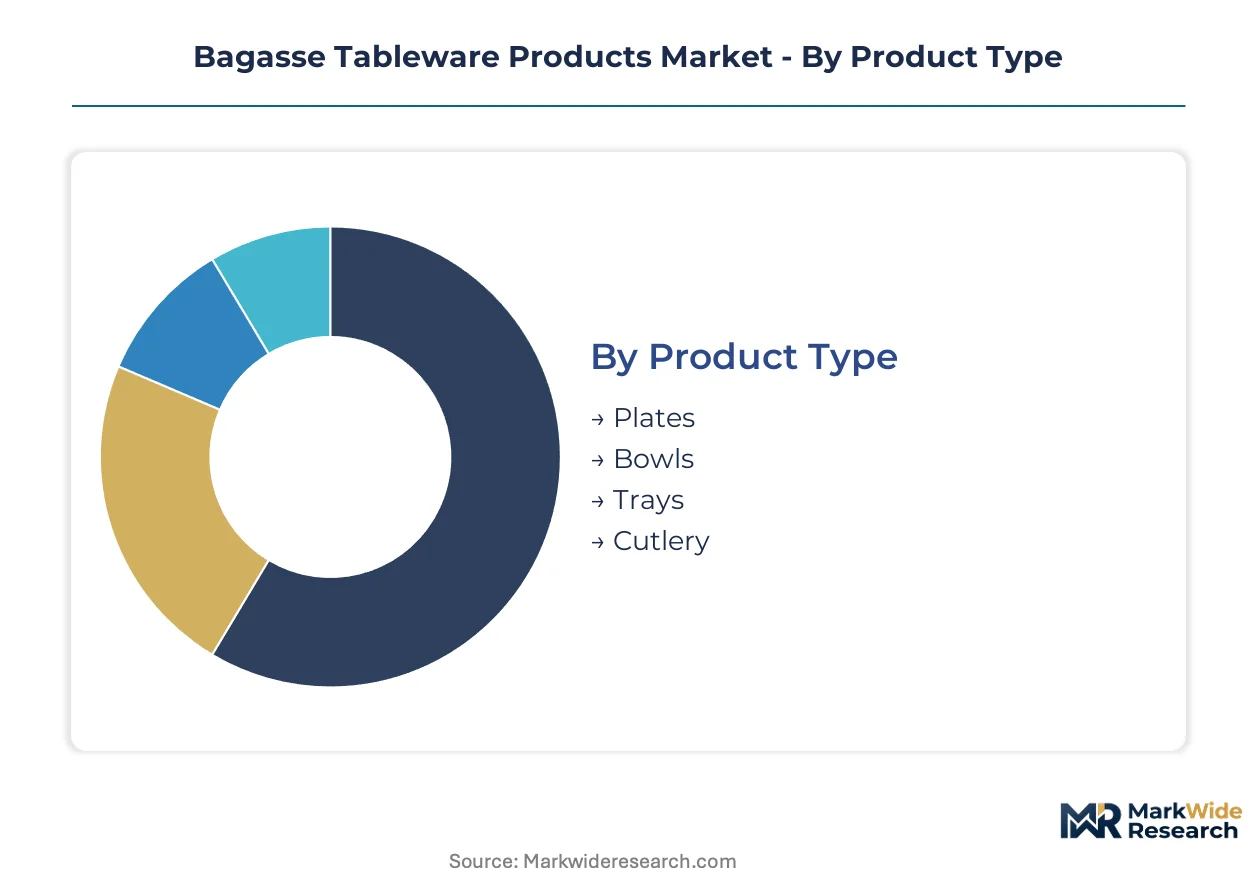
Product architecture in bagasse tableware responds to divergent durability and certification requirements across food service channels. Segmentation reveals how thermal pressing specifications, compostability standards, and procurement consolidation reshape competitive boundaries within each category.
Product Type:
Cost tier differentiation separates standardized molded fiber formats from specialized cutlery requiring reinforced fiber density and extended pressing cycles.
- Plates:Flat-pressed bagasse sheets formed at 180°C+ achieve structural rigidity for hot-food contact. Quick-service restaurants in France and Germany specify these for dine-in replacement under EU Single-Use Plastics Directive mandates.
- Bowls:Deep-drawn vacuum forming with reinforced rim structures resists liquid penetration for soup and sauce applications. Catering operators in India prioritize BIS-certified heat-resistant variants for institutional procurement contracts.
- Trays:Compartmentalized designs serve airline and institutional meal delivery with integrated lid compatibility.
- Cutlery:High-density fiber compression and extended hot-pressing cycles produce tine and blade durability. Cold-food chains specify these where PLA substitutes lack mechanical strength.
Plates command the established base. The steepest expansion runs through cutlery as operators pursue complete serviceware replacement.
End User:
Customer type determines volume scale, certification stringency, and procurement consolidation intensity across the value chain.
- Restaurants:Quick-service chains including Burger King and McDonald's specify bagasse alternatives in corporate sustainability mandates. Centralized procurement reduces vendor counts from 15-20 to 3-5 per category, favoring manufacturers with multi-continent certification coverage.
- Catering Services:Contract caterers Aramark, Compass Group, and Sodexo apply sustainability scorecards that lock in vertically integrated molders with guaranteed supply volumes. UK and US contract catering show the most visible supplier concentration.
- Households:German and Austrian retail channels demand TÜV Austria OK compost HOME certification where backyard composting rates exceed 40%.
- Events:Festival and stadium operators source compostable serviceware to meet temporary venue waste diversion targets.
Restaurants anchor volume concentration. Households are climbing the fastest as retail certification premiums compress toward mass-market accessibility.
Distribution Channel:
Supply concentration in Chinese manufacturing clusters shapes logistics economics and channel viability for different customer scales.
- Retail Stores:Supermarket and specialty food service outlets stock certified product lines commanding 20% shelf price premiums in German and French channels.
- Online Platforms:E-commerce penetration accelerates for small-batch household purchasers seeking home-composting verification.
- Wholesalers:Food service distributors consolidate procurement for mid-scale restaurant operators lacking direct manufacturer relationships.
- Direct Sales:Multinational operators bypass intermediaries to secure volume guarantees and custom mold development.
Direct sales capture the largest contract value. Online platforms gain share fastest as certification transparency tools mature.
Application:
Functional requirements for heat resistance, oil barrier performance, and logistical durability segment pricing power across use cases.
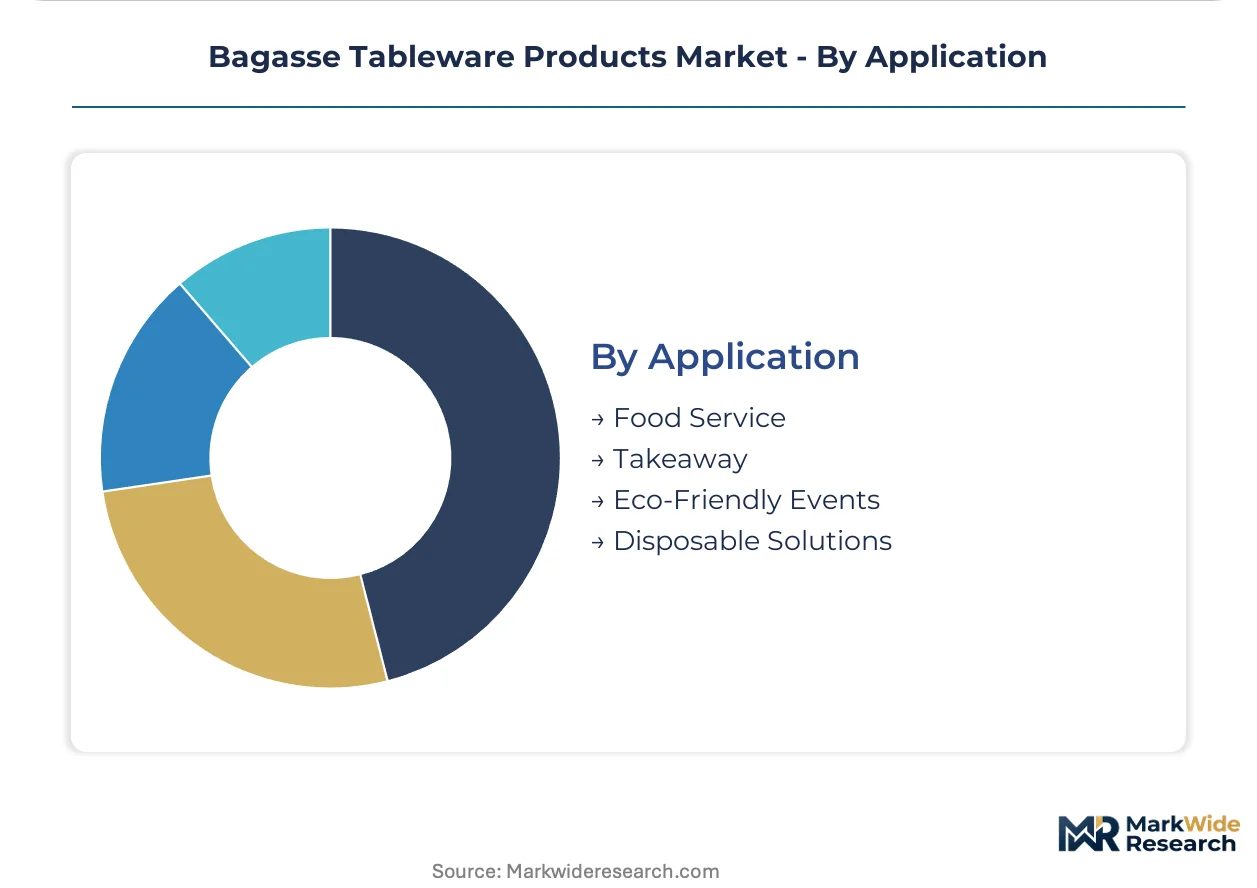
- Food Service:Dine-in disposable solutions emphasize standardized sizing and rapid table turnover compatibility. Plates and bowls dominate this segment with established supply chain integration.
- Takeaway:Premium pricing reflects branded packaging demands and enhanced structural durability for transport stress. California and New York operators specify PFAS-free oil barriers ahead of state-level bans.
- Eco-Friendly Events:Temporary venue procurement prioritizes visible compostability certification for attendee messaging.
- Disposable Solutions:Generic unbranded formats compete on unit cost for price-sensitive institutional buyers.
Food service holds volume leadership. Takeaway posts the steepest expansion trajectory as delivery platform growth extends addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangxi and Yunnan provinces in China control over 60 percent of global sugarcane pulp supply, locking in manufacturing advantages that ripple through pricing and availability across importing regions.
China
Food service operators in quick-service chains drive substitution demand as corporate sustainability mandates accelerate. The country's GB standards for food-contact materials govern molded fiber safety thresholds. Xiamen and Fuzhou host integrated pulp molding clusters where vacuum forming and thermal pressing capacity concentrates.
United States
California and New York state-level bans on PFAS in food packaging are forcing reformulation of oil barrier coatings. FDA food-contact substance notifications shape product entry pathways. Midwest distribution hubs consolidate procurement for national restaurant chains seeking multi-region supply guarantees.
Germany
Retail channels command 20 percent shelf price premiums for TÜV Austria OK compost HOME certified products. ECHA's REACH compliance frameworks tighten chemical additive disclosure for molded fiber coatings. Bavarian waste management firms pilot closed-loop collection partnerships with food service operators.
India
Quick-service restaurant chains specify bagasse alternatives in procurement mandates covering 1.4 billion consumers. BIS certification mandates heat-resistance thresholds that create barrier-to-entry protection. Maharashtra and Gujarat industrial corridors attract molded pulp manufacturing investments.
France
EU Single-Use Plastics Directive deadlines eliminate plastic serviceware in dine-in and takeaway applications. ANSM enforces food-contact material safety standards alongside EU-wide regulations. Lyon and Paris metropolitan clusters concentrate catering procurement decisions for multinational contract operators.
Bagasse Tableware Products Market Vendor Landscape
Vertically integrated pulp molders and specialized coating technology providers split the market between scale-driven supply security and formulation differentiation. Tiered concentration favors manufacturers with captive sugarcane pulp supply and multi-continent certification coverage. Strategic moves center on backward integration into raw material sourcing and geographic expansion through regional certification acquisition.
Among China-based fabricators, Xiamen Environmental Protection Technology Co., Ltd. and Hefei Craft Tableware Co., Ltd. exemplify integrated production models with in-house pulp molding capacity. European specialists including Vegware Ltd. occupy positions emphasizing certification depth and closed-loop collection partnerships. Huhtamaki represents multinational scale players leveraging regulatory expertise across multiple jurisdictions.
| Leading Market Players |
|---|
| Vegware Ltd. |
| Xiamen Environmental Protection Technology Co., Ltd. |
| Hangzhou Mana Technology Co., Ltd (ZX PACKING) |
| Dart Container |
| Huhtamaki |
| GangXuan Eco-Pack |
| Hefei Craft Tableware Co., Ltd. |
| BioPak Pty Ltd |
| Hefei Sumkoka Environmental Technology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Guangxi and Yunnan provinces in China host over 60 percent of global sugarcane pulp supply, anchoring raw material costs and compressing margin pools downstream toward certification-holding distributors and vertically integrated molders with captive thermal pressing capacity.
Pricing Analysis
EU Single-Use Plastics Directive deadlines dictate the pricing tier structure across European channels. Three-tier pricing stratifies across home-composting certified premium lines, industrial-composting standard grades, and uncertified economy formats for price-sensitive institutional buyers. PFAS-free coating reformulations are intensifying cost compression in the premium tier as California and New York state bans force ingredient substitution. Quick-service restaurant chains with centralized procurement show lowest price sensitivity, while independent food service operators exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for North American distributors. Raw material flows draw from Chinese sugarcane processing clusters, Southeast Asian pulp traders, and emerging Indian bagasse collectors. Thermal pressing machinery scarcity from European and Japanese equipment makers creates single-source vulnerability for capacity expansion. Distribution feeds from Fujian Province manufacturing hubs through Rotterdam and Los Angeles port consolidation points toward food service distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as multinational quick-service chains reduce vendor counts from 15-20 to 3-5 per category, extracting volume guarantees and custom mold development commitments from remaining suppliers.
For Market Incumbents: Build regulatory certification moats by securing dual ASTM D6400 and EN 13432 pathways ahead of compliance deadlines. Expand captive pulp molding capacity in Maharashtra and Gujarat industrial corridors to offset Chinese supply concentration risk. Deepen backward integration into sugarcane collection networks to secure feedstock priority during harvest volatility.
For New Entrants and Emerging Players: Mid-scale catering operators in India and Southeast Asia represent the most penetrable entry point given BIS certification barriers that filter out commodity competitors. Home-composting retail channels in German-speaking Europe offer premium positioning where backyard composting rates exceed 40 percent. Lead with TÜV Austria OK compost HOME certified product lines and direct e-commerce fulfillment to bypass established distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated molders with in-house pulp production and multi-continent certification coverage. Long-term viability hinges on positioning ahead of composting infrastructure buildout cycles rather than near-term volume capture. Monitor municipal industrial composting capacity announcements in target markets as the critical inflection signal for certified product value proposition realization.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Transition | California SB 1044 and New York bans force reformulation ahead of compliance deadlines. |
| Backward Integration into Pulp Supply | Captive sugarcane collection networks in Guangxi secure raw material priority during harvest peaks. |
| Home-Composting Certification Acquisition | TÜV Austria OK compost HOME unlocks 20 percent shelf price premiums in German retail. |
| Closed-Loop Collection Partnership | UK waste management pilots with Aramark and Compass Group capture end-of-life value. |
| Thermal Pressing Capacity Expansion | 180°C+ operational equipment from Japanese suppliers faces 12-18 month lead times. |
Methodological Framework
A standing panel of food service procurement directors, molded fiber plant managers, composting facility operators, and regulatory compliance officers provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FDA food-contact substance notifications, ECHA REACH authorization lists, BIS certification registries, and EU Single-Use Plastics Directive implementation trackers. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning product type, end user category, distribution channel, and application use case. CAGRs derived from installed base growth, replacement cycle acceleration, and regulatory mandate timing. Industry-specific forecast inputs included quick-service restaurant chain sustainability mandate rollouts and municipal composting infrastructure development pipelines.
Practitioners should monitor industrial composting capacity buildout announcements, PFAS regulatory expansion timelines, and sugarcane harvest yield volatility for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
PVC-Free Packaging Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market