
 Europe Green Packaging Market | 2026-2036
Europe Green Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Packaging Market Intelligence
Buyer concentration in European retail and quick-service food chains is decoupling from traditional plastic-dependent supply relationships as procurement teams diversify across multiple substrate categories. DS Smith leverages its recycled paperboard network to capture shelf-ready packaging contracts from grocery multiples. Mondi Group anchors its position through integrated kraft paper operations serving e-commerce protective formats. Amcor competes via flexible film innovations that incorporate chemically recycled content for branded consumer goods.
Europe green packaging encompasses materials and formats engineered for reduced environmental burden across full lifecycles, including recycled fiber content exceeding 80 percent in corrugated applications, biodegradable polymers certified to EN 13432 composting standards, and lightweight glass with reduced melting-energy profiles. Its primary commercial purpose is to maintain product protection and shelf appeal while satisfying extended producer responsibility frameworks and circular-economy reporting obligations. Recycled paper and cardboard command the largest volume share as established collection infrastructure and mill capacity create defensible margin pools, while bioplastics represent the fastest-expanding material category as injection-molding compatibility improves for food-contact applications. Food and beverage end users generate the dominant demand pull, though cosmetics brands are accelerating adoption of molded fiber and glass alternatives to meet premium positioning requirements.
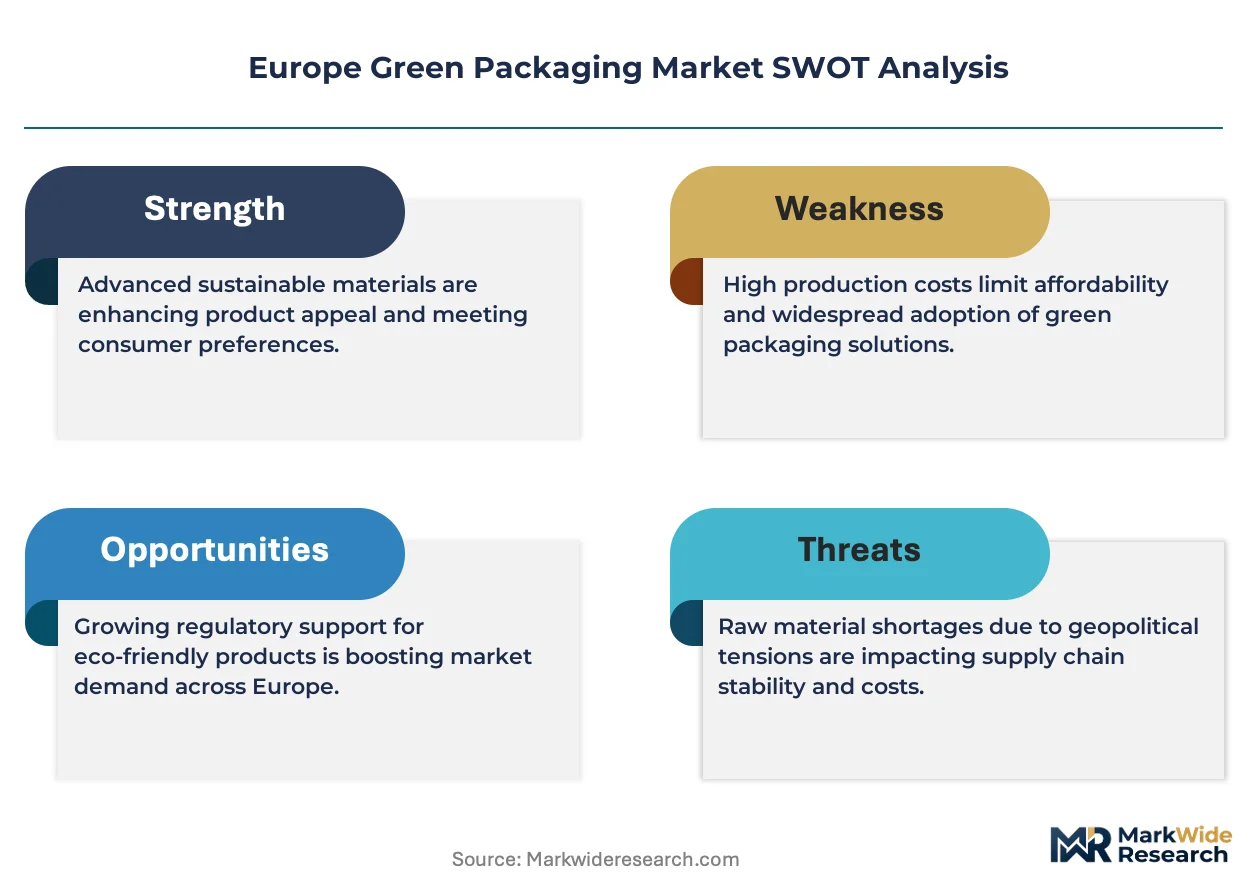
The EU Green Deal and the Packaging and Packaging Waste Regulation are tightening recycled-content mandates and reuse targets, compelling converters to revalidate material specifications and traceability systems. ECHA maintains substance restriction lists affecting additives in food-contact bioplastics, while national implementations of extended producer responsibility schemes across France, Germany, and Italy are recalibrating cost allocation between brand owners and waste managers. Stakeholders must monitor regulatory divergence between EU-level harmonization and member-state gold-plating to avoid compliance fragmentation that could disrupt cross-border packaging supply.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing compliance timelines for recycled-content verification, forcing converters to rebuild traceability systems before 2030 mandates take full effect.
Growth Catalysts
- EU Green Deal mandates:Binding recycled-content floors for plastic packaging create guaranteed offtake for chemically recycled feedstocks. Food-contact applications drive volume commitment.
- German retail procurement:Discounters and supermarket chains are retrofitting private-label supply chains to reusable formats, pulling fiber-based alternatives into high-velocity categories.
- Molded fiber tooling advances:Precision thermoforming of agricultural residues now achieves cosmetic-grade surface finish, unlocking premium cosmetics and electronics segments.
Market Restraints
- Recycled fiber input volatility:Old corrugated container availability fluctuates with e-commerce demand cycles, squeezing margin pools for integrated producers.
- Bioplastic cost structure:PLA and PHA resins trade at multiples of fossil polyethylene, limiting penetration in price-sensitive commodity categories.
- ECHA substance restrictions:Additive approval timelines for food-contact bioplastics extend 18-24 months, delaying product launches.
Strategic Opportunities
- Italian extended producer responsibility:New cost-allocation rules between brand owners and waste managers create service-model openings for packaging-as-a-service platforms.
- E-commerce protective formats:Void-fill and cushioning demand from logistics operators outpaces supply of certified-circular alternatives.
- Glass lightweighting convergence:Reduced-melting-energy profiles combined with refill infrastructure investments open premium beverage repositioning.
Industry Challenges
- Cross-border compliance fragmentation:Member-state gold-plating of EU directives creates divergent labeling and reporting obligations.
- Legacy equipment retrofit:Converting lines designed for conventional plastics require tooling and temperature-control upgrades for bioplastic processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Packaging Market |
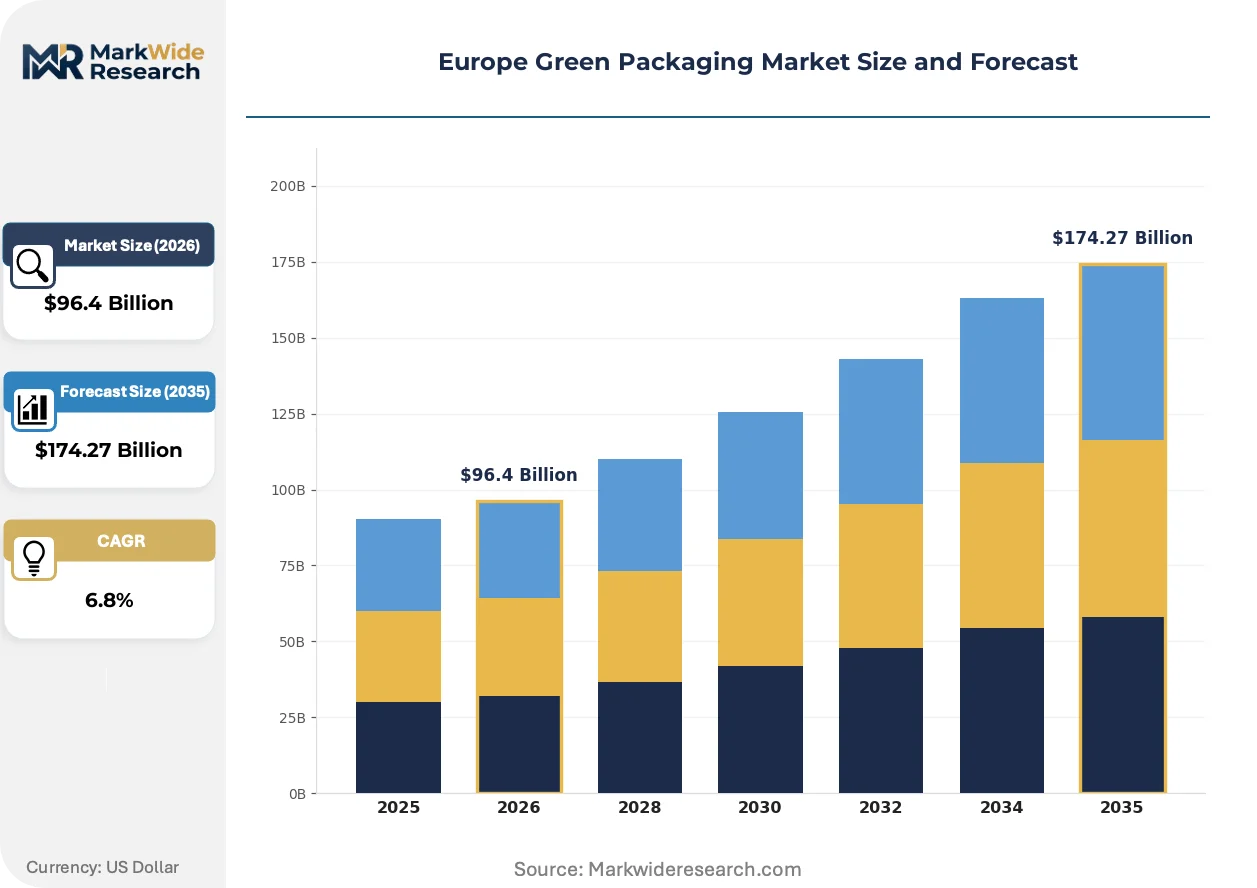
| Market Size in 2026 | $96.4 Billion |
| Market Size in 2035 | $174.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
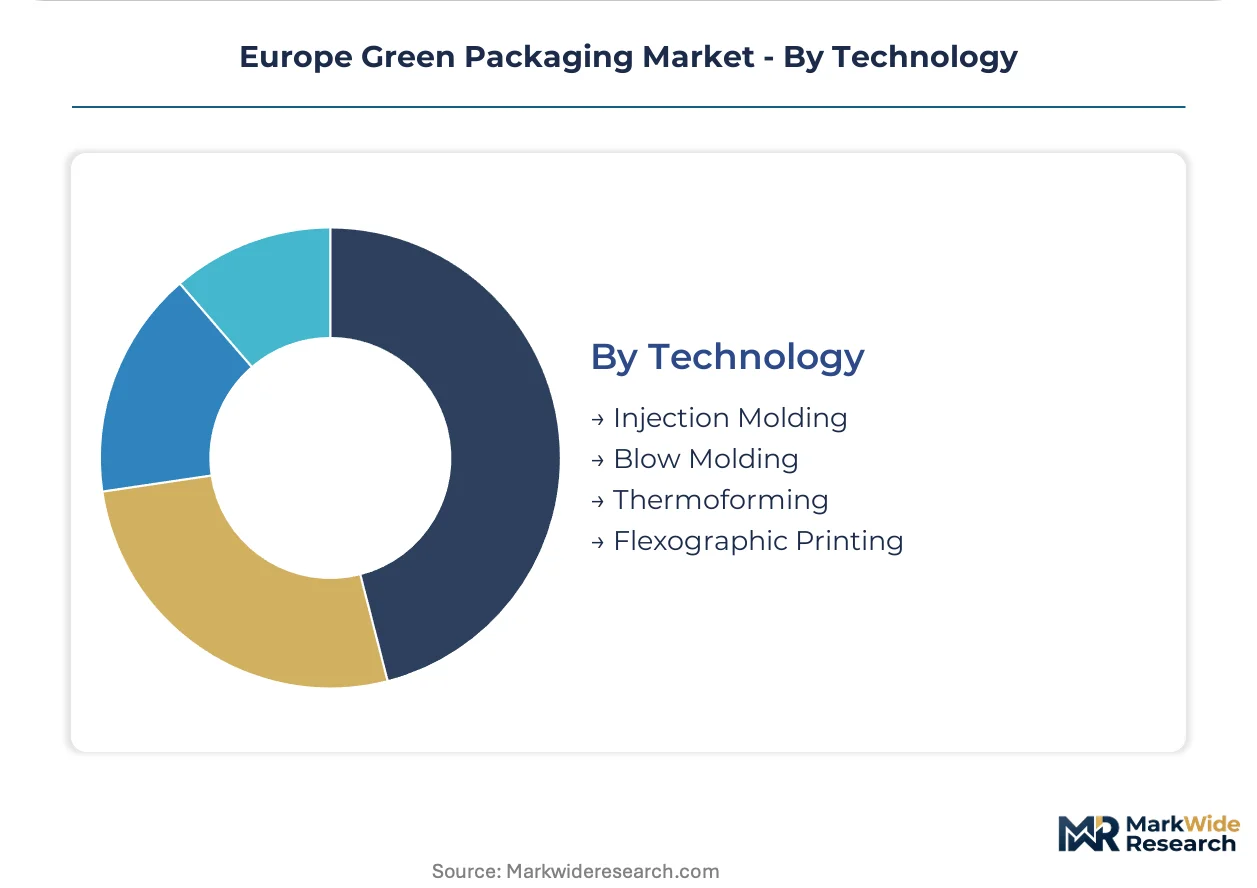
| Segmentation | Material Type: Bioplastics, Recycled Paper, Cardboard, Glass End User: Food & Beverage, Consumer Goods, Healthcare, Cosmetics Application: Retail Packaging, Transportation Packaging, Industrial Packaging, Protective Packaging Technology: Injection Molding, Blow Molding, Thermoforming, Flexographic Printing |
| Companies Covered | DS Smith, Mondi Group, Amcor, Sealed Air Corporation, Ardagh Group, Tetra Laval, DuPont, Ball Corporation, Huhtamaki, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Packaging Market Strategic Shifts & Innovations
Active packaging formats are compressing development cycles as brand owners demand performance verification alongside sustainability credentials. Three forces dominate current investment patterns.
Barrier-coated molded fiber is electrifying protective packaging for temperature-sensitive shipments. Pharmaceutical distributors and meal-kit operators are scaling procurement of cellulose-based insulated containers. This format is electrifying displacement of expanded polystyrene in cold-chain applications where thermal performance and curb-side recyclability must coexist.
REACH substance restriction updates are narrowing the additive palette for food-contact materials. Industrial consequence falls heaviest on bioplastic compounders reformulating colorants and slip agents. French and Italian converters are accelerating pre-registration dossier preparation to maintain market access.
Retail buyers are consolidating supplier relationships around integrated recyclability claims rather than single-attribute certifications. Discounters in Germany and the Netherlands are demanding batch-level traceability data. This pattern is most visible in fresh produce categories where shelf-life extension and circular-economy reporting obligations intersect.
Europe Green Packaging Market Segmentation
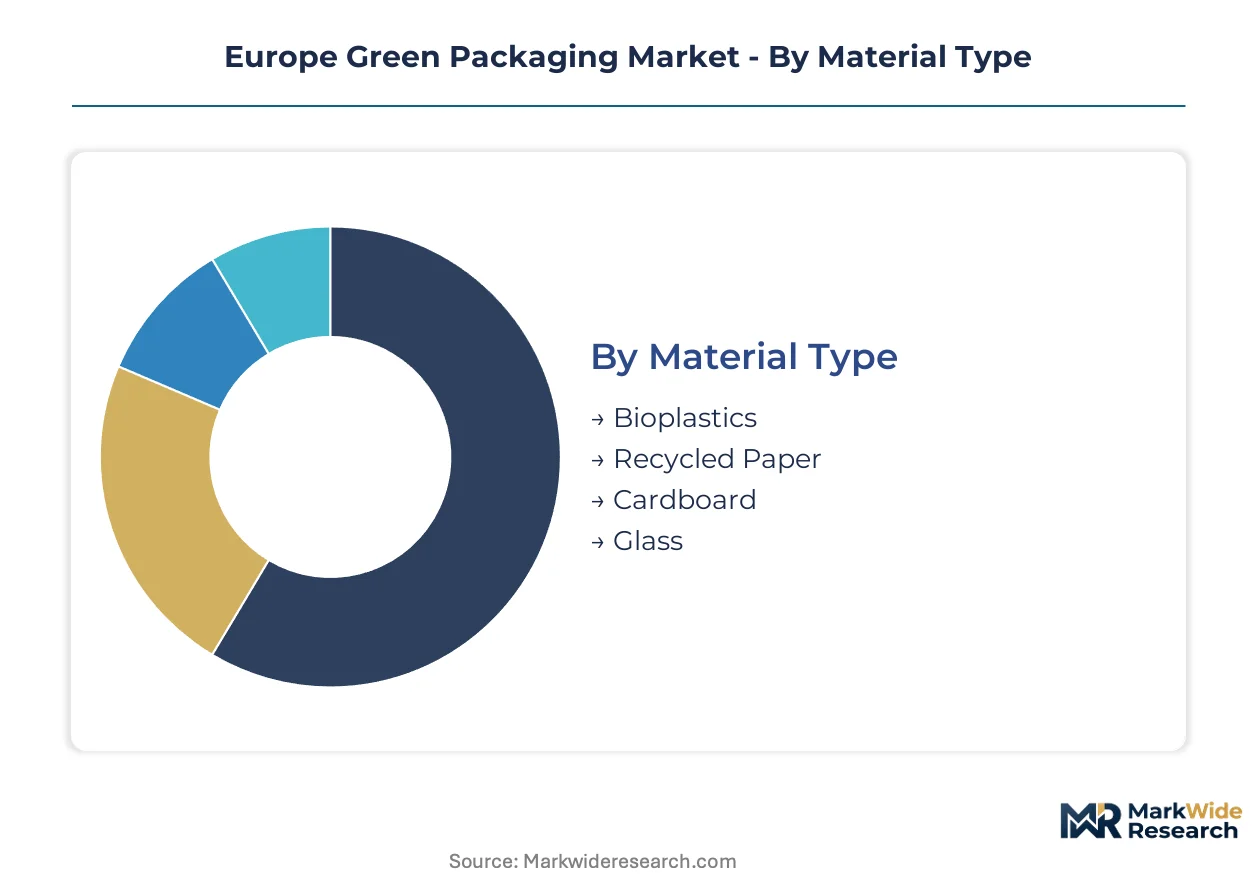
Material specifications and processing technologies determine compliance pathways under EU Green Deal mandates. End-use applications and customer procurement patterns reshape volume allocation across substrate categories.
Material Type:
Recycled fiber content thresholds and composting certification standards define technical positioning across converter portfolios.
- Recycled Paper:Corrugated formats with post-consumer fiber content exceeding 80 percent anchor grocery retail and e-commerce fulfillment. German supermarket chains mandate batch-level traceability for private-label procurement.
- Bioplastics:PLA and PHA polymers certified to EN 13432 composting standards enable food-contact applications with injection-molding compatibility. French and Italian converters face 18-24 month ECHA additive approval timelines that compress product launch windows.
- Cardboard:Lightweight kraft liners serve protective void-fill and shelf-ready display formats for discount retail channels.
- Glass:Reduced-melting-energy profiles combined with refill infrastructure investments reposition premium beverage segments.
Recycled paper leads on scale; bioplastics lead on momentum.
End User:
Extended producer responsibility cost allocation varies sharply across customer procurement sophistication.
- Food & Beverage:Binding recycled-content floors for plastic packaging create guaranteed offtake for chemically recycled feedstocks. Discounters retrofit supply chains for reusable and recyclable formats.
- Cosmetics:Molded fiber tooling advances unlock cosmetic-grade surface finish for premium positioning requirements.
- Consumer Goods:Batch-level traceability demands from Dutch and German retail buyers consolidate supplier relationships around integrated recyclability claims.
- Healthcare:Barrier-coated cellulose formats displace expanded polystyrene in pharmaceutical cold-chain distribution.
Food and beverage commands volume concentration; cosmetics climbs the fastest on sustainability premium capture.
Application:
Logistics operator procurement patterns outpace supply of certified-circular alternatives in protective categories.
- Transportation Packaging:Void-fill and cushioning demand from logistics operators concentrates procurement of fiber-based alternatives.
- Retail Packaging:Shelf-ready corrugated formats with shelf-life extension properties intersect circular-economy reporting obligations in fresh produce.
- Protective Packaging:Temperature-sensitive shipment formats electrify displacement of expanded polystyrene where thermal performance and curb-side recyclability must coexist.
- Industrial Packaging:Heavy-duty kraft applications serve manufacturing supply chains with established collection infrastructure.
Transportation packaging leads on scale; protective packaging leads on momentum.
Technology:
Legacy equipment retrofit requirements and temperature-control upgrades differentiate converter capital deployment.
- Injection Molding:Tooling and temperature-control upgrades enable bioplastic processing for food-contact applications.
- Thermoforming:Precision molding of agricultural residues achieves cosmetic-grade surface finish for electronics and premium cosmetics.
- Flexographic Printing:Water-based ink systems align with REACH substance restriction updates narrowing the additive palette.
- Blow Molding:Lightweight glass formats reduce melting-energy profiles for beverage refill infrastructure.
Injection molding leads on scale; thermoforming leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in green packaging procurement intensity, while Italian converters face steeper extended producer responsibility cost reallocation than their Spanish counterparts.
Germany
Discounters and supermarket chains drive fiber-based packaging procurement for private-label supply chains. The national extended producer responsibility scheme recalibrates cost allocation between brand owners and waste managers. The Rhine-Ruhr industrial corridor hosts converting operations retrofitting lines for reusable format production.
France
Cosmetics brands accelerate molded fiber adoption for premium positioning requirements. ECHA additive approval timelines extend product launch windows for food-contact bioplastics. The Lyon-Grenoble manufacturing cluster concentrates precision thermoforming operations for agricultural residue processing.
Italy
Food-contact bioplastic compounders reformulate colorants and slip agents under REACH restriction updates. National extended producer responsibility implementation creates service-model openings for packaging-as-a-service platforms. The Emilia-Romagna packaging district anchors flexible film and barrier-coated format production.
Netherlands
Retail buyers consolidate supplier relationships around integrated recyclability claims with batch-level traceability demands. Water-based ink systems align with substance restriction updates narrowing the additive palette. The Rotterdam-Antwerp logistics corridor concentrates e-commerce protective packaging distribution.
United Kingdom
Grocery multiples mandate shelf-ready corrugated formats with post-consumer fiber content exceeding thresholds. Divergence between EU harmonization and member-state gold-plating creates compliance complexity for cross-border suppliers. The Midlands manufacturing belt hosts integrated paperboard operations serving discount retail channels.
Europe Green Packaging Market Key Industry Players
British and Nordic producers anchor one tier; Central European specialists hold differentiated positions in fiber-based and flexible formats. The vendor base concentrates around integrated paperboard networks, kraft paper operations, and flexible film innovators. Three archetypes dominate: recycled fiber integrators, bioplastic compounders, and lightweight glass specialists. Competitive moves center on capacity expansion in molded fiber tooling and strategic partnerships for chemical recycling feedstock access.
Within the recycled fiber integrator tier, DS Smith and Mondi Group exemplify geographic anchoring strategies. DS Smith occupies a position tied to British industrial heritage in corrugated networks. Mondi Group represents Central European integration through kraft paper operations. Amcor sits within the flexible film archetype, illustrating how chemical recycling content incorporation reshapes competitive positioning for branded consumer goods applications.
| Leading Market Players |
|---|
| DS Smith |
| Mondi Group |
| Amcor |
| Sealed Air Corporation |
| Ardagh Group |
| Tetra Laval |
| DuPont |
| Ball Corporation |
| Huhtamaki |
| Others |
Cost & Logistics Intelligence
Precision thermoforming of agricultural residues into molded fiber formats simultaneously compresses unit economics for premium cosmetics applications and concentrates tooling ownership among German and Italian equipment specialists. This production-method transition redraws margin pools as converters with captive thermoforming capacity capture pricing power in segments where surface-finish specifications exclude commodity competitors.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for corrugated shelf-ready formats as integrated producers expand post-consumer fiber processing. Three-tier pricing structure across premium, standard, and economy levels separates batch-traceable certified-circular grades from generic recycled content, with cosmetics brands least price-sensitive and discount grocery chains most. Pricing pressure stems from old corrugated container availability swings tied to e-commerce demand cycles. Cost compression in standard-grade fiberboard is intensifying because German retail procurement teams are consolidating supplier relationships around integrated recyclability claims.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor and the Rotterdam-Antwerp logistics belt anchor hub-and-spoke patterns for e-commerce protective packaging fulfillment. Raw material flows draw from Swedish and Finnish pulp operations, German recovered paper collection networks, and Italian bioplastic compounding facilities. Supply chain risk centers on single-source vulnerability for precision thermoforming tooling manufactured by a concentrated base of German equipment builders. Distribution runs through retail-controlled consolidation points where batch-level traceability data gates supplier access to private-label procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation operates as a regulatory compounder, with binding recycled-content mandates for plastic packaging creating guaranteed offtake floors that restructure converter economics regardless of near-term demand fluctuations.
For Market Incumbents: Cement market position by acquiring precision thermoforming capabilities in the Lyon-Grenoble cluster before tooling lead times extend further. Prioritize backward integration into agricultural residue supply contracts to lock in feedstock for cosmetic-grade molded fiber expansion. The threat of ECHA additive approval delays for food-contact bioplastics compresses product launch windows for competitors lacking pre-registered dossier libraries.
For New Entrants and Emerging Players: Enter via packaging-as-a-service platforms targeting Italian extended producer responsibility cost reallocation between brand owners and waste managers. The most penetrable white space sits in temperature-sensitive pharmaceutical distribution where barrier-coated cellulose formats displace expanded polystyrene. A direct go-to-market angle partners with meal-kit operators seeking curb-side recyclable cold-chain insulation.
For Investors and Strategic Acquirers: Roll-up economics work for regional molded fiber specialists because customer consolidation around integrated recyclability claims favors scaled players with batch-traceability infrastructure. Long-term viability hinges on five-to-ten year positioning for refill infrastructure convergence in premium beverages. The signal to watch is German discounter procurement team mandates for reusable format retrofits in private-label supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Feedstock Partnership | Secures offtake for food-contact flexible film applications under EU Green Deal mandates. |
| Precision Thermoforming Capacity Expansion | Captures cosmetic-grade molded fiber demand from premium positioning requirements in France. |
| Packaging-as-a-Service Platform Launch | Exploits Italian extended producer responsibility cost reallocation between brand owners and waste managers. |
| Batch-Level Traceability System Investment | Meets German retail buyer consolidation of supplier relationships around integrated recyclability claims. |
| Lightweight Glass Refill Infrastructure Partnership | Positions for premium beverage repositioning through reduced-melting-energy profiles. |
Research Approach
Bottom-up food and beverage end-use modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with procurement directors at German discount retail chains, sustainability officers at French cosmetics brands, technical directors at Italian flexible film compounders, and logistics operators in the Rotterdam-Antwerp corridor combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation documents, ECHA substance restriction updates, national extended producer responsibility scheme filings, and trade data on old corrugated container flows. Triangulation between these sources anchors volume and value estimates.
Input-output matrices map material type specifications against end-use application requirements and technology processing constraints across the modeling period. Segmentation dimensions include material substrate, end-user industry, application format, and processing technology, with regional regulatory cluster variations captured for Germany, France, Italy, the Netherlands, and the United Kingdom. CAGRs derive from trend extrapolation of procurement pattern shifts and capacity expansion announcements, cross-referenced against EU Green Deal mandate compliance timelines and ECHA additive approval pipeline status.
Inputs from converter production disclosures and retail procurement documentation were available through the study window; gaps in real-time batch-level traceability system deployment rates introduce uncertainty bands around near-term adoption velocity. Forecasts reflect assumptions about regulatory enforcement consistency and chemical recycling feedstock scale-up timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Sustainable Packaging Market