
 GCC Green Packaging Market | 2026-2036
GCC Green Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Green Packaging Market Intelligence
Supermarket private-label sourcing is narrowing as retailers across the Gulf consolidate approved supplier lists for sustainable packaging. Amcor leverages its regional manufacturing footprint to secure multi-year contracts with major retail chains. Tetra Pak International anchors its position through liquid carton recycling infrastructure investments in Dubai and Jeddah. DS Smith competes aggressively in the corrugated segment, specializing in e-commerce-ready box designs that reduce material weight while maintaining structural integrity.
Green packaging encompasses materials and designs engineered to minimize environmental impact through biodegradability, recyclability, or reduced resource intensity, typically incorporating post-consumer recycled content or plant-based polymers with specified degradation timelines under composting conditions. Its primary commercial purpose is to satisfy brand-owner sustainability commitments while meeting product protection requirements across temperature and humidity ranges common to Gulf climates. Bags and containers lead current volume flows, though films represent the fastest-growing product type as snack and convenience food brands convert from conventional multilayer structures. Biodegradable plastics command premium positioning but face margin pressure from scaling recycled paper alternatives, particularly in food service applications where grease resistance specifications are less stringent.
SFDA and SASO frameworks in Saudi Arabia are tightening material safety and biodegradability certification requirements for food-contact packaging, effectively filtering out uncertified imports. The UAE's MOHAP and Emirates Authority for Standardization and Metrology coordinate technical regulations that extend beyond product safety to encompass end-of-life disposal pathways, compelling manufacturers to demonstrate composting or recycling compatibility. Stakeholders must monitor evolving Extended Producer Responsibility proposals across Gulf jurisdictions, as these mechanisms will fundamentally reshape cost allocation between packaging producers, brand owners, and waste management operators.
Market Dynamics
Consolidation among Gulf retailers is compressing supplier margins while SFDA and SASO certification requirements filter out uncertified imports, creating a bifurcated supply base where only capitalized producers survive procurement audits.
Growth Catalysts
- SFDA Biodegradability Mandates:Saudi Arabia's tightening food-contact certification requirements are eliminating low-compliance imports and redirecting procurement toward certified domestic and regional producers.
- E-commerce Expansion:Saudi Arabia's retail and logistics sectors are scaling corrugated and flexible packaging volumes as fulfillment centers demand lighter, stackable, and return-optimized designs.
- Plant-Based Polymers:Polylactic acid and polyhydroxyalkanoate formulations are gaining formulation trials in snack and convenience food applications where moisture barriers are less critical.
Market Restraints
- Petrochemical Feedstock Volatility:Biodegradable resin prices track naphtha and sugarcane ethanol benchmarks, exposing converters to margin compression when oil prices diverge from agricultural commodity cycles.
- Composting Infrastructure Gaps:The UAE and Saudi Arabia lack industrial composting capacity at scale, rendering biodegradability claims functionally unverifiable and limiting end-of-life value proposition.
- Multilayer Film Substitution:Conventional polyethylene terephthalate and polypropylene laminates retain cost and barrier-performance advantages in liquid dairy and meat packaging segments.
Strategic Opportunities
- Kuwait and Oman Penetration:These markets exhibit lower private-label consolidation and weaker local production capacity, creating first-mover advantages for certified regional suppliers.
- Extended Producer Responsibility Frameworks:Draft EPR legislation across Gulf jurisdictions will shift collection and recycling costs to producers, rewarding vertically integrated players with captive waste-management assets.
- Digital Printing Convergence:Combination of water-based inks and short-run flexographic presses enables hyper-localized SKUs for seasonal promotions without plate-changeover penalties.
Industry Challenges
- Halal Certification Complexity:Food-contact materials require dual verification of ingredient permissibility and production line segregation, extending product development timelines by four to six months.
- Legacy Equipment Retrofit Costs:Converting extrusion lines from conventional to bio-based resins demands screw and die modifications that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Green Packaging Market |
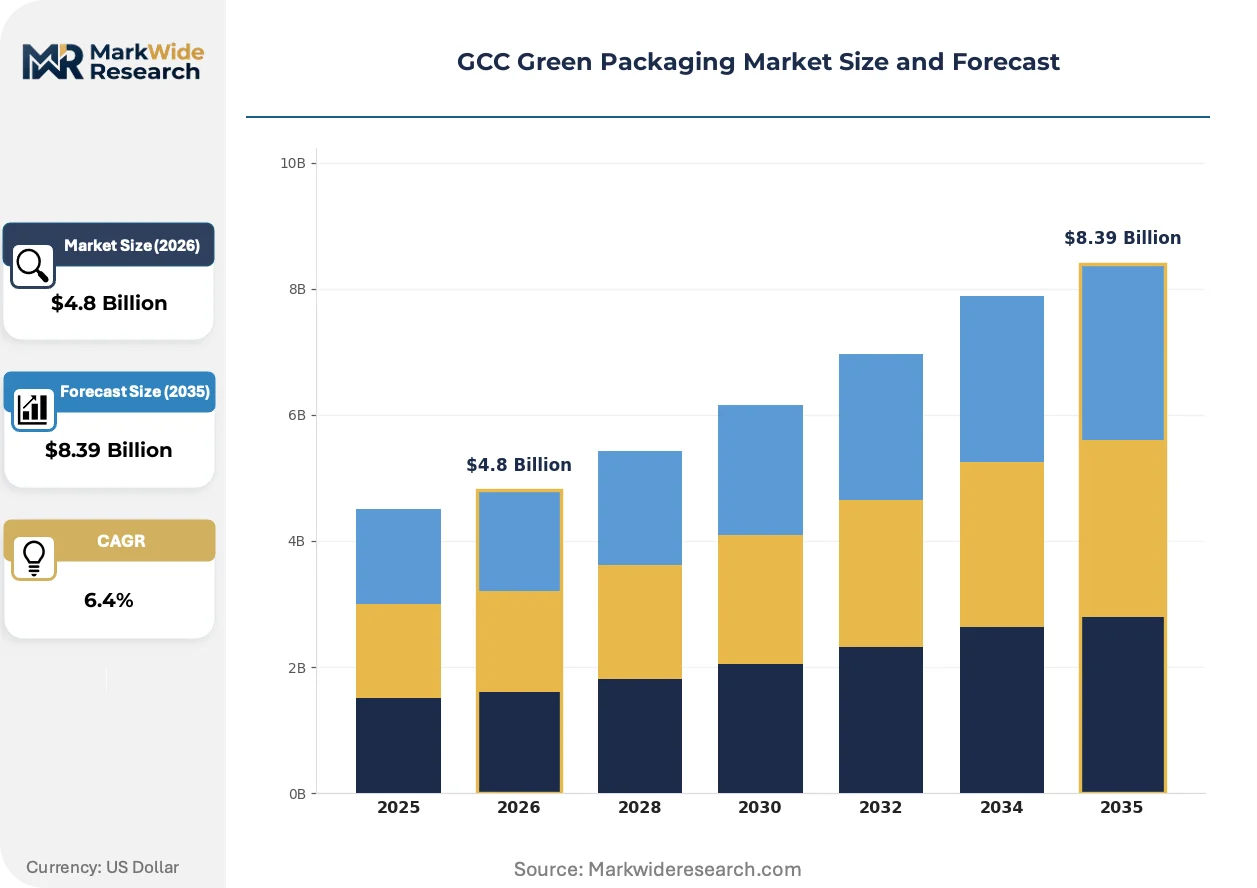
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Containers, Films, Boxes Material: Biodegradable Plastics, Recycled Paper, Plant-Based Materials, Metal Application: Food Packaging, Personal Care, Electronics, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, B2B Vendors |
| Companies Covered | Evergreen Packaging, Tetra Pak International, Amcor, Ball Corporation, Crown Holdings, Mondi Group, Ardagh Group, Sonoco Products Company, DS Smith, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Green Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory stringency are compressing acceptable performance-cost windows, forcing simultaneous innovation in barrier chemistry, end-of-life design, and supply chain transparency.
Mono-material polyethylene structures are collapsing the multilayer flexible packaging paradigm by satisfying mechanical recycling stream requirements without sacrificing heat-seal integrity. Snack food brands in the UAE are accelerating adoption as retailer sustainability scorecards penalize non-recyclable laminates. This shift is collapsing the addressable market for ethylene vinyl alcohol and polyamide barrier layers that previously dominated shelf-life extension.
SFDA and SASO harmonization on biodegradability testing protocols is eliminating regulatory arbitrage between Saudi Arabia and neighboring markets. Industrial converters must now submit to standardized composting simulations and heavy-metal threshold verification, raising compliance costs uniformly. Food service disposables and agricultural mulch films face the steepest certification burden as these categories lack established recycling infrastructure.
Private-label sustainability scorecards are reshaping retailer-procurement relationships across Dubai and Riyadh. Major chains now mandate supplier disclosure of recycled content percentages and carbon footprint estimates, replacing price-only tender evaluations. This behavioral shift is most pronounced in fresh produce and bakery categories where consumer-facing packaging carries visible sustainability claims.
GCC Green Packaging Market Segmentation
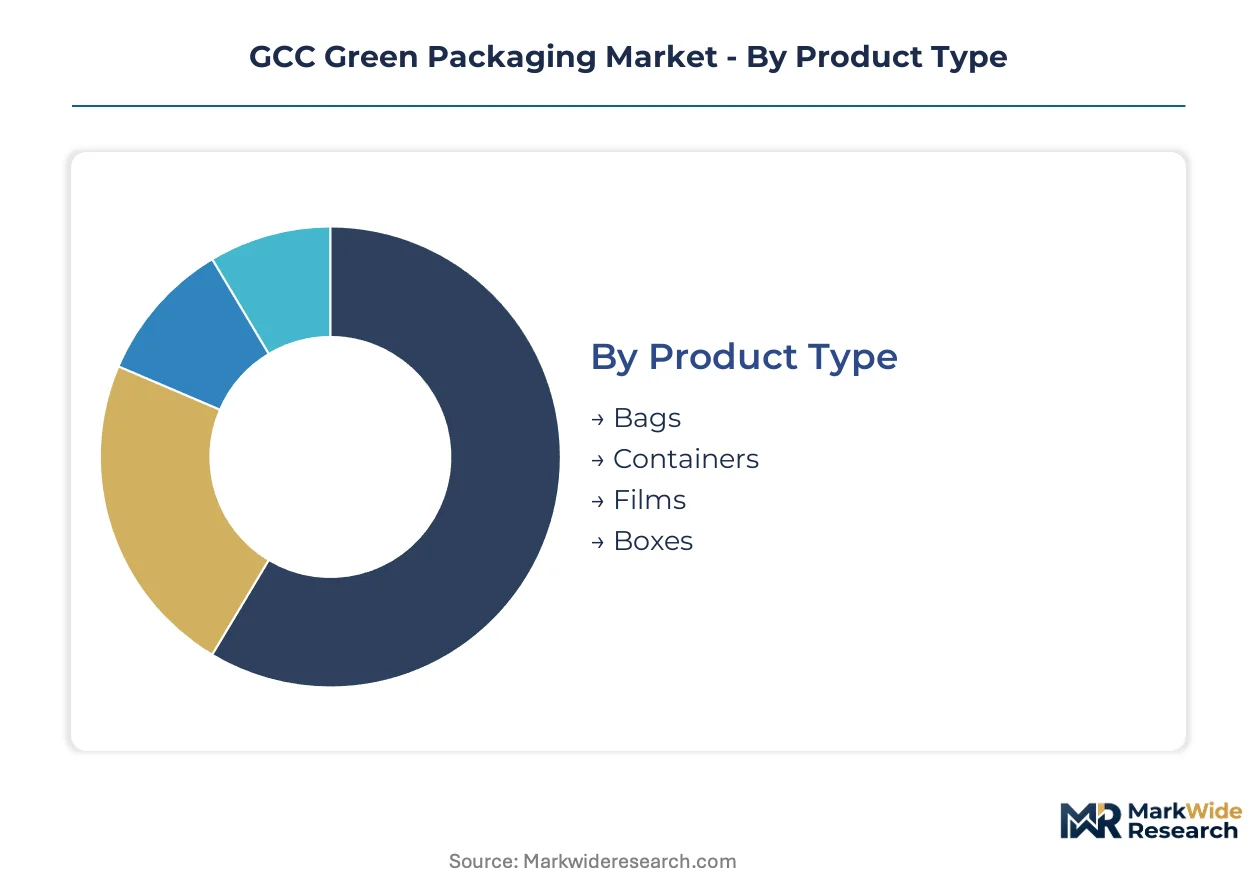
Packaging converters across the Gulf must align production capabilities with four intersecting dimensions: physical form, feedstock origin, end-use performance requirements, and channel-specific logistics. Procurement decisions in this market cascade through these layers, with SFDA certification requirements filtering options at each stage.
Product Type:
Volume concentration across physical formats reveals where material substitution delivers immediate compliance value versus where technical barriers persist.
- Bags:Polyethylene and paper-based carry bags dominate grocery and retail checkout applications. Saudi supermarket chains are consolidating approved supplier lists around certified compostable and recycled-content alternatives as private-label sustainability scorecards harden procurement criteria.
- Films:Mono-material polyethylene structures are displacing multilayer laminates in snack food packaging across UAE retail networks. Moisture barrier limitations constrain penetration in liquid dairy segments where conventional polyethylene terephthalate retains performance advantages.
- Containers:Rigid formats serve prepared meals and fresh produce categories with modified atmosphere requirements.
- Boxes:Corrugated designs optimized for e-commerce fulfillment centers emphasize stackability and return logistics over pure material substitution.
Bags command the established base. The steepest expansion runs through films.
Material:
Feedstock selection determines compliance pathway, cost structure, and end-of-life verifiability across Gulf jurisdictions with divergent waste infrastructure.
- Biodegradable Plastics:Polylactic acid and polyhydroxyalkanoate formulations carry premium positioning in food service disposables. Industrial composting capacity gaps in Saudi Arabia and the UAE render biodegradability claims functionally unverifiable, limiting value proposition despite regulatory enthusiasm.
- Recycled Paper:Post-consumer fiber alternatives are gaining share in food service and bakery applications where grease resistance specifications are less stringent than in liquid packaging. Saudi corrugated converters are scaling capacity to capture e-commerce demand.
- Plant-Based Materials:Bagasse and molded fiber formats serve hot beverage and takeaway food segments with visible sustainability positioning.
- Metal:Aluminum and tinplate retain dominance in aerosol and premium food segments where barrier performance and infinite recyclability offset weight penalties.
Recycled paper captures the volume base. Biodegradable plastics face the steepest climb.
Application:
End-use performance requirements create divergent technical barriers, with food-contact certification burdening some segments while electronics and personal care tolerate wider material experimentation.
- Food Packaging:SFDA and SASO frameworks mandate dual verification of ingredient permissibility and production line segregation, extending product development timelines. Fresh produce and bakery categories face visible sustainability claims pressure from retailer scorecards.
- Personal Care:Cosmetic and hygiene brands prioritize aesthetic finish and shelf presence over end-of-life pathways, enabling wider bio-based resin experimentation where moisture barriers are non-critical.
- Electronics:Protective formats emphasize anti-static and cushioning performance with less regulatory scrutiny of material origin.
- Pharmaceuticals:MOHAP and Emirates Authority for Standardization and Metrology requirements extend beyond product safety to encompass disposal pathway documentation.
Food packaging anchors procurement volume. Personal care permits the widest material experimentation.
Distribution Channel:
Channel structure determines order economics, customization requirements, and sustainability verification depth, with B2B and online retail imposing divergent technical specifications.
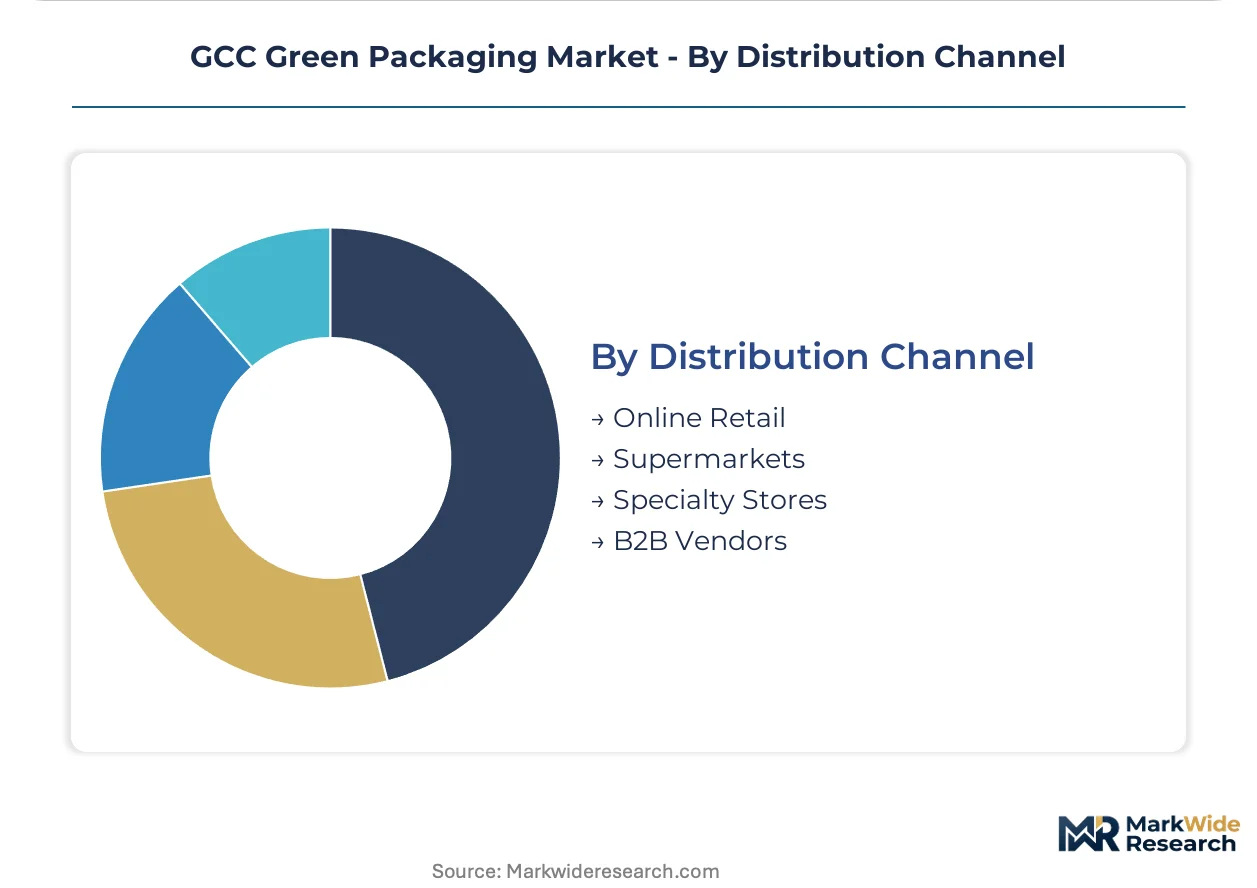
- Supermarkets:Private-label consolidation across Dubai and Riyadh is compressing approved supplier lists and mandating recycled content disclosure. Major chains now require carbon footprint estimates alongside price tenders.
- B2B Vendors:Industrial procurement from food manufacturers and logistics operators emphasizes volume scale and specification consistency over visible sustainability claims.
- Online Retail:Direct-to-consumer fulfillment demands lighter, return-optimized designs with shorter print runs enabled by digital flexographic convergence.
- Specialty Stores:Premium positioning in organic and gourmet segments tolerates higher material costs for visible eco-credentials.
Supermarkets concentrate procurement leverage. Online retail imposes the most demanding logistics specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's container throughput capacity underwrites the UAE's position as the Gulf's primary packaging import gateway, with direct feeder connections to Saudi Arabia's King Abdulaziz Port and Oman's Sohar Port creating a consolidated maritime corridor for sustainable materials distribution.
Saudi Arabia
Riyadh's retail consolidation drives corrugated and flexible packaging procurement at scale, with the Saudi Food and Drug Authority mandating biodegradability certification timelines that filter uncertified imports. The Eastern Province's Jubail Industrial City hosts expanding converter capacity targeting e-commerce fulfillment demand from Jeddah and Riyadh distribution hubs.
United Arab Emirates
Dubai's Jebel Ali Free Zone concentration of liquid carton recycling infrastructure anchors Tetra Pak's regional circular economy investments, while MOHAP coordinates technical regulations extending to composting pathway verification. Abu Dhabi's Khalifa Industrial Zone attracts post-consumer recycled fiber processors serving Emirates retailer sustainability scorecards.
Kuwait
Kuwait City's underdeveloped local production capacity creates first-mover openings for certified regional suppliers, with the Public Authority for Industry drafting packaging material standards that mirror SASO frameworks. The Shuwaikh Industrial Area lacks industrial composting infrastructure, limiting biodegradable plastics penetration despite regulatory enthusiasm.
Oman
Salalah Port's transshipment hub status positions the Sultanate as a secondary entry point for green packaging materials serving Yemen and East African markets, with the Ministry of Commerce, Industry and Investment Promotion reviewing extended producer responsibility mechanisms. Sohar's aluminum smelter complex supports premium beverage can demand from Muscat's retail expansion.
Qatar
Doha's FIFA World Cup legacy infrastructure sustains food service disposable demand from hospitality and catering sectors, with the Qatar General Organization for Standardization implementing food-contact material safety protocols. Ras Laffan's industrial city hosts limited converter presence, relying on Saudi and UAE supply chains for certified sustainable packaging.
GCC Green Packaging Market Key Industry Players
On the supply side, the industry is consolidating around capitalized multinationals with regional manufacturing footprints, as SFDA and SASO certification requirements eliminate low-compliance competitors and compress approved supplier lists for Gulf retailers. Three strategic archetypes dominate: integrated material-science conglomerates with captive resin production, specialized corrugated converters optimizing e-commerce logistics specifications, and liquid packaging system providers with recycling infrastructure lock-in. Competitive dynamics center on multi-year contract anchoring with retail chains and backward integration into post-consumer waste collection networks.
Within the integrated packaging tier, Amcor and Tetra Pak International exemplify divergent scale strategies. Amcor leverages its regional manufacturing presence to secure supermarket private-label contracts through volume consistency and carbon footprint disclosure capabilities. Tetra Pak International anchors its position through recycling infrastructure investments in Dubai and Jeddah, creating circular economy verification that satisfies retailer sustainability scorecards. DS Smith occupies a specialized position in corrugated optimization, with e-commerce-ready designs reducing material weight while maintaining structural integrity for Saudi fulfillment center specifications.
| Leading Market Players |
|---|
| Evergreen Packaging |
| Tetra Pak International |
| Amcor |
| Ball Corporation |
| Crown Holdings |
| Mondi Group |
| Ardagh Group |
| Sonoco Products Company |
| DS Smith |
| Others |
Cost & Logistics Intelligence
SFDA certification chokepoints determine both pricing tier spreads and supply chain shape across the Gulf, as uncertified imports face exclusion while approved suppliers capture procurement leverage with consolidating retailers. Biodegradable resin price volatility against recycled paper alternatives further compresses margin structures for converters lacking backward integration into feedstock sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract negotiations, with SFDA-certified biodegradable plastics commanding substantial premiums over recycled paper alternatives. Price differentiation rests on certification grade and volume scale, with supermarket private-label consolidation intensifying cost compression in the standard tier. Pricing pressure stems from retailer sustainability scorecards mandating carbon footprint disclosure alongside unit economics. Small-format food service operators exhibit highest price sensitivity, while multinational FMCG brands tolerate premium positioning for visible compliance credentials.
Supply Chain Analysis
Contract manufacturing concentration sits with Amcor's regional facilities, Tetra Pak's Jeddah and Dubai recycling infrastructure, and DS Smith's corrugated optimization centers. Geographic supply concentration draws from Saudi Arabia's Jubail Industrial City, UAE's Jebel Ali Free Zone, and India's post-consumer fiber processors. Raw material dependencies hinge on naphtha-derived resins, sugarcane ethanol feedstocks, and imported post-consumer paper pulp. Single-source vulnerability runs through Jebel Ali Port's container throughput capacity as the Gulf's primary packaging import gateway. Distribution runs through maritime feeder connections linking King Abdulaziz Port and Sohar Port.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating across Saudi Arabia and UAE supermarket chains as private-label consolidation compresses approved supplier lists from dozens to single-digit rosters. This structural shift rewards capitalized producers with certification depth while marginalizing mid-cap converters.
For Market Incumbents: Entrench procurement relationships through multi-year carbon footprint disclosure commitments and captive recycling infrastructure investments. SFDA harmonization with SASO protocols threatens regulatory arbitrage strategies, making backward integration into post-consumer waste collection networks the critical defensive lever against margin compression. For New Entrants and Emerging Players: Kuwait's underdeveloped local production capacity and Oman's transshipment hub status represent the most penetrable entry points for certified regional suppliers. First-mover positioning in industrial composting equipment partnerships addresses infrastructure gaps that limit biodegradable plastics penetration. Digital printing convergence for hyper-localized seasonal SKUs offers a differentiated go-to-market angle against volume-anchored incumbents. For Investors and Strategic Acquirers: The market sits at a regulatory enforcement phase that favors vertically integrated players with captive waste-management assets. Long-term viability over the coming decade hinges on Extended Producer Responsibility framework positioning. Acquisition targets should demonstrate recycling infrastructure lock-in or e-commerce logistics optimization capabilities. The signal to watch is draft EPR legislation progression across Gulf jurisdictions as cost allocation inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Investment | Secures procurement eligibility as Saudi Arabia eliminates uncertified imports from approved supplier lists. |
| Recycling Infrastructure Buildout | Tetra Pak's Dubai and Jeddah investments create circular economy verification satisfying retailer scorecards. |
| Mono-material Film Conversion | DS Smith and Amcor displacement of multilayer laminates aligns with mechanical recycling stream requirements. |
| E-commerce Logistics Optimization | Corrugated designs reducing material weight while maintaining stackability capture Saudi fulfillment center demand. |
| Extended Producer Responsibility Positioning | Vertical integration into post-consumer collection networks rewards players as Gulf jurisdictions shift cost allocation. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs records, SFDA regulatory filings, and retailer sustainability disclosure reports across the analysis window. Packaging converter executives, supermarket category buyers, and waste management operators provided operational perspective. Secondary validation drew from SASO technical standards documentation, MOHAP regulatory circulars, and maritime trade flow databases. Bottom-up capacity assessments triangulated against top-down demand modeling from retail expansion trajectories.
Forecast inputs span product type segmentation, material feedstock origin, application performance requirements, and channel-specific logistics configurations. Modeled dimensions include biodegradable versus recycled content tiers, food-contact certification status, and e-commerce fulfillment specifications. CAGRs were derived from volume trajectory analysis against regulatory mandate implementation timelines. Industry-specific inputs incorporated petrochemical feedstock price correlation patterns and industrial composting capacity development schedules.
Practitioners should monitor SFDA enforcement intensity, retailer sustainability scorecard evolution, and EPR legislative progression for early signals of forecast revision. Assumptions reflect current regulatory trajectories and infrastructure investment commitments. Quarterly review of certification approval rates, Jebel Ali Port throughput fluctuations, and supermarket private-label consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
North America Eco-Friendly Packaging Market