
 Sustainable Footwear Market | 2026-2036
Sustainable Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Footwear Market Intelligence
The athlete segment's performance needs are decoupling from traditional, petroleum-based material dependencies, creating new market dynamics. This shift opens opportunities for both specialized and incumbent brands. Allbirds leverages its direct-to-consumer model and material innovation to build a strong brand identity. New Balance competes by incorporating recycled content into its established, high-volume athletic shoe lines. Cariuma specializes in casual footwear using ethically sourced materials like organic cotton, targeting a specific lifestyle demographic.
Sustainable footwear refers to shoes manufactured using environmentally low-impact materials and processes, such as recycled rubber or organic cotton. Its purpose is to offer consumers an alternative that reduces the ecological footprint of conventional footwear production. Material selection is critical, with bamboo fiber representing a fast-growing category due to its rapid regeneration and minimal water requirements. In terms of production, upcycled materials are increasingly used by premium price tier brands to create unique value propositions.
Regulatory frameworks are standardizing sustainability claims and increasing transparency. The European Union’s Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure on environmental impacts for large companies. In the United States, the FTC's Green Guides police against deceptive marketing, compelling brands to substantiate claims like "eco-friendly." Future competitive advantage will hinge on a brand's ability to provide transparent, verifiable data on material sourcing and end-of-life product circularity.
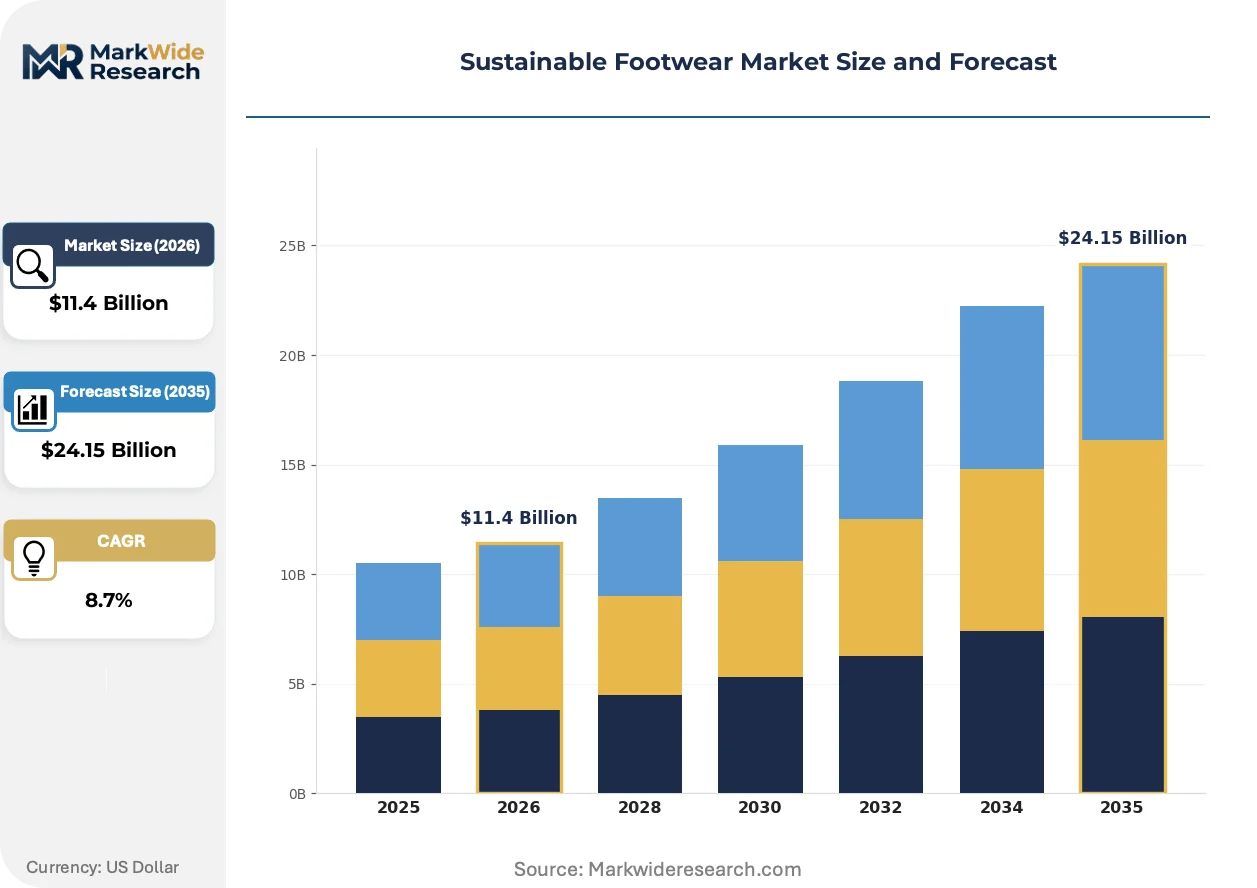
Market Dynamics
The convergence of stringent regulatory disclosure mandates, such as the EU's CSRD, and advanced material science is the central force shaping the market. This creates a new competitive basis where verifiable sustainability data is as critical as product performance.
Growth Catalysts
- Regulatory Mandates:The European Union's Corporate Sustainability Reporting Directive (CSRD) compels large companies to provide detailed, audited data on environmental impact, making sustainable sourcing a compliance necessity.
- Material Innovation:The development of high-performance, renewable materials like bamboo fiber and algae-based foams provides viable alternatives to petroleum-based plastics, attracting environmentally-conscious athletes.
- Consumer Preference:In developed economies like Germany and the United States, a growing cohort of consumers actively seeks and is willing to pay a premium for footwear with transparent and ethical supply chains.
Market Restraints
- Cost Structure:Certified organic cotton and recycled rubber command a significant price premium over conventional virgin materials, impacting final product pricing and limiting mass-market affordability.
- Performance Parity:Certain bio-based materials have yet to achieve the same level of durability, water resistance, and lightweight properties as high-performance synthetic polymers used in elite athletic footwear.
- Supply Chain Immaturity:The supply chains for novel materials, such as those derived from mycelium or pineapple leaf fiber, are often fragmented, geographically concentrated, and lack the scale to support high-volume production.
Strategic Opportunities
- Circular Business Models:Implementing brand-managed take-back programs for repair, refurbishment, and end-of-life recycling opens new revenue streams and enhances customer loyalty beyond the initial point of sale.
- Geographic Expansion:There is significant potential in Asia-Pacific's emerging economies, where a rising middle class with increasing disposable income is beginning to prioritize sustainable consumption patterns.
- Technology Convergence:Combining bio-based filaments with additive manufacturing (3D printing) enables on-demand production of customized, low-waste footwear components, reducing inventory risk and material scrap.
Industry Challenges
- Greenwashing Verification:Differentiating genuine sustainability efforts from deceptive marketing ("greenwashing") remains a significant hurdle, eroding consumer trust and requiring robust third-party certification which can be costly and slow.
- Production Scalability:Transitioning from pilot-scale production of innovative materials to the mass-volume outputs required by major footwear brands presents considerable capital investment and technical process engineering challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Footwear Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Recycled Rubber, Organic Cotton, Eco-friendly Leather, Bamboo Fiber Production Method: Handmade, 3D Printing, Zero Waste, Upcycled Materials End User: Men, Women, Children, Athletes Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Cariuma, Thousand Fell, Allbirds, New Balance, Saola, Veja, Nisolo, Puma, Rothy's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Footwear Market Strategic Shifts & Innovations
Data-driven transparency is reshaping the basis of competition. The ability to provide verifiable, granular proof of a product's lifecycle impact, from raw material sourcing to end-of-life circularity, is becoming a non-negotiable consumer and regulatory expectation.
Bio-fabrication, using organisms like mycelium to grow leather-like materials, offers a low-carbon alternative to animal and synthetic hides. This technology is being adopted primarily by niche and luxury brands seeking to differentiate on material novelty and ethical sourcing. Now, this material science is expanding into the performance footwear category, challenging the long-standing dominance of petroleum-derived textiles.
The Federal Trade Commission's (FTC) Green Guides in the United States provide an enforceable framework against deceptive environmental marketing claims. This regulation requires companies to possess reliable scientific evidence to back up terms like "eco-friendly" or "compostable." The lifestyle and casual footwear segments, which frequently use such branding, are most affected, pushing them toward more rigorous certification and substantiated claims.
A consumer-led shift toward circularity is disrupting the traditional linear model of footwear consumption. This change is creating demand for brand-operated resale, repair, and take-back programs, which function as new customer engagement channels. The trend is most pronounced in European markets like Germany and France, especially among younger, urban consumer demographics.
Sustainable Footwear Market Segmentation
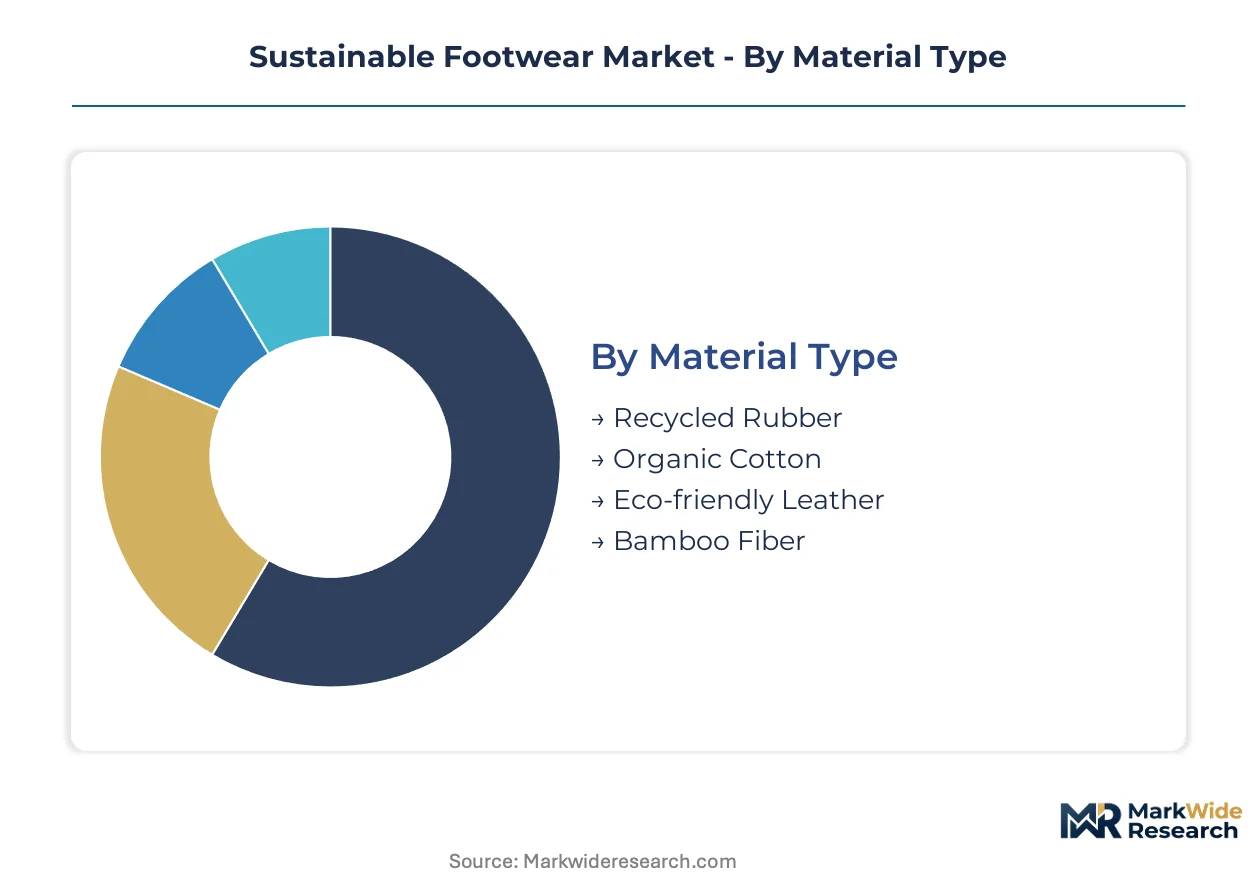
The sustainable footwear market's distinct segments reflect diverse consumer values and technological advancements. Understanding these classifications is essential for brands to effectively tailor product development and market strategies. This segmentation analysis highlights key areas of growth and competitive differentiation across the industry.
Material Type:
Supply chain development for sustainable footwear materials is concentrating on renewable and recycled feedstocks, which dictates material availability and adoption rates across manufacturers.
- Bamboo Fiber:This natural cellulose fiber offers rapid regeneration and minimal water requirements during cultivation, making it a highly sustainable textile. Demand is concentrating in performance athletic footwear, driven by consumer preference for lightweight, breathable, and environmentally responsible materials.
- Recycled Rubber:Composed of reclaimed rubber from tires or industrial waste, this material provides durable and slip-resistant outsoles for sustainable shoes. Demand is strong in the utility and casual footwear segments, supported by its cost-effectiveness and proven performance.
- Organic Cotton:Cultivated without synthetic pesticides or fertilizers, organic cotton offers a soft and breathable textile for shoe uppers and linings.
- Eco-friendly Leather:This category includes chrome-free tanned leather or plant-based alternatives, reducing the environmental impact of traditional leather production.
Today's leader: Recycled Rubber. Tomorrow's challenger: Bamboo Fiber.
Production Method:
Advanced production methods are enabling novel designs and reduced waste, directly influencing product innovation and manufacturing efficiency across the sustainable footwear sector.
- 3D Printing:This additive manufacturing technique constructs footwear components layer by layer, allowing for complex geometries and on-demand customization. Demand for 3D printed components is expanding in high-performance athletic footwear, driven by the ability to optimize structural integrity and minimize material scrap.
- Upcycled Materials:This method transforms discarded items like ocean plastics or textile waste into new footwear components, adding unique aesthetic and ethical value. Demand is strong in the premium and luxury segments, where brands differentiate through material novelty and circular economy principles.
- Handmade:Artisanal production techniques emphasize craftsmanship and often utilize locally sourced, natural materials, appealing to niche consumer preferences.
- Zero Waste:This approach designs products and processes to eliminate material waste throughout the entire production lifecycle, minimizing environmental impact.
3D Printing represents the fastest-growing trajectory in production innovation.
End User:
Specific end-user demographics exhibit distinct purchasing behaviors and product requirements, influencing design priorities and market volume for sustainable footwear brands.
- Athletes:This segment requires high-performance footwear that balances durability, support, and environmental responsibility, especially for running and training. Demand is significant in developed economies like the United States and Germany, where consumers prioritize both athletic performance and ecological impact.
- Women:This broad consumer group seeks sustainable footwear across various styles, from casual sneakers to formal options, often prioritizing aesthetic appeal and ethical sourcing. Demand is robust across all regions, reflecting a strong preference for fashion-forward and environmentally conscious choices.
- Men:Male consumers seek durable and versatile sustainable footwear for everyday wear and specific activities, valuing both comfort and environmental attributes.
- Children:This segment focuses on safe, non-toxic, and durable sustainable footwear for growing feet, with parents often prioritizing health and environmental considerations.
The Athlete segment exhibits the steepest expansion trajectory due to its performance-driven sustainability demands.
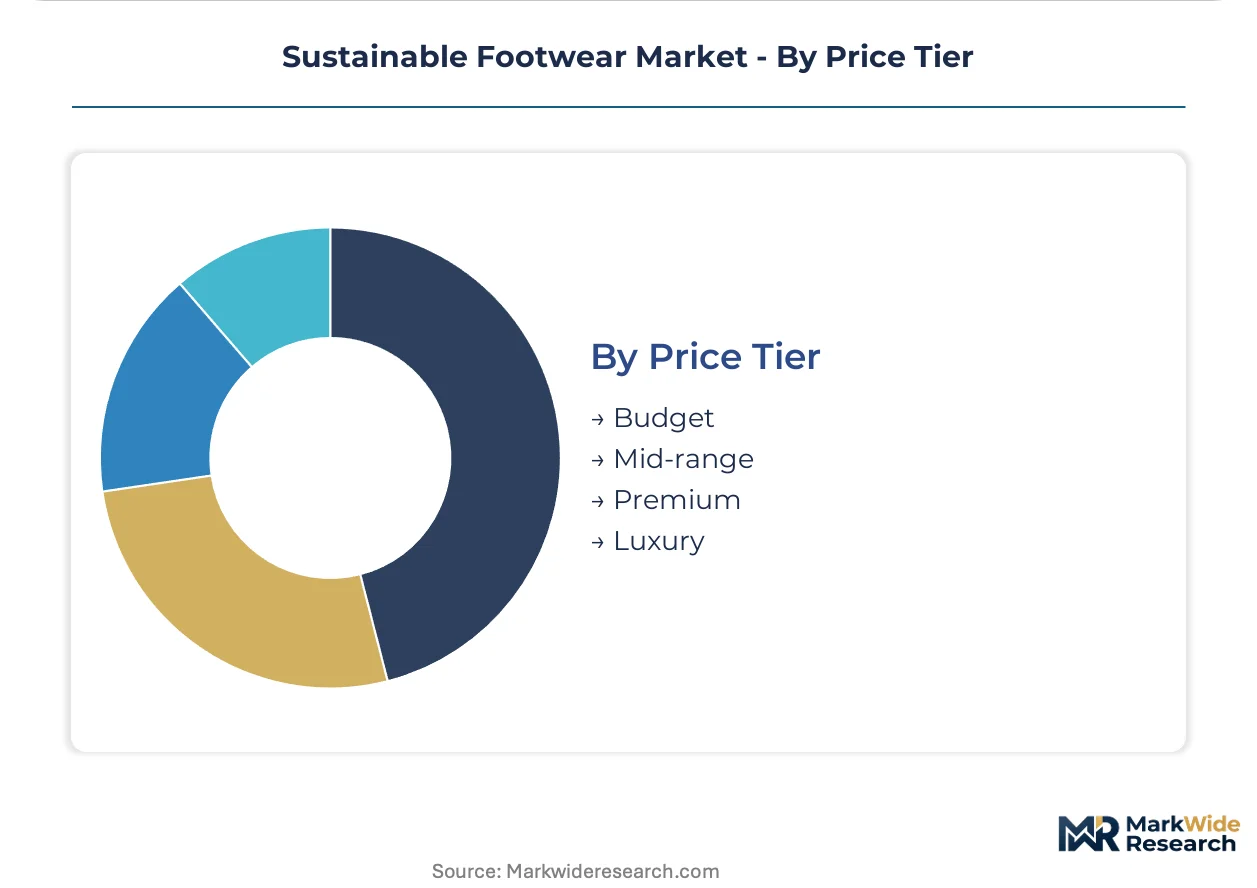
Price Tier:
Different price tiers reflect varying material costs, production complexities, and brand positioning, directly impacting profit margins and market accessibility within the sustainable footwear industry.
- Premium:Footwear in this tier utilizes advanced sustainable materials and innovative production methods, justifying higher price points through enhanced performance and ethical credentials. Demand is robust in European markets, where consumers are willing to invest in high-quality, transparently sourced products.
- Mid-range:This tier balances affordability with sustainable attributes, offering accessible options that incorporate recycled content or organic materials. Demand is widespread across developed economies, appealing to a broad base of environmentally aware consumers.
- Budget:This segment focuses on offering sustainable footwear at lower price points, often achieved through scaling production of basic recycled materials.
- Luxury:Exclusive designs, rare sustainable materials, and bespoke craftsmanship define this tier, targeting affluent consumers seeking unique, high-end ecological options.
The Premium tier is gaining share fastest as consumers increasingly prioritize verifiable sustainability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between regions influences sustainable footwear production, with stricter environmental mandates in developed markets potentially shifting manufacturing to regions with less stringent oversight. This dynamic creates a cost-of-compliance gap, impacting sourcing strategies for brands globally and reshaping market entry points.
United States
Demand for performance-oriented sustainable athletic footwear is significant among environmentally conscious consumers in the United States. The FTC's Green Guides enforce truthfulness in "eco-friendly" claims, requiring brands to substantiate all environmental benefits with reliable scientific evidence. California's advanced manufacturing hubs, particularly around Los Angeles, actively explore bio-based material integration for footwear production.
Germany
Consumers in Germany prioritize verifiable sustainability and ethical supply chains, driving demand for premium sustainable footwear across all segments. The EU's Corporate Sustainability Reporting Directive (CSRD) mandates extensive environmental impact disclosures for large companies operating within the Union. The Pirmasens footwear cluster focuses on material innovation and circular design principles for a competitive edge.
China
Rising middle-class disposable income in China fuels demand for sustainable casual footwear, particularly those emphasizing transparent material sourcing. The nation's dual carbon goals push industries towards greener manufacturing processes, including sustainable footwear production. Shenzhen's industrial parks are developing specialized facilities for recycled material processing and footwear component manufacturing.
India
India's growing urban population seeks affordable and durable sustainable footwear options, often prioritizing natural fiber use and local production. The Bureau of Indian Standards (BIS) develops guidelines for eco-labeling, influencing material selection and production methods for domestic brands. The leather goods cluster in Kanpur increasingly adopts chrome-free tanning techniques for sustainable alternatives.
Sustainable Footwear Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with established athletic brands leveraging existing supply chains for sustainable lines. The market features a mix of incumbent footwear giants adapting to sustainability mandates and agile, direct-to-consumer startups focused solely on eco-friendly products. Two strategic archetypes emerge: large-scale conventional manufacturers integrating sustainable practices, and niche players building brands around specific bio-materials. Strategic partnerships with material science innovators and targeted geographic expansion are common competitive moves.
Within the direct-to-consumer specialist tier, Allbirds exemplifies material innovation with its focus on natural fibers and a strong brand narrative that resonates with eco-conscious consumers globally. New Balance, as an established athletic footwear giant, represents the integration of recycled content into high-volume product lines, adapting its extensive manufacturing capabilities and distribution networks. Cariuma further anchors the lifestyle segment, specializing in casual footwear made from ethically sourced organic cotton and other low-impact materials, appealing to a specific, values-driven demographic seeking transparency.
| Leading Market Players |
|---|
| Cariuma |
| Thousand Fell |
| Allbirds |
| New Balance |
| Saola |
| Veja |
| Nisolo |
| Puma |
| Rothy's |
Cost & Logistics Intelligence
Family-owned mid-caps in sustainable footwear face pressure from both material cost volatility and consumer demand for transparent pricing. Their supply behavior, often reliant on niche material producers, directly influences their ability to maintain competitive pricing discipline.
Pricing Analysis
Retailer markup structures significantly influence final sustainable footwear prices. The dominant pricing model involves premium-mid-economy pricing differentiation, reflecting material certifications like GOTS for organic cotton and brand premium for innovative bio-materials. Pricing softness stems from increasing competition in the mid-range segment, where consumers seek affordability. The budget segment exhibits the highest price sensitivity, while premium buyers prioritize verifiable sustainability over cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized material suppliers for novel bio-based filaments and organic cotton, with production hubs in China, India, and specific European regions. Key dependencies include bamboo fiber, recycled rubber, and chrome-free tanned leather. Commodity price volatility for these specialized inputs represents a significant structural risk. Distribution runs through a hybrid model, combining direct-to-consumer channels with established multi-brand retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
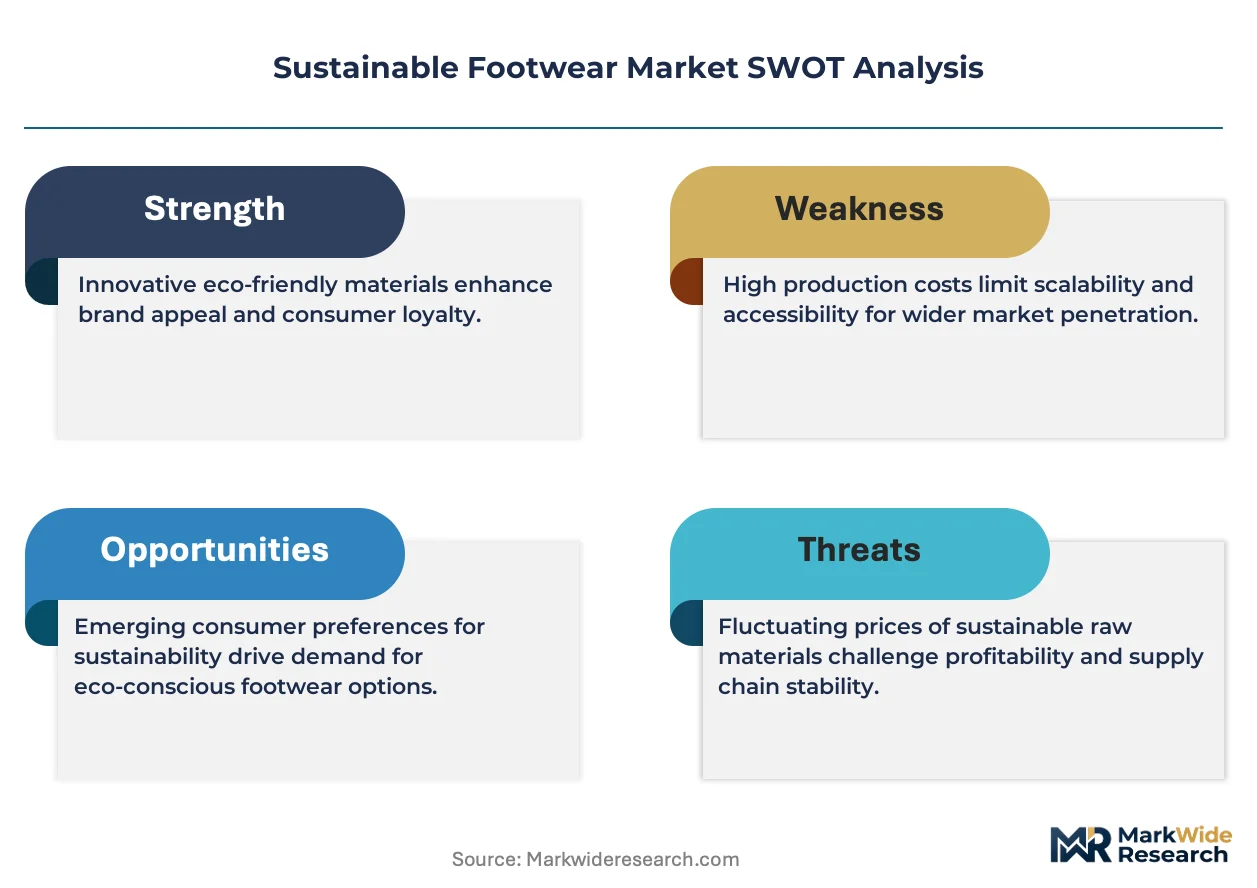
The sustainable footwear market presents a clear margin-expansion story, driven by consumer willingness to pay a premium for verifiable eco-credentials. This shift toward premiumization, especially in the athlete segment, allows brands to command higher price points.
For Market Incumbents: To counter the threat of agile direct-to-consumer startups capturing niche segments, incumbent brands must invest heavily in R&D for advanced bio-materials. They should also pursue strategic partnerships with material science innovators to secure exclusive access. Expanding manufacturing capacity in developed economies like Germany can mitigate supply chain risks and enhance brand trust. This approach strengthens their competitive positioning against emerging players.
For New Entrants and Emerging Players: The EU's Corporate Sustainability Reporting Directive (CSRD) in Europe opens a window for new entrants offering transparent, auditable supply chain solutions. Target the premium casual footwear segment in Germany, where consumers demand verifiable sustainability. Focus on a direct-to-consumer model emphasizing material traceability and end-of-life circularity. This strategy allows differentiation from larger brands lacking granular data.
For Investors and Strategic Acquirers: Established athletic footwear giants are the most active acquirers in this space, seeking to integrate sustainable material expertise. The market shows strong long-term viability over the next 5-10 years, driven by sustained consumer and regulatory pressure. Target direct-to-consumer specialists with proven material innovation and strong brand narratives, like Allbirds. The signal to watch is the increasing market share of bio-fabricated materials in performance athletic footwear.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Bio-material R&D | Developing high-performance bamboo fiber and mycelium-based alternatives reduces reliance on petroleum-derived plastics. |
| Circular Economy Program Launch | Implementing brand-managed take-back and repair services enhances customer loyalty and minimizes end-of-life waste. |
| Supply Chain Traceability Platform | Providing verifiable data on material sourcing and production processes builds consumer trust and ensures regulatory compliance. |
| Targeted Geographic Expansion | Entering Asia-Pacific markets leverages rising middle-class disposable income and sustainable consumption patterns. |
| 3D Printing Integration | Adopting additive manufacturing enables on-demand customization and significantly reduces material scrap in production. |
Research Approach
Multiple input streams — primary interviews, company reports, and regulatory filings — were reconciled to build a comprehensive market view. This involved engaging with R&D directors, procurement leads at footwear brands, and sustainability officers. Secondary validation drew from EU CSRD disclosures, FTC Green Guides enforcement actions, and customs data. Bottom-up data collection was triangulated with top-down market sizing approaches.
Data-stream reconciliation informed the analytical framework across the modeling period. Segmentation dimensions modeled included material type, production method, end user, price tier, and regional regulatory environment. Compound annual growth rates were derived from historical trends, projected material innovation, and consumer preference shifts. Key forecast inputs included the adoption rate of bio-based materials and the impact of regulatory compliance costs.
Revisions become necessary when significant shifts in consumer sustainability mandates or material science breakthroughs materialize. Forecasts reflect underlying assumptions regarding regulatory enforcement and supply chain maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Duck Boots Market
Footwear
Platform Boots Market
Footwear
Driving Footwear Market
Footwear
Winter Footwear Market
Footwear
Formal Shoes Market
Footwear
UK Lifestyle Sneakers Market
Footwear
Slip on Shoes Market
Footwear
Hiking Footwear Market
Footwear
Sports Shoes Market
Footwear
White Sneakers Market
Footwear
Slip Resistant Shoes Market
Footwear
Global Men Leather Shoes Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Sneaker Boots Market
Footwear
GCC Footwear Market
Footwear
Women's Non-Athletic Footwear Market