
 Global Men Leather Shoes Market | 2026-2036
Global Men Leather Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Men Leather Shoes Market Outlook
REACH is shifting the cost-of-entry calculus for European tanneries supplying finished leather to footwear manufacturers. ECCO Sko A/S leverages integrated tannery operations to control chemical compliance costs from raw hide through finished product. C. & J. Clark International Ltd anchors its competitive stance on durable construction methods that predate modern synthetic alternatives. Prada S.p.A. differentiates through vertical control over rare leather grades sourced from regulated Italian suppliers.
Men leather shoes constitute footwear constructed from tanned animal hides, typically cattle leather, with full-grain and top-grain finishes offering breathability and structural longevity through welted or cemented construction. The primary commercial purpose spans professional dress codes, ceremonial occasions, and elevated casual environments where synthetic alternatives fail to meet aesthetic or durability expectations. Oxfords dominate formal workplace procurement where professionals require closed-lacing silhouettes under conservative dress policies. Loafers represent the fastest-expanding product type as casual wearers adopt slip-on designs for hybrid office attendance. Online retail channels capture margin pools previously held by department stores as direct-to-consumer platforms reduce intermediary markups on made-to-order configurations.
EMA enforces chemical restrictions through REACH annexes that limit hexavalent chromium in leather finishing processes across European supply chains. EPA regulations in the United States govern wastewater discharge from tannery operations, raising compliance costs for domestic manufacturers sourcing from overseas processors. China's SAMR implements GB standards for leather product labeling that affect import clearance for foreign brands entering domestic distribution. Stakeholders must monitor evolving chemical disclosure requirements that threaten to disqualify legacy tanning methods from premium market tiers.
Market Dynamics
REACH compliance costs are compressing European tannery margins while hybrid work policies permanently alter formal footwear procurement volumes across corporate sectors.
Growth Catalysts
- Chrome-free tanning innovation:Italian tanneries pioneer metal-free finishing processes that satisfy ECHA chemical restrictions. Premium brands adopt these materials to maintain EU market access.
- China:Domestic menswear brands expand direct-to-consumer leather shoe lines through e-commerce platforms, capturing margin pools previously held by intermediaries.
- Hybrid work stabilization:Financial services and legal sectors establish permanent dress codes requiring formal footwear for in-office attendance, sustaining replacement demand cycles.
Market Restraints
- Hide supply concentration:Raw material sourcing concentrates in Brazil and Argentina, exposing finished goods manufacturers to livestock cycle volatility and currency fluctuation.
- REACH annex restrictions:Hexavalent chromium limits in leather finishing processes raise compliance costs for European tanneries supplying footwear manufacturers.
- Synthetic leather substitution:Polyurethane and microfiber alternatives improve aesthetic parity, capturing price-sensitive segments in mass-market distribution.
Strategic Opportunities
- India:Underpenetrated premium formal footwear markets present expansion paths for established European brands through BIS-certified domestic manufacturing partnerships.
- Made-to-order platforms:Direct-to-consumer configuration tools reduce inventory risk while capturing margin previously allocated to wholesale intermediaries.
- EU Green Deal alignment:Circular economy action plan incentives reward brands establishing take-back programs and regenerative leather sourcing certifications.
Industry Challenges
- Artisan skill scarcity:Hand-welted construction expertise concentrates in aging European workforces, constraining volume scaling for heritage-quality production.
- Dual certification timelines:Simultaneous REACH and GB standards compliance for China-EU product lines extends product development cycles and testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Men Leather Shoes Market |
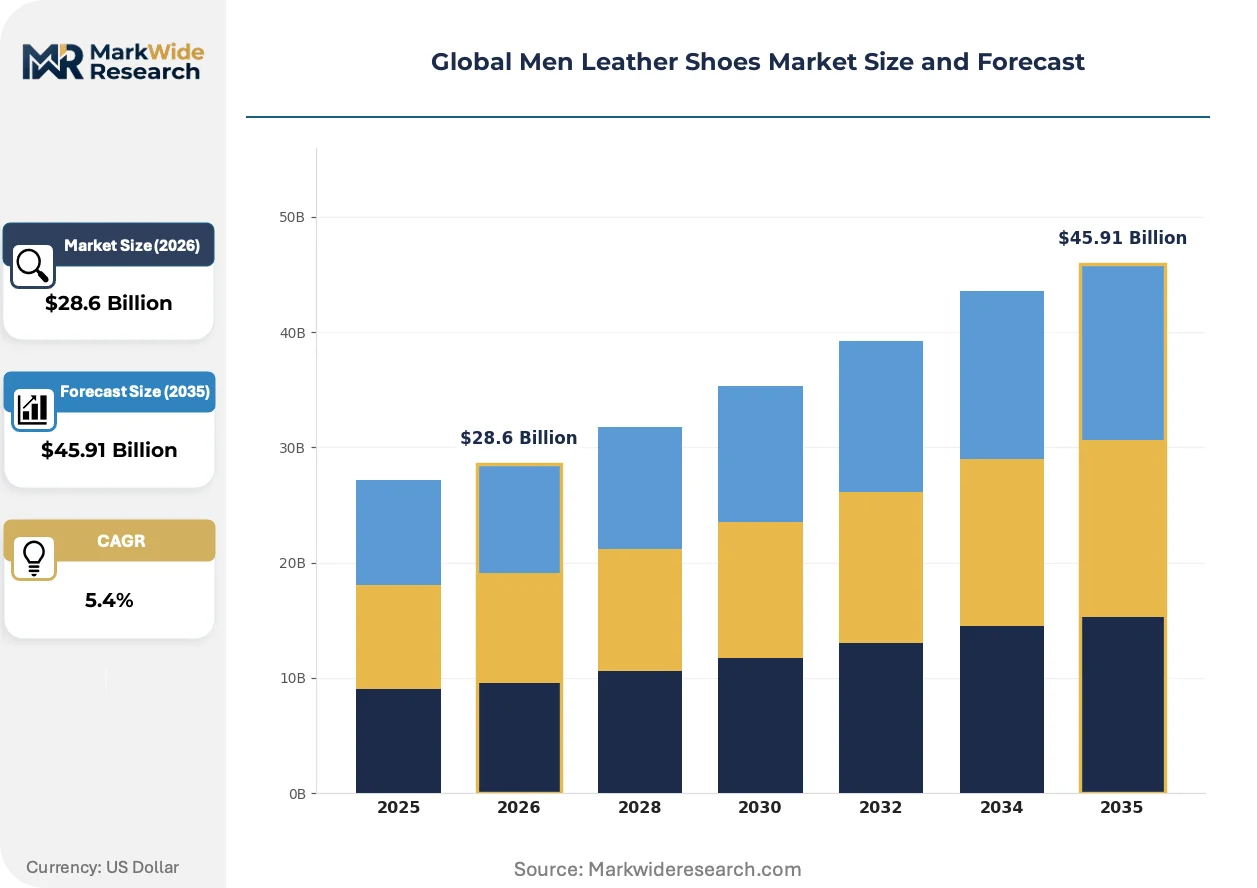
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxfords, Loafers, Derbies, Brogues End User: Professionals, Casual Wearers, Athletes, Students Distribution Channel: Online Retail, Department Stores, Specialty Stores, Direct Sales Style: Formal, Casual, Vintage, Contemporary |
| Companies Covered | Burberry Group Plc, C. & J. Clark International Ltd, Guccio Gucci S.p.A., Salvatore Ferragamo S.p.A., Hugo Boss AG, Prada S.p.A., Alden Shoe Company, Allen Edmonds Corporation, ECCO Sko A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Men Leather Shoes Market Strategic Shifts
Digital configuration tools and chemical compliance automation are compressing traditional footwear value chains while reshaping how premium brands interact with end consumers.
3D foot-scanning technology paired with parametric design software is modularizing bespoke production economics. Corporate professionals in hybrid work environments adopt made-to-measure services at accelerating rates. This capability is modularizing the historical trade-off between customization scale and unit economics that constrained accessible luxury positioning.
ECHA's expanding REACH annexes now restrict additional aromatic amines in leather dyes across European supply chains. Tanneries serving premium footwear manufacturers invest in alternative chemical inventories and wastewater treatment upgrades. Italian finished leather exports face the most concentrated compliance pressure given their centrality to luxury brand supply chains.
Corporate procurement departments now specify formal footwear allowances through centralized employee benefit platforms rather than individual expense reimbursement. Department store intermediaries lose volume to direct brand relationships as hybrid workers purchase through employer-negotiated portals. This pattern concentrates most visibly in United States financial services and technology sectors where remote-first policies have stabilized.
Global Men Leather Shoes Market Segmentation
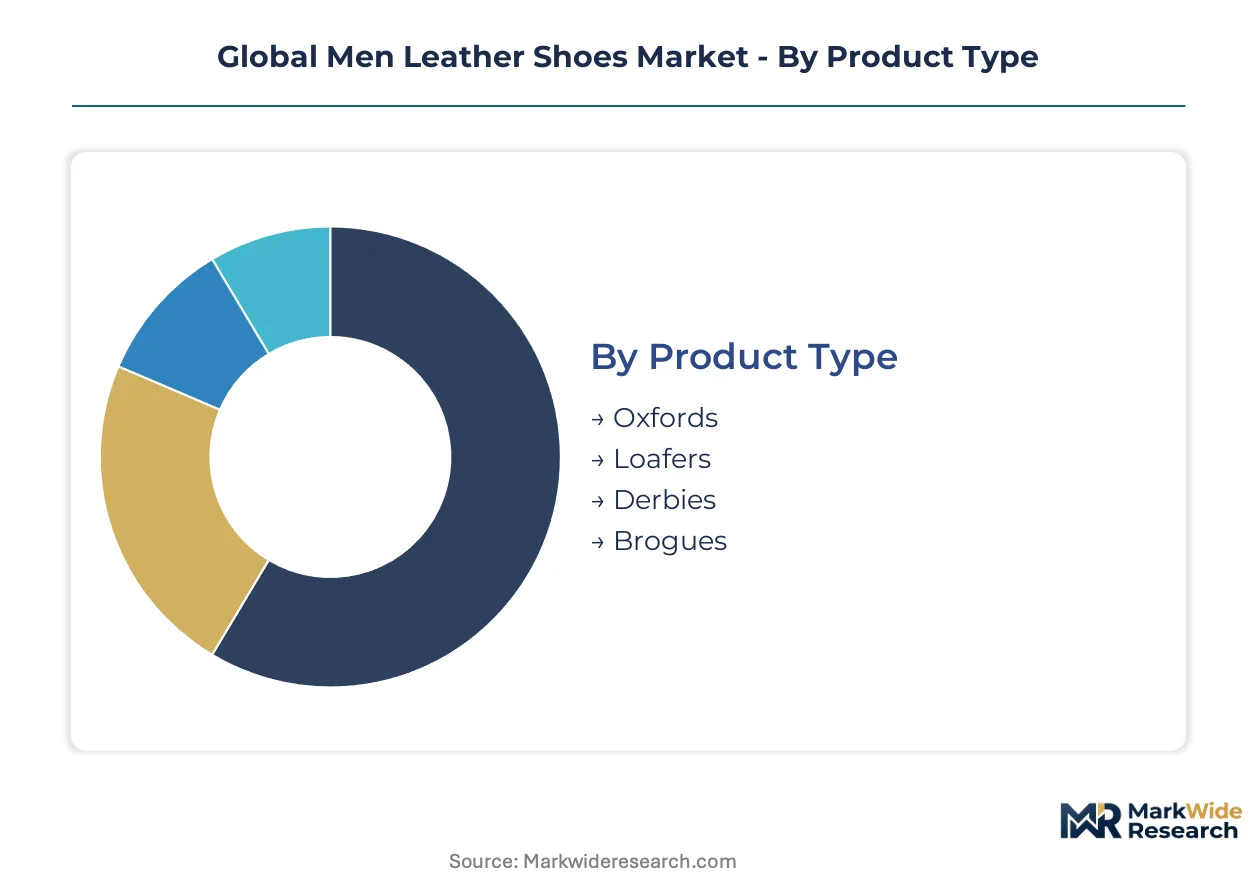
Leather shoe procurement cycles vary sharply across use cases, with formal workplace requirements driving predictable replacement intervals while casual adoption patterns fragment demand timing. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume expansion accelerates.
Product Type:
Upgrade cycles differ dramatically by construction complexity, with welted formal styles commanding longer replacement horizons than cemented casual alternatives.
- Oxfords:Closed-lacing construction using full-grain leather uppers with leather soles defines the conservative workplace standard. Financial services and legal professionals in London, New York, and Frankfurt sustain replacement demand through institutional dress codes that resist casualization.
- Loafers:Slip-on designs with moccasin or apron construction reduce barrier-to-entry for hybrid office attendees seeking polish without formality. White-collar workers in technology and consulting sectors across Singapore, Shanghai, and San Francisco adopt these for partial-week office presence, compressing purchase cycles through style experimentation.
- Derbies:Open-lacing systems accommodate wider foot geometries while maintaining professional acceptability.
- Brogues:Perforated decorative patterns signal regional heritage associations, particularly in British and Irish markets.
Volume placements concentrate in Oxfords; the faster expansion belongs to Loafers.
End User:
Customer type determines price tolerance and channel preference, with employer-subsidized procurement diverging sharply from individual discretionary spending.
- Professionals:Corporate dress codes and client-facing requirements sustain premium price acceptance. Centralized procurement platforms at financial institutions and law firms in Frankfurt, Chicago, and Hong Kong now negotiate direct brand relationships, bypassing traditional retail markups.
- Casual Wearers:Style-conscious consumers prioritize versatility across workplace and social contexts. Urban professionals in Milan, Tokyo, and São Paulo drive demand for hybrid designs that transition across settings without dedicated formal pairs.
- Athletes:Post-career lifestyle transitions create occasional ceremonial demand rather than sustained replacement cycles.
- Students:Entry-level price sensitivity and first-interview procurement concentrate demand in private-label and mass-market tiers.
Revenue concentration sits with Professionals; Casual Wearers are climbing the fastest.
Distribution Channel:
Channel economics reshape margin capture, with inventory risk allocation shifting decisively toward direct relationships.
- Online Retail:Configuration tools and virtual try-on technologies reduce fit uncertainty for made-to-order purchases. Direct-to-consumer platforms operated by Italian and Portuguese manufacturers now serve corporate clients in Germany, France, and the Netherlands with employer-negotiated portals.
- Department Stores:Foot traffic erosion and intermediary margin compression threaten historical volume leadership. Flagship locations in Paris, London, and New York retain relevance for tactile evaluation but lose transaction share to brand-controlled digital channels.
- Specialty Stores:Trained fitting expertise sustains premium price realization for complex lasts and width variations.
- Direct Sales:Corporate uniform programs and executive allowance platforms capture institutional procurement volumes.
Transaction volume tilts toward Online Retail; Direct Sales shows the steepest expansion trajectory.
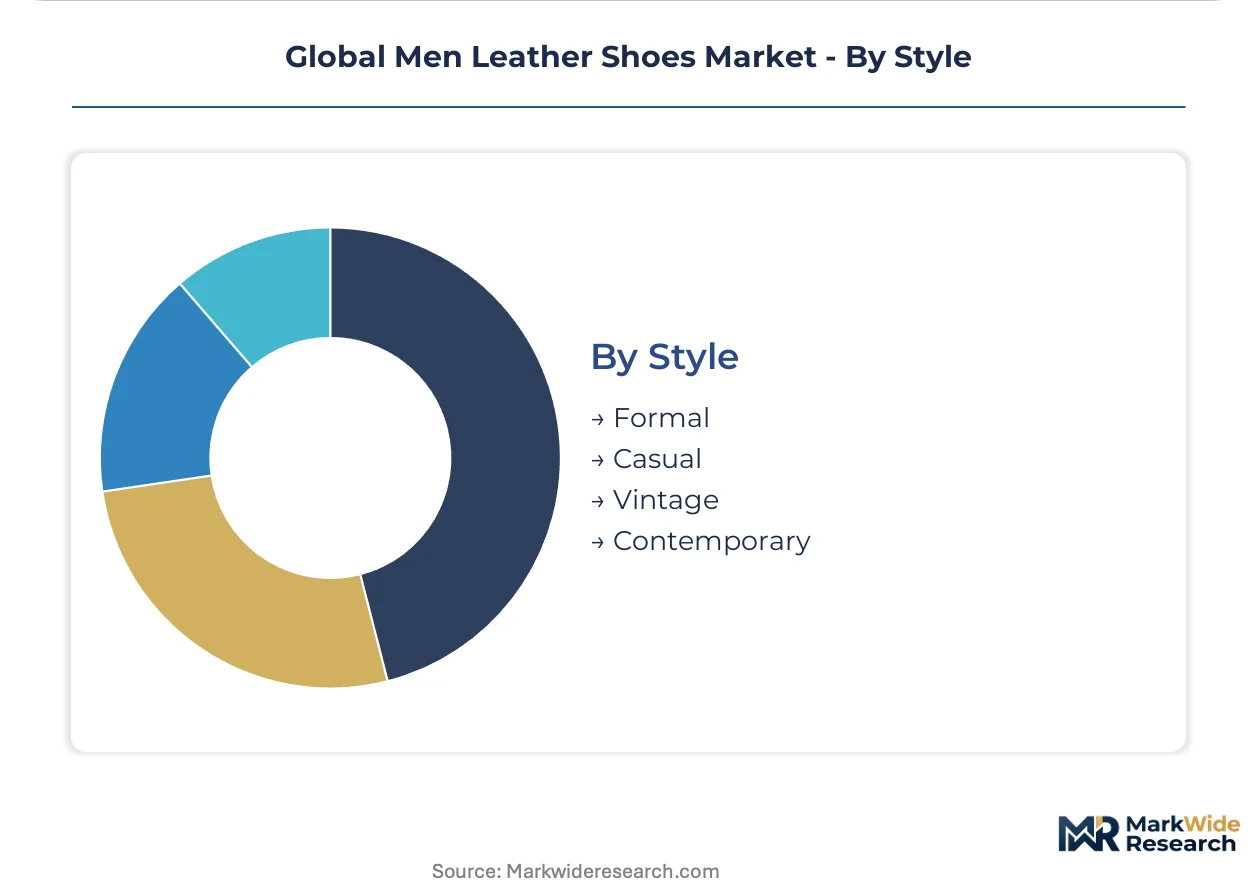
Style:
Aesthetic positioning determines material grade requirements and construction method selection, with heritage associations commanding sustainable price premiums.
- Formal:Conservative silhouettes with minimal ornamentation satisfy institutional dress codes. Full-grain calfskin from regulated Italian tanneries supplies manufacturers serving European Union markets where REACH compliance is non-negotiable.
- Casual:Relaxed proportions and mixed-material constructions expand addressable occasions. Suede and nubuck finishes from Spanish and Portuguese processors capture demand in Mediterranean and Latin American climates.
- Vintage:Reproduction lasts and hand-finished patina techniques appeal to heritage-focused collectors.
- Contemporary:Architectural silhouettes and experimental constructions target fashion-forward urban markets.
Formal styling retains volume dominance; Casual configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian industrial districts and Portuguese footwear zones concentrate premium leather shoe manufacturing through specialized tannery-to-finished-goods corridors. Tax incentives in these zones attract investment in chrome-free processing infrastructure. Demand clusters in financial centers across three continents drive regional procurement patterns.
United States
Corporate benefit platforms at financial institutions in Chicago and New York sustain formal footwear procurement through employer-negotiated direct brand relationships. EPA wastewater discharge regulations govern tannery suppliers serving domestic manufacturers. Wisconsin and Maine host heritage-focused factories producing hand-welted construction for discerning professionals.
Italy
Luxury menswear houses in Milan and Florence drive demand for rare leather grades from regulated Tuscan tanneries. ECHA REACH annexes restrict hexavalent chromium and aromatic amines in finishing processes, raising compliance costs for Venetian and Solofra processors. The Marche region anchors volume production of cemented casual styles for export markets.
China
Domestic menswear brands in Shanghai and Beijing expand direct-to-consumer leather shoe lines through e-commerce platforms, capturing margin pools from intermediaries. SAMR GB standards for leather product labeling affect import clearance for European brands entering domestic distribution. Guangdong province concentrates manufacturing partnerships serving both domestic consumption and re-export.
United Kingdom
City of London dress codes sustain replacement demand for conservative Oxford silhouettes among legal and financial professionals. Post-Brexit regulatory divergence from REACH creates dual certification burdens for brands serving both UK and EU markets. Northamptonshire retains concentration of heritage factories with artisan hand-welting capabilities.
India
Underpenetrated premium formal footwear markets in Mumbai and Delhi present expansion paths for established European brands. BIS certification requirements for domestic manufacturing partnerships create compliance timelines for market entry. Kanpur and Agra host leather processing clusters transitioning from bulk export to finished goods capability.
Global Men Leather Shoes Market Competitive Environment
Italian luxury houses anchor the premium tier; Danish and British specialists hold differentiated positions through construction heritage and integrated supply chains. Market structure concentrates in heritage brands with multi-decade positioning rather than scale-driven consolidation. Three archetypes dominate: vertically integrated tannery-owners controlling chemical compliance, artisan-construction specialists preserving hand-welted methods, and fashion-luxury houses leveraging brand equity for pricing power. Competitive moves center on direct-to-consumer platform development and regenerative leather sourcing certifications aligned with EU Green Deal incentives.
Among heritage-construction specialists, C. & J. Clark International Ltd and Alden Shoe Company exemplify durable-method positioning built on pre-synthetic construction expertise. Within integrated supply chain operators, ECCO Sko A/S represents captive tannery control from raw hide through finished product. On the luxury fashion vector, Prada S.p.A. occupies a position defined by vertical control over rare leather grades from regulated Italian suppliers.
| Leading Market Players |
|---|
| Burberry Group Plc |
| C. & J. Clark International Ltd |
| Guccio Gucci S.p.A. |
| Salvatore Ferragamo S.p.A. |
| Hugo Boss AG |
| Prada S.p.A. |
| Alden Shoe Company |
| Allen Edmonds Corporation |
| ECCO Sko A/S |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap tanneries in Italy's Marche and Veneto regions anchor premium leather supply, translating generational asset ownership into patient pricing discipline that resists cyclical discounting even when hide costs fluctuate. Their captive relationships with heritage footwear manufacturers create bilateral pricing power insulated from commodity spot volatility.
Pricing Analysis
Short lead-time premiums for chrome-free finished leather from Solofra tanneries command substantial markups over standard delivery schedules, while spot inventory of REACH-non-compliant stock trades at distressed levels. Three-tier pricing structure across heritage hand-welted, bench-made, and factory-cemented construction tiers differentiates on artisan labor intensity and certification grade. Price erosion runs through mass-market cemented imports as polyurethane alternatives narrow aesthetic gaps. Students and entry-level professionals exhibit acute price sensitivity; corporate procurement platforms at financial institutions demonstrate inelastic demand for certified Italian full-grain.
Supply Chain Analysis
Domestic-content mandates under India's BIS certification requirements are reshaping sourcing patterns for European brands seeking tariff-advantaged market entry. Raw material sourcing draws from Brazilian and Argentine hide processors, Italian chrome-free tanneries, and Portuguese finished leather exporters. Supply chain risk centers on livestock cycle volatility exposing finished goods manufacturers to currency fluctuation and hide price spikes. Distribution runs through direct-to-consumer brand platforms, employer-negotiated corporate portals, and declining department store intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artisan skill scarcity constrains heritage-quality production scaling, propping pricing power for incumbent specialists with captive workforces. This supply-constrained structure favors established players with multi-decade workforce development.
For Market Incumbents: To counter synthetic leather substitution in price-sensitive tiers, secure captive tannery capacity through backward integration into chrome-free processing infrastructure. Deepen channel control by deploying employer-negotiated corporate procurement portals that bypass retail markups and lock in institutional replacement cycles. For New Entrants and Emerging Players: REACH compliance costs in European Union markets open a window for India-based manufacturing partnerships serving underpenetrated premium formal footwear demand in Mumbai and Delhi. Target BIS-certified domestic production to circumvent import duty structures while building brand recognition through made-to-order digital configuration tools. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated Portuguese manufacturers with captive tannery operations and established e-commerce infrastructure. Long-term viability over a five-to-ten-year horizon hinges on regenerative leather sourcing certifications aligned with EU Green Deal incentive structures. Watch artisan workforce age demographics as the critical inflection signal for heritage-production scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Tanning Capacity Expansion | Italian tanneries investing in metal-free finishing secure REACH-compliant market access for luxury brand supply chains. |
| Direct-to-Consumer Platform Launch | Portuguese manufacturers bypassing wholesale intermediaries capture margin pools previously allocated to department stores. |
| Corporate Procurement Portal Development | Employer-negotiated platforms at Chicago and Frankfurt financial institutions institutionalize replacement demand cycles. |
| Regenerative Leather Sourcing Certification | EU Green Deal alignment rewards brands establishing take-back programs with circular economy incentive access. |
| Artisan Workforce Development Partnership | Northamptonshire heritage factories collaborating with technical institutes preserve hand-welted construction expertise. |
Study Parameters
Multi-period observation of hide price indices, tannery capacity utilization rates, and corporate procurement platform adoption anchored the trend analysis, supplemented by interviews with Italian tannery technical directors, Portuguese footwear factory operations managers, brand supply chain executives, and corporate benefits administrators at financial institutions. Secondary validation drew from ECHA REACH annex updates, SAMR GB standard filings, customs trade data for finished leather and footwear, and SEC disclosures from publicly traded luxury houses. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand indicators.
Input-output matrices mapping construction method to material grade, distribution channel to end-user segment, and geographic production cluster to regulatory compliance tier structured the analytical framework across the analysis window. CAGRs derived from fitted growth curves applied to segment-level volume and value baselines, incorporating hide supply cycle assumptions, hybrid work policy stabilization trajectories, and e-commerce penetration rates for made-to-order footwear.
Caveats apply where REACH annex expansion, BIS certification timeline delays, or livestock disease outbreaks could materially shift the outlook for raw material availability and compliance cost structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
White Sneakers Market
Footwear
Sustainable Footwear Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Waterproof Sneakers Market
Footwear
Sandals Market
Footwear
Global Recovery Footwear Market
Footwear
Leather Footwear Market
Footwear
Hiking Footwear Market
Footwear
Refurbished Sneaker Market
Footwear
Protective Footwear Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Sports Footwear Market
Footwear
Premium Shoes Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Wedge Boots Market
Footwear
Shoe Insoles Market