
 Slip Resistant Shoes Market | 2026-2036
Slip Resistant Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Slip Resistant Shoes Market Analytics
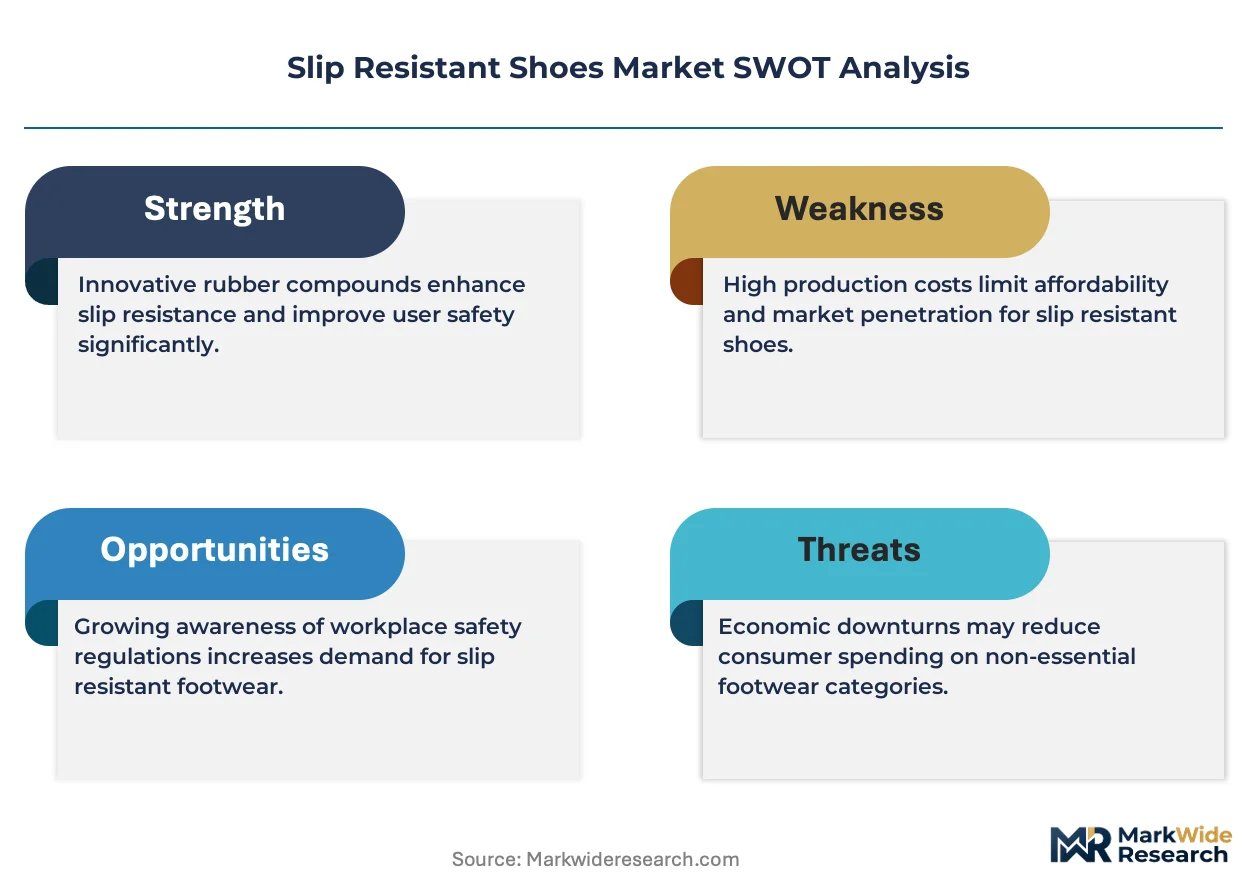
Advanced rubber compounding is narrowing the performance gap between occupational safety footwear and casual comfort designs. Skechers leverages proprietary outsole geometries to compete in the hospitality segment where all-day wearability commands premium positioning. Red Wing Shoe Company anchors its position through backward integration into leather tanning and domestic manufacturing. Nike sustains R&D intensity by applying athlete-biomechanics expertise to industrial sneaker categories.
Slip resistant shoes are engineered footwear incorporating specialized tread patterns, coefficient-of-friction outsoles exceeding 0.5 on wet and oily surfaces, and materials selected for chemical degradation resistance, designed primarily to prevent falls in hazardous work environments. The boots category dominates margin pools due to stringent ASTM F2413 safety requirements and longer replacement cycles in industrial settings. Sneakers represent the fastest-growing product type as food service chains standardize uniform programs around athletic-styled options. Rubber outsoles capture the largest material share, though polyurethane-TPU blends are gaining ground where lightweight properties reduce worker fatigue.
OSHA General Industry Standards 1910.136 mandate protective footwear in workplaces with foot injury hazards, directly expanding addressable demand across manufacturing and logistics facilities. ASTM International publishes F2913 for whole shoe slip resistance testing, while SATRA in the United Kingdom operates TM144 as a complementary benchmark adopted by multinational employers. The European Union's PPE Regulation 2016/425 requires CE marking for occupational footwear, creating compliance barriers for non-certified imports. Stakeholders must monitor how evolving state-level workers' compensation reforms and insurance premium incentives reshape employer procurement thresholds for certified footwear.
Market Dynamics
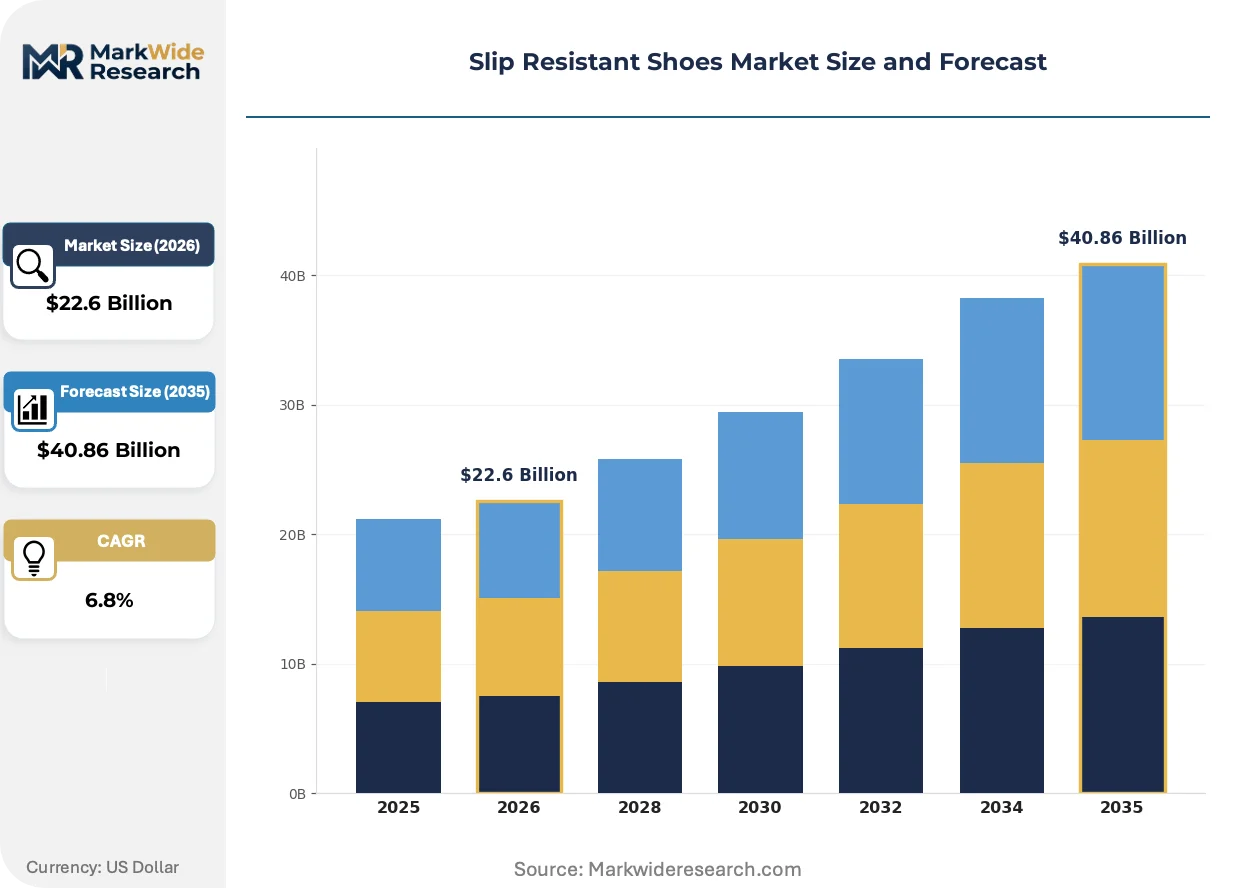
ASTM F2913 certification requirements and OSHA enforcement intensity are compressing procurement timelines while elevating technical barriers for uncertified suppliers across food service and industrial channels.
Growth Catalysts
- OSHA General Industry Standards 1910.136:Federal mandates for protective footwear in hazardous workplaces expand addressable demand across manufacturing and logistics facilities nationwide.
- Polyurethane-TPU outsole blends:Lightweight material innovations reduce worker fatigue during extended shifts, accelerating replacement cycles in hospitality and healthcare settings.
- Restaurant chain standardization:National food service operators are mandating uniform slip-resistant programs, consolidating volume procurement through approved vendor lists.
Market Restraints
- Natural rubber price volatility:Input cost swings for petroleum-derived synthetic rubbers compress margins for mid-tier manufacturers without captive supply arrangements.
- CE marking compliance barriers:The European Union's PPE Regulation 2016/425 blocks non-certified imports, fragmenting addressable market access for Asia-Pacific producers.
- Extended boot replacement cycles:Industrial safety footwear durability exceeds 18-24 months in heavy manufacturing, constraining recurring revenue velocity.
Strategic Opportunities
- Healthcare facility penetration:Hospital systems and long-term care operators remain underpenetrated relative to food service, offering white space for specialized antimicrobial outsole formulations.
- Workers' compensation premium incentives:State-level insurance reforms in California and Texas reward employers with certified footwear programs, creating policy-tailwinds for volume sales.
- Direct-to-workforce digital channels:Employer-subsidized individual purchasing platforms bypass traditional uniform distributor markups, capturing margin previously allocated to intermediaries.
Industry Challenges
- ASTM F2913 testing backlog:Third-party certification laboratory capacity constraints extend product launch timelines by 8-12 weeks for new outsole compounds.
- Biomechanical engineering talent scarcity:Specialized footwear design expertise combining slip-resistance science with all-day comfort engineering commands premium compensation, inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slip Resistant Shoes Market |
| Market Size in 2026 | $22.6 Billion |
| Market Size in 2035 | $40.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Sandals, Boots, Sneakers End User: Hospitality, Industrial Workers, Healthcare, Food Service Material: Rubber, Leather, Synthetic, Canvas Footwear Feature: Waterproof, Breathable, Lightweight, Puncture Resistant |
| Companies Covered | Skechers, Nike, Adidas, Crocs, New Balance, Keen, Caterpillar, Reebok, Red Wing Shoe Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slip Resistant Shoes Market Evolving Landscape
Digital measurement tools and predictive wear analytics are compressing traditional fit-trial cycles while reshaping how employers validate safety performance across distributed workforces.
3D foot-scanning technology integrated with mobile applications is digitizing how food service chains size and order uniform footwear programs. Large restaurant operators now deploy smartphone-based scanning for remote workers, reducing return rates and accelerating onboarding velocity. This capability is digitizing procurement workflows previously managed through physical distributor relationships.
The European Union's PPE Regulation 2016/425 enforcement intensification is elevating documentation requirements for occupational footwear importers. Manufacturers must now maintain technical files and conformity assessments across 27 member states, raising compliance overhead. Athletic-styled safety sneakers face heightened scrutiny in Germany and France where authorities prioritize SATRA TM144 benchmark alignment.
Employer-funded individual allowance models are displacing centralized bulk purchasing in multi-location hospitality chains. Workers receive annual stipends for certified footwear selection through approved digital catalogs, shifting volume toward direct fulfillment channels. This pattern concentrates in Texas and Florida where franchise density supports platform economics.
Slip Resistant Shoes Market Segmentation
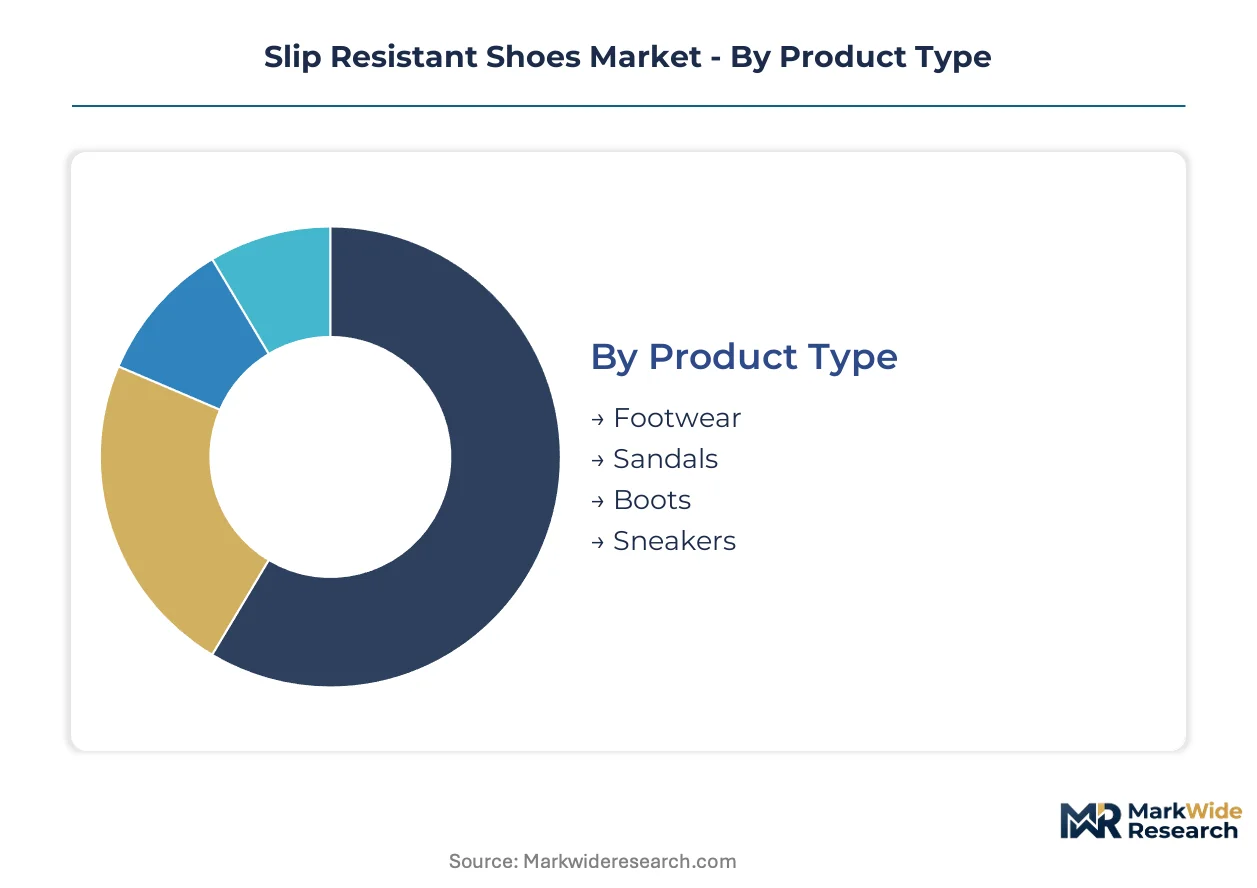
Segmentation in slip resistant footwear reveals how certification requirements, material science, and end-use hazards create distinct procurement channels. Each dimension shapes pricing power, replacement velocity, and compliance burden differently across occupational environments.
Product Type:
Cost tier stratification separates premium certified safety products from volume uniform replacements in food service and hospitality channels.
- Boots:Heavy-duty constructions meeting ASTM F2413 safety requirements command premium positioning through steel toe caps, metatarsal guards, and oil-resistant outsoles. Demand concentrates in heavy manufacturing across Texas, Ohio, and Pennsylvania where OSHA enforcement drives 18-24 month replacement cycles and elevated procurement thresholds.
- Sneakers:Athletic-styled designs with SATRA TM144-aligned outsoles are gaining share fastest as national restaurant chains standardize uniform programs around comfort-forward options. Quick-service operators in California and Florida now mandate sneaker formats for kitchen and front-of-house staff to reduce fatigue-related turnover.
- Footwear:General occupational slip-resistant designs serve light industrial and warehouse applications where ASTM F2913 certification suffices without supplemental safety features.
- Sandals:Open-toe configurations address limited healthcare and hospitality niches requiring ventilation and quick-dry properties in warm-climate facilities.
Boots hold installed capacity in heavy industrial channels. Sneakers are rotating up the share rankings through food service standardization.
End User:
Application severity and regulatory exposure create divergent margin structures across occupational categories.
- Food Service:High-volume procurement through approved vendor lists dominates this segment, with national chains consolidating spend across thousands of locations. Kitchen grease hazards and OSHA recordable fall metrics drive mandatory slip-resistant mandates in quick-service and casual dining operations.
- Industrial Workers:Manufacturing and logistics facilities combine ASTM F2413 impact protection with F2913 slip resistance, extending replacement intervals and concentrating demand with specialized safety distributors.
- Hospitality:Hotels and resorts prioritize all-day wearability and polished aesthetics for guest-facing roles, accepting lower technical specifications than back-of-house environments.
- Healthcare:Hospital systems and long-term care operators remain underpenetrated relative to food service, with antimicrobial and fluid-resistant features now driving specialized product development.
Food Service captures volume concentration through chain standardization. Healthcare is climbing the fastest as facility safety committees elevate footwear protocols.
Material:
Supply concentration and petroleum input exposure differentiate margin stability across material categories.
- Rubber:Natural and synthetic rubber compounds deliver coefficient-of-friction performance exceeding 0.5 on wet and oily surfaces, forming the technical foundation for certified outsoles. Petroleum price volatility compresses margins for manufacturers without captive supply arrangements or long-term purchasing contracts.
- Synthetic:Polyurethane-TPU blends reduce worker fatigue through 30-40% weight reduction versus rubber, accelerating replacement cycles in healthcare and hospitality settings where extended shifts are standard.
- Leather:Full-grain and split-leather uppers dominate boot constructions where abrasion resistance and professional appearance justify premium positioning in industrial and supervisory roles.
- Canvas:Woven textile uppers serve limited applications requiring maximum breathability in warm-climate food service and casual hospitality environments.
Rubber maintains technical dominance in certified outsoles. Synthetic formulations are expanding most quickly through weight-driven fatigue reduction.
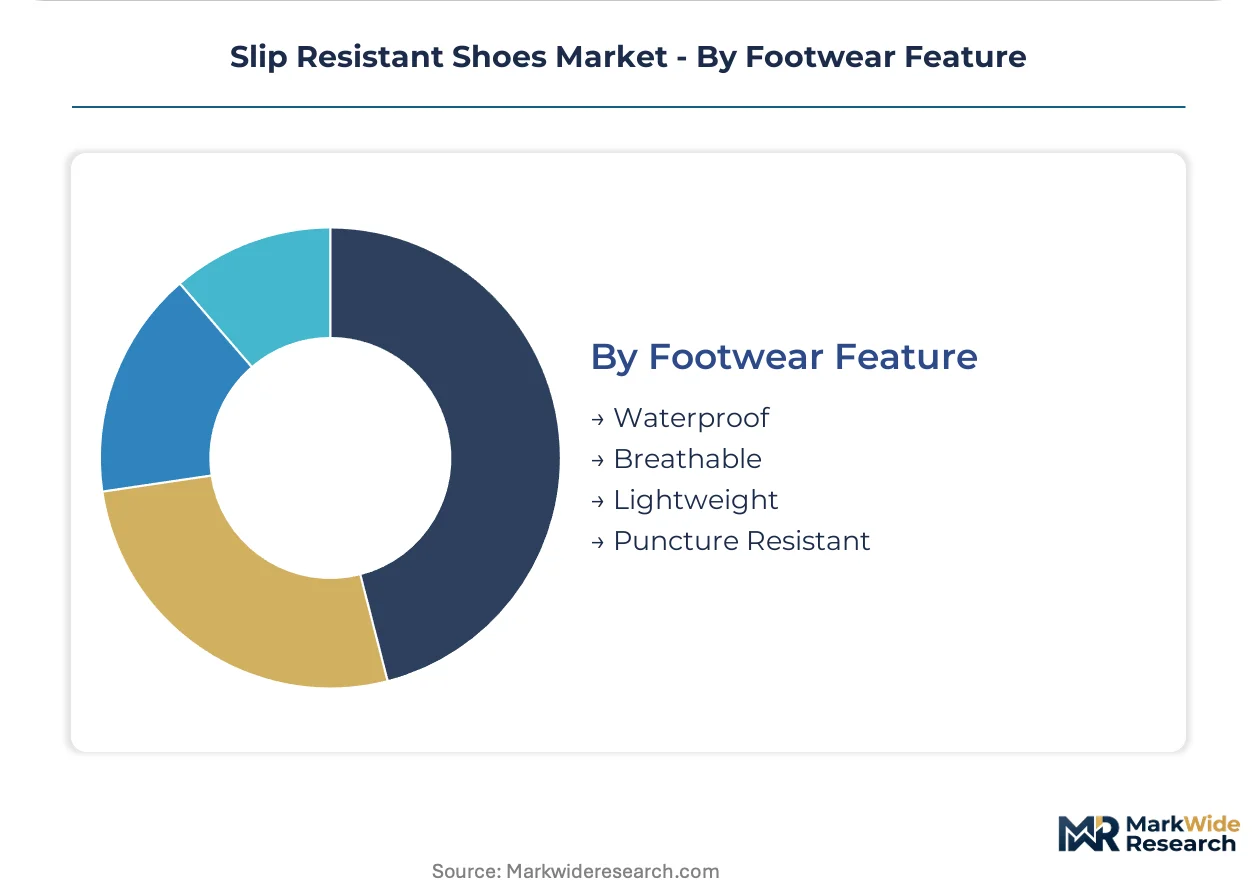
Footwear Feature:
Performance tier differentiation separates baseline compliance products from premium specifications addressing specific hazard profiles.
- Waterproof:Membrane-lined constructions with sealed seams address wet environment exposure in food processing, commercial cleaning, and outdoor hospitality roles where fluid contact is routine.
- Lightweight:Material optimization and structural engineering reduce musculoskeletal strain, commanding premium positioning in healthcare and hospitality segments with 12-hour shift standards.
- Breathable:Moisture-wicking linings and ventilated uppers target high-temperature kitchen environments and warm-climate operations where thermal comfort affects retention.
- Puncture Resistant:Steel or composite midsoles protect against nail and sharp object hazards in construction-adjacent industrial roles, typically combined with other ASTM F2413 features.
Waterproof specifications anchor demand in processing and cleaning applications. Lightweight engineering is gaining share fastest through healthcare penetration and hospitality comfort mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports slip-resistant footwear components and finished goods to North American and European industrial buyers, with Vietnam and Indonesia emerging as alternative assembly hubs for brands seeking tariff diversification.
United States
OSHA enforcement in food service and manufacturing drives volume procurement through certified vendor programs. The Department of Labor's recordable injury tracking creates liability pressure for national restaurant chains. Texas and California concentrate demand through franchise density and state-level workers' compensation reforms.
Germany
Industrial manufacturing and automotive assembly plants mandate CE-marked safety footwear under PPE Regulation 2016/425. The Federal Institute for Occupational Safety and Health (BAuA) enforces conformity assessment documentation. Bavaria and Baden-Württemberg anchor production through specialized safety footwear distributors serving Mittelstand manufacturers.
China
Domestic factory safety upgrades and export manufacturing capacity expand dual-market supply. The Standardization Administration of China (SAC) publishes GB standards for occupational footwear aligned with ISO benchmarks. Guangdong and Zhejiang provinces concentrate export-oriented production with SATRA TM144 testing partnerships.
United Kingdom
Hospitality sector recovery and healthcare facility modernization drive replacement demand. The Health and Safety Executive (HSE) enforces slip-risk assessments under the Workplace (Health, Safety and Welfare) Regulations. London and the Southeast concentrate procurement through group purchasing organizations serving NHS trusts and hotel chains.
Japan
Aging workforce demographics and service sector labor shortages elevate ergonomic footwear priorities. The Ministry of Health, Labour and Welfare (MHLW) enforces Industrial Safety and Health Act provisions for protective equipment. The Kanto region around Tokyo concentrates corporate procurement through trading house distribution networks.
Slip Resistant Shoes Market Competitive Landscape
On the supply side, the industry is tiered between mass-market athletic brands, specialized occupational safety manufacturers, and private-label suppliers serving uniform distributors. Athletic-styled safety sneakers are rotating up share rankings through food service chain standardization. Two strategic archetypes dominate: vertically integrated leather boot specialists with captive tanning operations, and biomechanics-driven athletic brands applying sports science to industrial categories. Competitive moves concentrate on ASTM F2913 certification acquisition and direct-to-workforce digital channel development.
Within the athletic-styled segment, Skechers and Nike occupy positions exemplifying comfort-forward design migration into occupational channels. Red Wing Shoe Company anchors the premium boot tier through domestic manufacturing and backward integration into leather supply. These three represent divergent archetypes—mass-market athletic crossover, sports-science industrial extension, and heritage craft manufacturing—each capturing distinct margin pools across food service, healthcare, and heavy industrial end uses.
| Leading Market Players |
|---|
| Skechers |
| Nike |
| Adidas |
| Crocs |
| New Balance |
| Keen |
| Caterpillar |
| Reebok |
| Red Wing Shoe Company |
| Others |
Value Network & Pricing Analysis
Guangdong and Zhejiang province manufacturing clusters anchor global outsole compound supply, concentrating margin capture with certified compounders who command premium positioning downstream through ASTM F2913 testing partnerships and multinational brand relationships.
Pricing Analysis
Prior-generation rubber-dominant constructions, current polyurethane-TPU blend iterations, and next-generation biomechanics-optimized platforms stratify across three performance tiers. Three-tier pricing structure across premium certified, standard compliant, and economy uniform levels separates Red Wing's domestic craft positioning from Skechers' athletic crossover and private-label food service volume. Price differentiation stems from certification grade attainment and captive leather supply control. Cost compression in mid-tier synthetic rubber formulations is intensifying because petroleum input volatility outpaces contract hedging coverage. Quick-service franchise operators exhibit highest price sensitivity, while hospital systems purchasing through GPO contracts demonstrate lowest elasticity.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Pou Chen, Feng Tay, and specialized SATRA-aligned testing facilities across Vietnam and Indonesia. Geographic supply concentration spans China, Vietnam, and Indonesia as brands diversify tariff exposure. Raw material dependencies rest on petroleum-derived synthetic rubbers, chromium-tanned leather hides, and TPU resin feedstocks. Single-source vulnerability in ASTM F2913 third-party laboratory capacity extends certification timelines. Distribution runs through uniform distributors, direct-to-workforce digital platforms, and specialized safety footwear channels serving industrial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASTM F2913 certification mandates and OSHA enforcement digitization are disrupting traditional procurement relationships, compressing vendor consolidation timelines while elevating technical barriers for uncertified suppliers.
For Market Incumbents: Entrench certification moats by accelerating third-party laboratory partnerships to clear ASTM F2913 testing backlogs, while securing captive tannery supply through long-term hide contracts. Athletic-styled sneaker entrants from sports brands threaten heritage boot positioning in food service channels. Backward integration into leather tanning preserves margin pools against synthetic compound price volatility. For New Entrants and Emerging Players: Healthcare facility procurement committees represent the most penetrable entry point, as hospital systems remain underpenetrated relative to food service standardization. Direct-to-workforce digital allowance platforms in Texas and Florida franchise-dense markets offer channel bypass opportunities. Antimicrobial outsole formulations targeting 12-hour nursing shifts provide differentiated positioning against commodity uniform suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed uniform distributors lacking certified footwear technical capabilities and direct digital fulfillment infrastructure. Five-to-ten year viability hinges on regulatory enforcement durability rather than cyclical replacement demand. Watch California and Texas workers' compensation premium incentive expansion as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM F2913 Certification Acceleration | Third-party laboratory partnerships compress 8-12 week testing backlogs for new outsole compounds. |
| Direct-to-Workforce Platform Launch | Employer-subsidized digital catalogs bypass uniform distributor markups in multi-location hospitality chains. |
| Antimicrobial Outsole Development | Specialized formulations target underpenetrated healthcare procurement committees elevating footwear protocols. |
| Backward Integration into Tanning | Captive leather supply insulates margin pools from petroleum-derived synthetic rubber price swings. |
| Polyurethane-TPU Blend Scale-Up | Lightweight material innovation reduces worker fatigue and accelerates replacement cycles in extended-shift environments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food service procurement directors, industrial safety managers, hospital materials management executives, footwear brand product development leads, and third-party certification laboratory technical directors. Secondary validation drew from OSHA enforcement records, ASTM International standards documentation, SATRA testing protocols, state workers' compensation regulatory filings, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, material, and footwear feature dimensions.
Calibration against historical replacement cycle data and certification penetration rates shaped projections across the analysis window. Segmentation dimensions modeled include product architecture, occupational hazard severity, material composition, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted volume trajectories and value-per-unit progression assumptions. Industry-specific forecast inputs incorporated restaurant chain standardization timelines and state-level insurance reform implementation patterns.
Practitioners should monitor ASTM F2913 laboratory capacity expansion, petroleum derivative price indices, and franchise operator digital platform adoption for early signals of supply constraint or demand acceleration. Forecasts reflect documented assumptions regarding OSHA enforcement continuity and certification standard stability. Regulatory enforcement intensity variations, raw material cost spikes, and healthcare procurement committee prioritization shifts present primary revision risks. Quarterly review of certification backlog durations, state workers' compensation legislative calendars, and quick-service chain uniform program RFP activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Training Shoes Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Desert Boots Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Sandals Market
Footwear
Trail Running Shoes Market
Footwear
US Slip Resistant Shoes Market
Footwear
Casual Shoes Market
Footwear
Cowboy Boots Market
Footwear
Athletic Footwear Market
Footwear
E-Commerce Footwear Market
Footwear
Middle East and Africa E-Commerce Footwear Market
Footwear
Snow Boots for Women Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
Winter Footwear Market