
 Winter Footwear Market | 2026-2036
Winter Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Winter Footwear Market Analytics
A shift from single-source Asian manufacturing to multi-source regional production is repositioning supply chain resilience as a competitive priority for winter footwear brands. Wolverine World Wide leverages its domestic factory network to reduce trans-Pacific dependency. Columbia Sportswear anchors its sourcing across Vietnam and Indonesia while testing nearshore alternatives. Deckers Outdoor Corporation specializes in premium sheepskin supply chains that compete on material traceability rather than labor arbitrage.
Winter footwear comprises insulated, weather-resistant closed-toe garments engineered with thermal ratings, waterproof membranes, and lug-pattern outsoles designed to maintain traction and body heat in sub-zero environments. Boots lead product type revenue due to their functional dominance across casual, outdoor, and work usage segments, while wool and synthetic materials are displacing leather in mid-tier lines as thermal efficiency standards tighten. The children's target audience represents a faster-growing segment than adults, driven by replacement frequency and parental safety prioritization.
EU REACH restrictions on perfluorinated compounds directly limit waterproofing chemistries available to manufacturers selling in Europe, while the US Consumer Product Safety Commission governs children's footwear flammability and small-part hazards. ASTM International traction-testing standards increasingly influence B2B procurement by municipal work departments and logistics operators. Stakeholders must monitor evolving chemical compliance thresholds and traction certification requirements to avoid product delisting in regulated channels.
Market Dynamics
EU REACH chemical restrictions on perfluorinated waterproofing compounds are forcing wholesale reformulation of membrane technologies, compressing supplier margins while accelerating R&D cycles across European-facing product lines.
Growth Catalysts
- Alpine tourism infrastructure:Austrian and Swiss ski resort operators are expanding cold-weather gear procurement budgets ahead of winter seasons, directly lifting institutional boot orders.
- Scandinavian per-capita consumption:Norway and Sweden lead replacement frequency for thermal-rated children's boots, where parental safety prioritization sustains above-average unit velocity.
- REACH compliance innovation:Restrictions on footwear adhesives are catalyzing bio-based bonding chemistry development that opens premium positioning for compliant manufacturers.
Market Restraints
- Sheepskin supply concentration:Premium material traceability requirements limit viable tannery sources to Australia and New Zealand, creating input bottlenecks for luxury tiers.
- Membrane chemistry switching costs:Transitioning from PFC-based waterproofing to fluorine-free alternatives requires 18-24 month validation cycles that freeze product pipelines.
- Synthetic thermal fill volatility:Petroleum-derived insulation pricing tracks crude oil indices, compressing margins on mid-tier synthetic-lined boots during energy price spikes.
Strategic Opportunities
- Municipal work department procurement:ASTM International traction certification is becoming a mandatory bid requirement for logistics and public works footwear in North American cities.
- Nearshore manufacturing trials:Brands testing regional production in Portugal and Romania can reduce trans-Pacific lead times while maintaining EU regulatory proximity.
- Children's segment thermal rating standardization:Unmet demand exists for standardized cold-weather performance labeling that would reduce parental purchase friction in retail channels.
Industry Challenges
- Multi-source quality consistency:Splitting production across Asian and European facilities creates lot-to-lot variation in waterproof seam sealing that triggers retailer returns.
- Certification timeline compression:Simultaneous pursuit of ASTM traction ratings and REACH chemical compliance stretches technical teams across incompatible testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winter Footwear Market |
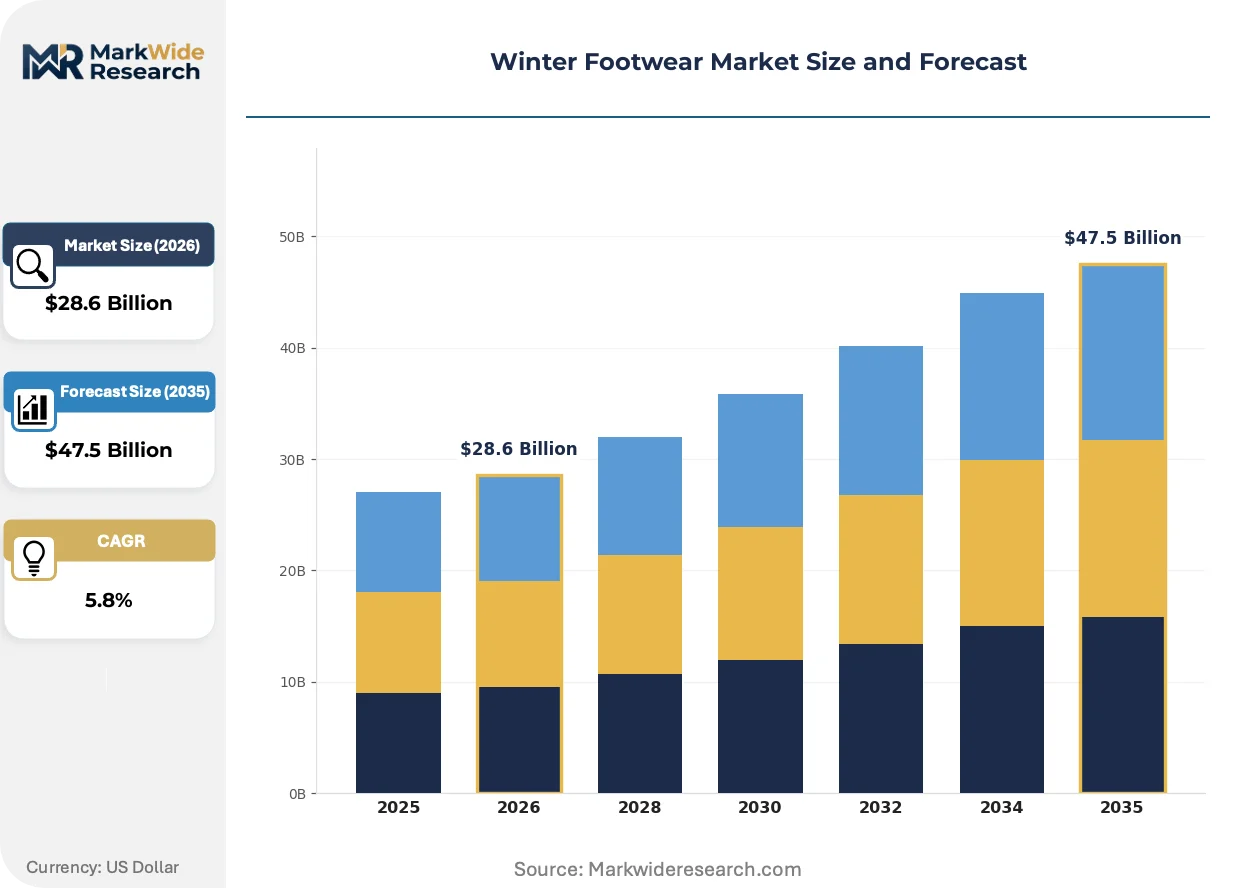
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boots, Sneakers, Slippers, Sandals Material: Leather, Synthetic, Rubber, Wool Target Audience: Adults, Children, Seniors, Athletes Usage: Casual, Outdoor, Work, Fashion |
| Companies Covered | Danner, Wolverine World Wide, SOREL Corporation, Rocky Brands, Merrell, Nike Inc., The North Face, Columbia Sportswear, Deckers Outdoor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winter Footwear Market Evolving Landscape
Bio-based membrane technologies and traction-testing standardization are converging to redefine product differentiation, while procurement patterns among institutional buyers are hardening around certified performance metrics rather than brand heritage.
Fluorine-free durable water repellent chemistries are expanding into membrane laminates previously dependent on perfluorinated compounds. Municipal work departments and alpine rescue services are adopting these reformulated boots ahead of consumer retail. This transition is expanding into premium outdoor segments where environmental claims now command shelf placement priority over legacy waterproofing performance.
EU REACH Annex XVII restrictions on perfluorinated compounds are eliminating established waterproofing chemistries from European market access. Manufacturers must reformulate bonding agents and membrane treatments simultaneously, raising technical qualification costs. Children's footwear faces the tightest compliance windows as the US Consumer Product Safety Commission's small-part testing overlays chemical safety requirements.
Institutional procurement is consolidating around ASTM F2913 traction certification as a gatekeeping standard for municipal and logistics contracts. Direct-to-operator sales channels are displacing traditional wholesale relationships for work-boot categories. This concentration is most visible in Scandinavian countries where public sector purchasing cooperatives aggregate demand across national borders.
Winter Footwear Market Segmentation
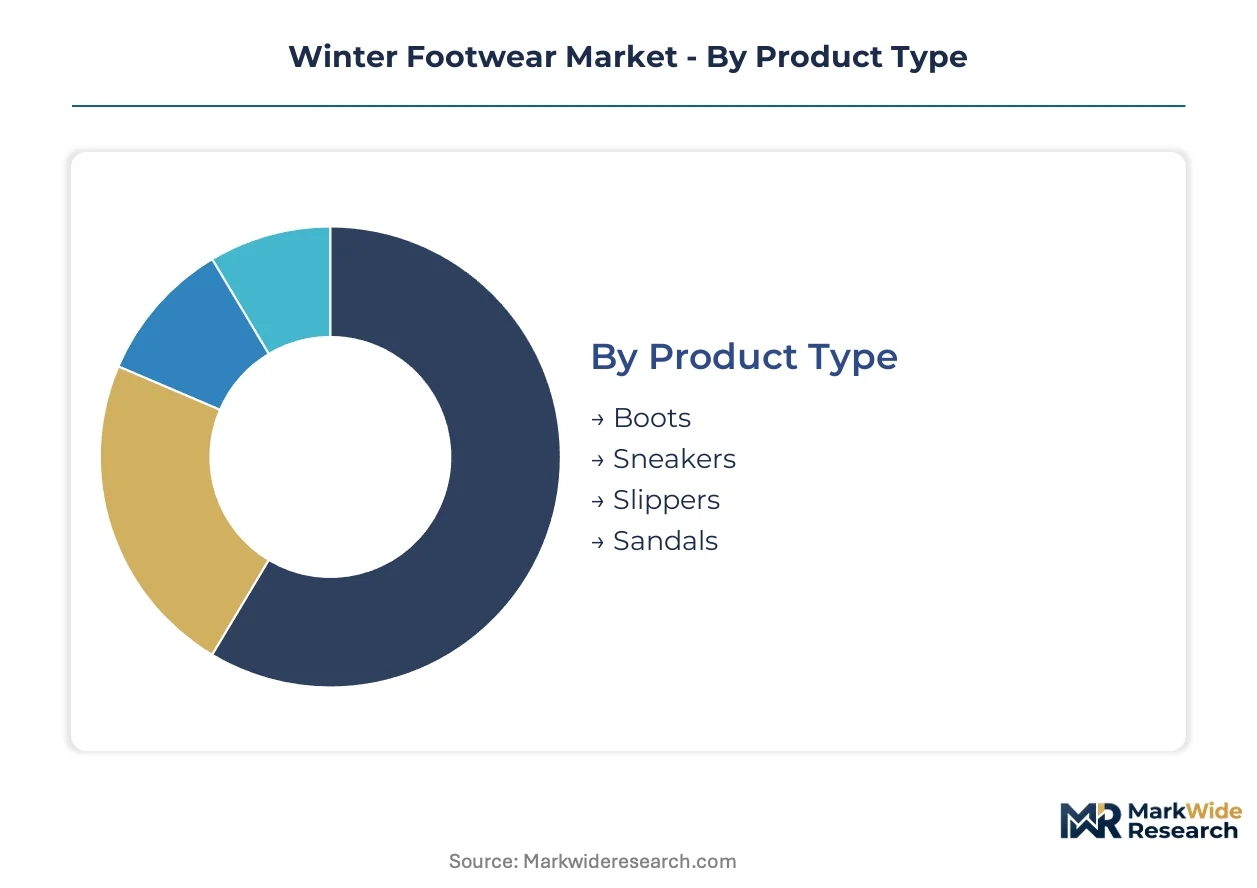
Winter footwear segmentation reveals distinct replacement cycles across product categories, with thermal performance requirements driving upgrade frequency in cold-climate regions. Material compliance costs and traction certification standards are reshaping how manufacturers prioritize segment development.
Product Type:
Replacement cycles vary dramatically by product type, with functional outdoor categories demanding more frequent thermal-rated upgrades than indoor alternatives.
- Boots:Insulated closed-toe garments engineered with thermal ratings, waterproof membranes, and lug-pattern outsoles for sub-zero traction. Norwegian and Swedish municipal procurement departments prioritize ASTM-certified work boots for logistics and public works crews, driving institutional volume concentration.
- Sneakers:Low-profile thermal-lined casual footwear with synthetic uppers and EVA midsoles. Austrian and Swiss alpine tourism operators are expanding cold-weather sneaker procurement for hospitality staff uniforms, lifting B2B orders ahead of winter seasons.
- Slippers:Indoor thermal footwear with shearling or synthetic pile linings. Sheepskin supply concentration in Australia and New Zealand tanneries limits premium tier scaling.
- Sandals:Open-toe designs with minimal winter application, primarily confined to heated indoor environments and spa hospitality segments in Nordic markets.
Boots sit at the top of the volume ranking, with sneakers climbing the fastest.
Material:
Cost tier stratification separates premium natural materials from mid-tier synthetics, with compliance costs compressing margins on petroleum-derived options.
- Leather:Traditional full-grain and nubuck uppers with natural water resistance. EU REACH Annex XVII restrictions on tanning chemistries are forcing tannery reformulation, raising qualification costs for European market access.
- Synthetic:Petroleum-derived PU and polyester textiles with membrane laminates. Pricing volatility tracks crude oil indices, compressing margins during energy price spikes.
- Rubber:Molded outsoles and waterproof shell constructions. ASTM F2913 traction certification requirements are hardening as mandatory bid criteria for North American municipal contracts.
- Wool:Natural fiber insulation and felted uppers with biodegradable end-of-life profiles. Scandinavian parental safety prioritization sustains above-average replacement frequency for children's wool-lined boots.
Leather commands the premium tier by revenue, with wool gaining share fastest.
Target Audience:
Customer type determines thermal rating standardization needs, with children's segments showing unmet demand for performance labeling that reduces purchase friction.
- Adults:Mass-market thermal footwear with work-casual crossover designs. Multi-source manufacturing quality consistency challenges create lot-to-lot waterproof seam variation.
- Children:Rapid replacement frequency driven by foot growth and parental safety prioritization. US Consumer Product Safety Commission small-part testing overlays EU REACH chemical requirements, tightening compliance windows.
- Seniors:Stability-focused designs with slip-resistant outsoles and easy-entry closures. ASTM traction standards increasingly influence retail channel positioning for fall-prevention claims.
- Athletes:Performance-oriented cold-weather training footwear with moisture-wicking liners. Bio-based membrane development opens premium positioning for fluorine-free alternatives.
Adults generate the largest absolute volume, with children expanding most quickly.
Usage:
Application context dictates certification requirements, with work and outdoor segments hardening around institutional procurement standards.
- Casual:Everyday thermal footwear prioritizing comfort over technical performance. Nearshore manufacturing trials in Portugal and Romania target reduced trans-Pacific lead times.
- Outdoor:Technical alpine and backcountry designs with rated temperature limits. Alpine rescue services in Austria and Switzerland are adopting fluorine-free membrane boots ahead of consumer retail channels.
- Work:Safety-rated boots with ASTM traction certification and composite toe protection. Municipal procurement cooperatives in Scandinavia aggregate cross-border demand, consolidating direct-to-operator sales channels.
- Fashion:Aesthetic-driven designs with minimal functional thermal engineering. Material traceability claims now command shelf placement priority over legacy waterproofing performance.
Work applications anchor institutional procurement volume, with outdoor showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Scandinavian cluster anchored by Norway and Sweden drives per-capita consumption intensity through parental safety prioritization and municipal procurement standardization. Alpine tourism corridors in Austria and Switzerland lift institutional cold-weather gear orders ahead of winter seasons. Manufacturing trials in Portugal and Romania test nearshore alternatives to trans-Pacific dependency.
United States
Municipal work departments in Chicago and Minneapolis mandate ASTM F2913 traction certification for logistics and public works footwear contracts. The US Consumer Product Safety Commission governs children's footwear flammability and small-part hazards, tightening compliance windows for imported products. Wolverine World Wide leverages its domestic factory network to reduce trans-Pacific lead times while serving institutional buyers.
Norway
Public sector purchasing cooperatives aggregate cross-border demand for thermal-rated children's boots across Nordic municipalities. EU REACH Annex XVII restrictions on perfluorinated compounds eliminate established waterproofing chemistries from market access. Bergen and Oslo anchor retail concentration where standardized cold-weather performance labeling reduces parental purchase friction.
Germany
Industrial safety footwear procurement by logistics operators in the Ruhr region hardens around traction certification requirements. ECHA enforcement of REACH chemical restrictions on footwear adhesives accelerates bio-based bonding chemistry development. Bavarian tanneries face reformulation costs as tanning chemistry qualifications rise for European market access.
Austria
Alpine tourism operators in Tyrol and Salzburg expand cold-weather gear procurement budgets ahead of winter hospitality seasons. EU REACH compliance timelines compress product development cycles for membrane technologies facing fluorine-free transitions. Innsbruck clusters institutional buyers adopting reformulated boots ahead of consumer retail channels.
Switzerland
Alpine rescue services in Graubünden and Valais adopt fluorine-free membrane boots before consumer market penetration. Swissmedic-aligned material traceability requirements limit viable tannery sources for premium tiers to Australia and New Zealand supply chains. Zurich concentrates direct-to-operator sales channels displacing traditional wholesale relationships.
Winter Footwear Market Competitive Landscape
Global majors compete with regional champions across certification standards and supply chain proximity rather than scale alone. The vendor base organizes around three tiers: diversified outdoor conglomerates with multi-brand portfolios, specialized cold-weather houses with material traceability positioning, and contract manufacturers serving institutional procurement channels. Two dominant competitive moves reshape positioning: backward integration into captive membrane development and geographic expansion through nearshore production trials in Southern Europe.
Within the diversified outdoor tier, Columbia Sportswear and The North Face exemplify multi-source sourcing strategies across Vietnam and Indonesia while testing regulatory proximity through Portuguese manufacturing. Deckers Outdoor Corporation occupies a distinct position built on premium material supply chains that compete on traceability rather than labor arbitrage. Wolverine World Wide anchors the institutional work-boot segment through domestic factory networks serving ASTM-certified municipal contracts.
| Leading Market Players |
|---|
| Danner |
| Wolverine World Wide |
| SOREL Corporation |
| Rocky Brands |
| Merrell |
| Nike Inc. |
| The North Face |
| Columbia Sportswear |
| Deckers Outdoor Corporation |
| Others |
Value Network & Pricing Analysis
Portuguese membrane-lamination specialists in the Porto industrial corridor anchor premium-tier production, where labor-cost differentials against Vietnamese assembly widen pricing-tier spreads between ASTM-certified work boots and unlabeled casual alternatives.
Pricing Analysis
Input-cost pass-through from petroleum-derived synthetic insulation and Australian sheepskin tanneries drives three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on ASTM F2913 traction certification grade and EU REACH chemical compliance status, with certified institutional work boots commanding substantial premiums over casual retail alternatives. Pricing pressure stems from crude oil volatility compressing margins on mid-tier synthetic-lined products. Municipal procurement departments show lowest price sensitivity due to safety-liability considerations, while mass-market casual consumers exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows from retailer waterproof-seam failure returns concentrate refurbishment activity in Romanian contract facilities serving European distribution networks. Manufacturing concentrates in Vietnam, Indonesia, and Portugal, with sheepskin supply tethered to Australian and New Zealand tanneries. Raw material dependencies include petroleum-derived thermal fills, fluorine-free membrane laminates, and chrome-free tanning agents. Single-source vulnerability in premium sheepskin traceability creates input bottlenecks for luxury tiers. Distribution runs through direct-to-operator municipal procurement cooperatives in Scandinavia alongside traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with parental safety prioritization and institutional certification requirements shifting demand toward premium thermal-rated specifications.
For Market Incumbents: Lock in ASTM traction certification advantages by accelerating captive membrane development before fluorine-free chemistry patents consolidate. Defend margin position through backward integration into Portuguese nearshore production, insulating against trans-Pacific logistics volatility and EU REACH compliance timeline compression. For New Entrants and Emerging Players: Bio-based bonding chemistry development offers a technology-first wedge into premium outdoor segments where environmental claims command shelf placement priority. White-space targets include standardized children's thermal rating labeling in Nordic retail channels and fluorine-free membrane supply to Alpine rescue services. A direct-to-municipality go-to-market angle bypasses entrenched wholesale relationships. For Investors and Strategic Acquirers: Specialized cold-weather houses with material traceability positioning are the most active acquirer targets in this space for diversified outdoor conglomerates seeking premium-tier expansion. Long-term viability hinges on regulatory compliance capabilities rather than scale alone. Watch for ECHA enforcement acceleration on perfluorinated compound deadlines as an inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Membrane Development | Fluorine-free chemistry patents differentiate premium tiers from reformulation-lagged competitors. |
| Nearshore Manufacturing Trials | Portuguese and Romanian facilities reduce EU REACH compliance timelines versus Asian supply chains. |
| ASTM Certification Investment | Municipal procurement cooperatives in Chicago and Oslo mandate F2913 traction ratings as bid gatekeepers. |
| Material Traceability Programs | Australian and New Zealand sheepskin sourcing claims command shelf placement in Swissmedic-aligned channels. |
| Direct-to-Operator Sales Channels | Scandinavian public sector purchasing cooperatives aggregate cross-border demand, displacing traditional wholesale. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged brand managers at diversified outdoor conglomerates, category buyers at Scandinavian retail cooperatives, procurement leads at Alpine tourism operators, and technical R&D directors at membrane suppliers. Secondary validation drew from customs and trade data, SEC 10-K footwear segment disclosures, ECHA REACH restriction updates, and ASTM International certification registries. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Comparable-period historical analysis anchored projections across the modeling period. The analytical framework modeled volume and value trajectories by product type, material grade, target audience demographic, and usage application, with thermal rating standardization tracked as a cross-cutting dimension. CAGRs derived from regression-based trend extrapolation adjusted for regulatory phase-in schedules and institutional procurement cycle timing. Forecast inputs incorporated crude oil price indices for synthetic fill costs and sheepskin auction price trends from Australian tannery exchanges.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA enforcement acceleration, petroleum price volatility, and Alpine tourism infrastructure investment cycles. Practitioners should monitor fluorine-free membrane validation timelines and municipal traction certification mandate expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Sneaker Boots Market
Footwear
US Slip Resistant Shoes Market
Footwear
Football Shoes Market
Footwear
Slip Resistant Shoes Market
Footwear
Platform Boots Market
Footwear
Asia Pacific Footwear Market
Footwear
Global Footwear Market
Footwear
Tactical Footwear Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
UGG Boots Market
Footwear
Refurbished Running Shoes Market
Footwear
Luxury Footwear Market
Footwear
Ankle Boots Market
Footwear
Premium Shoes Market
Footwear
Leather Footwear Market