
 GCC Footwear Market | 2026-2036
GCC Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Footwear Market Intelligence
Retail buyer concentration across the Gulf is consolidating as mega-mall operators and omnichannel platforms gain procurement leverage over suppliers. Nike, Inc. leverages its direct-to-consumer infrastructure to sustain premium positioning in Dubai and Riyadh flagship locations. Adidas AG anchors its regional competitiveness through localized product lines adapted to Gulf climate conditions and cultural preferences. Skechers USA, Inc. competes aggressively on value-tier positioning across family-oriented retail channels.
Footwear encompasses protective, athletic, casual, and formal apparel designed for human locomotion, typically constructed from leather, synthetic polymers, rubber compounds, or textile uppers with molded or stitched soles. Manufacturing employs cemented, stitched, or injection-molded assembly processes to achieve specified flex resistance, abrasion thresholds, and moisture management performance. Sneakers dominate volume flows across the GCC, while leather dress shoes command concentrated margin pools in professional and ceremonial segments. The synthetic material category captures expanding share as manufacturers reformulate polyurethane and thermoplastic elastomer compounds for desert heat durability. Specialty stores and online platforms represent the fastest-growing distribution channels as digital payment penetration deepens across Kuwait, Qatar, and the UAE.
Saudi Standards, Metrology and Quality Organization (SASO) mandates conformity assessment for imported footwear, while the UAE's Ministry of Industry and Advanced Technology enforces technical regulations on chemical content and labeling transparency. The Gulf Cooperation Council's unified customs framework streamlines cross-border circulation but requires unified compliance documentation across member states. Stakeholders must monitor evolving sustainability disclosure obligations as Saudi Arabia and the UAE integrate circular economy principles into national industrial strategies.
Market Dynamics
Vision 2030 retail infrastructure investments across Saudi Arabia are fundamentally restructuring footwear demand patterns, pulling volume toward experiential mall formats and accelerating direct-to-consumer channel development.
Growth Catalysts
- SASO Conformity Assessment:Saudi Arabia's unified technical regulations streamline import documentation across the GCC customs union, reducing cross-border clearance friction for compliant suppliers.
- Synthetic Material Reformulation:Thermoplastic elastomer compounds engineered for desert heat durability are expanding addressable use-cases in outdoor and athletic segments previously dominated by leather.
- Women's Public Life Participation:Social reforms enabling expanded female workforce and recreational access are generating incremental demand for professional and leisure footwear categories.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane and synthetic rubber input costs fluctuate with regional petrochemical pricing, compressing margin predictability for mid-tier manufacturers.
- Compliance Cost Escalation:UAE Ministry of Industry and Advanced Technology mandatory labeling requirements elevate testing and certification expenditures for imported inventory.
- Leather Substitution Pressure:Performance-engineered textiles and bio-based synthetics are displacing traditional leather in formal segments, threatening established tanning supply relationships.
Strategic Opportunities
- Kuwait Digital Payment Penetration:E-wallet and BNPL infrastructure maturity enables pure-play online footwear platforms to bypass capital-intensive flagship retail.
- Circular Economy Integration:Saudi Arabia and UAE national industrial strategies are embedding sustainability disclosure obligations that reward early movers with procurement preference.
- Climate-Adapted Product Lines:Breathable mesh constructions combined with moisture-wicking linings address unmet performance needs in high-humidity coastal environments.
Industry Challenges
- Conformity Assessment Timeline Compression:SASO certification cycles for seasonal collections create inventory deployment risks against fashion-calendar deadlines.
- Last-Mile Temperature Control:Synthetic sole compounds require climate-controlled logistics infrastructure that remains underdeveloped outside Dubai, Riyadh, and Jeddah corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Footwear Market |
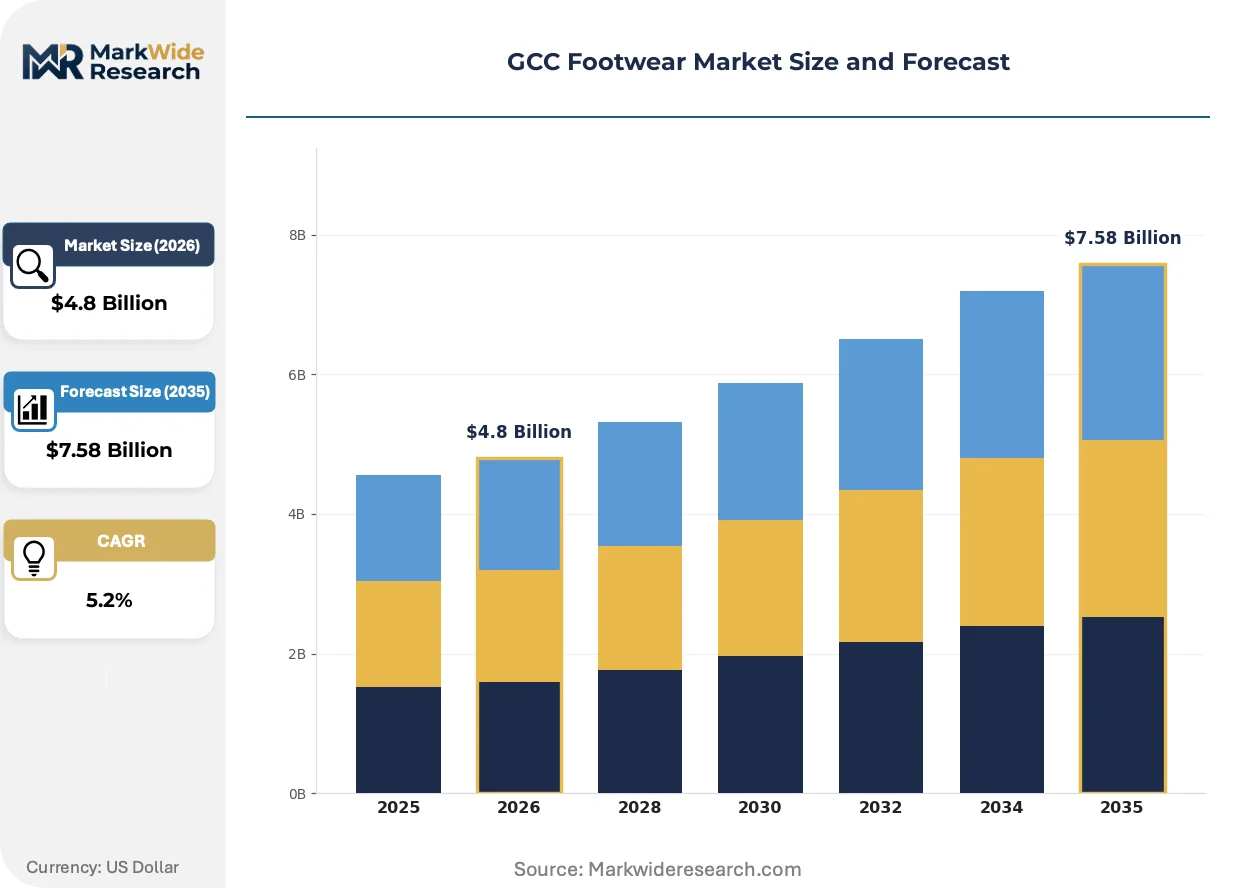
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sneakers, Sandals, Boots, Dress Shoes Material: Leather, Synthetic, Rubber, Textile End User: Men, Women, Children, Athletes Distribution Channel: Retail Stores, Online, Supermarkets, Specialty Stores |
| Companies Covered | Nike, Inc., Adidas AG, Puma SE, Skechers USA, Inc., ASICS Corporation, New Balance Athletics, Inc., Under Armour, Inc., Crocs, Inc., ECCO Sko A/S, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Footwear Market Strategic Shifts & Innovations
Digital payment infrastructure maturity and regulatory sustainability mandates are converging to reshape how footwear reaches Gulf consumers, compressing traditional wholesale intermediation.
3D foot-scanning and automated last-matching technology is consolidating fit-prediction accuracy across e-commerce platforms. Regional pure-play retailers are deploying smartphone-based sizing tools to reduce return rates on high-value athletic imports. This capability compression is enabling inventory-light marketplace models to challenge capital-heavy flagship operators.
SASO and UAE Ministry of Industry technical regulations on chemical content and labeling transparency are tightening import gateway controls. Manufacturers must reformulate adhesives and dyes to meet restricted substance lists, elevating R&D expenditure for Gulf-bound production. Mid-tier suppliers without captive testing facilities face exclusion from tender processes with mega-mall anchor tenants.
Family-oriented retail channels are fragmenting as hypermarket operators consolidate footwear procurement under private-label programs. Value-tier brands now compete for shelf space against captive imports sourced through direct Asian manufacturing relationships. Qatar and Bahrain markets exhibit this pattern most acutely, where retail buyer concentration has advanced fastest.
GCC Footwear Market Segmentation
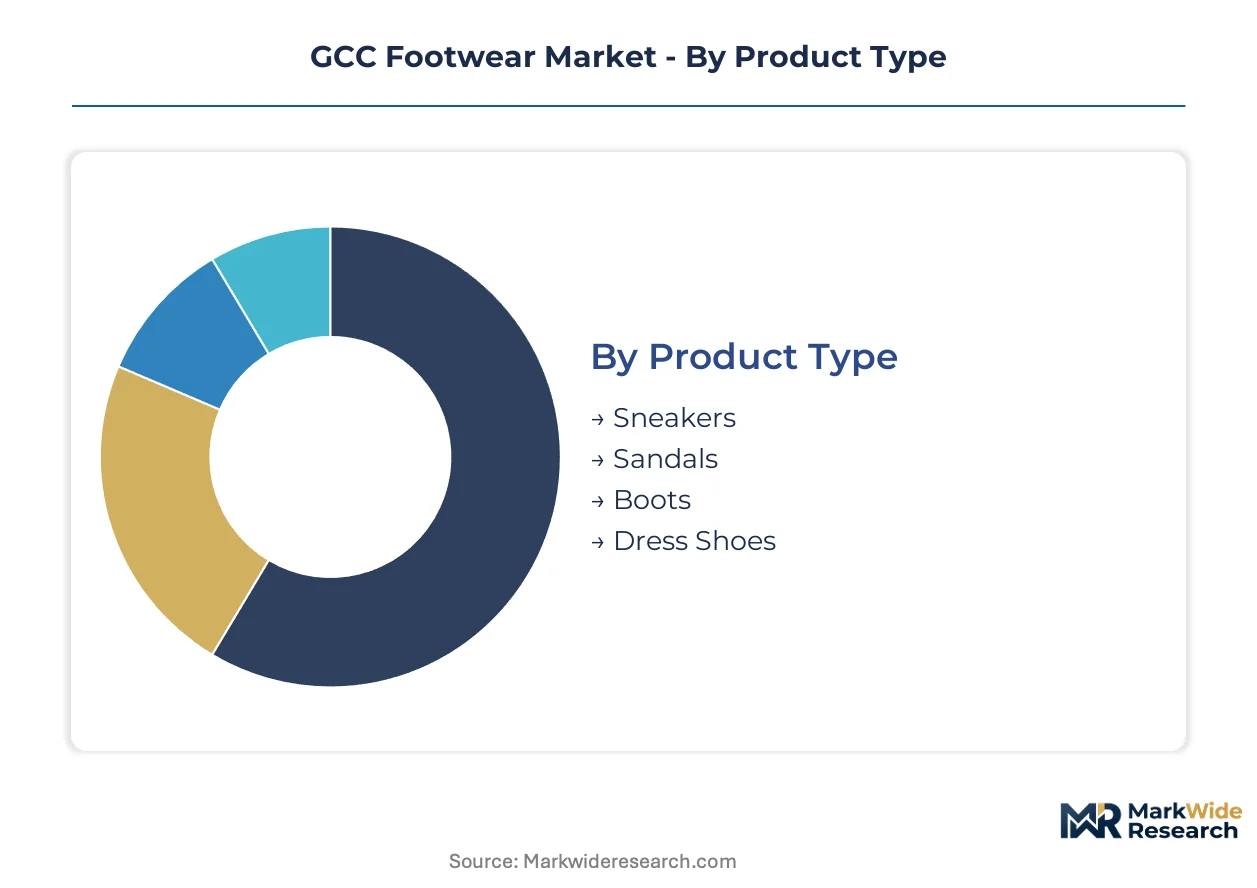
Footwear purchasing decisions across the GCC diverge sharply by occasion, climate exposure, and social context. Manufacturers must align product architecture with distinct performance expectations and distribution access patterns.
Product Type:
Usage occasion and climate exposure drive category selection across Gulf consumer segments.
- Sneakers:Athletic and lifestyle constructions dominate volume flows through mall-based retail and direct-to-consumer platforms. Saudi Arabia's Vision 2030 retail infrastructure investments pull sneaker demand toward experiential flagship formats in Riyadh and Jeddah.
- Sandals:Open-toe designs engineered for desert heat tolerance capture sustained demand across casual and traditional wear occasions. UAE consumers exhibit preference for premium leather variants in professional contexts where climate-controlled environments permit.
- Boots:Protective and fashion-forward constructions serve industrial safety requirements and seasonal fashion cycles. Construction activity across Qatar and Kuwait generates specialized demand for steel-toe safety specifications.
- Dress Shoes:Formal leather constructions maintain ceremonial and professional relevance despite synthetic substitution pressure. Saudi corporate environments sustain concentrated margin pools for Italian and British imported bench-grade footwear.
Volume sits with Sneakers; growth tilts toward Sandals as climate-adapted casualization accelerates.
Material:
Performance specifications and cost architecture determine material selection for Gulf-bound production.
- Leather:Full-grain and corrected-grain hides from European tanneries supply formal and premium casual segments. Bahrain and Qatar retail buyers concentrate procurement of bench-grade leather footwear for luxury mall positioning.
- Synthetic:Thermoplastic elastomer and polyurethane compounds engineered for desert heat durability are displacing leather in athletic and outdoor categories. SASO chemical content regulations mandate reformulation of adhesives and dyes for Gulf-bound synthetic production.
- Rubber:Molded sole compounds and full-rubber constructions address industrial safety and water-exposure requirements. Kuwait's petrochemical feedstock availability supports regional compounding operations for vulcanized footwear components.
- Textile:Breathable mesh and woven upper materials enable moisture management in high-humidity coastal environments. UAE technical standards on labeling transparency elevate certification costs for textile-heavy imports.
Margin concentrates in Leather; expansion velocity favors Synthetic as manufacturers optimize for heat durability and regulatory compliance.
End User:
Demographic access patterns and social participation reforms are restructuring demand composition.
- Men:Established purchasing patterns across formal, athletic, and traditional categories sustain volume concentration. Saudi male workforce participation supports steady replacement demand for professional footwear.
- Women:Social reforms enabling expanded public life participation are generating incremental demand for professional and leisure categories. Dubai and Riyadh retail operators report accelerating women's athletic footwear attachment rates.
- Children:Growth-driven replacement cycles and school uniform requirements create predictable seasonal demand patterns. Family-oriented retail channels in Qatar and Kuwait concentrate volume through back-to-school procurement windows.
- Athletes:Performance-specified constructions for organized sport and fitness activity represent specialized demand with premium pricing tolerance. UAE investment in sports infrastructure ahead of major events pulls specialized athletic imports.
Established volume rests with Men; the steepest expansion trajectory attaches to Women as workforce and recreational access broadens.
Distribution Channel:
Capital requirements and customer acquisition economics determine channel viability for brand positioning.
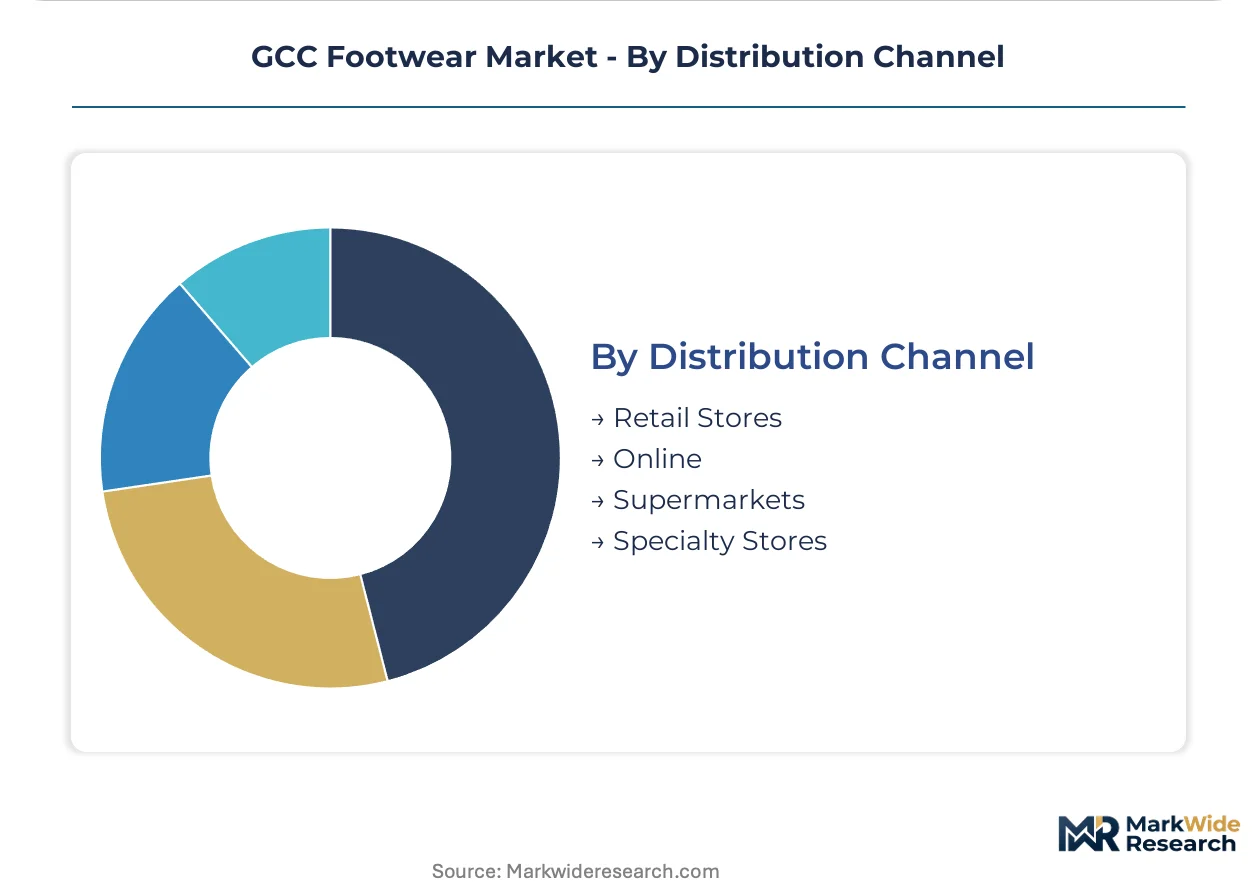
- Retail Stores:Mall-based flagship and department store concessions sustain premium brand visibility across Saudi Arabia and the UAE. Mega-mall operator consolidation is elevating procurement leverage over supplier terms.
- Online:Pure-play platforms and marketplace integrations are gaining share as digital payment infrastructure matures across Kuwait and Qatar. Return rate compression through 3D foot-scanning technology is improving unit economics.
- Supermarkets:Value-tier volume concentrates through hypermarket private-label programs and direct Asian sourcing relationships. Bahrain and Qatar exhibit the most advanced retail buyer concentration in this channel.
- Specialty Stores:Verticalized athletic and luxury footwear retailers command differentiated access to enthusiast segments. Climate-controlled logistics requirements limit specialty store expansion outside Dubai, Riyadh, and Jeddah corridors.
Transaction volume flows through Retail Stores; share gain velocity favors Online as BNPL infrastructure deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia concentrates the strongest demand pull across the GCC, with retail infrastructure investments and rising disposable incomes reshaping footwear consumption patterns throughout the Gulf.
Saudi Arabia
Vision 2030 retail investments and female workforce participation expansion drive demand across professional and leisure categories. SASO mandates conformity assessment for all imported footwear, streamlining cross-border documentation within the GCC customs union. Riyadh and Jeddah anchor experiential mall development, pulling sneaker volume toward flagship retail formats.
United Arab Emirates
Dubai's mega-mall operators and digital payment maturity sustain premium brand positioning across omnichannel platforms. The Ministry of Industry and Advanced Technology enforces technical regulations on chemical content and labeling transparency, elevating compliance costs for imported inventory. Dubai International Financial Centre corridor concentrates climate-controlled logistics infrastructure for synthetic sole compounds.
Kuwait
E-wallet and BNPL infrastructure maturity enables pure-play online platforms to bypass capital-intensive flagship retail. The central bank's regulatory framework supports digital payment penetration, reducing friction for marketplace models. Kuwait City retail clusters exhibit accelerating procurement consolidation under hypermarket private-label programs.
Qatar
Construction activity and sports infrastructure investment ahead of major events generate specialized demand for protective and athletic footwear specifications. The Qatar Central Bank oversees financial regulations affecting retail payment systems. Doha retail corridors show advanced buyer concentration, with family-oriented channels fragmenting under direct Asian sourcing relationships.
Bahrain
Luxury mall positioning and bench-grade leather procurement concentrate demand among premium retail buyers. The national standards body enforces import conformity requirements aligned with GCC technical regulations. Manama retail clusters sustain ceremonial and professional footwear relevance despite synthetic substitution pressure in formal segments.
GCC Footwear Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital-native positioning and climate-adapted product lines. The vendor base stratifies across three tiers: global athletic brands with direct-to-consumer infrastructure, European heritage houses commanding formal segment margins, and value-tier specialists competing through family retail channels. Two dominant competitive moves define current dynamics: mega-mall operators consolidating procurement leverage over supplier terms, and manufacturers reformulating synthetic compounds for desert heat durability to expand addressable use-cases.
Within the global athletic archetype, Nike, Inc. and Adidas AG exemplify premium positioning through flagship retail infrastructure and localized product adaptation. Skechers USA, Inc. occupies a position within the value-tier vector, competing aggressively across family-oriented retail channels. These three entities represent distinct strategic postures: direct-to-consumer premium anchoring, climate-adapted technical specialization, and volume-driven value penetration.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Puma SE |
| Skechers USA, Inc. |
| ASICS Corporation |
| New Balance Athletics, Inc. |
| Under Armour, Inc. |
| Crocs, Inc. |
| ECCO Sko A/S |
| Others |
Cost & Logistics Intelligence
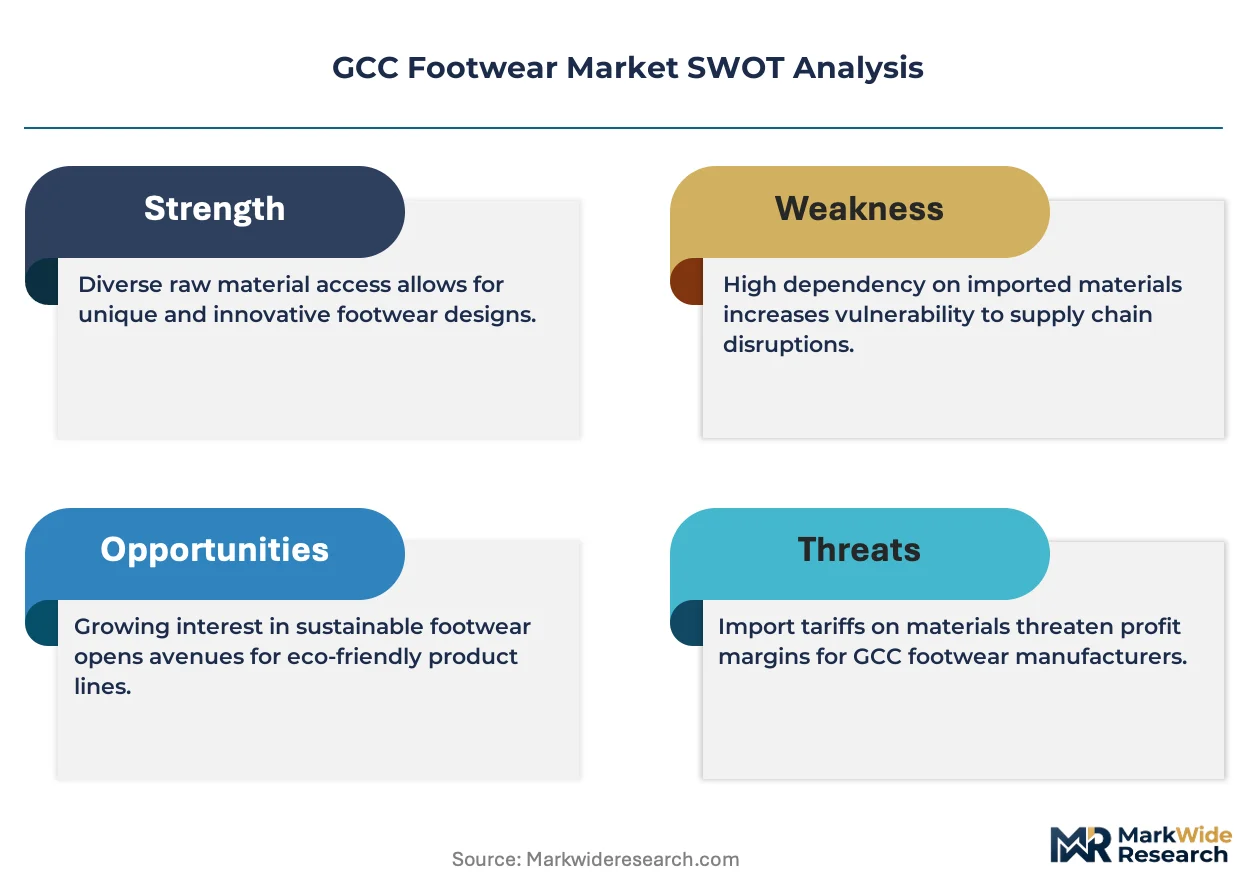
Captive control over synthetic compound formulation anchors both supply security and pricing power for Gulf-bound footwear manufacturers. SASO chemical content mandates and UAE labeling transparency requirements elevate compliance investment thresholds, compressing margin flexibility for suppliers without in-house testing infrastructure.
Pricing Analysis
Volume concentrates in value-tier family footwear while margin pools in premium athletic and formal leather segments. Three-tier pricing structure across premium, standard, and economy levels separates flagship retail positioning from hypermarket private-label penetration. Price differentiation hinges on certification grade completion and after-sales service bundling. Cost compression in synthetic material tiers is intensifying because petrochemical feedstock volatility erodes predictability for mid-tier manufacturers. Hypermarket procurement teams in Qatar and Bahrain exhibit the sharpest price sensitivity, while specialty athletic retailers in Dubai sustain premium tolerance.
Supply Chain Analysis
Petrochemical feedstock supply rests on Saudi Arabia and Kuwait's regional compounding infrastructure for polyurethane and thermoplastic elastomer inputs. Manufacturing draws from Vietnam, China, and Bangladesh for finished assembly, with European tanneries supplying full-grain hides for formal segments. Single-source vulnerability concentrates in desert-heat adhesive formulations certified for SASO compliance. Distribution runs through Dubai, Riyadh, and Jeddah climate-controlled logistics corridors before final-mile deployment to mega-mall operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC footwear market reads as a cost-of-compliance story where SASO conformity assessment creates a barrier-to-entry moat for suppliers with captive testing facilities and reformulation capabilities.
For Market Incumbents: Deepen backward integration into thermoplastic elastomer compounding to secure heat-durability formulation control against petrochemical price volatility. Fortify procurement relationships with mega-mall anchor tenants by pre-positioning seasonal inventory ahead of SASO certification cycles. Synthetic substitution pressure in formal segments demands accelerated R&D in bio-based leather alternatives to defend bench-grade positioning.
For New Entrants and Emerging Players: Kuwait's e-wallet and BNPL infrastructure maturity opens a window for pure-play online platforms to bypass capital-intensive flagship retail. Target women's athletic footwear in Saudi Arabia as workforce participation reforms generate incremental demand with premium pricing tolerance. Deploy smartphone-based 3D foot-scanning technology to compress return rates and improve marketplace unit economics.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by global athletic brands seeking direct-to-consumer infrastructure in Riyadh and Dubai. Long-term viability favors vertically integrated manufacturers with in-house SASO certification capabilities and synthetic compound formulation expertise. Watch for inflection where circular economy disclosure obligations in Saudi Arabia and the UAE trigger procurement preference shifts toward sustainability-certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Adapted Product Line Extension | Breathable mesh constructions with moisture-wicking linings capture unmet demand in UAE coastal humidity. |
| Direct-to-Consumer Platform Launch | Flagship retail bypass in Kuwait leverages BNPL infrastructure to reduce customer acquisition costs. |
| SASO Certification Pre-Positioning | Seasonal inventory deployment ahead of conformity assessment cycles mitigates fashion-calendar deadline risk. |
| Synthetic Compound Backward Integration | In-house thermoplastic elastomer formulation secures margin control against petrochemical feedstock volatility. |
| Circular Economy Sustainability Repositioning | Early compliance with Saudi Arabia and UAE disclosure obligations secures mega-mall procurement preference. |
Research Approach
Multi-period observation of mega-mall procurement consolidation, digital payment penetration rates, and SASO regulatory enforcement anchored the trend analysis, supplemented by interviews with footwear brand managers, category buyers at Gulf retailers, synthetic material procurement leads, and logistics operators. Secondary validation drew from customs and trade data, SEC filings of listed footwear manufacturers, GCC technical regulation publications, and retail audit databases. Bottom-up demand modeling across product type, material, end user, and distribution channel dimensions was cross-checked against top-down macroeconomic indicators.
Segment-weighting approaches applied differential growth assumptions across women's workforce participation expansion zones, climate-adapted product adoption curves, and digital payment maturity corridors. CAGRs were derived from trend extrapolation moderated by regulatory compliance cost trajectories and petrochemical feedstock price elasticity. Forecast inputs incorporated Vision 2030 retail infrastructure investment flows and circular economy policy integration timelines across member states.
Caveats apply where petrochemical price volatility, SASO certification timeline compression, or last-mile logistics infrastructure gaps could materially shift the outlook. A small set of named triggers warrants ongoing watch: synthetic material substitution rates in formal segments, mega-mall operator procurement leverage escalation, and sustainability disclosure obligation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Casual Shoes Market
Footwear
Protective Footwear Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Europe Athletic Footwear Market
Footwear
Light Up Shoes Market
Footwear
Refurbished Sneaker Market
Footwear
Golf Footwear Market
Footwear
Desert Boots Market
Footwear
Water Shoes Market
Footwear
Leather Sneakers Market
Footwear
Women's Sneakers Market
Footwear
Dance Shoes Market
Footwear
Loafers Market
Footwear
South America Athletic Footwear Market
Footwear
Cyber-Shoes Market
Footwear
PU Sole (Footwear Polyurethane) Market