
 White Sneakers Market | 2026-2036
White Sneakers Market Size, Share, and Industry Trends Forecast 2026-2036
White Sneakers Market Analytics
Digital knitting and automated last-forming technology is tilting production economics toward smaller batch sizes with faster turnaround cycles. Nike, Inc. leverages proprietary Flyknit-derived architectures to reduce material waste in white sneaker uppers. Adidas AG anchors its competitive stance through Speedfactory-adjacent automation partnerships that compress lead times for replenishment orders. New Balance Athletics, Inc. differentiates via domestic manufacturing scale in the northeastern United States, where it controls regional distribution velocity.
White sneakers are closed-toe athletic-casual footwear constructed with rubber or EVA outsoles, textile or leather uppers, and lace or slip-on closure systems, designed for urban mobility, gym crossover, and uniform-adjacent workplace dress codes. Low-top and platform variants currently occupy the largest volume positions, while mesh and synthetic material segments capture disproportionate margin expansion as brands reformulate for lighter weight and improved breathability. Unisex and women-targeted sizing architectures represent the fastest-growing demand pools, reflecting silhouette diversification beyond traditional men's athletic lasts.
REACH in Europe, the EPA's chemical emissions frameworks in the United States, and California's Proposition 65 disclosure requirements collectively govern volatile organic compound limits, adhesive chemistry, and end-of-life labeling obligations that shape supplier qualification and retail market access. Brands must monitor how these standards cascade through tier-two material vendors. Stakeholders should track which regulatory filing deadlines force reformulation cycles, as compliance lead times increasingly determine seasonal go-to-market windows.
Market Dynamics
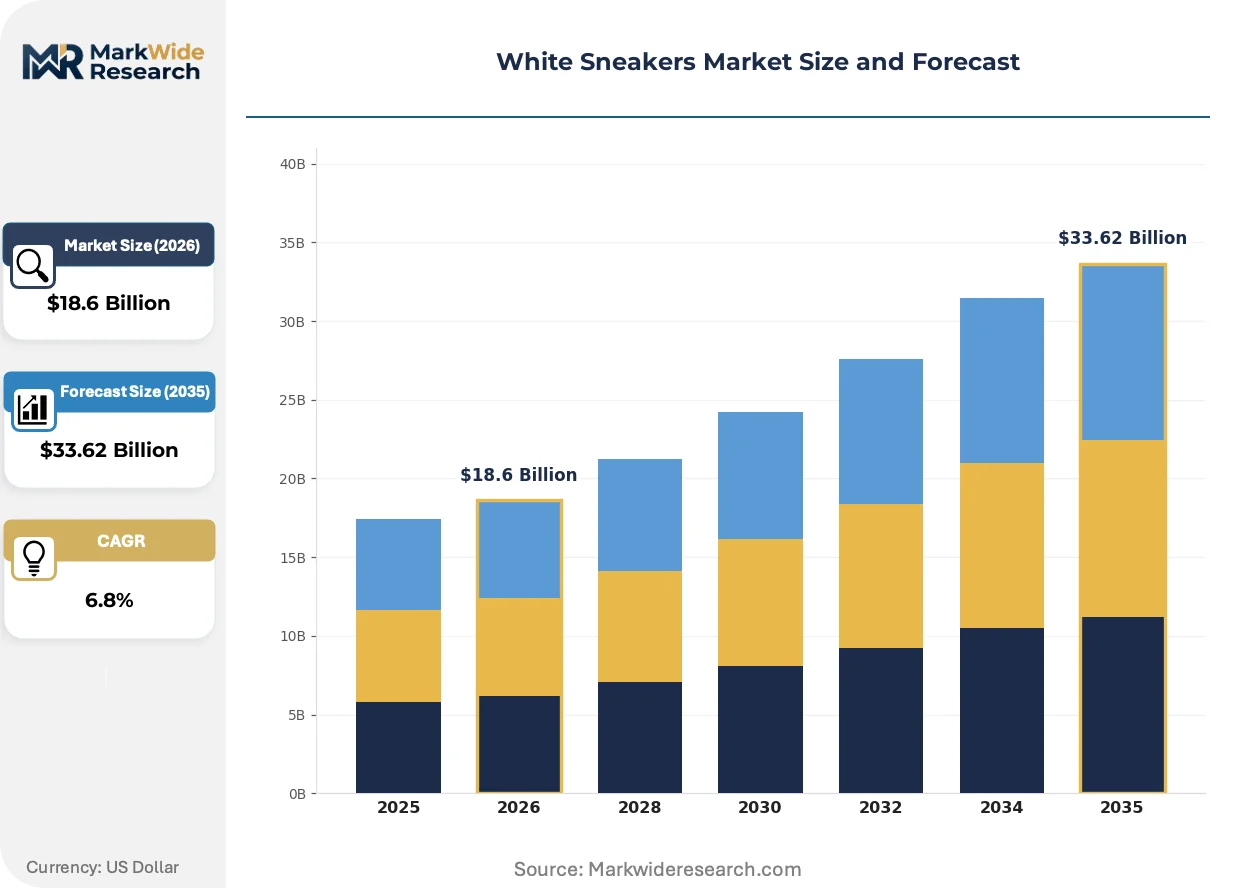
Digital knitting and automated last-forming technology are compressing production economics toward smaller batch sizes with faster turnaround cycles, forcing brands to reconfigure supplier relationships and inventory models.
Growth Catalysts
- REACH compliance cycles:European chemical safety standards are accelerating material reformulation across textile uppers and adhesive systems. Suppliers investing early in volatile organic compound reduction secure preferred vendor status with major brands.
- Athleisure workplace penetration:Professional dress code relaxation in corporate environments expands addressable demand beyond traditional athletic segments. White sneakers now function as uniform-adjacent footwear in hybrid office settings.
- Direct-to-consumer channel maturation:Owned digital storefronts capture margin previously allocated to wholesale partners. Brands leveraging proprietary apps for sizing and customization build recurring purchase behavior.
Market Restraints
- Petroleum-derived input volatility:Synthetic rubber and EVA foam prices fluctuate with crude oil benchmarks. Margin compression intensifies during energy price spikes.
- Southeast Asian supply concentration:Tier-one manufacturing clusters in Vietnam and Indonesia create single-point vulnerability. Geopolitical friction or shipping disruptions cascade through replenishment timelines.
- California Proposition 65 disclosure burden:Chemical labeling requirements impose compliance costs that disproportionately burden smaller brands lacking legal infrastructure.
Strategic Opportunities
- Domestic manufacturing scale:Northeastern United States production bases reduce trans-Pacific lead times for North American demand. Regional distribution velocity improves replenishment responsiveness.
- Biodegradable midsole chemistry:Emerging bio-EVA formulations address end-of-life disposal concerns. Early adopters capture sustainability-premium pricing.
- Platform silhouette diversification:Elevated sole variants attract women-targeted sizing architectures previously underserved by traditional athletic lasts.
Industry Challenges
- Digital knitting technician scarcity:Automated upper production requires specialized programming and maintenance skills. Talent pipelines lag equipment deployment schedules.
- Multi-jurisdiction certification overlap:Simultaneous EPA, REACH, and state-level chemical filings compress seasonal go-to-market windows. Compliance teams face coordination complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Sneakers Market |
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-top, High-top, Slip-on, Platform Material: Canvas, Leather, Synthetic, Mesh Target Audience: Men, Women, Children, Unisex Usage: Casual, Sports, Fashion, Work |
| Companies Covered | Nike, Inc., Adidas AG, PUMA SE, Converse Inc., Vans, Veja Fair Trade SARL, Reebok International Ltd., New Balance Athletics, Inc., SKECHERS USA, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Sneakers Market Evolving Landscape
Material science and regulatory chemistry are converging to reshape how white sneakers are engineered, sourced, and brought to market. Three distinct movements are altering competitive positioning.
Flyknit-derived digital knitting architectures are migrating from performance running into lifestyle white sneaker uppers. Brands adopting these systems reduce material waste by eliminating cutting scraps. The technology compresses pattern-to-production timelines from weeks to days.
REACH substance restrictions and evolving EU Green Deal implementation timelines are forcing adhesive reformulation across European-bound production. Suppliers must qualify alternative chemistries that maintain bond strength under stress testing. Smaller batch producers face disproportionate qualification cost burdens relative to volume.
Urban lifestyle branding now drives purchase decisions ahead of pure athletic performance credentials. Direct-to-consumer channels displace traditional wholesale relationships in customer acquisition. This shift concentrates most visibly in United States metropolitan markets where brand-owned flagship stores anchor neighborhood retail strategies.
White Sneakers Market Segmentation
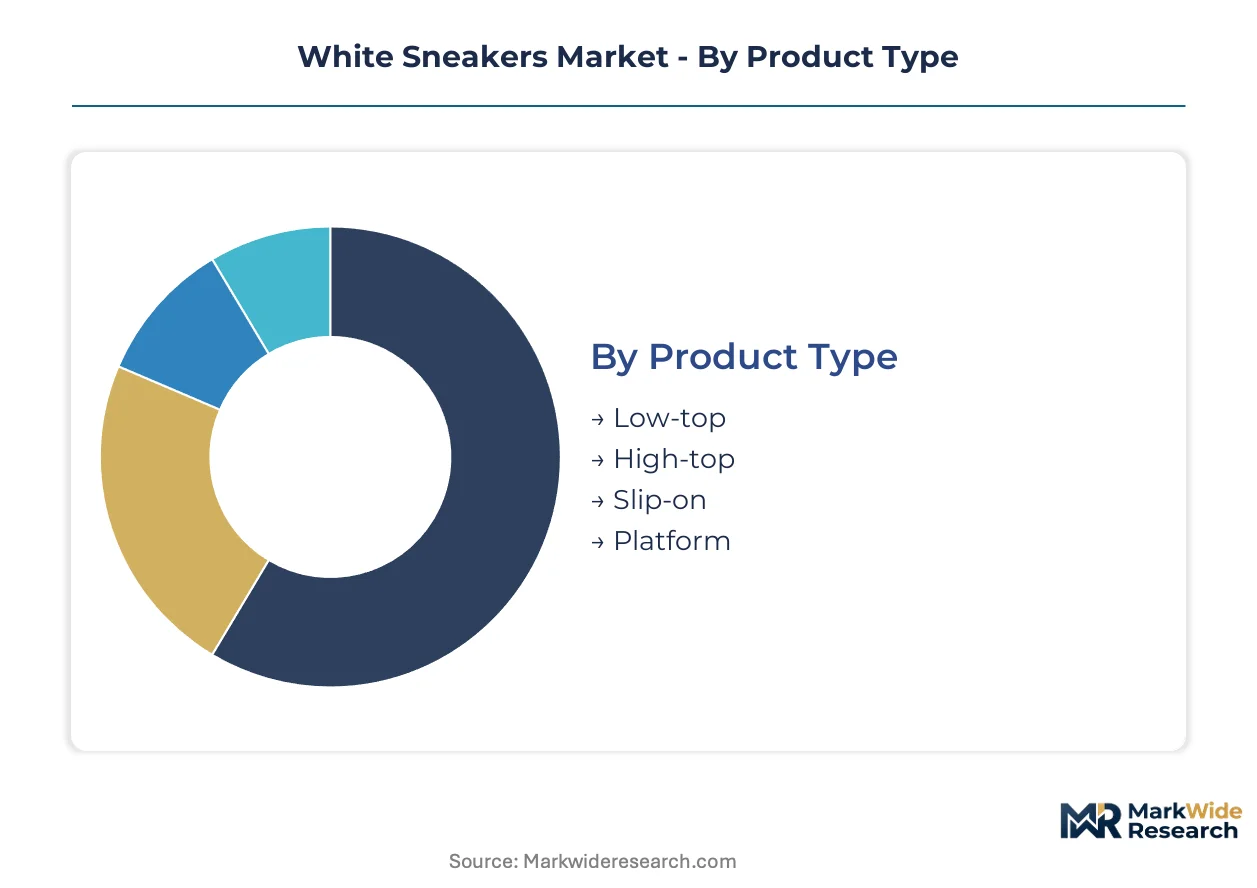
White sneaker segmentation reveals how brands architect product portfolios across competing demand signals. Silhouette, material, audience, and occasion each impose distinct technical and commercial requirements on manufacturing and distribution systems.
Product Type:
The use-case spectrum spans gym crossover, uniform-adjacent workplaces, and pure fashion positioning.
- Low-top:Ankle-below construction with minimal collar padding dominates replenishment velocity in urban retail. United States metropolitan demand concentrates here for office-to-gym crossover, though margin pressure intensifies from commoditized supply.
- Platform:Elevated sole stacks 3-5cm above standard midsole height, capturing women-targeted sizing architectures previously underserved by athletic lasts. Direct-to-consumer channels show disproportionate conversion for this silhouette.
- High-top:Extended collar construction with additional eyestay rows serves basketball heritage positioning and ankle stability requirements.
- Slip-on:Elastic gore or bungee closure systems eliminate lacing for rapid on-off functionality in travel and healthcare settings.
Established volume favors low-top; emerging adoption favors platform.
Material:
Cost tier separation runs from commodity textiles to performance-engineered synthetics with certified chemistry compliance.
- Synthetic:Thermoplastic polyurethane and engineered knit formulations enable weight reduction and batch-to-batch color consistency. REACH-compliant adhesive bonding with synthetic uppers secures European market access for tier-one suppliers.
- Mesh:Open-weave polyester or nylon constructions maximize breathability for warm-climate athletic crossover. United States demand clusters in southern states where humidity drives material selection.
- Canvas:Cotton duck or twill uppers carry heritage authenticity positioning with higher water absorption trade-offs.
- Leather:Full-grain or corrected-grain hides command premium placement in uniform-adjacent workplace segments requiring scuff resistance.
Margin expansion concentrates in synthetic; sustainability signaling favors mesh.
Target Audience:
Customer type fragmentation reflects sizing architecture investments and marketing channel specialization.
- Women:Narrower heel-to-ball ratios and elevated platform variants drive the steepest expansion trajectory in direct-to-consumer conversion rates.
- Unisex:Extended size runs with neutral color blocking reduce SKU complexity for smaller batch producers.
- Men:Traditional athletic lasts with wider forefoot dimensions retain volume concentration in wholesale department store channels.
- Children:Scaled-down constructions with reinforced toe caps address growth-stage replacement cycles and school uniform requirements.
Volume concentration remains with men; growth velocity favors women.
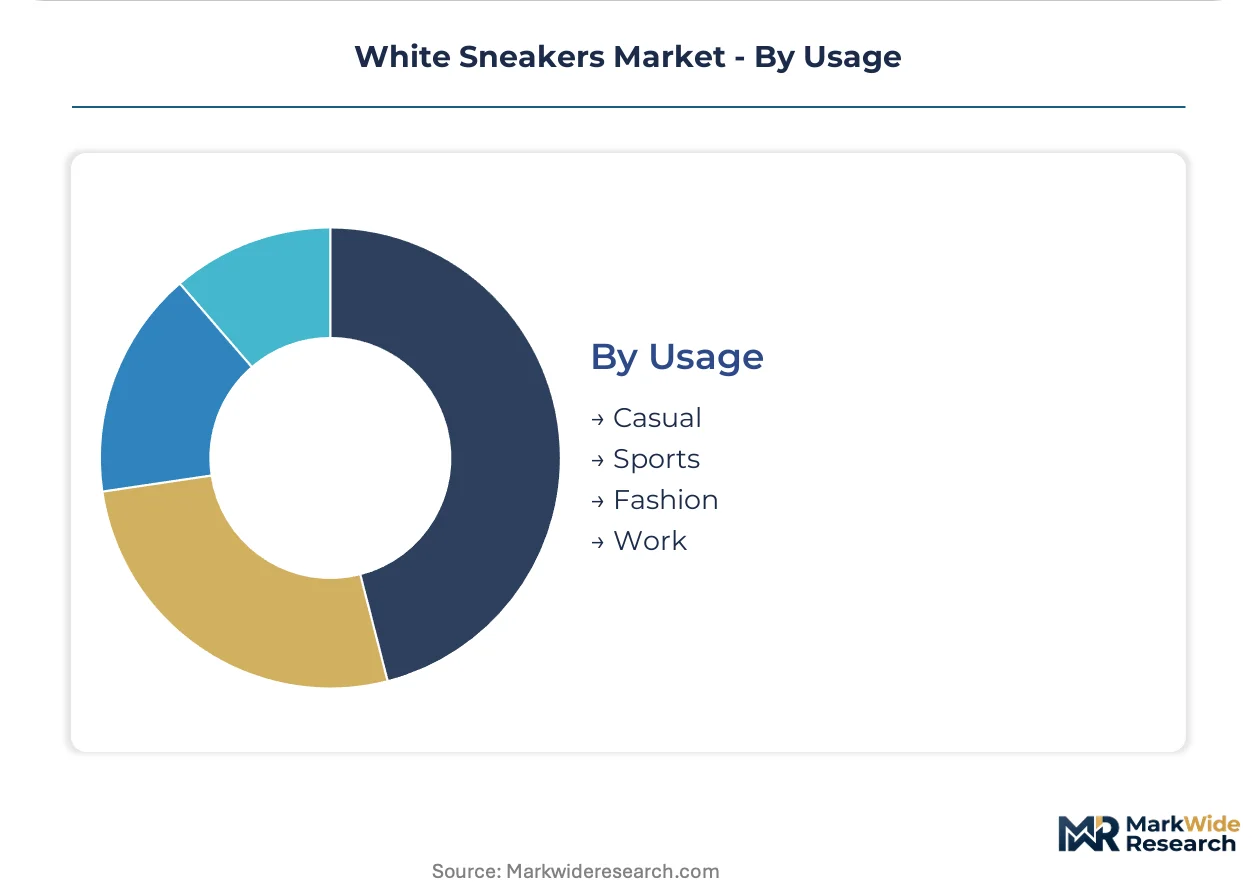
Usage:
Application context determines performance specification thresholds and replacement frequency.
- Casual:Lifestyle positioning prioritizes aesthetic versatility over technical performance, with colorway breadth driving purchase frequency.
- Fashion:Runway-derived silhouettes and collaboration releases command scarcity pricing through limited distribution.
- Sports:Cross-training specifications require cushioning density and outsole traction ratings for gym floor and light court use.
- Work:Slip-resistant outsole compounds and closed-toe safety compliance expand into healthcare and hospitality uniform programs.
Replacement cycles favor casual; specification intensity favors work.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in white sneakers favor manufacturing hubs with preferential trade agreements and established logistics infrastructure. The United States absorbs the largest import volume while Vietnam and Indonesia dominate outbound shipment flows. Currency fluctuations and shipping rate volatility now determine regional competitiveness as much as labor costs.
United States
Urban lifestyle branding and direct-to-consumer flagship stores drive replenishment velocity in metropolitan markets. The EPA's chemical emissions frameworks govern volatile organic compound limits in imported footwear. Los Angeles and New York City anchor neighborhood retail strategies where brand-owned stores displace wholesale department store channels.
Germany
Athleisure workplace penetration in corporate environments expands addressable demand beyond traditional athletic segments. ECHA's REACH substance restrictions force adhesive reformulation across European-bound production. Bavaria hosts Speedfactory-adjacent automation partnerships that compress lead times for replenishment orders.
Vietnam
Tier-one manufacturing clusters concentrate synthetic upper production for global brand partners. The country's national chemical safety regulator enforces evolving standards that cascade through tier-two material vendors. Ho Chi Minh City industrial zones face single-point vulnerability from geopolitical friction or shipping disruptions.
China
Digital knitting technician pipelines and automated last-forming equipment deployment outpace regional competitors. MIIT's GB standards and dual carbon goals reshape supplier qualification requirements. Dongguan and Wenzhou manufacturing bases supply mesh and engineered knit formulations for weight reduction programs.
United Kingdom
Platform silhouette diversification attracts women-targeted sizing architectures through direct-to-consumer conversion. The country's national chemical regulator enforces disclosure requirements that align with EU-derived frameworks. London metropolitan demand clusters for office-to-gym crossover styling with minimal collar padding preferences.
White Sneakers Market Competitive Landscape
On the supply side, the industry is tiered between scale-driven multinationals with captive automation partnerships and smaller batch producers competing on sustainability signaling. Three strategic archetypes dominate: technology-licensing giants controlling proprietary knitting architectures, domestic manufacturing specialists optimizing regional distribution velocity, and fair-trade positioning challengers capturing sustainability-premium pricing. Competitive moves concentrate on M&A for automation capabilities and strategic partnerships for biodegradable midsole chemistry access.
Within the technology-licensing tier, Nike, Inc. and Adidas AG exemplify scale-driven archetypes with proprietary production architectures. New Balance Athletics, Inc. anchors the domestic manufacturing specialist position. These three occupy distinct competitive vectors rather than direct confrontation, with technology licensing, regional production scale, and automation partnerships serving as primary differentiation mechanisms.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| PUMA SE |
| Converse Inc. |
| Vans |
| Veja Fair Trade SARL |
| Reebok International Ltd. |
| New Balance Athletics, Inc. |
| SKECHERS USA, Inc. |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Ho Chi Minh City to Los Angeles govern landed cost differentials between Vietnamese manufacturing clusters and domestic northeastern United States production bases. These freight dynamics compress margin structures for brands reliant on Southeast Asian supply while amplifying price premiums for regional distribution velocity.
Pricing Analysis
Prior-generation canvas and leather constructions anchor economy positioning, while current-generation synthetic knit uppers with REACH-compliant adhesive bonding command standard-tier placement, and emerging bio-EVA midsole formulations with digital knitting architectures occupy premium bandwidth. Price differentiation separates heritage material tiers from performance-engineered synthetics certified for European market access. Pricing pressure stems from petroleum-derived input volatility in synthetic rubber and EVA foam, compressing margins during energy price spikes. Wholesale department store channels exhibit highest price sensitivity, while direct-to-consumer flagship stores in United States metropolitan markets sustain premium absorption.
Supply Chain Analysis
Petroleum feedstock derivatives—synthetic rubber, thermoplastic polyurethane, and EVA foam—anchor raw material cost structures for white sneaker production. Manufacturing concentrates in Vietnam, Indonesia, and China, with Vietnam hosting tier-one synthetic upper production and China controlling digital knitting equipment deployment. Single-source vulnerability in Southeast Asian clusters creates replenishment timeline risk from geopolitical friction or shipping disruptions. Distribution runs through brand-owned direct-to-consumer flagship stores displacing traditional wholesale department store channels, particularly in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in white sneakers hinges on scarce automation technician pipelines and captive digital knitting architectures, creating asymmetric capability accumulation between scale-driven multinationals and smaller batch producers. The report identifies three stakeholder archetypes with distinct strategic imperatives.
For Market Incumbents: Insulate proprietary production architectures through captive automation partnerships and technician training pipelines that lag equipment deployment schedules. Deepen backward integration into bio-EVA midsole chemistry to preempt sustainability-premium pricing capture by emerging entrants. Defend against Speedfactory-adjacent automation partnerships by accelerating domestic manufacturing scale in northeastern United States production bases. For New Entrants and Emerging Players: Establish a beachhead in platform silhouette diversification targeting women-targeted sizing architectures previously underserved by traditional athletic lasts. Penetrate direct-to-consumer channels where conversion rates show disproportionate strength for elevated sole variants. Leverage fair-trade positioning and biodegradable midsole chemistry to capture sustainability-premium pricing in European markets bound by REACH substance restrictions. For Investors and Strategic Acquirers: Domestic manufacturing specialists with regional distribution velocity control represent the highest-conviction acquisition archetype for North American demand exposure. Long-term viability favors brands with in-house digital knitting capabilities and qualified REACH-compliant adhesive supplier networks. Monitor ECHA substance restriction filing deadlines as inflection indicators forcing reformulation cycles that determine seasonal go-to-market windows.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Knitting Architecture Deployment | Nike's Flyknit-derived systems reduce material waste and compress pattern-to-production timelines from weeks to days. |
| Domestic Manufacturing Scale-Up | New Balance's northeastern United States production bases improve replenishment responsiveness for North American demand. |
| Bio-EVA Midsole Chemistry Investment | Early adopters of biodegradable formulations capture sustainability-premium pricing in European markets. |
| Direct-to-Consumer Channel Expansion | Owned digital storefronts in Los Angeles and New York City displace wholesale partners and capture margin concentration. |
| REACH Compliance Certification Program | Suppliers investing in volatile organic compound reduction secure preferred vendor status with Adidas and other tier-one brands. |
Research Methodology
Initial hypotheses were tested against primary input from brand sourcing executives, tier-one manufacturing plant managers, digital knitting equipment technicians, and retail category buyers, then refined through secondary validation against customs records, footwear trade association filings, and SEC 10-K disclosures from publicly traded competitors. Bottom-up demand modeling across silhouette, material, and audience segments was triangulated with top-down market sizing from production capacity and import-export flow analysis.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeling spanning product type, material chemistry, target audience architecture, and usage occasion. CAGRs were derived from fitted growth curves against historical volume trajectories and forward-looking capacity expansion announcements. Forecast inputs incorporated REACH compliance cycle timing, petroleum price elasticity coefficients, and direct-to-consumer channel penetration rates by metropolitan market.
Stress conditions across crude oil price volatility, trans-Pacific shipping rate spikes, and ECHA substance restriction enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding automation equipment deployment schedules and adhesive reformulation lead times. Cross-checking against customs import volume data and retail point-of-sale audit benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Football Shoes Market
Footwear
Light Up Shoes Market
Footwear
Waterproof Sneakers Market
Footwear
Orthopedic Footwear Market
Footwear
Europe Athletic Footwear Market
Footwear
Athletic Footwear Market
Footwear
Mountain Bike Footwear and Socks Market
Footwear
Middle East and Africa Athletic Footwear Market
Footwear
Refurbished Sneaker Market
Footwear
Tactical Footwear Market
Footwear
Running Shoes Market
Footwear
Western Boots Market
Footwear
Platform Boots Market
Footwear
PVC Footwear Market
Footwear
Footwear Testing Services Market
Footwear
Middle East and Africa E-Commerce Footwear Market