
 Formal Shoes Market | 2026-2036
Formal Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Formal Shoes Market Analysis
Market Dynamics
Premium full-grain leather construction is reorganizing the formal shoes market as manufacturers respond to professional buyers seeking durability credentials. C. & J. Clark International Ltd leverages its Northampton heritage to sustain artisan positioning against mass-market alternatives. Crockett & Jones anchors British manufacturing credibility through in-house finishing operations. Cole Haan competes by integrating athletic comfort technology into traditional silhouettes for extended-wear office environments.
Product Architecture
Formal shoes denote closed-lace footwear engineered with welted or cemented construction, leather uppers, and structured toe profiles designed for professional, ceremonial, and diplomatic settings. Oxfords dominate corporate dress codes through their closed-throat lacing system, while patent leather variants command ceremonial occasion segments including state functions and formal weddings. The men's end-user category occupies the largest volume share, though unisex styling gains traction among younger professional cohorts seeking versatile wardrobe investments.
Regulatory Environment
REACH governs chromium VI limits in European leather tanning, compelling suppliers to certify chemical compliance for market access. The US EPA regulates volatile organic compound emissions from footwear adhesives and finishes, affecting import eligibility. ISO 17072 standards for leather chemical testing shape quality assurance protocols across export-oriented production hubs. Stakeholders must monitor evolving bio-based material certifications as vegetable-tanned alternatives displace conventional chrome processes in premium supply chains.
Market Dynamics
REACH chemical restrictions on tanning agents are forcing European tanneries toward vegetable-based alternatives, restructuring upstream supply relationships and certifiable material flows across premium leather footwear production.
Growth Catalysts
- Corporate hiring rebound:Financial services recruitment across the United States and Singapore is expanding workplace footwear procurement volumes for entry-level professional cohorts.
- REACH compliance migration:European manufacturers adopting chrome-free tanning processes are capturing sustainability premiums from environmentally credentialed institutional buyers.
- White-collar workforce expansion:China's tier-one cities sustain premium leather goods consumption through sustained professional services sector growth.
Market Restraints
- Raw material cost volatility:Full-grain hide prices fluctuate with livestock supply cycles and tanning chemical substitution costs.
- Supply concentration risk:Vegetable-tanned leather production clusters in Italian and Spanish tanneries with limited scalable alternatives.
- Substitution threat:High-grade synthetic microfiber materials from South Korean and Taiwanese suppliers erode mid-market leather positioning.
Strategic Opportunities
- Underpenetrated Indian market:Metropolitan professional services growth in Mumbai and Bangalore outpaces domestic formal footwear brand presence.
- Regulatory tailwind:EU Green Deal bio-based material certifications create preferential procurement channels for vegetable-tanned product lines.
- Direct-to-professional channel innovation:Corporate uniform and dress-code stipend platforms enable bypass of traditional retail markup structures.
Industry Challenges
- Artisan skill scarcity:Northampton and Florentine hand-sewing traditions face generational workforce attrition without structured apprenticeship pipelines.
- Certification timeline compression:ISO 17072 leather chemical testing protocols extend product development cycles for export-oriented manufacturers.
- Legacy sizing standard fragmentation:Incompatible last measurements between British, American, and Continental systems inflate inventory complexity for multi-market brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Formal Shoes Market |
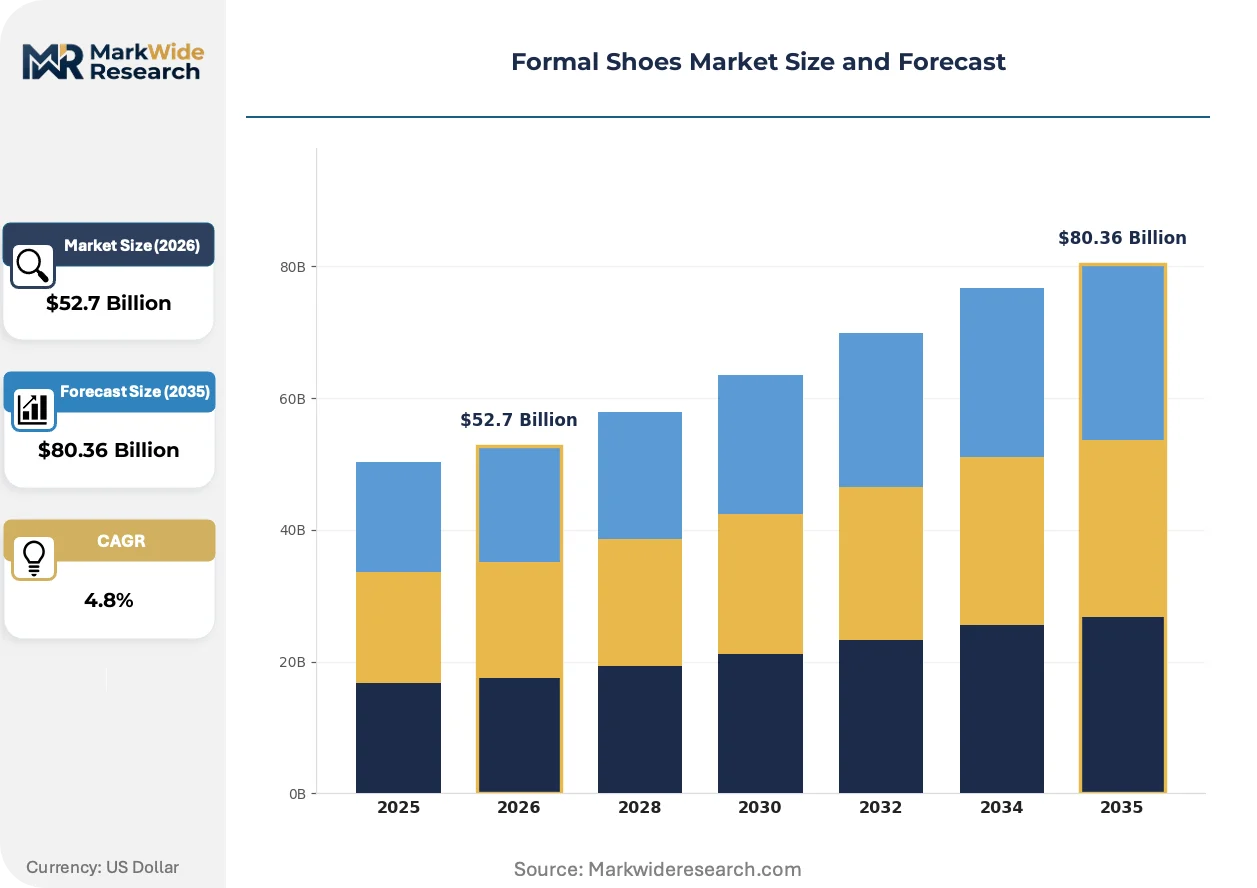
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxfords, Brogues, Loafers, Derby Shoes Material: Leather, Suede, Synthetic, Patent Leather End User: Men, Women, Kids, Unisex Occasion: Office, Parties, Weddings, Business Meetings |
| Companies Covered | Steven Madden, John Lobb, C. & J. Clark International Ltd, Edward Green, Church's, Cole Haan, Kenneth Cole Productions, Crockett & Jones, Bata Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Formal Shoes Market Emerging Trajectories
Material science convergence with heritage craft traditions is actively reshaping competitive positioning across price tiers, as established houses and emerging suppliers diverge in their technical bets.
3D-knitted textile uppers with integrated structural reinforcement are fragmenting traditional leather-dominant construction methods. Younger professional cohorts in technology and creative industries are adopting hybrid-material oxfords at accelerating rates. This adoption is fragmenting the historical correlation between price tier and leather percentage in formal footwear specifications.
REACH chromium VI limits are compelling tanneries to revalidate entire chemical input streams for European market access. Manufacturers dependent on chrome-tanned supply chains face reformulation costs and extended certification periods. Premium British and Italian producers with existing vegetable-tan capabilities are consolidating supplier relationships to secure compliant material allocation.
Corporate stipend-based footwear procurement is displacing individual retail purchasing for entry-level professional segments. Human resources departments in United States financial services and United Kingdom consulting firms are negotiating direct supplier contracts. This concentration is most visible in London and New York, where bulk professional onboarding volumes favor standardized sizing and expedited fulfillment models over bespoke fitting services.
Formal Shoes Market Segmentation
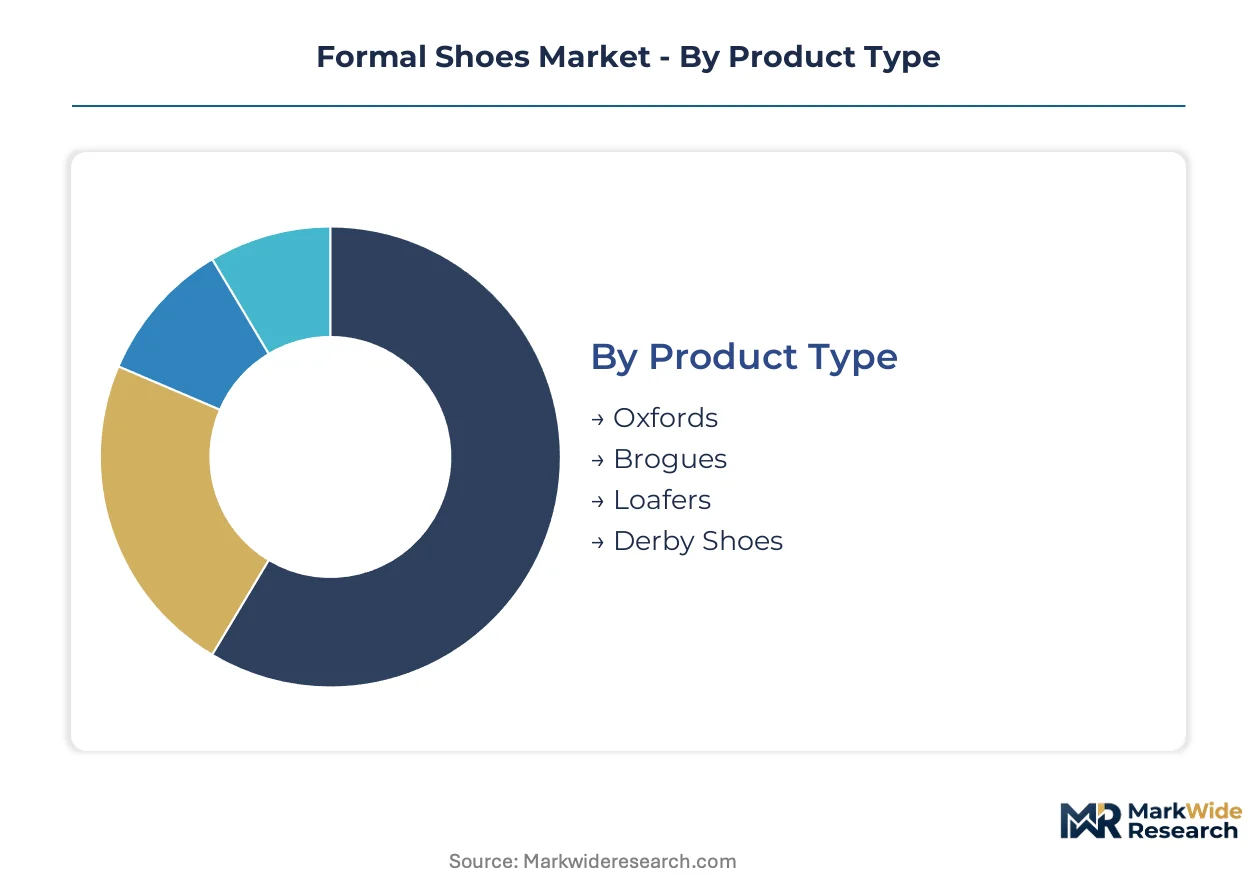
Segmentation in formal footwear reveals divergent margin architectures across construction methods and material certifications. Procurement patterns vary sharply between ceremonial occasion buyers seeking single-use investment pieces and corporate wardrobe builders prioritizing cost-per-wear durability.
Product Type:
Margin pools concentrate in welted construction categories where artisan positioning commands sustained price premiums against cemented alternatives.
- Oxfords:Closed-throat lacing systems with quarters stitched under the vamp create the most formal silhouette in professional dress codes. Demand clusters in London and New York financial services, where strict wardrobe policies sustain volume despite higher unit costs.
- Brogues:Decorative perforations and pinked edges originated as Scottish drainage features, now signaling heritage authenticity in premium tiers. Growth concentrates among technology sector professionals in San Francisco and Austin seeking personality differentiation within business-casual environments.
- Loafers:Slip-on construction with saddle or tassel ornamentation dominates warmer-climate professional markets.
- Derby Shoes:Open-lacing configuration permits wider foot entry, capturing comfort-prioritizing segments in extended-wear office settings.
The dominant share belongs to Oxfords, while Brogues are closing the gap fastest.
Material:
Cost tier stratification follows tanning process complexity, with vegetable-tanned full-grain commanding the widest spread over chrome-tanned alternatives.
- Leather:Full-grain hides with intact surface fiber structure deliver maximum durability and patina development. Procurement from Italian and Spanish tanneries faces REACH compliance bottlenecks as chrome-free validation extends lead times.
- Patent Leather:High-gloss resin finishes achieved through lacquer coating or plastic film lamination serve ceremonial occasion segments. State functions in Washington DC and diplomatic events in Geneva sustain concentrated demand despite limited wear frequency.
- Suede:Split-grain or reversed full-grain with napped surface offers textural variety in seasonal collections.
- Synthetic:Microfiber and polyurethane constructions from South Korean suppliers erode mid-market positioning through performance parity claims.
Leather retains volume leadership, though Patent Leather shows steepest expansion trajectory in occasion-specific channels.
End User:
Customer type determines sizing standard complexity and distribution channel selection, with institutional procurement favoring standardized fits over bespoke services.
- Men:Traditional last shapes with structured toe profiles dominate corporate dress code enforcement. China's tier-one cities sustain premium consumption through white-collar workforce expansion in Shanghai and Beijing professional services.
- Unisex:Shared sizing architectures and versatile styling reduce inventory carrying costs for multi-brand retailers. Younger professional cohorts in Berlin and Amsterdam drive adoption through wardrobe minimalism preferences.
- Women:Heel height variation and decorative detailing create higher SKU complexity per collection.
- Kids:Occasion-driven purchases concentrate in private school enrollment corridors and ceremonial family events.
Men's segments hold established share dominance, while Unisex is gaining share fastest among urban professional entrants.
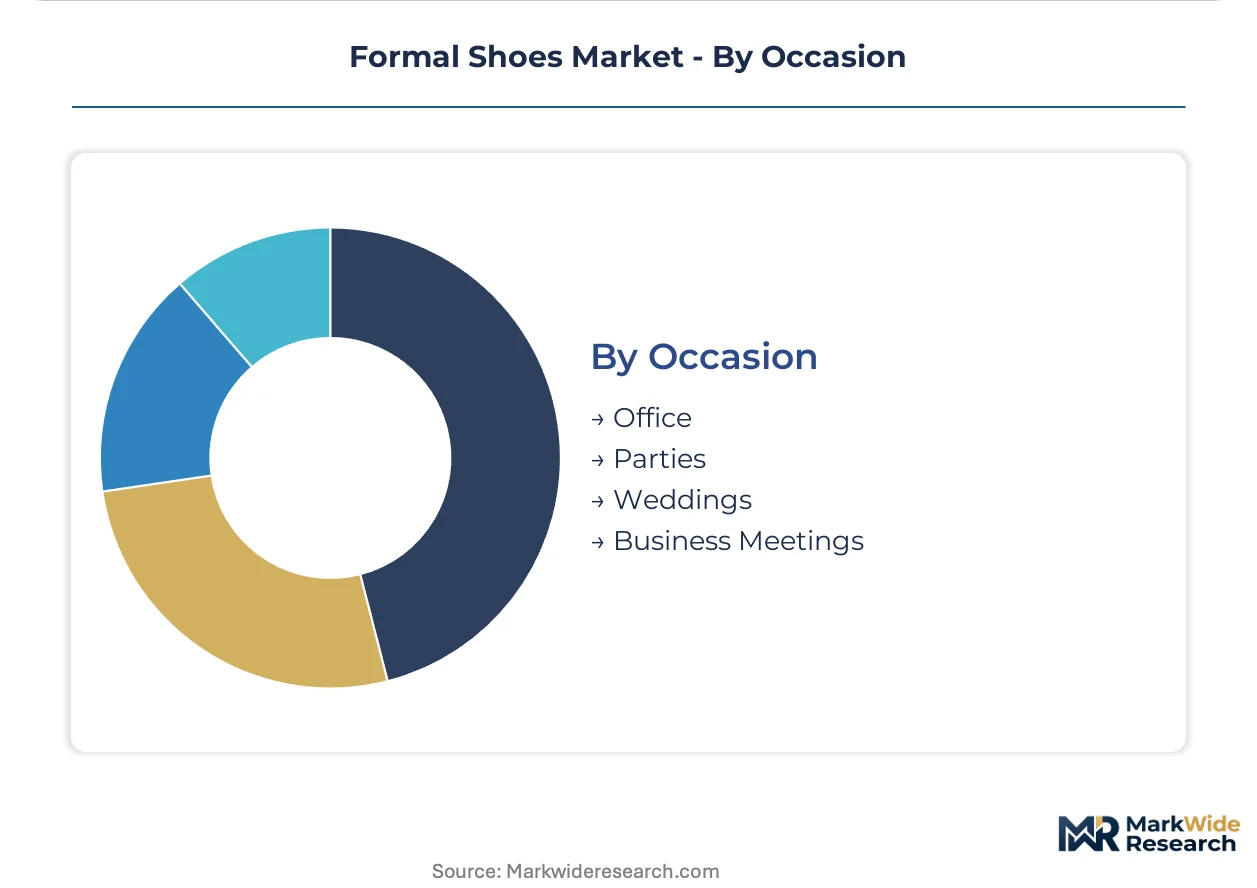
Occasion:
Application context dictates construction durability requirements and price elasticity thresholds across replacement cycles.
- Office:Daily wear specifications prioritize cushioning systems and abrasion-resistant outsoles for extended standing. United States consulting firms and Singapore financial services drive corporate stipend procurement at volume scale.
- Weddings:Single-use investment psychology permits higher absolute expenditure on statement construction and finish quality. Seasonal concentration in June and September creates production planning challenges for made-to-order workshops.
- Business Meetings:Client-facing presentation requirements sustain conservative styling preferences with minimal trend exposure.
- Parties:Social occasion flexibility permits bolder material and color experimentation outside dress code constraints.
Office applications command the largest volume position, while Weddings demonstrate the sharpest price inelasticity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in formal footwear tilt toward net-importing advanced economies while manufacturing clusters concentrate in heritage leatherworking regions. This asymmetry shapes tariff exposure and supply chain vulnerability assessments across procurement networks.
United States
Corporate stipend procurement from financial services and consulting firms drives volume demand in New York and Chicago. The EPA regulates volatile organic compound emissions from footwear adhesives under Clean Air Act provisions. Domestic finishing operations in Maine and Massachusetts handle final assembly of imported uppers from Italian tanneries.
United Kingdom
Northampton's welted shoemaking tradition sustains premium export positioning despite raw material import dependence. REACH compliance through ECHA governs chromium VI limits in leather goods entering the single market. London's corporate headquarters concentration generates concentrated demand for entry-level professional footwear through HR-managed procurement platforms.
Italy
Florentine and Tuscan tanneries supply vegetable-tanned full-grain leather to premium manufacturers worldwide. EU Green Deal bio-based material certifications create preferential channels for chrome-free production lines. The Marche region's footwear industrial district clusters assembly operations with direct tannery relationships.
China
Shanghai and Beijing white-collar workforce expansion sustains premium leather goods consumption despite domestic manufacturing dominance. GB standards and MIIT regulations govern product safety and labeling requirements. Guangdong Province hosts synthetic microfiber production that competes with imported leather in mid-market segments.
India
Metropolitan professional services growth in Mumbai and Bangalore outpaces domestic formal footwear brand presence. BIS certification requirements create compliance barriers for imported finished goods. Kanpur's leather cluster supplies semi-finished hides to European manufacturers while domestic brands struggle to capture organized retail space.
Formal Shoes Market Vendor Landscape
Concentration sits with heritage manufacturers possessing vertical control over finishing operations and established Northampton or Florentine credentials. The vendor base spans three tiers: artisan workshops with century-old last archives, mid-market houses blending Asian manufacturing with European design licensing, and volume distributors leveraging synthetic material cost advantages. Strategic moves center on securing compliant vegetable-tanned leather allocations and building direct corporate procurement relationships that bypass traditional retail markups.
Within the British heritage tier, C. & J. Clark International Ltd and Crockett & Jones occupy positions defined by Northampton manufacturing credibility and in-house finishing capabilities. Cole Haan represents the comfort-technology hybrid archetype, integrating athletic cushioning systems into traditional silhouettes for extended-wear office environments. These three exemplify divergent bets on material authenticity versus functional innovation as competitive differentiation vectors.
| Leading Market Players |
|---|
| Steven Madden |
| John Lobb |
| C. & J. Clark International Ltd |
| Edward Green |
| Church's |
| Cole Haan |
| Kenneth Cole Productions |
| Crockett & Jones |
| Bata Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with Italian and Spanish tanneries lock in vegetable-tanned leather allocations for premium British manufacturers, anchoring both supply security and forward price visibility against raw material volatility cycles.
Pricing Analysis
Corporate uniform buyers anchor volume-based pricing structures in the formal footwear market. Three-tier pricing stratifies across Goodyear-welted artisan construction, bench-made standard lines, and cemented entry-level products. Price differentiation rests on tanning certification grade and in-house finishing capability rather than brand markup alone. Cost compression in mid-market tiers intensifies as South Korean microfiber suppliers achieve performance parity claims. Entry-level professional cohorts recruited through HR stipend programs exhibit highest price sensitivity, while ceremonial occasion purchasers demonstrate lowest elasticity.
Supply Chain Analysis
Tuscan tannery district concentration in Italy underwrites premium full-grain leather flows to Northampton and Florentine finishing operations. Raw material sourcing draws from Brazilian and Argentinian hide processors, with chemical inputs dependent on German and Belgian specialty suppliers. Single-source vulnerability concentrates in chrome-free tanning agent production, where REACH compliance validation extends lead times. Distribution runs through corporate procurement platforms, specialty retail networks, and direct-to-professional uniform channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
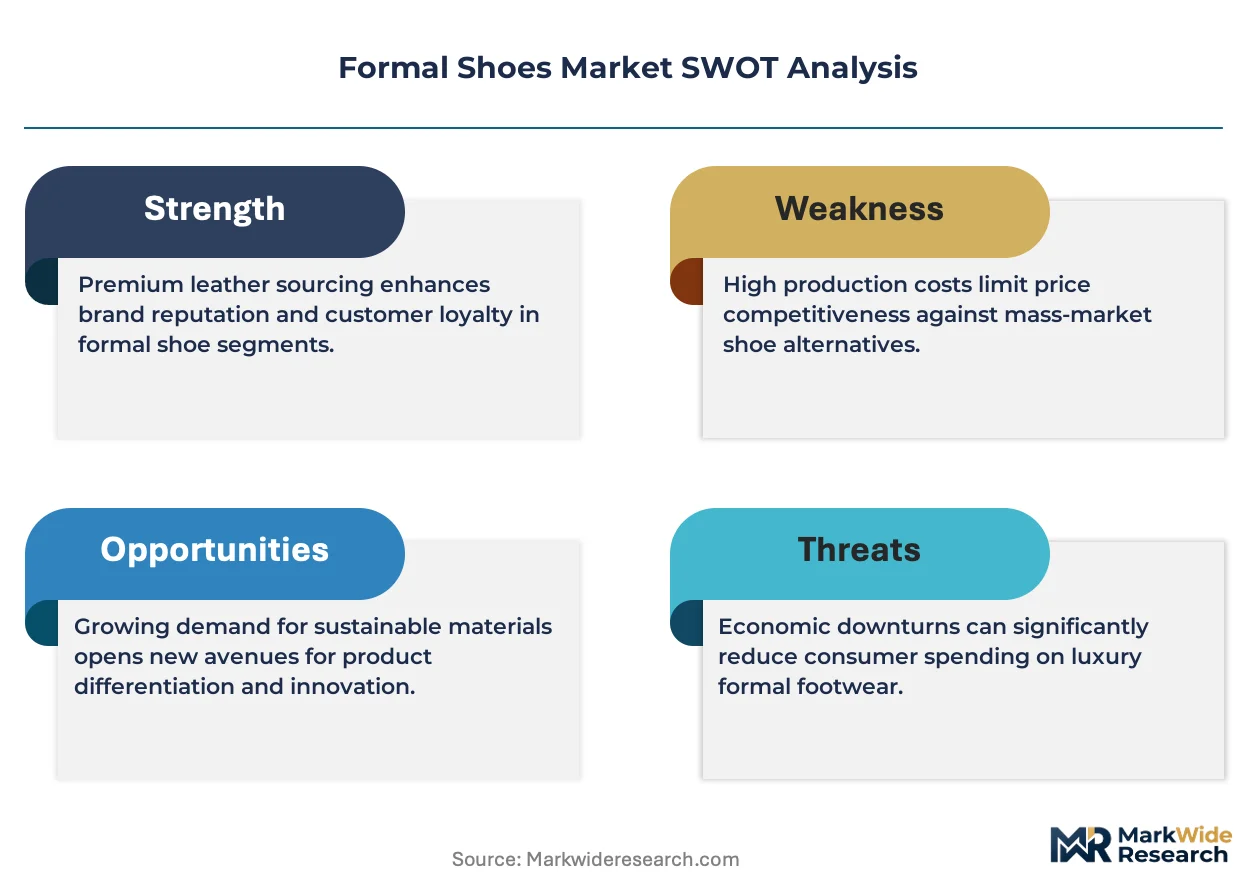
The formal footwear market functions as a regulatory-entrenchment story where REACH compliance timelines and artisan skill scarcity create defensive moats for established vegetable-tan capable manufacturers.
For Market Incumbents: Secure captive allocations of chrome-free leather from Tuscan tanneries before compliance bottlenecks tighten further. Deepen backward integration into finishing operations to preserve margin control against raw material cost pass-through. Counter synthetic microfiber substitution threats by emphasizing patina development and repairability credentials in corporate procurement pitches. For New Entrants and Emerging Players: Corporate stipend administration services represent an underserved layer where incumbents rely on legacy retail relationships. Target direct-to-HR platform partnerships in United States financial services and United Kingdom consulting sectors. Penetrate through expedited fulfillment models and standardized sizing systems that bypass bespoke fitting bottlenecks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with existing vegetable-tan capabilities and Northampton or Florentine manufacturing credentials. Long-term viability hinges on securing generational artisan workforce pipelines and compliant material flows. Watch for EU Green Deal bio-based certification expansion as an inflection signal for preferential procurement channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Tanning Transition | REACH compliance through ECHA validation opens EU market access for certified producers. |
| Corporate Procurement Platform Partnership | Direct HR stipend contracts bypass retail markup and capture entry-level professional volumes. |
| Artisan Apprenticeship Pipeline Investment | Northampton and Florentine hand-sewing traditions require structured workforce development. |
| Vegetable-Tanned Leather Backward Integration | In-house finishing operations preserve margin control against Tuscan tannery supply constraints. |
| Sustainability Certification Program | EU Green Deal bio-based credentials create preferential channels for institutional buyers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, tannery association reports, and corporate procurement disclosures. Primary interviews engaged brand managers at heritage manufacturers, category buyers at United States and United Kingdom retailers, supply planners at Italian tanneries, and HR procurement leads at financial services firms. Secondary validation drew from ECHA REACH compliance databases, ISO 17072 testing protocols, and EU Green Deal certification registries. Bottom-up volume estimates triangulated against top-down market sizing across construction method and material certification tiers.
Segmentation dimensions modeled include product architecture, tanning process type, end-user category, and occasion context across the projection horizon. CAGRs derived from regression analysis of historical procurement volumes against corporate hiring indices and professional services workforce expansion. Industry-specific forecast inputs incorporated REACH compliance timeline assumptions and vegetable-tanned leather supply elasticity parameters.
Underlying assumptions cover sustained corporate dress code enforcement and REACH regulatory stability, with deviation risk concentrated in synthetic material substitution acceleration and artisan skill attrition rates. Practitioners should keep alternative scenarios live as EU bio-based certification criteria and stipend program adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Sports Footwear Market
Footwear
Self-Lacing Shoes Market
Footwear
Running Shoes Market
Footwear
Womens Footwear Market
Footwear
White Sneakers Market
Footwear
Europe Athletic Footwear Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Orthopedic Footwear Market
Footwear
Tennis Shoes Market
Footwear
North America Athletic Footwear Market
Footwear
Luxury Footwear Market
Footwear
Tactical Footwear Market
Footwear
Duck Boots Market
Footwear
E-Commerce Footwear Market
Footwear
Ankle Boots Market
Footwear
Custom Shoes Market