
 Slip on Shoes Market | 2026-2036
Slip on Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Slip on Shoes Market Analytics
The capital-intensity gap between vertically integrated manufacturers and asset-light brand licensors is collapsing as automated knitting and direct-injection molding lower entry barriers. Nike Inc. leverages its Flyknit and React foam technologies to control premium performance slip-on positioning. Skechers USA Inc. anchors its competitive stance through memory foam insoles and mass-market distribution density across North American retail. ECCO Sko A/S differentiates via in-house tanneries and European leather sourcing that sustains margin pools in the dress and casual categories.
Slip-on shoes are footwear constructed without laces, fasteners, or closures, designed for donning through elasticized goring, stretchable uppers, or structured heel counters that permit foot entry via a pulling motion; primary specifications include outsole flexibility measured in bending resistance, upper breathability in grams per square meter, and heel-to-toe drop angles that determine biomechanical function during walking or standing. The industrial purpose spans consumer comfort footwear, occupational safety compliance, and fashion accessorizing across casual and formal contexts. Canvas materials lead volume in the sports and casual product type segments due to lower unit costs and seasonal color agility, while leather commands margin concentration in dress and loafer categories where durability and patina development justify premium positioning. The unisex target audience segment is expanding fastest among Gen Z consumers who reject binary sizing conventions, though men and women still represent the dominant revenue pools in work and formal occasion usage.
The EU REACH regulation and California's Proposition 65 constrain phthalate and heavy metal content in synthetic uppers and adhesives, compelling suppliers to reformulate or source certified alternatives. ISO 9001 quality management and SATRA footwear testing standards govern slip resistance, abrasion durability, and seam strength for market access in Europe and North America. Stakeholders must monitor biomaterial certification schemes and extended producer responsibility frameworks as these will reshape sourcing decisions and product take-back obligations.
Market Dynamics
Automated knitting and direct-injection molding technologies are collapsing the capital barrier between vertically integrated manufacturers and asset-light brand licensors, redistributing competitive advantage toward design speed and material science rather than production scale.
Growth Catalysts
- EU Green Deal compliance mandates:REACH regulations and extended producer responsibility frameworks push manufacturers toward bio-based uppers and water-based adhesives, creating certified product premiums in European retail channels.
- Workplace casualization:Technology sector employers in the United States and Germany now permit slip-on footwear in formal client settings, expanding addressable occasions beyond traditional leisure contexts.
- Gen Z sizing rejection:Young consumers in China and South Korea demand unisex lasts and binary-agnostic colorways, forcing brands to collapse gendered SKU architectures into unified collections.
Market Restraints
- Petrochemical input volatility:Synthetic rubber and EVA foam prices track crude oil indices, compressing margin predictability for mass-market producers dependent on petroleum-derived cushioning systems.
- Tannery concentration risk:Premium leather sourcing clusters in Italian and Portuguese processing hubs, exposing dress-category manufacturers to single-region supply disruptions and hide cost spikes.
- Biomechanical limitation:Slip-on construction without lacing systems cannot achieve the heel lock and midfoot stability required for high-impact occupational safety certification, capping penetration in industrial end-uses.
Strategic Opportunities
- India domestic market expansion:Rising disposable income in Mumbai and Bangalore metro corridors creates first-time branded footwear demand among white-collar workers seeking office-appropriate casual options.
- Circular take-back mandates:France's AGEC law and forthcoming EU textile strategy require brands to establish reverse logistics for end-of-life footwear, rewarding early movers with regulatory goodwill and material recovery economics.
- 3D-printed midsole convergence:Lattice-structured TPU and photopolymer resins enable mass customization of arch support without last inventory, pairing with AI foot-scanning apps to capture medical wellness positioning.
Industry Challenges
- Biomaterial certification timelines:SATRA and ISO 17088 biodegradability testing protocols require 18-24 month validation cycles, delaying market entry for innovative plant-based alternatives.
- Legacy ERP integration friction:Direct-to-consumer channel shift demands real-time inventory visibility across wholesale and owned-commerce stacks, straining mid-tier manufacturers with heterogeneous IT architectures.
- Specialized last engineering scarcity:Unisex and adaptive sizing requires anthropometric database development and CAD expertise concentrated in Northern Italian technical institutes, constraining rapid product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slip on Shoes Market |
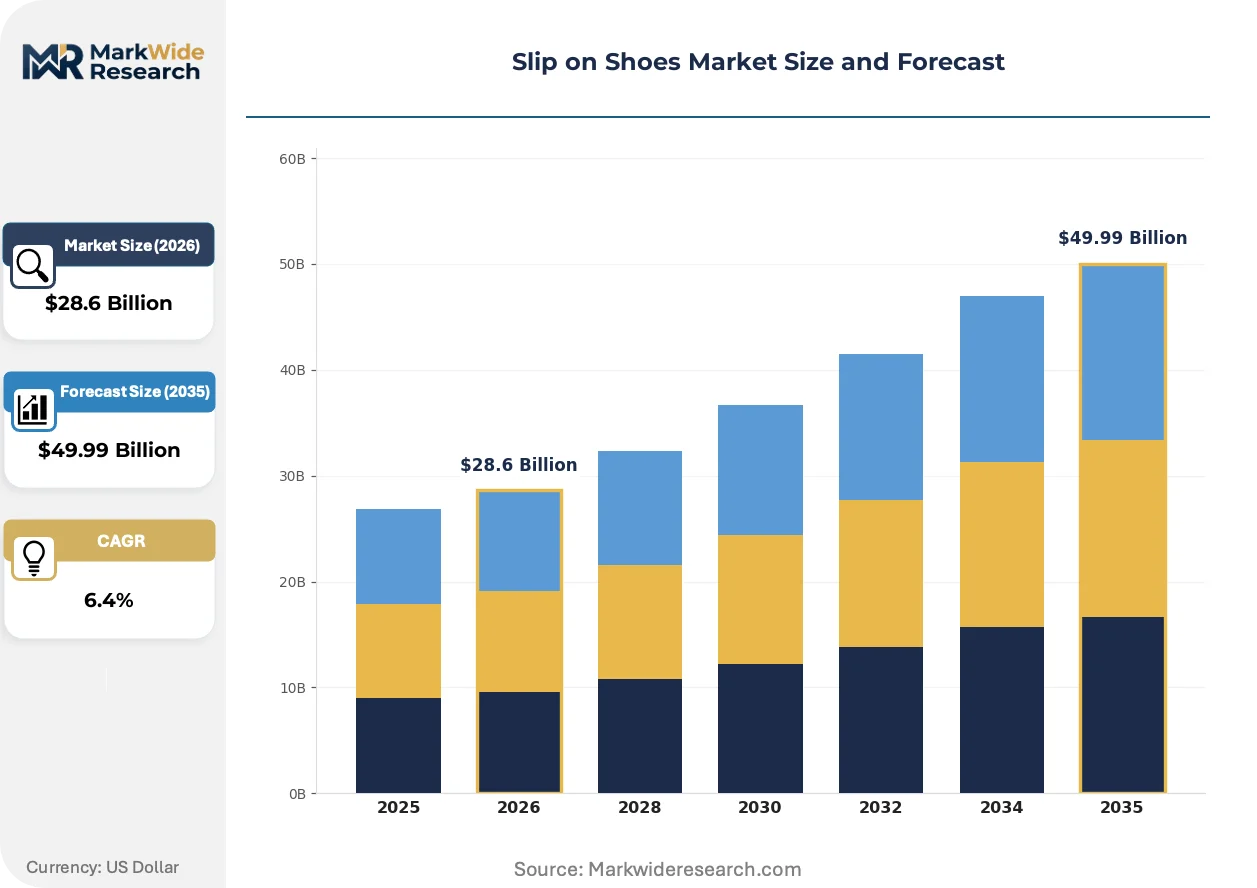
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casual, Dress, Sports, Loafers Material: Leather, Canvas, Synthetic, Suede Target Audience: Men, Women, Children, Unisex Usage Occasion: Everyday Wear, Formal Events, Outdoor Activities, Work |
| Companies Covered | Nike Inc., Adidas AG, Vans, Skechers USA Inc., Crocs Inc., Puma SE, TOMS Shoes LLC, ECCO Sko A/S, Clarks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slip on Shoes Market Evolving Landscape
Material substitution and manufacturing automation are compressing development cycles while regulatory pressure on chemical content forces reformulation across the supply base.
Flyknit-style automated upper knitting is displacing traditional cut-and-sew assembly in performance and casual categories. Running-focused consumers in the United States and Japan adopt seamless constructions for reduced irritation and weight. This technology is displacing manual labor cost advantages that previously anchored mass production in low-wage manufacturing clusters.
California's Proposition 65 enforcement against phthalate-containing synthetic leathers compels reformulation of PU uppers and solvent-based adhesives. Brands serving the US West Coast now pre-certify materials through third-party labs to avoid litigation exposure. Children's and occupational safety segments face the strictest testing burdens, with some suppliers exiting these categories entirely.
Medical channel partnerships now drive premium positioning for orthopedic slip-on variants. Podiatry clinics in Germany and Australia prescribe certified footwear with metatarsal support, bypassing traditional retail markup structures. This clinical endorsement model concentrates volume in metropolitan health networks where reimbursement codes recognize preventive foot care.
Slip on Shoes Market Segmentation
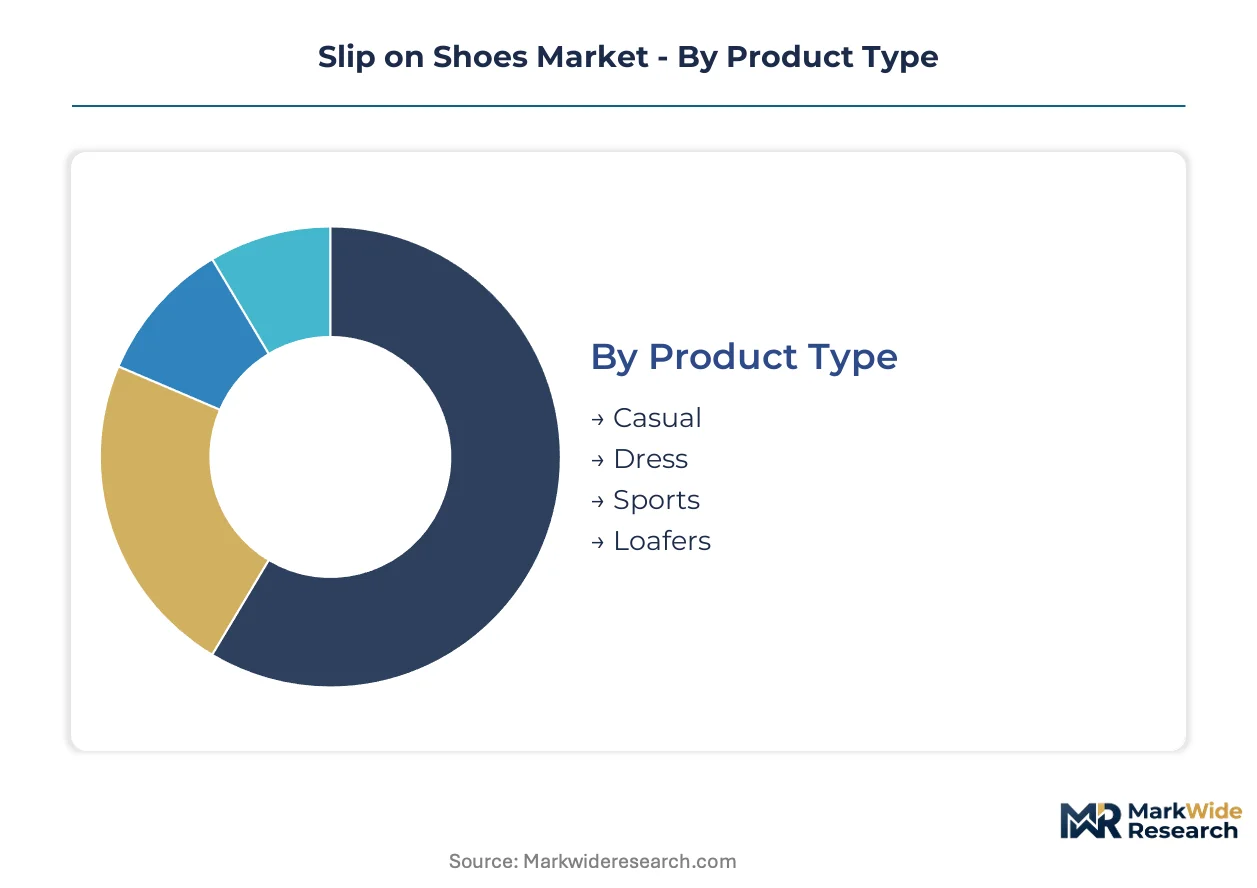
Segmentation in slip-on footwear reveals divergent margin architectures across material grades and occasion-based positioning. Canvas constructions dominate volume throughput while leather commands premium pricing in formal channels. Understanding these splits enables targeted resource allocation across manufacturing and distribution investments.
Product Type:
Margin pools concentrate in dress and loafer categories where material costs justify elevated price points and repeat purchase cycles extend.
- Casual:Elasticized goring and unstructured uppers prioritize convenience over support. Demand clusters in United States suburban retail and German weekend leisure contexts where workplace casualization permits all-day wear. Volume leadership here depends on color agility and rapid replenishment cycles.
- Dress:Burnished leather uppers with leather soles or stacked heels meet formal occasion requirements. Italian tannery sourcing and Portuguese finishing sustain margin premiums in Paris, Milan, and London professional corridors. REACH-compliant water-based adhesives are becoming non-negotiable for EU market access.
- Sports:Performance-engineered with knit uppers and energy-return foams. Running communities in Japan and Australia adopt seamless constructions for reduced friction during training.
- Loafers:Moccasin construction with saddle straps or tassel detailing bridges casual and formal occasions. British and American heritage positioning supports pricing power in secondary cities.
The dominant share belongs to Casual, while Dress is closing the gap fastest as office norms relax across European capitals.
Material:
Cost tier stratification separates petroleum-derived synthetics from hide-based alternatives with divergent supply risk profiles.
- Leather:Full-grain and corrected-grain hides deliver patina development and durability measured in wear cycles. Italian and Portuguese processing hubs concentrate supply, exposing brands to hide cost volatility and single-region disruption risk. France's AGEC law and forthcoming EU textile strategy intensify traceability requirements.
- Canvas:Cotton or cotton-blend uppers with rubber vulcanized soles enable sub-$50 retail positioning. Chinese and Vietnamese weaving clusters supply global volume with seasonal color flexibility. California's Proposition 65 enforcement drives reformulation of dyes and treatments for US West Coast distribution.
- Synthetic:PU and microfiber constructions offer water resistance and uniform appearance at mid-tier pricing. Reformulation away from phthalate-containing compounds is ongoing under REACH and state-level US pressure.
- Suede:Napped leather surfaces provide tactile differentiation in fashion-forward segments. Stain resistance treatments face regulatory scrutiny in children's and occupational categories.
Canvas holds volume leadership, yet leather sustains profitability concentration despite supply chain concentration risks.
Target Audience:
Customer type fragmentation is accelerating as generational preferences diverge on sizing conventions and purchase channels.
- Men:Workplace and formal occasion demand concentrates in professional services sectors across Germany, United Kingdom, and United States metropolitan cores. Width sizing and orthopedic compatibility drive retention in 35-55 demographic.
- Women:Fashion cycle sensitivity requires accelerated SKU turnover and influencer channel investment. Seasonal color and embellishment variation supports premium positioning in Seoul, Tokyo, and Shanghai.
- Children:Growth-accommodating construction with reinforced toe caps faces strictest chemical testing burdens under CPSIA and EN 71. Some suppliers have exited this segment entirely due to compliance cost structures.
- Unisex:Binary-agnostic lasts and neutral colorways are expanding most quickly among Gen Z consumers in China and South Korea who reject traditional gendered merchandising. Unified collections collapse inventory complexity but require anthropometric database investment.
Men retain revenue concentration in formal channels, while Unisex is gaining share fastest through digital-native brand positioning.
Usage Occasion:
Application-based segmentation maps directly to distribution channel selection and margin realization.
- Everyday Wear:All-day comfort prioritization drives memory foam insole and flexible outsole specifications. Mass-market retail density in North American suburban malls and European hypermarket chains captures volume.
- Formal Events:Leather construction with minimal visible hardware aligns with black-tie and business formal dress codes. Boutique and direct-to-consumer channels preserve margin through service differentiation.
- Outdoor Activities:Water-resistant treatments and lugged outsoles address garden, beach, and light trail contexts. Australian and California coastal markets show consistent seasonal demand.
- Work:Occupational safety requirements for slip resistance and electrical hazard protection constrain design freedom. Biomechanical limitations of slip-on construction cap penetration in high-impact industrial settings where laced boots dominate certification.
Everyday Wear commands the broadest distribution footprint, though Formal Events sustains the highest per-unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by a factor of four, reflecting divergent brand premiums and distribution infrastructure maturity across these markets.
United States
Technology sector employers in Seattle and Austin now permit slip-on footwear in formal client settings, expanding addressable occasions. California's Proposition 65 enforces strict phthalate limits on synthetic uppers. Portland and Boston anchor premium performance positioning where Nike Inc. leverages automated knitting technologies.
Germany
Workplace casualization in Munich and Frankfurt banking corridors drives dress-category demand for leather constructions. REACH regulations mandate water-based adhesives and reduced chemical footprints in manufacturing. The Bavarian industrial belt hosts specialized last engineering expertise concentrated in technical institutes around Rosenheim.
China
Gen Z consumers in Shanghai and Shenzhen reject binary sizing conventions, forcing unisex collection architectures. The country's dual carbon goals pressure manufacturers toward bio-based materials and energy-efficient production. Dongguan and Wenzhou contract manufacturers serve both domestic markets and export channels with integrated supply chains.
India
Rising disposable income in Mumbai and Bangalore metro corridors creates first-time branded footwear demand among white-collar workers. The Bureau of Indian Standards governs quality benchmarks for consumer safety. Chennai and Delhi-NCR retail expansion targets office-appropriate casual options with localized color preferences.
Japan
Running communities in Tokyo and Osaka adopt seamless knit constructions for reduced friction during training. METI standards guide product safety and material disclosure requirements. The Kansai region maintains concentration in precision footwear manufacturing with heritage craft integration.
Slip on Shoes Market Competitive Landscape
Concentration sits with diversified sportswear conglomerates that control premium performance positioning through proprietary material science. The vendor base spans three tiers: vertically integrated manufacturers with captive tanneries, asset-light brand licensors dependent on contract manufacturing, and regional specialists serving price-sensitive segments. Two dominant competitive moves define current dynamics: automated production technology licensing to collapse unit economics, and direct-to-consumer channel expansion to capture margin previously allocated to wholesale partners.
Within the sportswear conglomerate tier, Nike Inc. and Adidas AG exemplify scale-driven positioning through technology differentiation and global distribution density. Skechers USA Inc. occupies a distinct mass-market position anchored in memory foam comfort positioning and North American retail penetration. Among European heritage specialists, ECCO Sko A/S represents vertically integrated manufacturing with in-house tannery control and premium leather sourcing.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Vans |
| Skechers USA Inc. |
| Crocs Inc. |
| Puma SE |
| TOMS Shoes LLC |
| ECCO Sko A/S |
| Clarks |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with Italian and Portuguese tanneries lock in hide supply access and price visibility for dress-category manufacturers, insulating premium leather sourcing from spot-market volatility while anchoring margin pools in formal footwear channels.
Pricing Analysis
The customization-premium spread separates configured-to-order orthopedic variants from standard casual collections. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and material provenance, with REACH-compliant water-based adhesives commanding tier premiums in EU channels. Price erosion runs through mass-market synthetic segments as automated knitting collapses labor cost differentials. White-collar professionals in German banking corridors exhibit lowest price sensitivity, while suburban North American retail buyers drive volume through promotional elasticity.
Supply Chain Analysis
Just-in-time inventory preferences dominate sportswear conglomerates leveraging automated knitting, while strategic stockpiling of full-grain hides sustains European heritage specialists against tannery concentration risk. Manufacturing gravity centers on China, Vietnam, and Indonesia for canvas and synthetic uppers, with Italian and Portuguese hubs captive for premium leather finishing. Raw material dependencies span natural rubber, EVA foam compounds, and chrome-tanned hides. Single-source vulnerability in hide processing exposes dress-category brands to regional disruption. Distribution runs through wholesale retail partnerships in North American malls and direct-to-consumer platforms capturing margin from owned-commerce expansion.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated knitting and direct-injection molding technologies are collapsing entry barriers, while EU Green Deal compliance mandates reshape material specifications across the value chain.
For Market Incumbents: Compound technology licensing advantages by extending automated production partnerships to mid-tier contract manufacturers, defending against emerging direct-to-consumer entrants. Deepen backward integration into bio-based upper materials to satisfy REACH reformulation timelines and capture certified product premiums. Prioritize in-house tannery control or long-term hide offtakes to mitigate Italian-Portuguese supply concentration. For New Entrants and Emerging Players: Medical-channel service-layer gaps in podiatry clinic partnerships present white-space capture opportunities, where incumbents under-serve orthopedic customization at scale. Target unisex sizing architectures in Chinese and South Korean digital-native segments as the most penetrable consumer type. Deploy AI foot-scanning apps paired with 3D-printed midsole offerings to bypass wholesale margin extraction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers with captive tanneries and direct-to-consumer channel penetration. Long-term viability over the projection horizon favors asset-light brand licensors with design-speed advantages over production-scale dependence. Monitor biomaterial certification timeline compression as the inflection signal for plant-based alternative viability.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Repositioning | REACH-compliant water-based adhesives unlock EU retail channel access and certified product premiums. |
| Direct-to-Consumer Launch | Owned-commerce platforms capture wholesale margin allocation and enable AI-driven customization at scale. |
| Backward Integration | In-house tannery control insulates Italian-Portuguese supply concentration and sustains dress-category margin pools. |
| Technology Licensing | Automated knitting partnerships redistribute competitive advantage toward design speed from production scale. |
| Distribution Channel Expansion | Medical-channel partnerships with German podiatry clinics bypass traditional retail markup structures. |
Research Methodology
A spread of perspectives from brand managers at sportswear conglomerates, category buyers at North American retail chains, technical R&D directors at contract manufacturers, and supply planners at tannery operations converged on the working assumptions. Primary interview insights combined with secondary validation from customs records, SEC footwear sector filings, SATRA testing protocol documentation, and EU regulatory databases. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled span product type, material grade, target audience, and usage occasion, with regional regulatory cluster as the industry-specific overlay. CAGRs derived from historical trajectory analysis and forward-looking scenario weighting. Forecast inputs incorporated workplace casualization velocity indices and biomaterial certification pipeline status throughout the projection horizon.
Forecasts assume regulatory continuity in EU REACH, California Proposition 65, and India's BIS regimes; material policy shifts would require re-modeling. Specific risks include petrochemical input volatility, tannery supply disruption, and extended biodegradability validation timelines. Revision becomes warranted when automated production cost curves cross traditional cut-and-sew breakeven thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Waterproof Sneakers Market
Footwear
Dance Shoes Market
Footwear
Sneaker Boots Market
Footwear
Premium Shoes Market
Footwear
Running Shoes Market
Footwear
North America Athletic Footwear Market
Footwear
Global Footwear Market
Footwear
Sports Footwear Market
Footwear
Formal Shoes Market
Footwear
Snow Boots for Women Market
Footwear
Cowboy Boots Market
Footwear
Athletic Footwear Market
Footwear
E-Commerce Footwear Market
Footwear
White Sneakers Market
Footwear
UGG Boots Market
Footwear
Europe Athletic Footwear Market