
 Women's Non-Athletic Footwear Market | 2026-2036
Women's Non-Athletic Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Women's Non-Athletic Footwear Market Insights
A capital-intensity divergence between heritage luxury manufacturers and fast-fashion retailers is bifurcating competitive dynamics across the women's non-athletic footwear landscape. Prada SpA leverages its vertically integrated Italian manufacturing base to command premium positioning in formal leather segments. Bata Corporation anchors volume distribution through its company-owned retail network spanning emerging markets. Ecco Sko AS differentiates through proprietary direct-injection polyurethane sole technology that reduces labor steps while improving durability.
Women's non-athletic footwear encompasses closed-toe and open-toe styles engineered without performance athletic features, typically constructed through cemented or Blake-stitched assembly using leather uppers, TPU outsoles, and padded footbeds designed for occupational, social, and daily casual wear rather than sport-specific biomechanics. The material dimension shows leather commanding the luxury tier while synthetic alternatives capture mid-range and affordable segments where cost scalability matters. Style segmentation reveals casual and formal categories generating the majority of revenue pools, with bohemian and vintage sub-styles growing fastest among younger demographics seeking differentiation through aesthetic niche positioning.
REACH in Europe restricts chromium VI and certain azo dyes in leather tanning, compelling suppliers to reformulate chemical processes or face market exclusion. The US Consumer Product Safety Commission monitors phthalate content in synthetic uppers and PVC components, particularly affecting discount-tier imports. China's GB standards for footwear quality and labeling, administered by SAMR, create compliance thresholds for both domestic distribution and export manufacturing. Stakeholders must track evolving chemical restriction schedules and traceability mandates to anticipate which material technologies will secure regulatory clearance ahead of competitors.
Market Dynamics
REACH chemical restrictions in Europe are forcing tanneries to abandon chromium VI processes, triggering a supply-chain recalibration that favors manufacturers with advanced material R&D capabilities and certified alternative tanning chemistry.
Growth Catalysts
- Urban professional wardrobe expansion:Working women in tier-one Chinese cities are building occasion-specific footwear collections, driving demand for formal leather pumps and versatile block-heel designs.
- Direct-injection polyurethane technology:Proprietary sole-molding processes reduce assembly labor while improving outsole durability, compressing unit economics for mid-tier producers.
- EU Green Deal textile strategy:Circular design mandates and extended producer responsibility frameworks are accelerating investment in recyclable TPU and bio-based synthetic alternatives.
Market Restraints
- Leather input cost volatility:Premium hide prices fluctuate with livestock supply cycles and tanning chemical substitution costs, squeezing margin structures for Blake-stitched formal segments.
- Supply concentration in Italian manufacturing clusters:Heritage production gravity in Marche and Tuscany creates bottleneck risk for luxury cemented construction.
- Phthalate restriction compliance friction:US Consumer Product Safety Commission monitoring of PVC components in synthetic uppers blocks entry for uncertified discount-tier imports.
Strategic Opportunities
- Underpenetrated Indian tier-two cities:Rising female workforce participation in Bengaluru and Hyderabad outpaces formal footwear availability, creating whitespace for organized retail expansion.
- Regulatory tailwind from China's dual carbon goals:MEE emissions standards favor domestic brands investing in waterless dyeing and renewable energy-tethered production.
- Digital-native resale channel emergence:Peer-to-peer authenticated pre-owned platforms capture younger demographics seeking vintage sub-styles without primary purchase commitment.
Industry Challenges
- Specialized pattern-making talent scarcity:Last design and fit engineering expertise concentrates in aging European workforces, constraining new entrant capability building.
- Multi-jurisdiction certification timelines:Simultaneous compliance with REACH, GB standards, and state-level US requirements extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women's Non-Athletic Footwear Market |
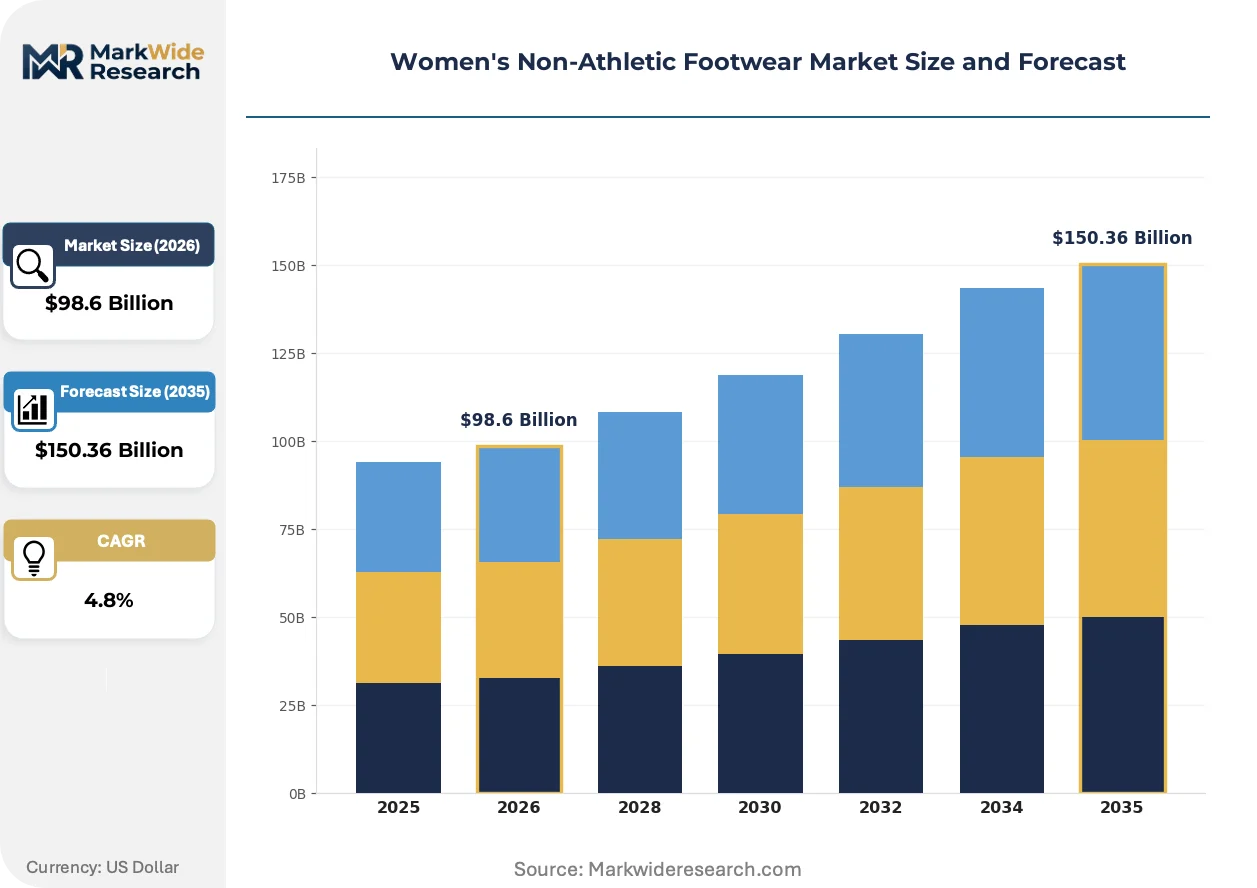
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $150.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flats, Heels, Loafers, Sandals Material: Leather, Suede, Synthetic, Canvas Style: Casual, Formal, Bohemian, Vintage Price Tier: Luxury, Mid-Range, Affordable, Discount |
| Companies Covered | Prada SpA, Bata Corporation, LVMH, Capri Holdings, Chanel, Kering, The ALDO Group Inc., Ecco Sko AS, Tapestry Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women's Non-Athletic Footwear Market Trends and Innovations
Material science breakthroughs and chemical compliance mandates are restructuring how women's non-athletic footwear is designed, sourced, and sold. Three converging developments are compressing legacy competitive advantages.
Waterless dyeing and digital printing technologies are displacing conventional drum-dyeing processes in synthetic upper production. Fast-fashion retailers in Zhejiang province are adopting these systems at scale to meet shorter color-cycle demands. The shift is compressing minimum order quantities and enabling micro-batch releases that disrupt seasonal wholesale calendars.
EU REACH annex XVII updates restricting chromium VI and specific azo dyes have forced tanneries to reformulate wet-blue processing. Italian manufacturers absorbing these compliance costs are passing premiums to formal leather segments. The regulation is accelerating supplier consolidation toward integrated chemical management systems certified by ECHA-recognized bodies.
After-sales service unbundling is fragmenting traditional retail relationships as direct-to-consumer brands sell repair kits and resoling subscriptions separately from initial purchase. Urban professional women in Shanghai and São Paulo demonstrate highest uptake of these modular ownership models. The behavior is compressing brand loyalty metrics and elevating transparency around material provenance as a purchase determinant.
Women's Non-Athletic Footwear Market Segmentation
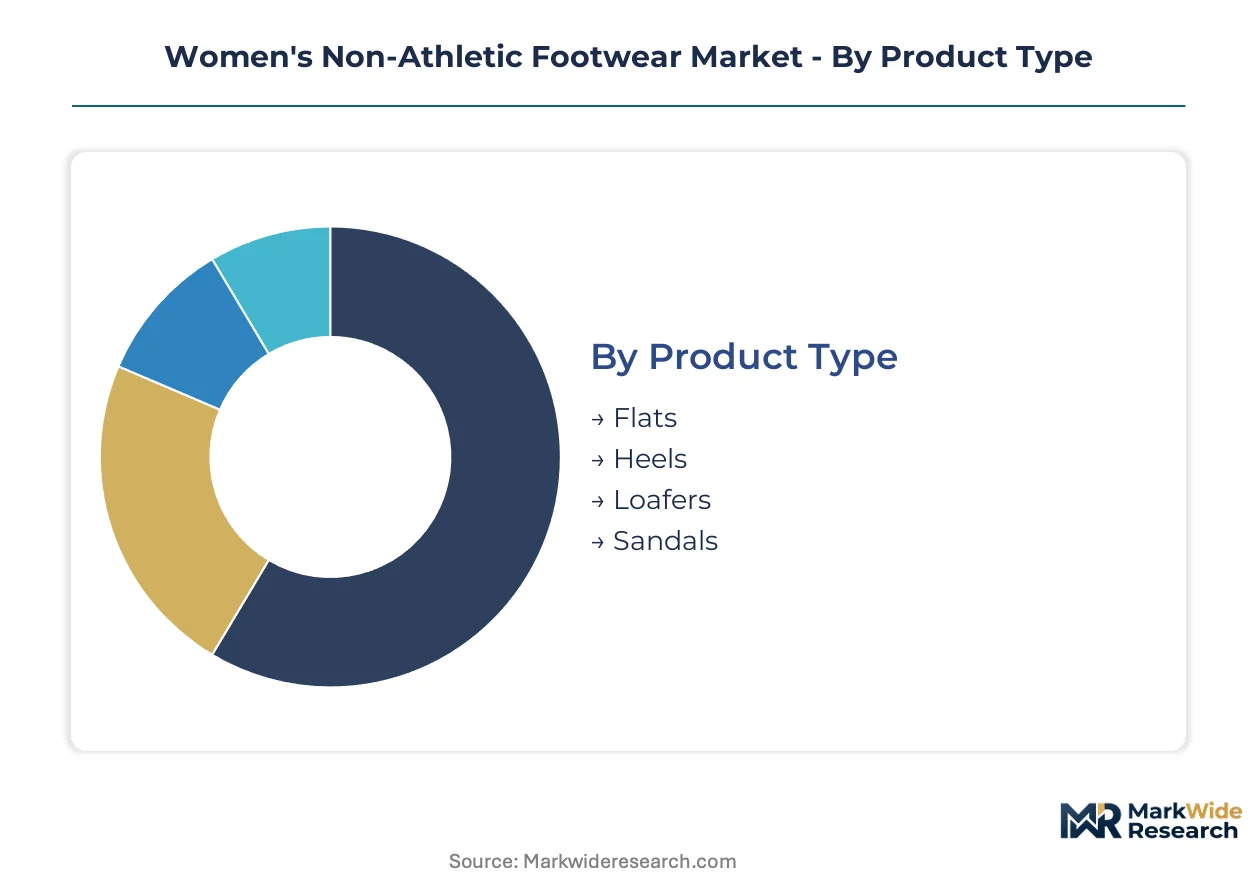
Segmentation in women's non-athletic footwear reveals how occasion-specific demand, material provenance, and price accessibility split purchasing decisions across channels. Understanding these divides exposes where margin pools concentrate and which technology investments reshape competitive positioning.
Product Type:
Wholesale and direct-to-consumer channels carry sharply different product mixes, with formal styles dominating department store floors while flats and sandals drive e-commerce conversion rates.
- Flats:Closed-toe and open-toe designs with sub-2cm heel elevation, constructed through cemented assembly for lightweight daily wear. Demand clusters among urban professional women in Shanghai and São Paulo seeking commute-compatible versatility, constrained by synthetic upper breathability limitations in humid climates.
- Heels:Elevated designs exceeding 5cm employing steel shank reinforcement and padded footbeds for structural integrity. Corporate dress codes in tier-one Chinese cities sustain formal pump demand, though block-heel variants are gaining share fastest as comfort priorities shift.
- Loafers:Slip-on constructions with moccasin or apron-toe stitching, traditionally Blake-stitched for flexibility. Traction concentrates in transitional workwear segments where hybrid office policies blur formal-casual boundaries.
- Sandals:Open constructions with TPU or leather strap systems, ranging from minimalist flatbeds to platform elevations. Seasonal purchasing patterns in Mediterranean and Southeast Asian climates sustain volume, with digital-native resale channels capturing vintage sub-style interest.
Flats dominate installed base across all measured channels. Heels represent where expansion concentrates among professional wardrobe builders.
Material:
Cost tier alignment determines material deployment, with luxury houses absorbing hide price volatility while mid-range producers pivot to synthetic alternatives for margin protection.
- Leather:Full-grain and corrected-grain cattle hides processed through chrome or vegetable tanning, delivering structural memory and patina development. Italian Marche and Tuscany clusters anchor premium supply, though REACH chromium VI restrictions are forcing wet-blue process reformulation that compresses certified tannery availability.
- Suede:Split leather with napped surface finish, requiring specialized brushing equipment and moisture-resistant treatments. Niche positioning in bohemian and vintage style segments limits volume scale but sustains price premiums in authenticated resale channels.
- Synthetic:Polyurethane and PVC upper formulations enabling color consistency and water resistance at production scale. Fast-fashion retailers in Zhejiang province deploy waterless dyeing systems to compress lead times and meet micro-batch release demands.
- Canvas:Cotton or hemp woven uppers with rubber cupsole attachment, historically associated with casual beach and resort wear. Sustainability-focused brands emphasize organic fiber certification and natural rubber sourcing to differentiate within affordable tiers.
Leather commands the premium tier by installed value. Synthetic materials are climbing the fastest as waterless dyeing and direct-injection sole technologies compress unit economics.
Style:
Customer type fragmentation splits style demand, with millennial and Gen-Z demographics driving aesthetic niche positioning that resists mass-market standardization.
- Casual:Versatile designs prioritizing comfort engineering and multi-occasion adaptability, typically constructed with cemented soles and padded insoles. Volume concentration in mass-market retail and e-commerce platforms reflects wardrobe staple purchasing behavior.
- Formal:Occasion-specific constructions adhering to corporate and ceremonial dress codes, employing Blake-stitched or Goodyear-welted assembly for durability signaling. Heritage Italian manufacturers maintain production gravity despite supply concentration risk.
- Bohemian:Artisanal aesthetics featuring fringe, embroidery, and natural material combinations, often produced through small-batch manufacturing in Rajasthan and Marrakech clusters. Digital-native resale platforms capture younger demographic interest without primary purchase commitment.
- Vintage:Reproduction or authenticated pre-owned styles referencing 1920s-1980s design archives. Peer-to-peer authentication services in Shanghai and São Paulo demonstrate highest uptake, compressing traditional brand loyalty metrics.
Casual and formal styles dominate installed revenue pools. Bohemian and vintage sub-styles are expanding most quickly among differentiation-seeking younger consumers.
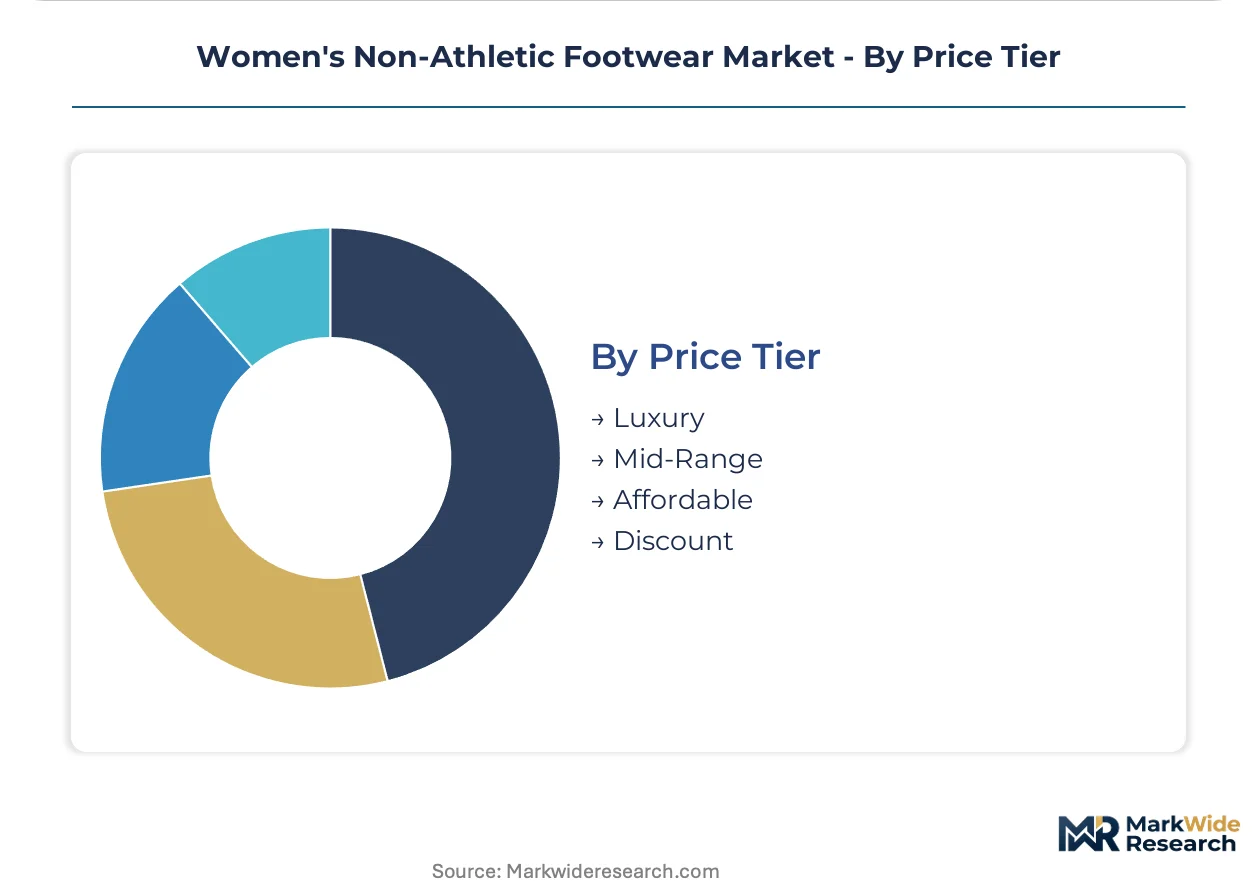
Price Tier:
Margin structure varies dramatically across tiers, with luxury segments absorbing compliance and certification costs that exclude discount-tier competitors from regulated markets.
- Luxury:Heritage house positioning above $500 retail, justified by vertically integrated Italian manufacturing, hand-finished details, and material traceability documentation. ECHA-recognized chemical management certification and extended producer responsibility compliance sustain entry barriers.
- Mid-Range:Organized retail and direct-to-consumer brands occupying $100-300 price band, competing on design refresh velocity and comfort technology claims. Proprietary direct-injection polyurethane sole processes enable durability differentiation without full luxury cost structure.
- Affordable:Mass-market distribution through hypermarket and value retail channels, typically $30-100 retail with synthetic-dominant material mixes. GB standards compliance and phthalate restriction adherence determine China and US market access.
- Discount:Unbranded or private-label imports through informal retail and marketplace platforms, sub-$30 price positioning. US Consumer Product Safety Commission monitoring of PVC components blocks uncertified entry, concentrating volume in less regulated developing markets.
Mid-range and affordable tiers dominate unit volume. Luxury positioning captures where margin expansion concentrates as regulatory compliance costs reshape competitive dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese consumers in tier-one cities show the lowest price elasticity for formal leather construction, while Indian tier-two buyers remain acutely sensitive to synthetic alternatives. European professional women absorb REACH compliance premiums without volume contraction. US discount-tier demand collapses where phthalate restrictions bite hardest.
China
Urban professional women in Shanghai and Beijing are building occasion-specific wardrobes across pumps, loafers, and block-heel designs. SAMR-administered GB standards for footwear quality and labeling create compliance thresholds for both domestic distribution and export manufacturing. The Yangtze River Delta manufacturing cluster around Wenzhou and Guangdong's Pearl River Delta dominate synthetic upper production with waterless dyeing adoption.
United States
Corporate dress code relaxation in coastal metros is shifting volume toward transitional loafers and versatile flats. The Consumer Product Safety Commission monitors phthalate content in PVC components, blocking uncertified discount-tier imports from informal channels. New York and Los Angeles anchor premium retail distribution while Southeast Asian-sourced inventory concentrates in Miami logistics hubs.
Italy
Heritage formal segments sustain demand for Blake-stitched and Goodyear-welted construction despite unit contraction in mass channels. REACH annex XVII restrictions on chromium VI and azo dyes are forcing Marche and Tuscany tanneries to reformulate wet-blue processes. The Marche manufacturing cluster around Macerata maintains production gravity for luxury cemented construction.
India
Rising female workforce participation in Bengaluru and Hyderabad is outpacing organized formal footwear availability. Bureau of Indian Standards quality mandates and DGFT import regulations shape competitive access for synthetic versus leather product lines. The Tamil Nadu leather cluster around Ambur and Vaniyambadi supplies domestic tanneries while Kanpur's Uttar Pradesh hub struggles with effluent compliance.
Brazil
Peer-to-peer authenticated resale platforms in São Paulo demonstrate highest uptake of vintage sub-styles among younger demographics. ANVISA monitoring of chemical content in imported synthetics creates friction for uncertified Asian suppliers. The Rio Grande do Sul footwear cluster around Novo Hamburgo specializes in comfort-engineered casual construction for Latin American distribution.
Women's Non-Athletic Footwear Market Competitive Landscape
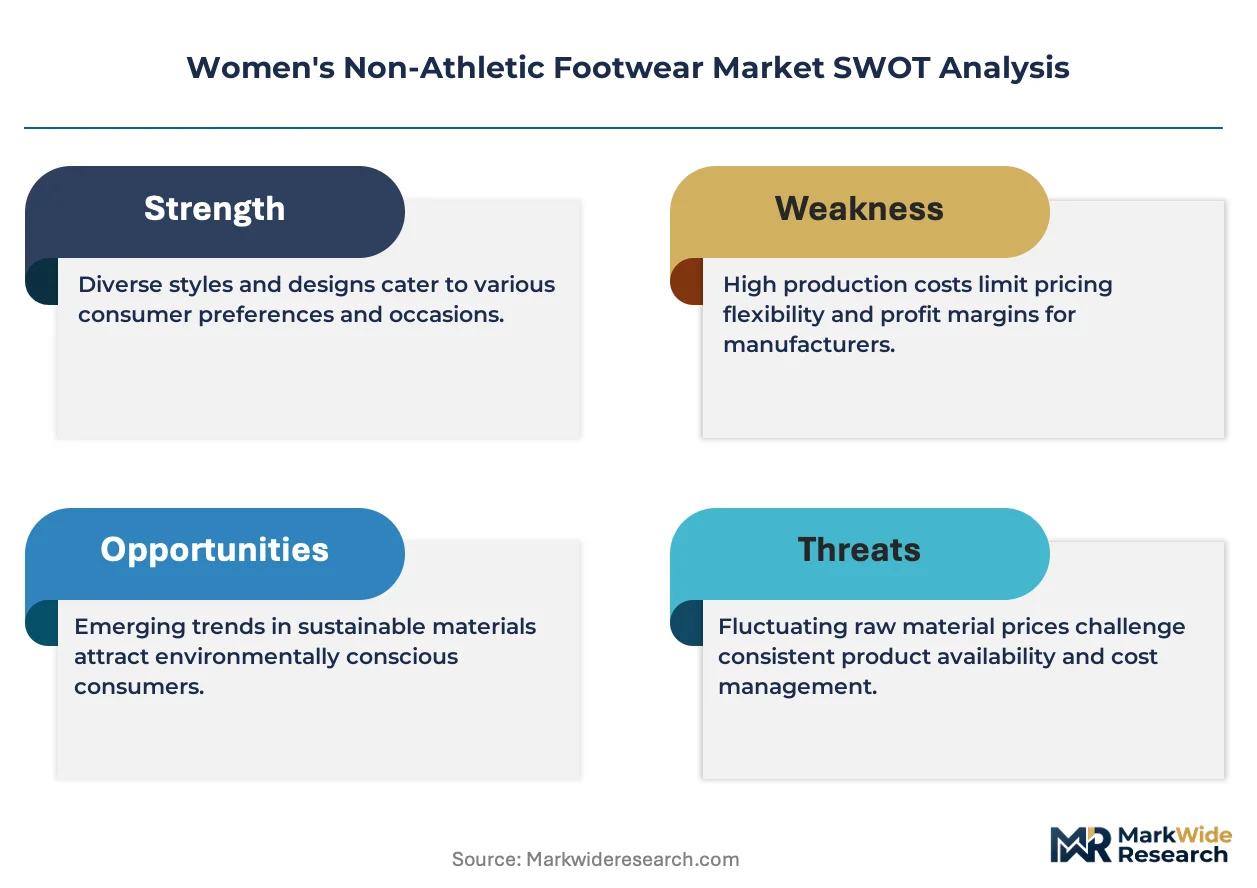
A small set of integrated leaders sits above a broader specialist tier, with heritage luxury houses controlling premium material pipelines and fast-fashion retailers capturing volume through rapid design refresh. The competitive structure rewards players with captive tannery relationships or proprietary sole technology. Three archetypes dominate: vertically integrated Italian manufacturers, emerging-market retail network operators, and technology-differentiated mid-tier producers. Consolidation is concentrating among M&A-driven portfolio expansion and direct-to-consumer channel builds.
Within the heritage luxury tier, Prada SpA and LVMH exemplify vertically integrated positioning anchored in Italian manufacturing gravity. Ecco Sko AS occupies a distinct technology-differentiated position through proprietary sole processes. Bata Corporation represents the emerging-market network archetype with company-owned retail spanning multiple continents. Kering and Tapestry Inc. sit within the diversified portfolio tier, while Capri Holdings and Chanel exemplify brand-centric positioning. The ALDO Group Inc. anchors mid-market accessible fashion distribution.
| Leading Market Players |
|---|
| Prada SpA |
| Bata Corporation |
| LVMH |
| Capri Holdings |
| Chanel |
| Kering |
| The ALDO Group Inc. |
| Ecco Sko AS |
| Tapestry Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Italian tanneries and heritage luxury houses lock in hide supply access while anchoring price visibility for Blake-stitched formal segments. This contract structure insulates premium manufacturers from spot-market volatility in raw cattle hide costs, though REACH chemical reformulation expenses are compressing margin structures across certified wet-blue processing tiers.
Pricing Analysis
After-sales service revenue from repair kits and resoling subscriptions now drives lifetime value compression across direct-to-consumer brands. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and material provenance documentation, with ECHA-recognized chemical management systems commanding measurable premiums. Pricing pressure stems from waterless dyeing technology adoption in Zhejiang synthetic production clusters. Discount-tier buyers in informal channels exhibit acute price sensitivity, while tier-one Chinese urban professionals absorb REACH compliance premiums without volume contraction.
Supply Chain Analysis
Inventory cycles stretching across seasonal wholesale calendars are compressing as waterless dyeing and digital printing technologies displace conventional drum-dyeing processes. Supply concentration rests on Italy for premium leather tanning, China for synthetic upper production, and India for emerging-market volume manufacturing. Raw material dependencies center on cattle hides, polyurethane formulations, and TPU outsole compounds. Single-source vulnerability concentrates in Marche and Tuscany clusters for Blake-stitched formal construction. Distribution runs through company-owned retail networks in emerging markets and direct-to-consumer platforms in developed economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are restructuring competitive dynamics as peer-to-peer authenticated resale channels fragment traditional retail relationships and elevate transparency around material provenance as a purchase determinant.
For Market Incumbents: Shield formal leather positioning by deepening captive tannery relationships in Marche and Tuscany clusters against synthetic substitution threats. Invest in ECHA-recognized chemical management certification to sustain REACH compliance barriers that exclude discount-tier competitors. Channel control through company-owned retail expansion in Indian tier-two cities offers defensive whitespace capture. For New Entrants and Emerging Players: Repair and resoling subscription services represent the most penetrable service-layer gap where heritage houses under-serve younger demographics. Target digital-native resale platform partnerships in São Paulo and Shanghai for vintage sub-style authentication without primary inventory risk. Go-to-market through micro-batch waterless dyeing capabilities enables rapid color-cycle responsiveness that disrupts seasonal wholesale calendars. For Investors and Strategic Acquirers: Proprietary direct-injection polyurethane sole technology specialists with certified alternative tanning chemistry represent the priority acquisition archetype. Long-term viability frames around regulatory tailwinds from circular design mandates and extended producer responsibility frameworks. Watch for MEE emissions standard enforcement intensity in China as the inflection signal for domestic brand competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Buildout | Bypasses wholesale margin compression while capturing resale subscription revenue from urban professional women. |
| Waterless Dyeing Technology Adoption | Zhejiang province deployment enables micro-batch releases that compress lead times against seasonal calendars. |
| Certified Alternative Tanning Chemistry | ECHA-recognized wet-blue reformulation secures REACH compliance clearance ahead of supplier consolidation. |
| Indian Tier-Two Retail Expansion | Bengaluru and Hyderabad female workforce participation outpaces organized formal footwear availability. |
| Resale Platform Authentication Partnership | Peer-to-peer vintage sub-style capture elevates material provenance transparency as purchase determinant. |
Research Methodology
The analysis maps formal leather, synthetic casual, and resale platform sub-sectors, each validated through supply chain stakeholders including tannery operations managers, retail category buyers, and direct-to-consumer brand founders. Primary interviews with Italian manufacturing cluster supervisors and Zhejiang province production directors combined with secondary validation from SAMR GB standards filings, REACH annex XVII updates, and customs trade data. Bottom-up unit economics modeling and top-down market sizing triangulated across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across material type, price tier, and regional regulatory cluster segmentation. CAGRs derived from trend extrapolation of urban professional wardrobe expansion patterns and technology adoption curves in waterless dyeing systems. Forecast inputs incorporated female workforce participation trajectories in tier-one Chinese cities and REACH chemical restriction implementation timelines.
Forecasts assume regulatory continuity in EU REACH, US Consumer Product Safety Commission, and China SAMR regimes; material policy shifts would require re-modeling of tannery compliance cost pass-through and synthetic import access. Revision becomes warranted when MEE emissions enforcement intensity or peer-to-peer resale platform penetration crosses thresholds that reshape primary purchase commitment behavior.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Leather Footwear Market
Footwear
Driving Footwear Market
Footwear
Outdoor Trail Running Shoes Market
Footwear
Womens Footwear Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
GCC Footwear Market
Footwear
Women's Sneakers Market
Footwear
Golf Footwear Market
Footwear
Trail Running Shoes Market
Footwear
Chunky Sneaker Market
Footwear
South America Athletic Footwear Market
Footwear
Global Men Leather Shoes Market
Footwear
UGG Boots Market
Footwear
Duck Boots Market
Footwear
White Sneakers Market
Footwear
High Heels Footwear Market