
 UK Lifestyle Sneakers Market | 2026-2036
UK Lifestyle Sneakers Market Size, Share, and Industry Trends Forecast 2026-2036
UK Lifestyle Sneakers Market Insights
Market Context with Strategic Players
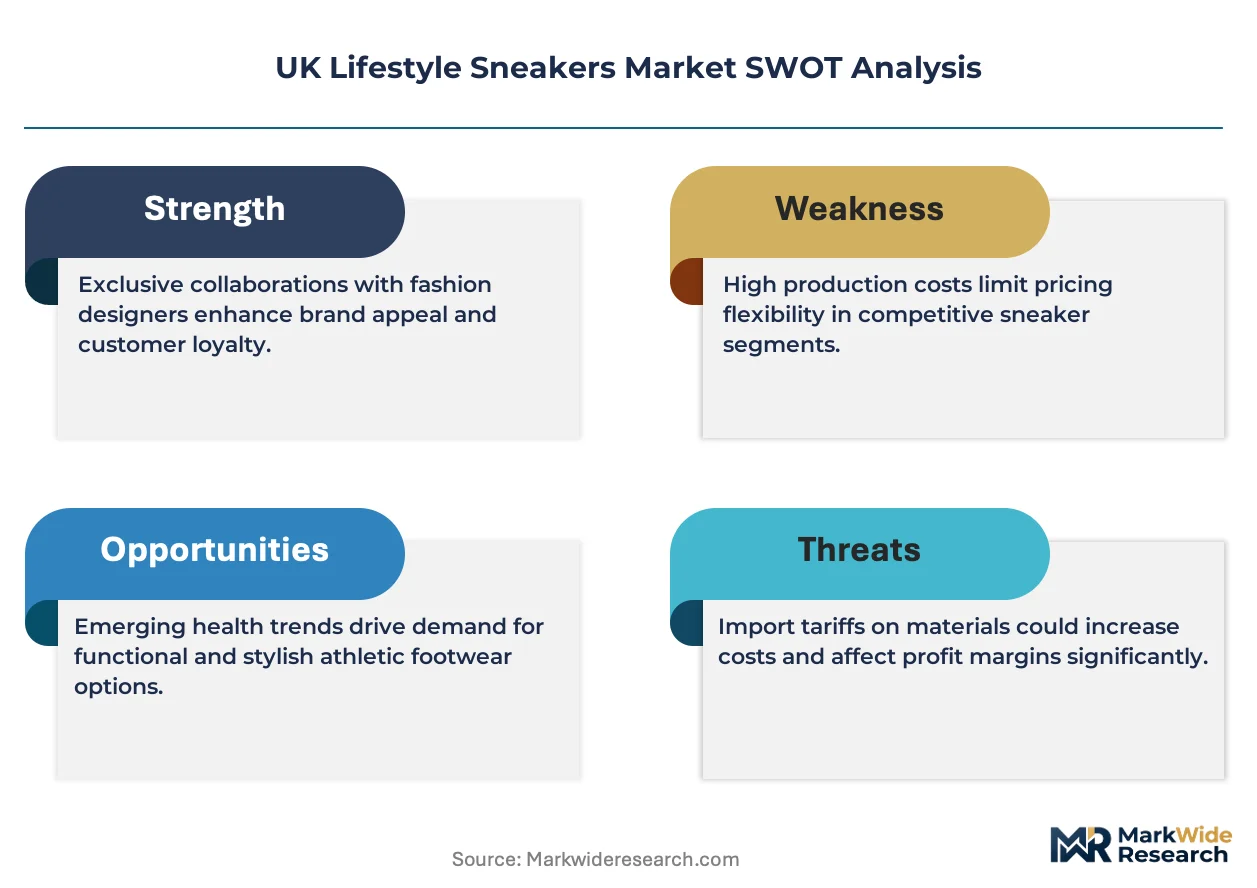
Sneaker design talent scarcity is bifurcating the UK market between heritage houses and agile newcomers. Nike, Inc. leverages its London-based innovation hub to anchor trend responsiveness in the capital's fashion ecosystem. Adidas AG sustains competitive pressure through specialized sustainable material R&D partnerships with British textile developers. Grenson Shoes differentiates via artisanal Northamptonshire manufacturing heritage that commands premium positioning in independent retail channels.
Technical Definition and Structural Segments
UK lifestyle sneakers are non-performance athletic footwear engineered with EVA or polyurethane midsoles, knit or leather uppers, and rubber outsoles, designed primarily for casual, social, and fashion-forward everyday wear rather than sport-specific function. Casual Sneakers and Slip-Ons dominate volume through mass-market accessibility, while the Premium and Luxury price tiers capture disproportionate margin pools as British consumers prioritize provenance and limited-edition collaborations. Mesh and Synthetic materials lead unit production for their cost efficiency, though Leather commands higher per-unit profitability and stronger resale velocity in secondary markets.
Regulatory Frame and Forward-Looking Close
The UK's Plastic Packaging Tax, Extended Producer Responsibility framework, and Trading Standards product safety requirements collectively elevate compliance costs while rewarding circular business models and domestic repair services. BSI standards for footwear safety and chemical content restrict import flexibility, particularly for synthetic-heavy supply chains. Stakeholders must monitor how post-Brexit customs alignment with EU REACH chemical regulations evolves, as divergence would fragment sourcing strategies across Northern Ireland and Great Britain distribution networks.
Market Dynamics
The UK's Plastic Packaging Tax and Extended Producer Responsibility framework are compressing margins for synthetic-heavy supply chains while creating asymmetric advantages for brands with circular repair infrastructure and domestic material partnerships.
Growth Catalysts
- Gen Z Urban Demand:Consumers in London and Manchester prioritize sustainable and tech-integrated footwear, pulling premium and limited-edition releases into faster inventory turnover cycles.
- REACH Alignment Pressure:Post-Brexit chemical regulation continuity with EU standards maintains import pathway clarity for compliant British distributors sourcing from continental suppliers.
- Northamptonshire Manufacturing Heritage:Artisanal production clusters command independent retail channel access and provenance premiums that mass-market competitors cannot replicate.
Market Restraints
- Petrochemical Input Volatility:EVA and polyurethane midsole materials face price instability tied to crude oil derivatives, compressing margin predictability for volume-tier producers.
- Asian Supply Concentration:Rubber outsole and knit upper production concentrates in East Asian contract manufacturers, exposing British brands to shipping cost spikes and customs friction.
- BSI Certification Burden:Footwear safety and chemical content standards create multi-month compliance timelines that delay seasonal product launches for new market entrants.
Strategic Opportunities
- Circular Repair Services:The UK's Extended Producer Responsibility framework incentivizes domestic refurbishment infrastructure that captures resale velocity and extends customer lifetime value.
- Recycled Material R&D Partnerships:Collaboration with British textile developers on sustainable uppers creates differentiated positioning against import-dependent competitors.
- Greater London Premium Concentration:Southeast England's disproportionate purchasing power supports direct-to-consumer flagship expansion with higher per-unit profitability than wholesale channels.
Industry Challenges
- Sneaker Design Talent Scarcity:Bifurcation between heritage houses and agile newcomers intensifies compensation pressure for footwear designers with both technical and fashion credentials.
- Northern Ireland Distribution Fragmentation:Post-Brexit customs alignment uncertainty complicates unified inventory management across Great Britain and Northern Ireland retail networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Lifestyle Sneakers Market |
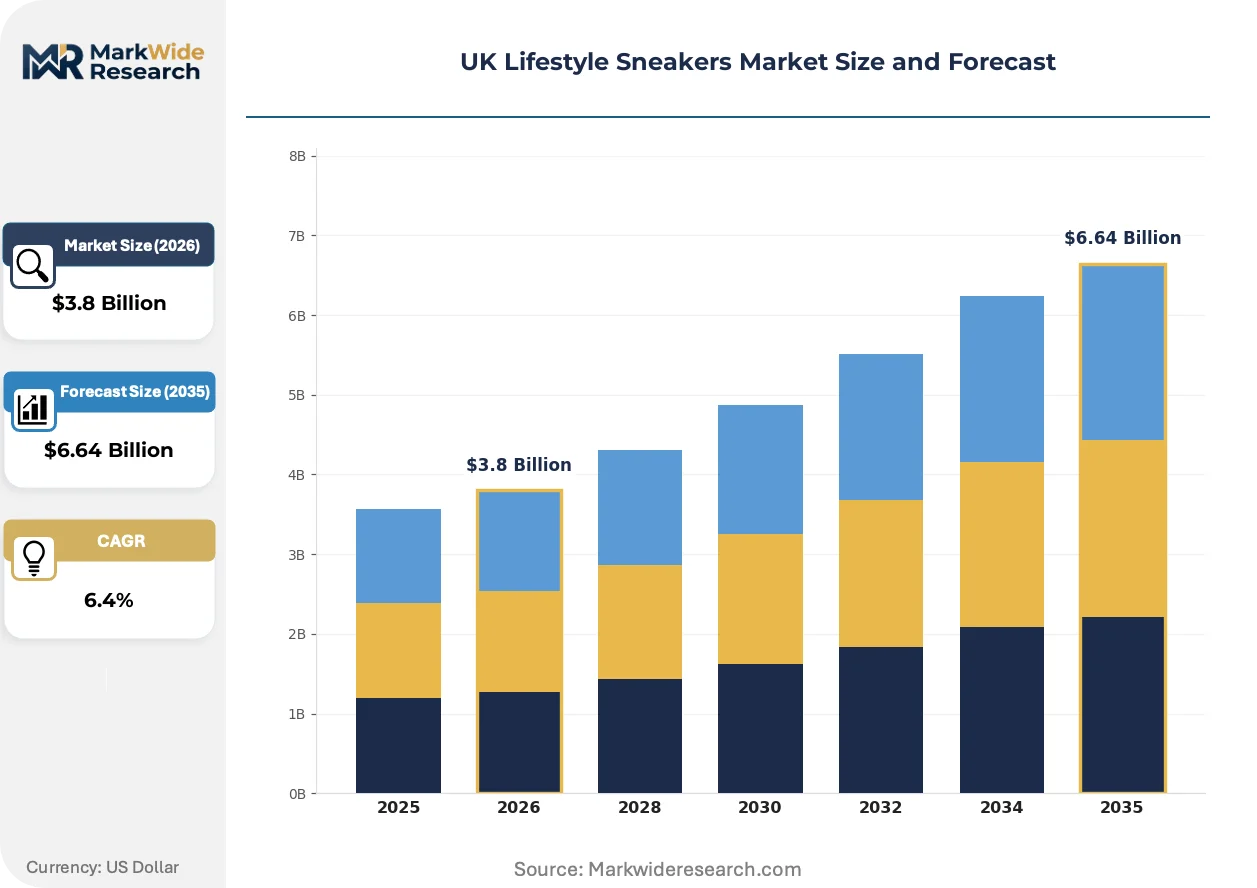
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Running Shoes, Casual Sneakers, High-Tops, Slip-Ons End User: Men, Women, Children, Unisex Shoe Material: Leather, Canvas, Synthetic, Mesh Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Puma SE, Converse, Nike, Inc., C. & J. Clark International Limited, FILA, Adidas AG, Vans, Grenson Shoes, New Balance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Lifestyle Sneakers Market Trends and Innovations
Bio-based material chemistry, regulatory compliance automation, and resale platform integration are restructuring how UK lifestyle sneakers are designed, certified, and monetized across their lifecycle.
Algae-derived foam midsoles are displacing conventional petroleum-based EVA in premium tier production. London-based innovation labs and independent British brands are piloting these compounds for limited releases. The shift is compressing synthetic material demand while creating supply bottlenecks for cultivated algae feedstock.
The UK's Extended Producer Responsibility framework and Plastic Packaging Tax are accelerating circular design investment. Brands must now account for end-of-life material recovery costs in upfront pricing. Premium and luxury segments are responding fastest through take-back programs and modular construction that simplifies component separation.
Secondary market authentication via embedded NFC chips is shortening replacement cycles among collector segments. Digital verification platforms are displacing traditional retail trust relationships for high-value releases. This behavior concentrates most visibly in Greater London's resale ecosystem and Manchester's fashion-forward consumer base.
UK Lifestyle Sneakers Market Segmentation
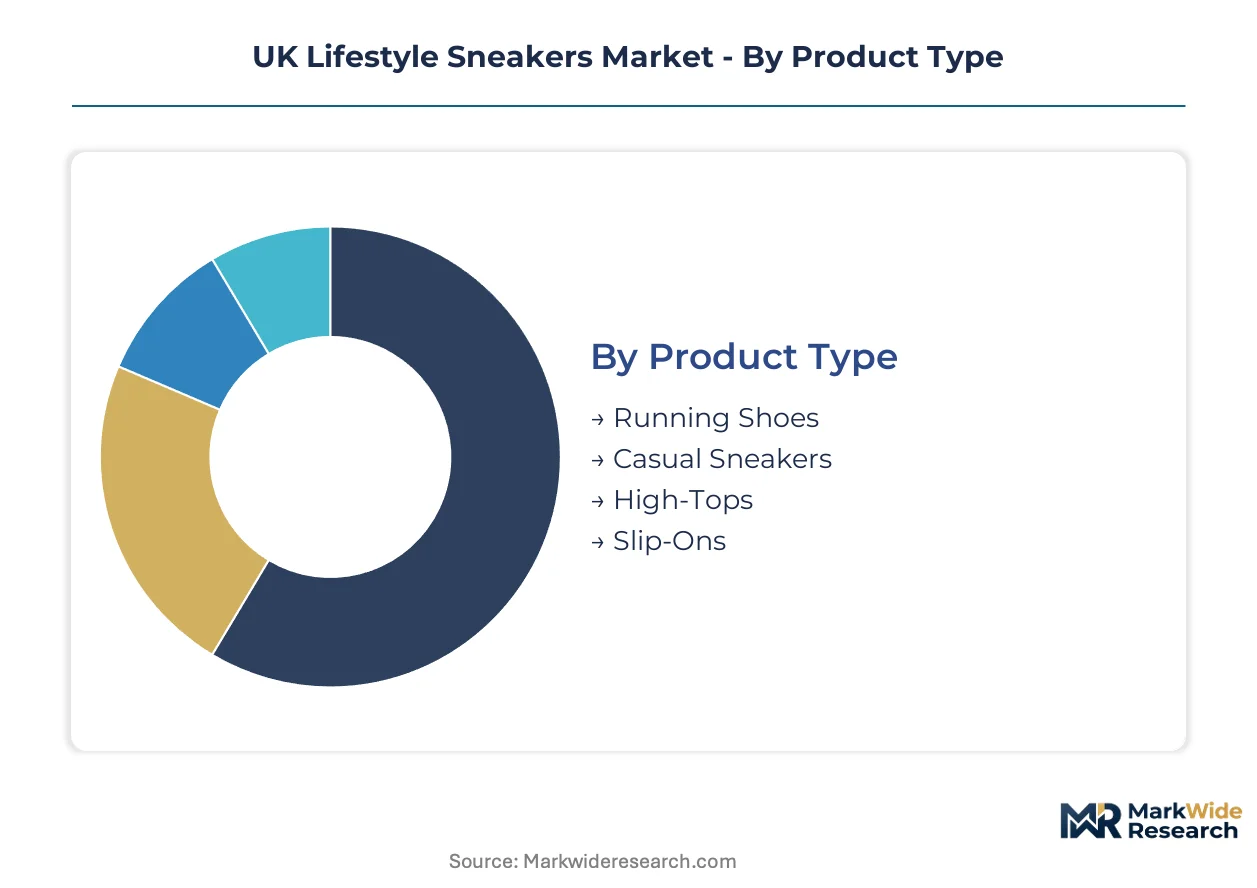
Segmentation in the UK lifestyle sneakers market reveals how regulatory pressure and consumer preference divergence are fragmenting demand across material, demographic, and price dimensions. Understanding these fault lines exposes where substitution threats from resale platforms, repair services, and alternative footwear categories concentrate.
Product Type:
Casual Sneakers and Slip-Ons face intensifying substitution pressure from refurbished footwear platforms and minimalist shoe trends, while performance-adjacent categories defend share through technical differentiation.
- Casual Sneakers:Engineered with EVA or polyurethane midsoles and knit or leather uppers for everyday social wear. Demand concentrates in Greater London and the Southeast where Gen Z consumers prioritize limited-edition collaborations and faster inventory turnover cycles.
- Slip-Ons:Constructed with elasticized goring or knit collars eliminating lacing systems for convenience-focused urban commuters. Manchester's fashion-forward consumer base drives adoption as work-leisure boundaries blur in northern urban centers.
- Running Shoes:Lifestyle-oriented designs borrowing performance aesthetics without sport-specific function. Northamptonshire artisanal clusters supply premium tier variants commanding independent retail provenance premiums.
- High-Tops:Ankle-stabilizing silhouettes with extended collars targeting collector segments and streetwear alignment. Secondary market authentication via embedded NFC chips concentrates value in Greater London's resale ecosystem.
Casual Sneakers anchors the volume base while Slip-Ons gains share at the steepest rate.
End User:
Demographic concentration follows urban disposable income distribution, with gendered purchasing patterns diverging sharply on sustainability premium willingness.
- Women:Prioritize material provenance and circular design features, driving fastest adoption of take-back programs and modular construction. London-based innovation hubs target this segment with algae-derived foam midsoles and British textile partnerships.
- Men:Dominate collector and resale platform engagement, with secondary market velocity concentrated in high-value limited releases. Digital verification platforms displace traditional retail trust relationships for authentication.
- Children:Growth-constrained segment facing compressed replacement cycles as sizing requirements outpace durability design. Parents in the Southeast show elevated price sensitivity despite overall regional purchasing power concentration.
- Unisex:Emerging positioning strategy for brands seeking inventory efficiency across gendered retail floor plans. Sizing standardization challenges complicate fit consistency in volume-tier production.
Men anchors the volume base while Women climbs the fastest as sustainability premiums reshape purchasing hierarchies.
Shoe Material:
Material cost tiers stratify around regulatory compliance burden, with petroleum-derived synthetics facing margin compression from the UK's Plastic Packaging Tax and evolving Extended Producer Responsibility frameworks.
- Mesh:Knitted synthetic or natural fiber uppers delivering breathability and cost efficiency at volume scale. East Asian contract manufacturers dominate production, exposing British brands to shipping cost spikes and customs friction.
- Leather:Tanned hide uppers commanding highest per-unit profitability and strongest resale velocity in secondary markets. Northamptonshire manufacturing heritage provides domestic sourcing alternative reducing import dependency.
- Synthetic:Petroleum-derived polymer uppers facing price instability tied to crude oil derivatives. BSI standards for chemical content restrict import flexibility particularly for non-compliant Asian supply chains.
- Canvas:Woven cotton or hemp uppers occupying mid-tier positioning with heritage aesthetic appeal. British textile developers are piloting recycled cotton variants in response to circular design investment acceleration.
Synthetic anchors the volume base while Leather expands most quickly as provenance premiums and resale velocity concentrate value.
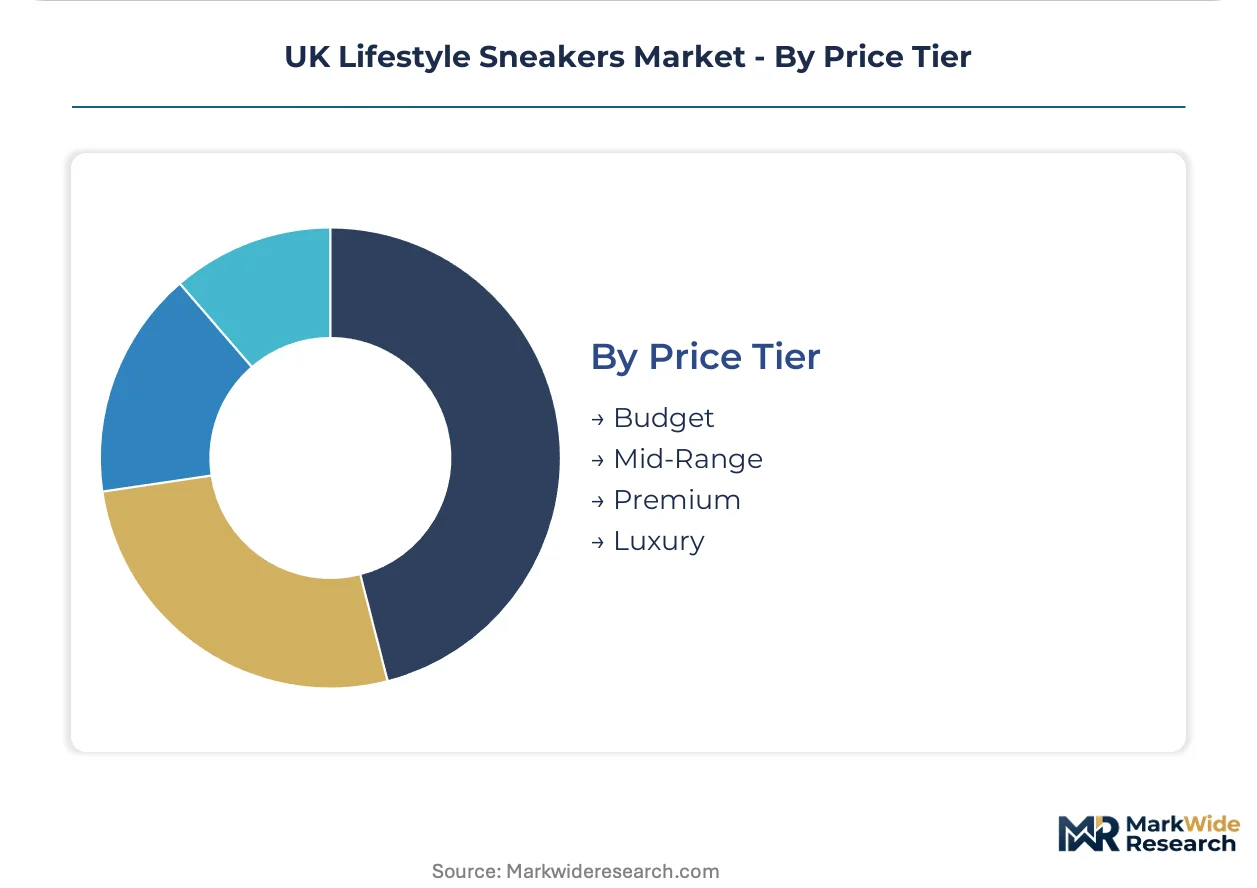
Price Tier:
Pricing stratification reflects the bifurcation between heritage houses with artisanal credibility and agile newcomers competing on trend responsiveness, with compliance costs asymmetrically burdening budget tier competitors.
- Premium:Positioned above mass-market accessibility with provenance signaling, limited production runs, and domestic or near-shored manufacturing. Greater London's disproportionate purchasing power supports direct-to-consumer flagship expansion with higher per-unit profitability than wholesale channels.
- Luxury:Artisanal construction with Northamptonshire heritage or designer collaboration credentials commanding independent retail channel access. Multi-month BSI certification timelines delay seasonal launches for new entrants attempting tier ascension.
- Mid-Range:Volume-competitive positioning balancing material quality with accessibility, increasingly squeezed by circular repair services extending customer lifetime value in adjacent tiers.
- Budget:Synthetic-heavy construction facing compressed margins from petrochemical input volatility and Extended Producer Responsibility cost accounting requirements. Asian supply concentration exposes this tier to shipping cost spikes and customs friction.
Budget anchors the volume base while Premium shows the steepest expansion trajectory as British consumers prioritize provenance and limited-edition collaborations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK's Trading Standards and Extended Producer Responsibility framework anchor regulatory compliance across England, Scotland, Wales, and Northern Ireland. Regional demand clusters concentrate purchasing power and manufacturing heritage in distinct sub-national markets.
London and Southeast England
Gen Z consumers in Greater London accelerate adoption of sustainable and tech-integrated footwear, pulling premium releases into faster inventory turnover cycles. The Plastic Packaging Tax elevates compliance costs for synthetic-heavy supply chains serving this high-value region. London-based innovation hubs pilot algae-derived foam midsoles for limited releases targeting fashion-forward urban demographics.
Midlands
Northamptonshire's artisanal manufacturing heritage commands independent retail channel access and provenance premiums that mass-market competitors cannot replicate. BSI standards for footwear safety and chemical content restrict import flexibility for synthetic-heavy supply chains attempting regional penetration. Domestic leather tanning clusters reduce import dependency while supporting circular repair infrastructure development.
North England
Manchester's fashion-forward consumer base drives slip-on adoption as work-leisure boundaries blur in northern urban centers. Post-Brexit customs alignment uncertainty complicates unified inventory management across Great Britain distribution networks. Secondary market authentication via embedded NFC chips concentrates value in collector segments.
Scotland
Edinburgh and Glasgow urban centers show elevated price sensitivity despite sustainability premium willingness among younger demographics. Extended Producer Responsibility cost accounting requirements compress margins for budget-tier synthetic construction. Scottish textile developers pilot recycled cotton variants in response to circular design investment acceleration.
Northern Ireland
Belfast retail networks face distribution fragmentation from post-Brexit customs alignment uncertainty with EU REACH chemical regulations. Divergence would fragment sourcing strategies across Northern Ireland and Great Britain distribution channels. Local independent retailers leverage artisanal provenance positioning to differentiate against import-dependent competitors.
UK Lifestyle Sneakers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UK lifestyle sneakers market. Heritage houses with Northamptonshire manufacturing roots command premium positioning through artisanal credibility, while agile newcomers compete on trend responsiveness and sustainable material innovation. Three strategic archetypes dominate: global sportswear majors with London innovation hubs, British heritage manufacturers with domestic production heritage, and digitally native challengers leveraging direct-to-consumer channels. Competitive moves concentrate on circular repair service expansion and recycled material R&D partnerships with British textile developers.
Within the heritage manufacturing tier, Grenson Shoes anchors artisanal positioning through Northamptonshire production roots. Among global sportswear majors, Nike, Inc. and Adidas AG occupy positions defined by innovation hub investment and sustainable material partnerships respectively. These three companies exemplify how domestic manufacturing heritage and urban innovation infrastructure create divergent competitive advantages under UK regulatory pressure.
| Leading Market Players |
|---|
| Puma SE |
| Converse |
| Nike, Inc. |
| C. & J. Clark International Limited |
| FILA |
| Adidas AG |
| Vans |
| Grenson Shoes |
| New Balance |
| Others |
Pricing and Supply Chain Analysis
Algae-derived foam midsoles displacing petroleum-based EVA simultaneously pull manufacturing toward British innovation hubs and compress synthetic material premiums across pricing tiers. The UK's Plastic Packaging Tax and Extended Producer Responsibility framework accelerate this substitution by penalizing carbon-intensive inputs while rewarding domestic circular infrastructure.
Pricing Analysis
Greater London commands 35-40% price premiums over Northern England for equivalent provenance-tier sneakers, with Southeast purchasing power concentration enabling direct-to-consumer flagship economics. Three-tier pricing structure across premium, standard, and economy levels stratifies around Northamptonshire artisanal heritage, BSI certification burden, and volume-scale material efficiency. Cost compression in budget-tier synthetic construction intensifies as petrochemical input volatility and Extended Producer Responsibility cost accounting erode margin predictability. Parents in the Southeast exhibit highest price sensitivity despite regional purchasing power concentration, while collector segments in Manchester and London show least sensitivity for limited-edition releases.
Supply Chain Analysis
China, Vietnam, and Bangladesh anchor knit upper and rubber outsole production for volume-tier British brands, with East Asian contract manufacturers exposing importers to shipping cost spikes and customs friction. British textile developers in Scotland and Northamptonshire leather tanning clusters feed premium-tier domestic sourcing alternatives. Supply chain risk centers on single-source vulnerability for algae-derived foam feedstock as London-based innovation labs scale pilot programs. Distribution runs through independent retail channels for heritage houses and direct-to-consumer flagships for digitally native challengers, with wholesale intermediaries losing share in Greater London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK lifestyle sneakers market sits in early-cycle expansion as Gen Z urban adoption of sustainable and tech-integrated footwear outpaces replacement of conventional synthetic construction. Circular repair infrastructure and resale platform integration extend product lifecycles while creating new revenue pools beyond initial purchase.
For Market Incumbents: Shield premium positioning by deepening Northamptonshire manufacturing heritage integration and accelerating BSI certification investment ahead of chemical regulation divergence risk. Consolidate independent retail channel control against digitally native challengers leveraging direct-to-consumer economics. Vertical integration into British textile R&D partnerships creates asymmetric advantage under Extended Producer Responsibility cost accounting.
For New Entrants and Emerging Players: Circular repair services represent the most penetrable white-space where heritage houses under-serve collector segments seeking authenticated refurbishment. Target Manchester's fashion-forward consumer base with slip-on silhouettes optimized for work-leisure boundary blur. A modular construction go-to-market angle simplifies component separation for end-of-life recovery compliance while differentiating against synthetic-heavy import competitors.
For Investors and Strategic Acquirers: Post-Brexit REACH alignment divergence reshapes the acquisition landscape by fragmenting sourcing strategies across Northern Ireland and Great Britain distribution networks. Long-term viability favors vertically integrated specialists with domestic material partnerships and circular infrastructure. The signal to watch is customs alignment policy shifts affecting unified inventory management economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Material R&D Partnership | Collaboration with British textile developers creates differentiated positioning against import-dependent competitors under UK Plastic Packaging Tax. |
| Circular Repair Service Launch | Extended Producer Responsibility incentives capture resale velocity and extend customer lifetime value in premium collector segments. |
| Direct-to-Consumer Flagship Expansion | Greater London's purchasing power concentration supports higher per-unit profitability than wholesale channel dependence. |
| Algae-Derived Foam Scale-Up | London innovation hub pilot programs compress synthetic demand while creating supply bottleneck risk for cultivated feedstock. |
| BSI Certification Pre-Investment | Multi-month compliance timelines for chemical content standards delay seasonal launches for competitors lacking advance preparation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with footwear brand managers, category buyers at independent retailers, Northamptonshire manufacturing cluster operators, and British textile R&D directors. Secondary validation drew from UK Trading Standards filings, British Footwear Association industry reports, customs import records for rubber and synthetic materials, and BSI certification documentation databases. Bottom-up segment sizing triangulated against top-down market value reconstructions across material, price tier, and regional dimensions.
The projection horizon spans the full analysis window with segmentation modeling across product type, end user demographic, shoe material composition, and price tier positioning. CAGRs were derived from trend extrapolation of adoption rates for sustainable and tech-integrated silhouettes, adjusted for regulatory compliance cost trajectories and petrochemical input volatility assumptions. Forecast inputs incorporated Gen Z urban demand concentration patterns, Extended Producer Responsibility implementation phases, and post-Brexit customs alignment scenarios.
Underlying assumptions cover sustained urban disposable income growth in Greater London and Manchester, with deviation risk concentrated in petrochemical price spikes and REACH regulatory divergence. Forecasts reflect these documented conditions with acknowledged sensitivity to material substitution velocity and circular infrastructure buildout pace. Recalibration cycles align with material shifts in UK Plastic Packaging Tax enforcement and Extended Producer Responsibility framework evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Tennis Shoes Market
Footwear
Formal Shoes Market
Footwear
Global Espadrille Flats Market
Footwear
Snow Boots Market
Footwear
Cyber-Shoes Market
Footwear
Protective Footwear Market
Footwear
Western Boots Market
Footwear
Light Up Shoes Market
Footwear
Barefoot Shoes Market
Footwear
Middle East and Africa Athletic Footwear Market
Footwear
Second Hand Designer Shoes Market
Footwear
Gypsy Jazz Shoes Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Women's Sneakers Market
Footwear
Dance Shoes Market
Footwear
Europe Athletic Footwear Market