
 Sports Shoes Market | 2026-2036
Sports Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Shoes Market Outlook
Capital-intensity divergence between automated manufacturing platforms and labor-dependent assembly is collapsing as digital tooling costs fall. Nike leverages robotic knitting and 3D-printed midsoles to compress prototype-to-production cycles. Adidas anchors its European supply base with Speedfactory-adjacent partnerships while competing in North American direct-to-consumer channels. New Balance sustains domestic manufacturing in Massachusetts and Maine as a brand-differentiation asset.
Sports shoes are engineered footwear systems combining ethylene-vinyl acetate (EVA) or thermoplastic polyurethane (TPU) midsole foams with engineered mesh uppers and carbon-fiber or nylon plate inserts, designed to attenuate impact forces and enhance propulsive efficiency during athletic movement. Running and basketball categories concentrate premium innovation investment, with carbon-plated racing flats and position-specific court shoes commanding the highest margin pools. Mesh and synthetic materials displace leather across performance segments due to weight reduction and breathability engineering, while specialty shops and online channels capture the fastest-growing share of athlete and enthusiast transactions.
China's SAMR enforces GB standards for footwear physical safety and chemical content, while the EU's REACH regulation and F-Gas Framework constrain solvent-based adhesives and synthetic foam blowing agents used in midsole production. India's BIS certification requirements for imported footwear create compliance thresholds that filter market access for smaller exporters. Stakeholders must monitor regulatory convergence on recycled content mandates and per- and polyfluoroalkyl substance (PFAS) restrictions that will reshape material specifications and supplier qualification protocols.
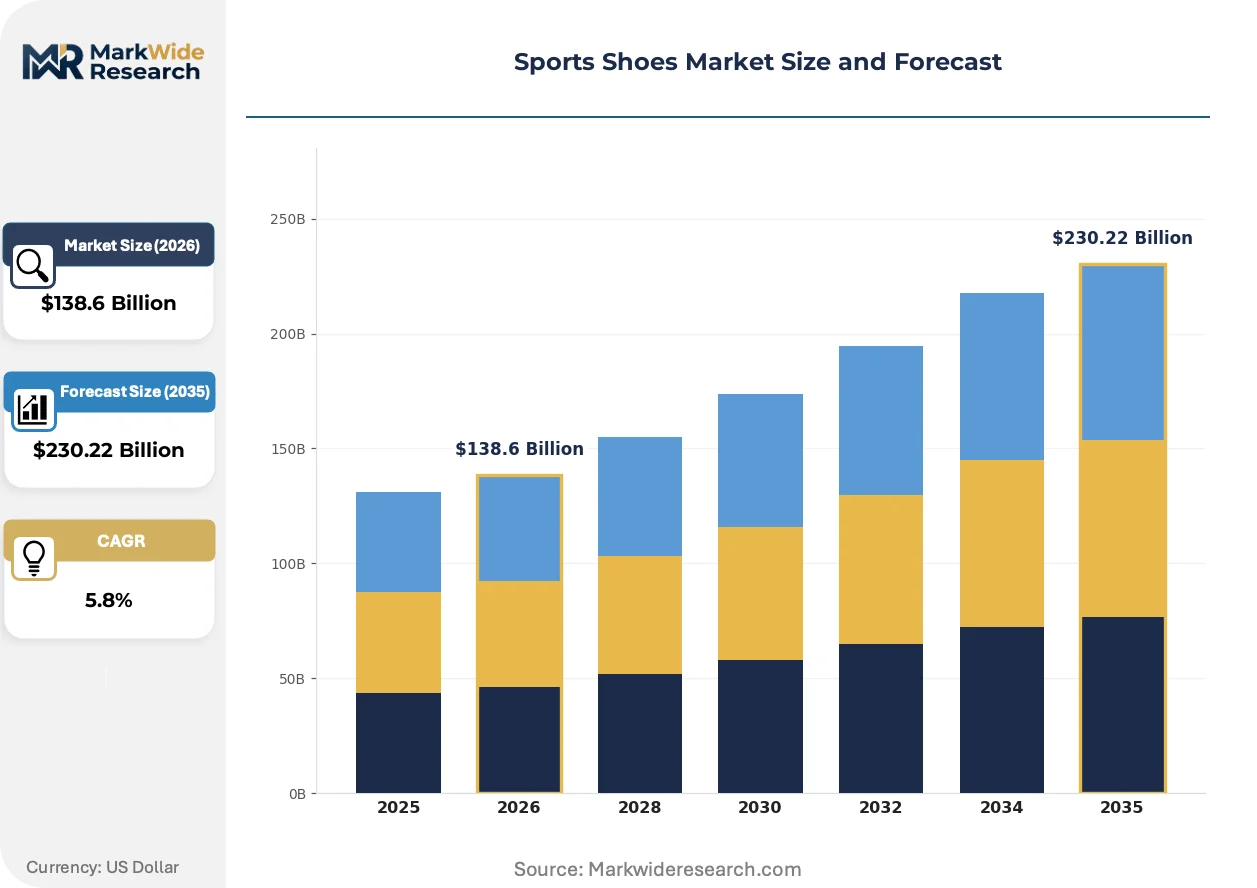
Market Dynamics
Carbon-plate insertion and robotic knitting are compressing prototype cycles while China's GB standards and India's PLI scheme redraw where manufacturing capital lands. These forces are restructuring competitive advantage around automation compliance and geographic incentive capture.
Growth Catalysts
- Carbon-plate engineering:Marathon runners and amateur enthusiasts in China and India drive demand for propulsive-efficiency footwear, expanding the performance premium segment.
- PLI scheme for textiles and leather:India's production-linked incentive attracts manufacturing investment from global brands seeking cost-competitive assembly bases outside China.
- Recycled material mandates:China's GB standards for footwear safety and recycled content reshape supplier qualification protocols across the Asia-Pacific supply base.
Market Restraints
- Petrochemical input volatility:Ethylene-vinyl acetate and thermoplastic polyurethane foam prices fluctuate with crude oil derivatives, compressing midsole margins unpredictably.
- Single-region supply concentration:China's dominance in engineered mesh weaving and carbon-fiber plate fabrication creates vulnerability to SAMR enforcement actions and logistics disruption.
- REACH solvent constraints:The EU's restriction on solvent-based adhesives forces reformulation of bonding processes, extending qualification timelines for European market entry.
Strategic Opportunities
- Underpenetrated amateur running segment:India's secondary cities and Southeast Asian urban centers show rising participation in recreational marathon events, creating white space for mid-tier performance positioning.
- Direct-to-consumer channel expansion:North American and European brands bypass wholesale intermediaries through app-based customization and subscription replenishment models.
- Dual carbon goal alignment:China's MEE enforcement of carbon intensity targets rewards suppliers with verified recycled content streams and renewable energy procurement.
Industry Challenges
- Automation engineering talent scarcity:Robotic knitting and 3D-printed midsole production require mechatronics specialists that contract manufacturers struggle to recruit at scale.
- Legacy ERP integration friction:Digital tooling platforms for automated size-run customization clash with established order-management systems, delaying real-time inventory visibility.
- PFAS testing backlog:Laboratory capacity constraints for per- and polyfluoroalkyl substance detection extend certification timelines for water-resistant upper treatments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Shoes Market |
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $230.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Running, Training, Basketball, Football Material: Leather, Synthetic, Mesh, Rubber Distribution Channel: Online, Retail Stores, Specialty Shops, Discount Outlets End User: Men, Women, Kids, Athletes |
| Companies Covered | Nike, Adidas, New Balance, ASICS Corporation, Puma, Skechers USA, On Holding, Under Armour, Saucony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Shoes Market Strategic Shifts
Digital manufacturing and regulatory chemistry constraints are rewriting material specifications and production geography simultaneously. Three developments are compressing competitive timelines.
Embedded sensor arrays for gait analysis are miniaturizing from laboratory equipment to consumer-accessible insole formats. Amateur runners and physical therapy clinics adopt pressure-mapping footwear to quantify pronation and impact asymmetry. This capability is miniaturizing the performance feedback loop from annual biomechanical assessments to real-time training adjustments, compressing the upgrade cycle for serious enthusiasts.
REACH and the EU F-Gas Framework constrain hydrofluorocarbon blowing agents in thermoplastic polyurethane midsole expansion, forcing suppliers to adopt water-based or physical foaming alternatives. German and Italian compounders lead reformulation efforts to maintain energy-return metrics under stricter chemical thresholds. Racing-flat categories face the steepest compliance costs due to density and rebound specifications.
Specialty running shops consolidate athlete transaction share against general sporting goods retailers through gait-analysis services and community event programming. Digital-native entrants capture enthusiast attention via Strava-integrated challenge campaigns and limited-drop collaborations. This channel rotation is most visible in Germany's Rhine-Ruhr corridor and Australia's Melbourne-Sydney corridor, where run-club density supports premium positioning independent of mass retail presence.
Sports Shoes Market Segmentation
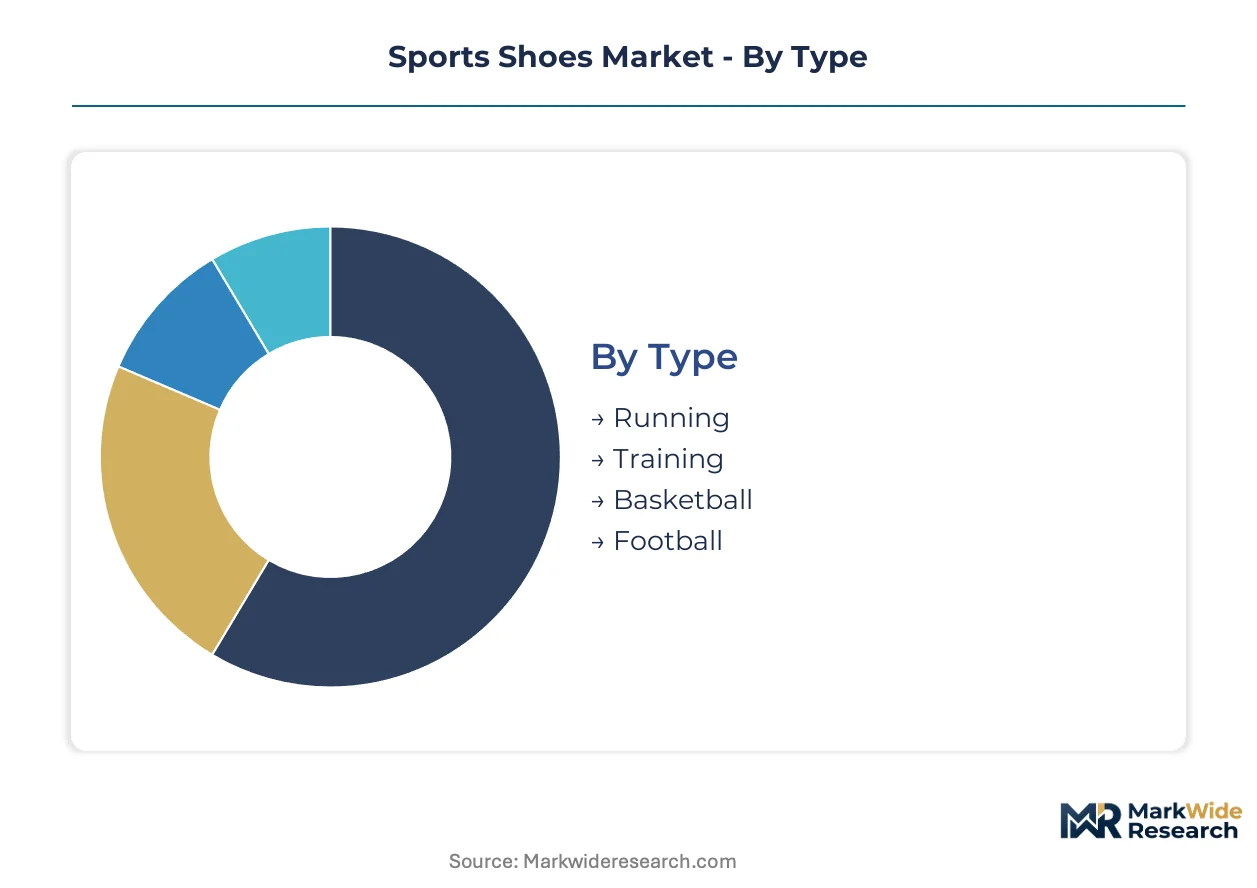
Sports shoes segment along performance specifications, material engineering, channel economics, and user biomechanics. Margin concentration varies sharply across these dimensions, with carbon-plated racing flats and direct-to-consumer channels capturing disproportionate value pools relative to volume share.
Type:
Running and basketball concentrate premium innovation investment and margin extraction, while training and football categories compete on volume scale and team-sport procurement contracts.
- Running:Carbon-plated racing flats and energy-return foams command the highest unit economics in the performance segment. Marathon participation in China and India drives amateur upgrade cycles toward propulsive-efficiency footwear with nylon or carbon-fiber plate inserts.
- Basketball:Position-specific court shoes with herringbone traction patterns and ankle-stabilizing collar heights address distinct biomechanical loading profiles. NBA athlete endorsements and collegiate program sponsorships sustain wholesale premium pricing in North American markets.
- Training:Cross-training hybrids prioritize lateral stability and multi-surface durability over category-specific optimization. Gym-based functional fitness adoption in European urban centers sustains mid-tier volume.
- Football:Stud configuration and upper touch sensitivity dominate product differentiation for pitch conditions. Club-licensed replica editions drive retail traffic through seasonal kit cycles.
Running holds installed capacity in automated knitting and 3D-printed midsole tooling. Basketball is rotating up the share rankings through direct-to-consumer drops and limited collaborations.
Material:
Cost tier and performance tier diverge sharply here, with engineered synthetics displacing leather in premium positioning while rubber compounds anchor entry-level durability specifications.
- Synthetic:Thermoplastic polyurethane films and engineered overlays enable seamless construction and localized support mapping. REACH solvent constraints and F-Gas Framework regulations force reformulation of synthetic foam blowing agents in European supply chains.
- Mesh:Knitted engineered uppers with zoned breathability and stretch recovery dominate weight-sensitive categories. China's GB standards for recycled content mandate are reshaping virgin polyester sourcing for mesh weavers supplying domestic brands.
- Leather:Full-grain and synthetic leather alternatives persist in heritage lifestyle positioning and indoor court applications. Tanning chemistry compliance costs filter smaller suppliers from premium contract manufacturing.
- Rubber:Carbon-black reinforced outsole compounds deliver abrasion resistance across price tiers. Natural rubber price volatility and synthetic alternatives create input cost pressure for high-wear training categories.
Synthetic materials hold installed capacity in automated cutting and bonding workflows. Mesh is climbing the fastest in share rankings as weight reduction engineering penetrates mid-tier price points.
Distribution Channel:
Channel economics determine margin capture efficiency, with specialty retail and digital direct-to-consumer models extracting superior unit economics against wholesale-dependent alternatives.
- Specialty Shops:Gait-analysis services and community event programming consolidate enthusiast transaction share against general sporting goods. Melbourne-Sydney and Rhine-Ruhr corridor run-club density supports premium positioning independent of mass retail presence.
- Online:App-based customization, subscription replenishment, and Strava-integrated challenge campaigns capture digitally native athlete engagement. Nike and Adidas deploy proprietary sizing algorithms to reduce return rates in direct-to-consumer expansion.
- Retail Stores:Mass sporting goods chains depend on brand marketing co-investment and seasonal floor set rotations. Inventory carrying costs and markdown risk compress net margins for wholesale-dependent brands.
- Discount Outlets:Off-price channels clear excess inventory from prior season collections without damaging full-price positioning. Factory outlet geography in secondary US and European markets targets value-conscious family purchasers.
Specialty shops hold installed capacity in certified fitting expertise and local athlete community development. Online is gaining share fastest through personalization technology and inventory visibility advantages.
End User:
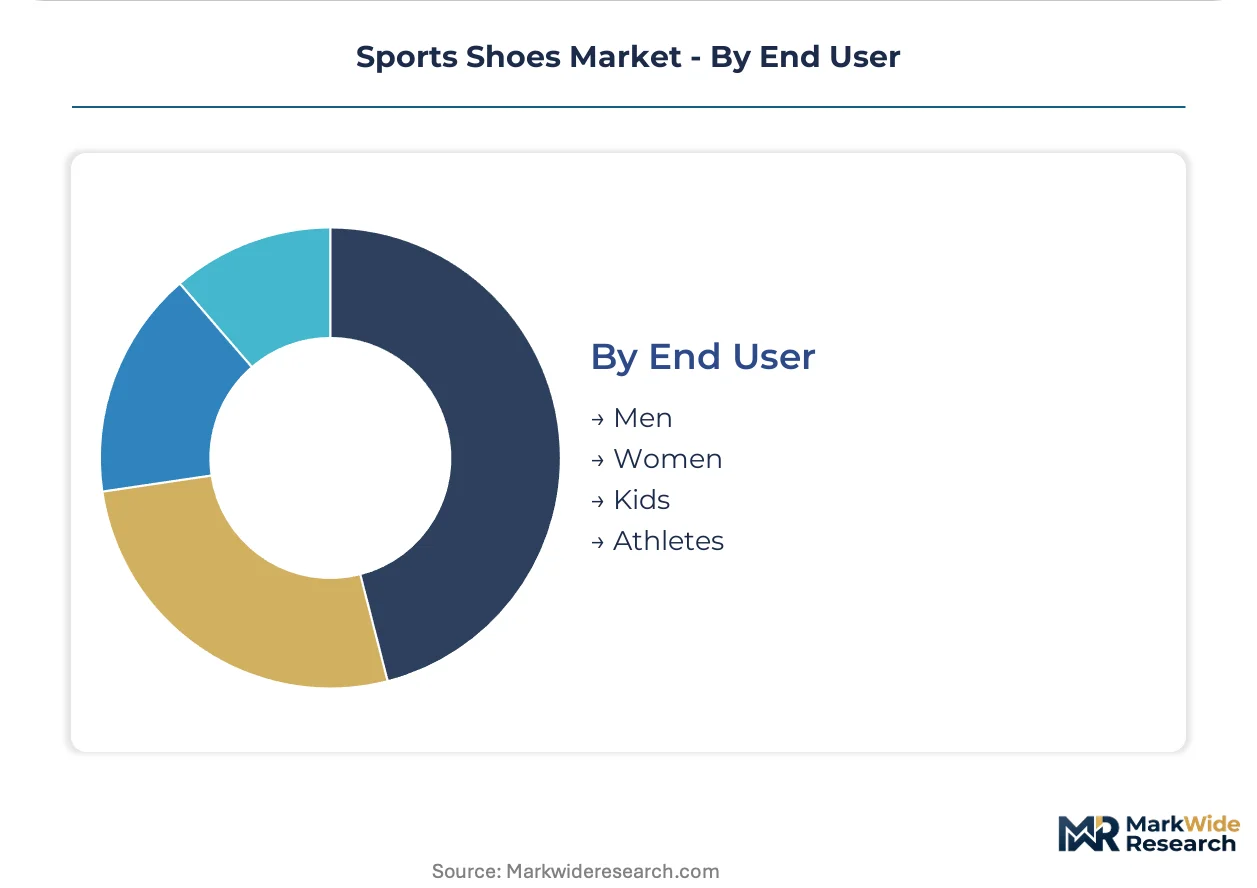
Demographic segmentation maps to biomechanical variation, participation frequency, and replacement cycle velocity, with amateur adult runners and youth athletes presenting distinct value extraction profiles.
- Men:Higher average selling prices in performance running and basketball reflect sizing scale economies and technology penetration. Amateur marathon participation in Asia-Pacific secondary cities drives replacement frequency among recreational male runners.
- Women:Narrower heel-to-toe lasts and adjusted Q-angle geometry require distinct last engineering and mold investment. Women's-specific product development accelerates in trail running and cross-training categories.
- Kids:Growth-accommodating fit systems and durable construction prioritize value positioning over performance engineering. Back-to-school seasonal concentration creates inventory planning challenges for retail partners.
- Athletes:Elite and professional endorsement contracts subsidize product development amortization across commercial ranges. Collegiate and semi-professional procurement operates on team contract pricing with customized colorway minimums.
Men's segments hold installed capacity in performance technology amortization and sizing standardization. Women's categories are expanding most quickly as brand product development resources rebalance toward underpenetrated fitting specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amateur runners in China and India absorb premium carbon-plate pricing with minimal elasticity, while Southeast Asian secondary markets and Latin American urban centers exhibit sharper volume sensitivity to mid-tier positioning. Europe's regulatory compliance costs filter price-competitive entrants from its performance segment.
China
Marathon participation in Beijing, Shanghai, and Chengdu sustains demand for propulsive-efficiency footwear with carbon-fiber plate inserts. SAMR enforces GB standards for footwear physical safety and recycled content mandates that reshape supplier qualification protocols. The Yangtze River Delta cluster around Suzhou and Taicang concentrates automated knitting capacity for engineered mesh uppers serving domestic brands.
United States
Direct-to-consumer channel expansion and subscription replenishment models capture enthusiast replacement cycles in Boston, New York, and Austin running communities. No federal footwear-specific regulator exists; California's Proposition 65 drives chemical disclosure requirements for imported products. The Pacific Northwest corridor between Portland and Seattle anchors specialty retail density with gait-analysis service integration.
Germany
Rhine-Ruhr corridor run-club density supports premium positioning independent of mass retail presence through specialty shop community programming. ECHA's REACH regulation and the EU F-Gas Framework constrain solvent-based adhesives and hydrofluorocarbon blowing agents in midsole production. Bavaria's footwear manufacturing base around Herzogenaurach maintains compounder leadership in thermoplastic polyurethane reformulation.
India
Secondary cities including Pune, Hyderabad, and Ahmedabad show rising participation in recreational marathon events, creating white space for mid-tier performance positioning. The PLI scheme for textiles and leather attracts manufacturing investment from global brands seeking cost-competitive assembly bases. Tamil Nadu's leather and footwear cluster around Ambur and Vaniyambadi expands capacity under incentive-linked capital deployment.
Japan
Master runners and trail enthusiasts in Tokyo, Osaka, and Fukuoka sustain replacement frequency for durability-engineered training categories. METI's industrial standards and JIS certification requirements maintain quality thresholds for domestic distribution. The Kobe-Osaka corridor retains specialty manufacturing expertise in custom last engineering for narrow-foot anatomical specifications.
Sports Shoes Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the sports shoes market structure. The upper tier commands disproportionate margin capture through proprietary automation platforms and direct-to-consumer channel ownership. Mid-tier specialists compete on regional manufacturing incentive access and category-specific biomechanical engineering. Capacity expansion in India's PLI zones and strategic partnerships for robotic knitting deployment constitute the dominant competitive moves reshaping manufacturing geography.
Within the integrated leader archetype, Nike and Adidas occupy positions defined by automation scale and multi-channel presence across North American and European markets. ASICS Corporation exemplifies the specialist tier through its concentration in running-specific biomechanical engineering and Japanese manufacturing heritage. New Balance represents geographic differentiation strategy through sustained domestic production in Massachusetts and Maine as brand-differentiation asset.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| New Balance |
| ASICS Corporation |
| Puma |
| Skechers USA |
| On Holding |
| Under Armour |
| Saucony |
| Others |
Value Chain & Pricing Dynamics
Carbon-fiber plate insertion displacing nylon alternatives in marathon racing flats simultaneously redraws supplier geography toward China's Yangtze River Delta cluster and compresses margin pools for mid-tier compounders lacking automated knitting integration. This substitution dynamic concentrates pricing power with vertically integrated brands while fragmenting component-level profit capture.
Pricing Analysis
After-sales replenishment through subscription-based insole replacement and app-integrated gait-tracking services drives lifetime value extraction beyond the initial footwear transaction. Three-tier pricing structure across premium carbon-plated racing flats, standard energy-foam trainers, and economy rubber-outsole entry levels segments buyer willingness-to-pay by marathon participation frequency. Cost compression in midsole foam tiers stems from petrochemical derivative volatility, while amateur runners in India and Southeast Asian secondary cities exhibit highest price elasticity. Elite athletes and Strava-integrated enthusiasts demonstrate lowest sensitivity, absorbing premium positioning for propulsive-efficiency engineering.
Supply Chain Analysis
Inventory cycles for engineered mesh uppers stretch 8-12 weeks against compressed 3-5 week lead times for 3D-printed midsole components, creating mismatched working capital demands across tiered supplier bases. Manufacturing gravity centers on China for carbon-fiber plate fabrication and automated knitting, Vietnam for assembly scale, and India for leather tanning under PLI incentive deployment. Raw material flows draw from Saudi ethylene derivatives for EVA foam, German TPU compounders for energy-return formulations, and Japanese carbon-fiber weavers for plate inserts. Single-region concentration in Chinese engineered mesh production creates tariff-exposure vulnerability for brands diversifying toward Indian assembly. Distribution runs through direct-to-consumer apps for enthusiast segments and specialty retail for gait-analysis-dependent fitting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as embedded sensor arrays and Strava-integrated challenge campaigns transform footwear from transactional products into data-capture ecosystems with recurring engagement hooks.
For Market Incumbents: Compound automation scale advantages through robotic knitting capacity expansion in Suzhou and Taicang clusters while securing exclusive carbon-fiber plate supply agreements with Japanese weavers. Defend against digital-native entrants by integrating proprietary gait-analysis algorithms into direct-to-consumer apps, creating switching costs through training-data accumulation. Prioritize REACH-compliant TPU reformulation investment to maintain European market access as F-Gas Framework constraints tighten. For New Entrants and Emerging Players: Anchor in India's secondary city marathon participation growth—Pune, Hyderabad, Ahmedabad—where mid-tier performance positioning faces incumbent whitespace. Target trail running and women's-specific Q-angle geometry segments where product development resources remain underweight against demand. Deploy Strava-integrated community challenge campaigns as low-cost customer acquisition, bypassing wholesale margin compression. For Investors and Strategic Acquirers: The market sits at an automation-investment phase that favors compounders with verified recycled content streams and renewable energy procurement under China's MEE enforcement. Long-term viability over the next decade hinges on supplier qualification protocol mastery rather than brand equity alone. Acquisition targets should demonstrate robotic knitting integration or 3D-printed midsole tooling deployment. The signal to watch is laboratory capacity expansion for PFAS detection, indicating regulatory compliance infrastructure depth.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Knitting Capacity Expansion | Automated upper production in Yangtze River Delta clusters compresses prototype-to-production cycles for domestic Chinese brands. |
| Direct-to-Consumer App Launch | Proprietary sizing algorithms reduce return rates while capturing Strava-integrated athlete engagement independent of retail intermediaries. |
| Recycled Content Certification | Verified polyester streams satisfy China's GB standards for footwear safety while qualifying suppliers for MEE carbon intensity incentives. |
| Specialty Retail Partnership | Gait-analysis service integration in Rhine-Ruhr and Melbourne-Sydney corridors consolidates enthusiast transaction share against mass sporting goods. |
| TPU Reformulation Investment | Water-based foaming alternatives maintain energy-return metrics under REACH and EU F-Gas Framework constraints for European market access. |
Study Parameters
A spread of perspectives from brand product development executives, contract manufacturing procurement leads, specialty retail category managers, and amateur marathon participants converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC footwear segment filings, and SAMR GB standard enforcement records. Bottom-up sizing of carbon-plate and mesh knitting capacity triangulated against top-down marathon participation and replacement cycle velocity estimates across China, India, and Southeast Asian urban centers.
Segmentation dimensions modeled span performance category, material engineering tier, distribution channel economics, and end-user biomechanical profile across the projection horizon. CAGRs derived from regression analysis of historical footwear shipment volumes against macroeconomic indicators and regulatory enforcement intensity. Industry-specific forecast inputs incorporated PLI scheme capital deployment tracking in Tamil Nadu and MEE carbon intensity target compliance verification for recycled content mandates.
Material uncertainties—petrochemical price volatility, SAMR enforcement action timing, PFAS testing laboratory capacity constraints—sit outside the modeled envelope and could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Second Hand Designer Shoes Market
Footwear
Cyber-Shoes Market
Footwear
North America Footwear Market
Footwear
Tactical Footwear Market
Footwear
PVC Footwear Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Tennis Shoes Market
Footwear
Sandals Market
Footwear
Athletic Footwear Market
Footwear
Footwear Testing Services Market
Footwear
Luxury Footwear Market
Footwear
Refurbished Running Shoes Market
Footwear
Self-Lacing Shoes Market
Footwear
Barefoot Shoes Market
Footwear
Leather Sneakers Market
Footwear
Dance Shoes Market