
 Platform Boots Market | 2026-2036
Platform Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Platform Boots Market Analytics
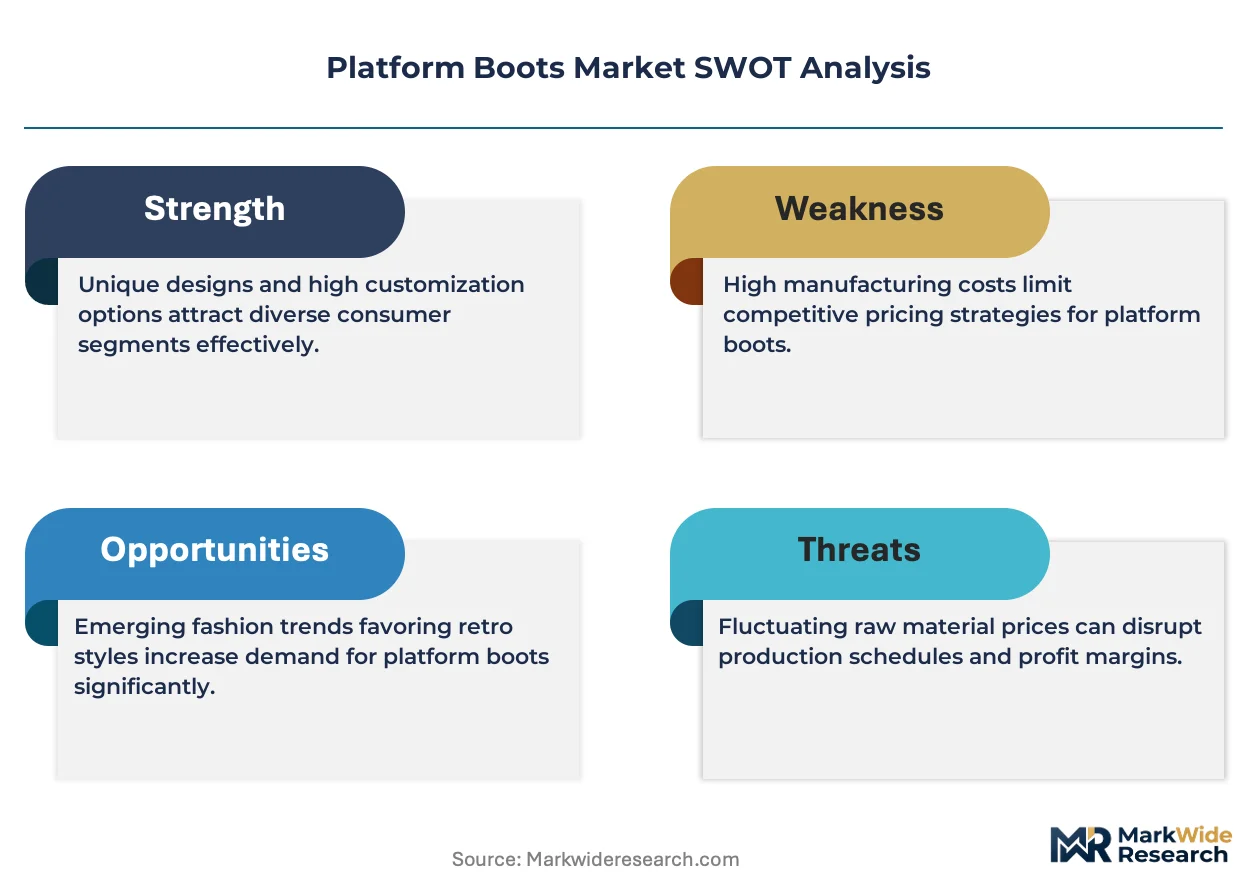
The premium-commodity split in platform boots is restructuring around material provenance and construction depth rather than brand alone. Dr. Martens plc leverages its British manufacturing heritage to command higher price points in leather-focused collections. Steve Madden, Ltd. competes through rapid style turnover and synthetic material flexibility across mass-market channels. ASOS plc anchors its position through data-driven trend response and direct-to-consumer reach in digital-native demographics.
Platform boots are elevated footwear with thick, layered soles typically constructed from rubber, EVA foam, or polyurethane, designed to add height while distributing weight across a broad base for stability. The manufacturing process involves molded sole attachment to leather or synthetic uppers through cemented or welted construction, serving fashion-forward consumers seeking statement footwear with ergonomic load distribution. Leather platform boots sustain premium positioning due to durability perception and aging aesthetics that synthetic alternatives struggle to replicate. Fashion platform boots lead volume growth as social media-driven trend cycles compress refresh rates among teen and young adult buyers. Online Retail captures the fastest-growing distribution share as virtual try-on tools and influencer partnerships reduce purchase friction for fit-sensitive elevated footwear.
REACH in Europe restricts phthalates and heavy metals in synthetic sole compounds, pushing manufacturers toward bio-based polyurethane alternatives or natural rubber sourcing. The US Consumer Product Safety Commission monitors heel stability and slip resistance through voluntary ASTM standards that major retailers increasingly mandate for shelf access. California's Proposition 65 labeling requirements add compliance costs for brands selling leather-tanned products containing trace chromium compounds. Stakeholders must monitor how chemical disclosure mandates evolve across jurisdictions and whether material transparency becomes a purchase trigger rather than a cost center.
Market Dynamics
REACH compliance in Europe is modularizing supply chains as manufacturers fragment production between bio-based polyurethane R&D hubs and legacy synthetic sole facilities to maintain EU market access while serving cost-sensitive channels elsewhere.
Growth Catalysts
- Teen streetwear adoption:Urban coastal consumers in the United States drive volume through social media amplification of platform boot aesthetics in music and skate culture.
- REACH chemical restrictions:ECHA enforcement against phthalates and heavy metals accelerates investment in natural rubber sourcing from Southeast Asian plantations.
- Virtual try-on technology:AR fitting tools reduce return rates for fit-sensitive elevated footwear in digital-native demographics.
Market Restraints
- Petrochemical input volatility:Polyurethane and EVA foam prices fluctuate with crude oil derivatives, compressing margins on synthetic-soled mass-market lines.
- Chrome tanning disclosure costs:California Proposition 65 labeling mandates add per-unit compliance expenses for leather platform boots containing trace chromium compounds.
- Heel stability certification friction:ASTM slip resistance standards that major US retailers now mandate create barrier-to-entry for smaller manufacturers lacking testing infrastructure.
Strategic Opportunities
- Underpenetrated Japanese market:METI sustainability guidelines favoring durable goods create opening for British-manufactured heritage leather collections with proven longevity metrics.
- Circular material mandates:EU Green Deal textile strategy incentives reward brands developing take-back programs for end-of-life platform boot recycling.
- Live commerce integration:Influencer-hosted streaming sales on Chinese platforms compress trend-to-purchase cycles for statement footwear.
Industry Challenges
- Welted construction skill scarcity:British and Italian manufacturing regions face aging artisan populations with limited apprenticeship pipeline replacement.
- Multi-jurisdiction chemical tracking:Brands must maintain parallel compliance documentation for ECHA REACH, US CPSC voluntary standards, and California Prop 65 with conflicting disclosure thresholds.
- Legacy ERP integration:Direct-to-consumer data systems require costly retrofitting for heritage manufacturers operating on wholesale-centric software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platform Boots Market |
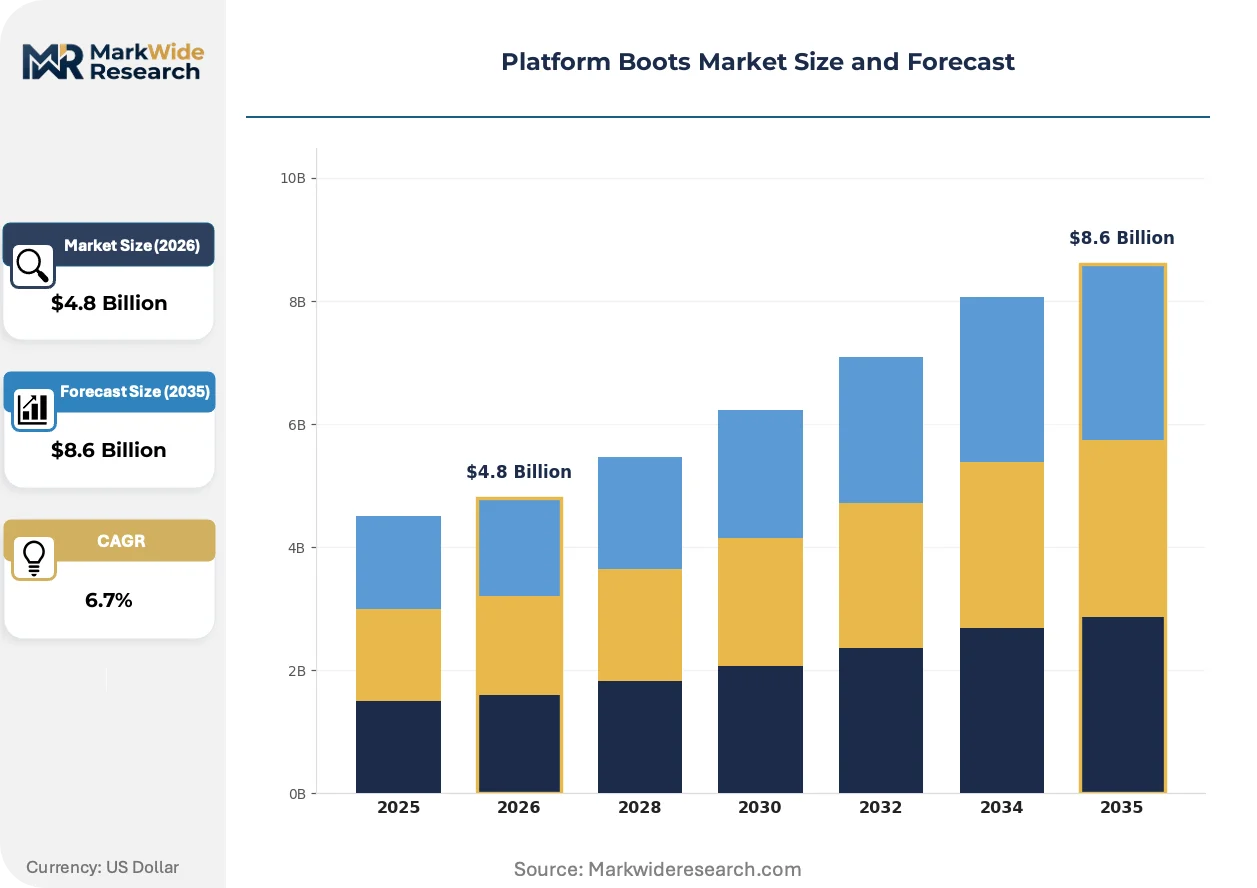
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casual, Formal, Sports, Fashion Material: Leather, Synthetic, Suede, Canvas End User: Women, Men, Kids, Teens Distribution Channel: Online Retail, Specialty Stores, Department Stores, Discount Outlets |
| Companies Covered | Dr. Martens plc, Steve Madden, Ltd., ASOS plc, Gucci, Timberland LLC, Christian Louboutin, Stuart Weitzman, The Frye Company, Wolverine Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platform Boots Market Evolving Landscape
Bio-based material science and digital fitting infrastructure are compressing traditional seasonality in platform boot development. Manufacturers now balance heritage construction credibility against synthetic material agility.
Modular sole systems using interchangeable TPU and cork layers are modularizing repair economics. Premium buyers in Germany and the Netherlands adopt component-replacement models that extend product lifespan. This architecture shifts competitive advantage toward after-sales service networks rather than initial manufacturing scale.
ECHA REACH Annex XVII restrictions on persistent organic pollutants in rubber compounding force reformulation of traditional vulcanization processes. Italian tanneries now pre-certify leather uppers for dual EU-US market entry. Smaller brands lacking in-house compliance teams outsource chemical documentation to specialized third-party laboratories.
Social commerce algorithms compress trend identification-to-production timelines from months to weeks. Teen buyers in Los Angeles and London discover platform boot styles through short-form video before traditional retail buyers place seasonal orders. Fast-response manufacturers capture margin by bypassing wholesale forecasting entirely.
Platform Boots Market Segmentation
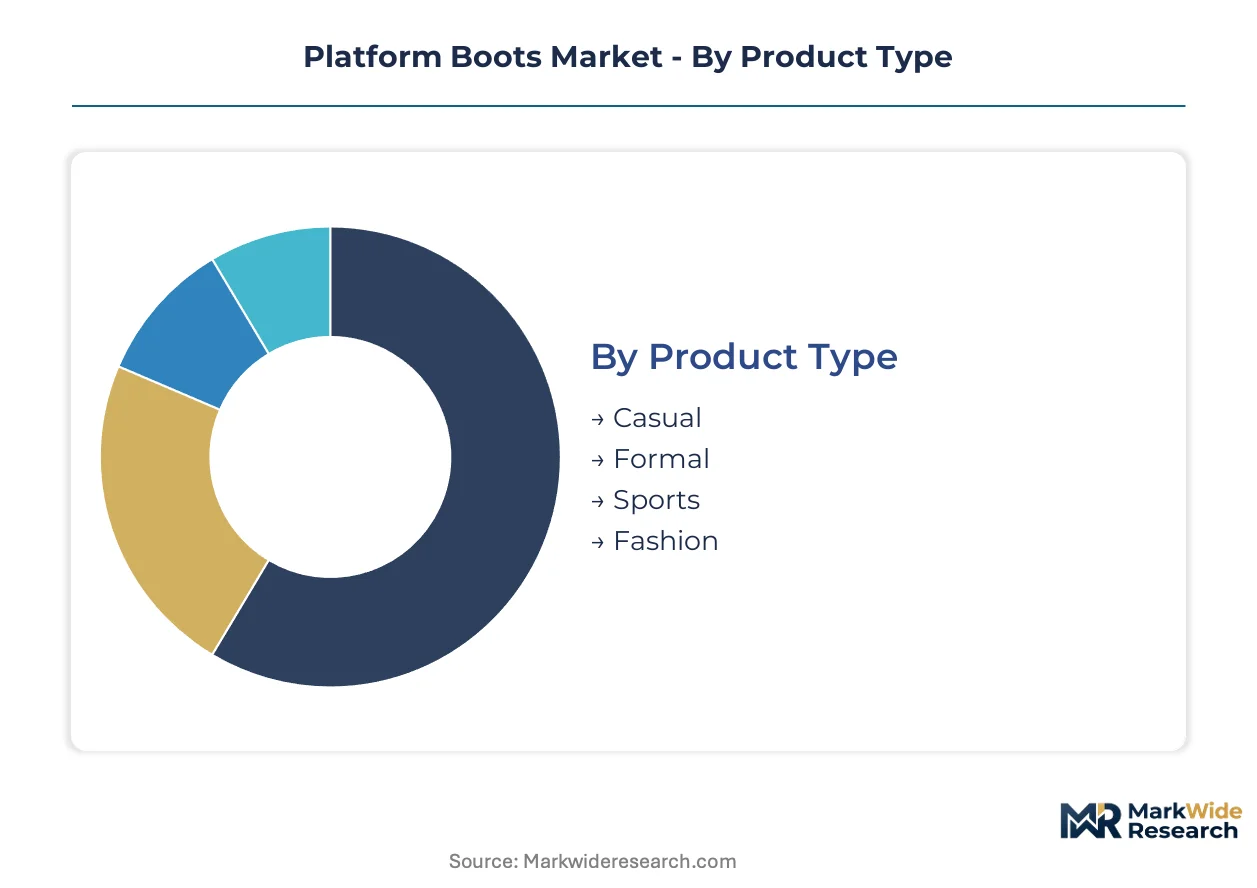
Platform boots demand fragments across four distinct dimensions, each commanding different margin structures and compliance obligations. Material provenance and distribution channel access determine competitive positioning more than brand heritage alone in this market.
Product Type:
Upgrade cycles vary dramatically across use-case categories, with fashion-forward buyers replacing statement pieces faster than functional collections.
- Fashion:Statement silhouettes with exaggerated sole stacks and experimental finishes dominate social media-driven purchase cycles. Teen buyers in Los Angeles and London refresh these styles every 8-12 weeks as short-form video platforms accelerate trend obsolescence.
- Casual:Everyday wearable designs with moderate 4-6cm sole elevation balance comfort aesthetics with walkability. Urban coastal consumers in the United States concentrate demand here, prioritizing versatility across work and social contexts.
- Formal:Refined leather constructions with subtle platform elevation for professional environments.
- Sports:Performance-oriented designs with athletic sole technology and enhanced grip patterns.
Fashion sits at the top of the volume ranking, with Casual climbing the fastest as workplace dress codes relax.
Material:
Cost tier alignment separates premium positioning from mass-market penetration, with chemical compliance costs widening the gap.
- Leather:Full-grain and corrected-grain hides with chrome or vegetable tanning deliver aging patina and structural longevity. British manufacturing heritage commands price premiums, though California Proposition 65 disclosure mandates add per-unit compliance burden.
- Synthetic:Polyurethane and bio-based alternatives offer color flexibility and water resistance at lower entry points. ECHA REACH Annex XVII restrictions on phthalates force reformulation investments that smaller manufacturers struggle to absorb.
- Suede:Napped leather surfaces requiring protective treatments and specialized cleaning protocols.
- Canvas:Woven cotton uppers with rubber foxing for lightweight summer variants.
Leather dominates absolute revenue contribution, while Synthetic gains share fastest as bio-based polyurethane R&D matures.
End User:
Customer type determines sizing complexity and marketing channel allocation, with fit sensitivity varying across demographic groups.
- Teens:Trend-responsive buyers with high social media exposure and limited brand loyalty. Music and skate culture adoption in United States urban centers drives volume, with peer influence outweighing durability considerations.
- Women:The largest addressable base spanning fashion, casual, and formal use cases. German and Dutch buyers in this segment increasingly favor modular sole systems with component-replacement options.
- Men:Growing acceptance of elevated footwear in streetwear contexts, though average price points trail women's collections.
- Kids:Size-rapid turnover category with safety certification requirements for heel stability.
Women anchor current volume leadership, with Teens expanding most quickly as social commerce penetration deepens.
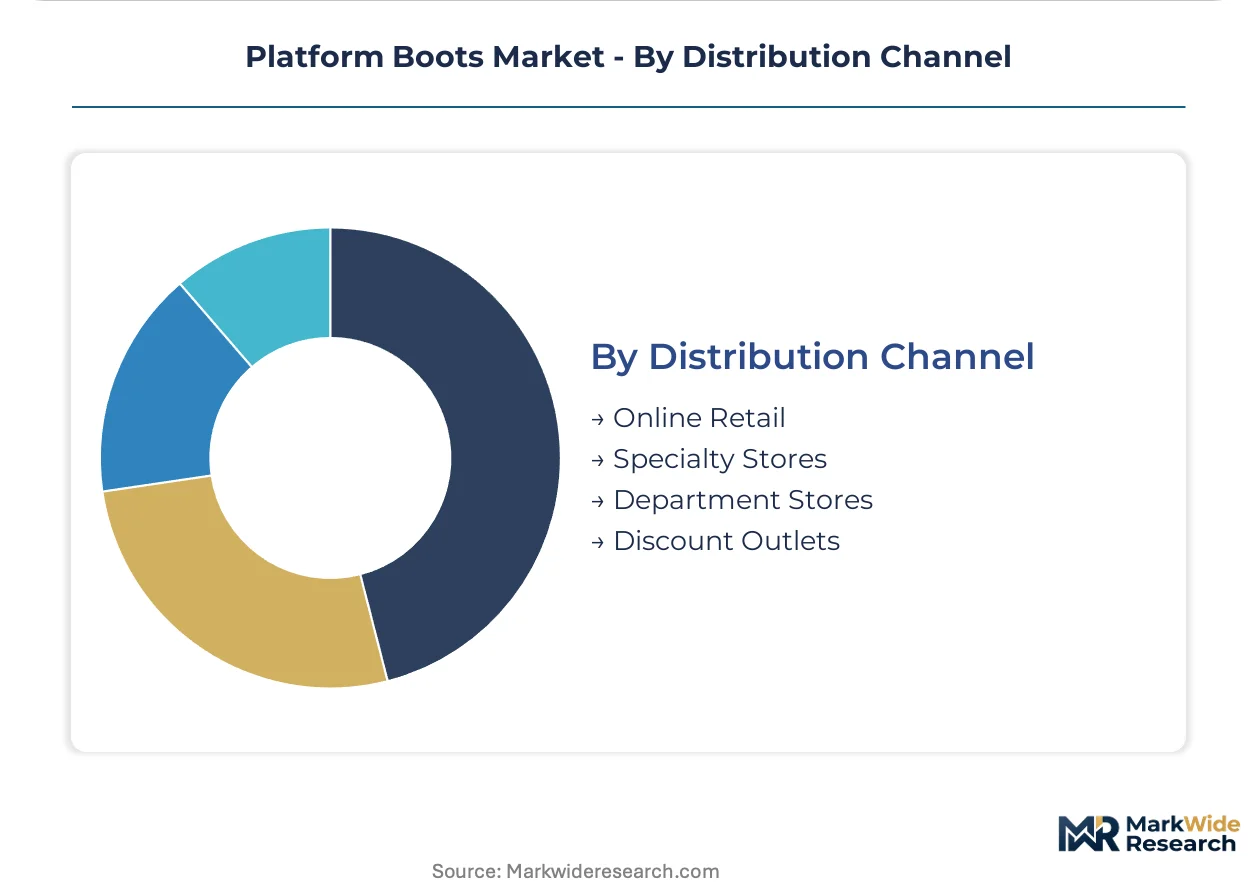
Distribution Channel:
Margin structure and customer acquisition cost diverge sharply between physical and digital routes, reshaping manufacturer channel strategy.
- Online Retail:Direct-to-consumer platforms with AR virtual try-on tools reducing return rates for fit-sensitive elevated footwear. Influencer partnerships on Chinese live commerce platforms compress trend-to-purchase cycles for statement styles.
- Specialty Stores:Curated assortments with trained staff guiding fit and material selection. Heritage British manufacturers defend position here through storytelling around welted construction techniques.
- Department Stores:Broad reach with seasonal buy commitments and promotional calendar pressure.
- Discount Outlets:Off-price clearance for end-of-season inventory and factory seconds.
Online Retail leads growth velocity, while Specialty Stores retain the highest margin per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
British welted construction artisans and Italian tannery technicians anchor the skilled workforce concentration in European platform boot manufacturing. German chemical engineers specializing in bio-based polyurethane formulations and Los Angeles-based social media trend scouts complete the talent geography.
United States
Teen streetwear adoption in Los Angeles and New York City drives volume through music and skate culture amplification. The Consumer Product Safety Commission monitors heel stability through voluntary ASTM standards that major retailers now mandate for shelf access. California's Proposition 65 labeling requirements add compliance costs for leather-tanned products containing trace chromium compounds in the Los Angeles apparel cluster.
Germany
Premium buyers in Berlin and Hamburg increasingly favor modular sole systems with component-replacement options that extend product lifespan. ECHA REACH Annex XVII restrictions on phthalates and heavy metals push manufacturers toward bio-based polyurethane alternatives. Bavarian chemical R&D hubs fragment production between legacy synthetic facilities and emerging bio-material laboratories to maintain EU market access.
United Kingdom
British manufacturing heritage commands price premiums in leather-focused collections with welted construction credibility. REACH compliance modularizes supply chains as producers balance heritage techniques against chemical disclosure mandates. Northamptonshire retains concentration of aging artisan populations with limited apprenticeship pipeline replacement for Goodyear welted methods.
Japan
METI sustainability guidelines favoring durable goods create market opening for heritage leather collections with proven longevity metrics. The country's national consumer safety regulator monitors product labeling standards for footwear imports. Tokyo and Osaka urban consumers concentrate demand for refined platform boot silhouettes in professional environments.
Italy
Italian tanneries pre-certify leather uppers for dual EU-US market entry to streamline chemical documentation. ECHA enforcement against persistent organic pollutants in rubber compounding forces reformulation of traditional vulcanization processes. Tuscany and Veneto manufacturing districts face welted construction skill scarcity amid aging specialist populations.
Platform Boots Market Competitive Landscape
Top-tier vendors anchor heritage manufacturing credibility, while mass-market competitors compete through rapid style turnover and synthetic material flexibility. The vendor base structures around three strategic archetypes: British-heritage leather specialists, fast-fashion digital natives, and diversified footwear conglomerates. Competitive moves concentrate on M&A for artisan capacity capture and direct-to-consumer platform buildout.
Within the heritage manufacturing tier, Dr. Martens plc and The Frye Company exemplify British and American leather-craft positioning respectively. ASOS plc occupies the digital-native fast-fashion vector with data-driven trend response capabilities. Steve Madden, Ltd. sits within the diversified mass-market archetype with synthetic material agility across wholesale and direct channels.
| Leading Market Players |
|---|
| Dr. Martens plc |
| Steve Madden, Ltd. |
| ASOS plc |
| Gucci |
| Timberland LLC |
| Christian Louboutin |
| Stuart Weitzman |
| The Frye Company |
| Wolverine Worldwide |
| Others |
Value Network & Pricing Analysis
British welted construction artisans in Northamptonshire anchor the premium tier through labor-cost differentials that separate heritage leather collections from mass-market synthetic lines. These aging specialist populations command wage premiums that propagate through three-tier pricing structures across premium, standard, and economy levels, while REACH compliance costs in European bio-based polyurethane R&D hubs compress margins on mid-market offerings.
Pricing Analysis
Bundled after-sales service for modular sole systems separates premium positioning from unbundled transactional pricing in mass-market channels. Price differentiation rests on construction depth and material provenance, with welted British-manufactured collections commanding premiums against cemented synthetic alternatives. Cost compression in synthetic-soled lines is intensifying because petrochemical input volatility erodes margins on rapid style turnover. Teen buyers in Los Angeles and London exhibit highest price sensitivity, while German modular-sole adopters demonstrate lowest sensitivity due to lifecycle cost calculations.
Supply Chain Analysis
REACH Annex XVII domestic-content mandates for bio-based materials are reshaping sourcing toward Southeast Asian natural rubber plantations and Italian pre-certified tanneries. Raw material dependencies draw from crude oil derivatives for polyurethane and EVA foam, chrome-tanned hides from Italian and British suppliers, and natural rubber from Thai and Indonesian estates. Single-source vulnerability concentrates in aging welted construction artisan pools across Northamptonshire and Tuscany. Distribution runs through direct-to-consumer platforms with AR virtual try-on tools, bypassing traditional wholesale forecasting for fast-response manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA REACH chemical restrictions on phthalates and heavy metals are accelerating bio-based material R&D investment and reshaping competitive economics.
For Market Incumbents: Anchor heritage manufacturing credibility through apprenticeship pipeline investment in Northamptonshire and Tuscany welted construction regions. Capture artisan capacity before demographic retirement waves eliminate transferable skill bases. Counter synthetic fast-fashion entrants by certifying leather uppers for dual EU-US market entry through Italian tannery partnerships, reducing compliance documentation duplication.
For New Entrants and Emerging Players: Chinese live commerce platforms offer the lowest customer acquisition cost route for statement fashion platform boots. Target teen buyers in underpenetrated Japanese professional environments where METI sustainability guidelines favor durable goods with proven longevity metrics. Launch through influencer-hosted streaming sales that compress trend-to-purchase cycles below traditional retail lead times.
For Investors and Strategic Acquirers: Diversified footwear conglomerates are the most active acquirer in this space, seeking digital-native direct-to-consumer capabilities to retrofit wholesale-centric heritage architectures. Long-term viability hinges on circular material mandate readiness under EU Green Deal textile strategy incentives. Watch ECHA enforcement intensity against persistent organic pollutants in rubber compounding as the inflection indicator for bio-based polyurethane substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Apprenticeship Pipeline Investment | Secures welted construction capacity in Northamptonshire against aging artisan retirement. |
| Bio-based Polyurethane R&D Scale-up | Positions manufacturers for REACH Annex XVII compliance without synthetic material disqualification. |
| Direct-to-Consumer Platform Buildout | Enables data-driven trend response that matches ASOS plc velocity in teen fashion cycles. |
| Dual EU-US Pre-certification Partnership | Streamlines chemical documentation through Italian tannery alliances for cross-border market access. |
| Modular Sole System After-sales Network | Captures German and Dutch buyer preference for component-replacement lifespan extension. |
Research Methodology
Bottom-up teen and women end-user modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at specialty retailers, supply planners, and Northamptonshire artisan workshop heads combined with secondary validation from ECHA enforcement databases, customs trade records, and SEC footwear company filings. Top-down and bottom-up triangulation cross-checks volume assumptions against production facility utilization and raw material import flows.
Historical trendline analysis across platform boot refresh cycles and construction method adoption patterns informs the projection framework. Segmentation dimensions modeled include product type, material provenance, end-user demographic, and distribution channel architecture. CAGRs derive from fitted growth curves applied to verified baseline volumes, incorporating social commerce penetration rates and virtual try-on technology diffusion as industry-specific forecast inputs throughout the forecast period.
The model assumes a particular technology adoption path for bio-based polyurethane formulations; alternative pathways for natural rubber sole compounds would alter the outlook. Forecasts reflect assumptions around ECHA enforcement consistency, teen social media platform stickiness, and artisan skill transferability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Middle East and Africa Athletic Footwear Market
Footwear
Sandals Market
Footwear
Luxury Footwear Market
Footwear
Sneaker Identification Service Market
Footwear
Golf Footwear Market
Footwear
Global Recovery Footwear Market
Footwear
Driving Footwear Market
Footwear
Waterproof Sneakers Market
Footwear
Slip Resistant Shoes Market
Footwear
Formal Shoes Market
Footwear
Tennis Shoes Market
Footwear
North America Athletic Footwear Market
Footwear
Custom Shoes Market
Footwear
Sports Footwear Market
Footwear
Kids Barefoot Shoes Market
Footwear
Duck Boots Market