
 Hiking Footwear Market | 2026-2036
Hiking Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Hiking Footwear Market Outlook
Direct-to-consumer digital channels is reshaping how hiking footwear reaches end buyers, compressing traditional wholesale markups and forcing brands to build in-house fulfillment capabilities. Salomon leverages its trail-running heritage to dominate alpine performance segments across European specialty retailers. Merrell sustains broad distribution through mass-market outdoor chains while competing on accessibility. KEEN differentiates through its American-built manufacturing narrative and toe-protection patents.
Hiking footwear comprises purpose-engineered shoes and boots designed for uneven terrain, typically incorporating lugged rubber outsoles with depths exceeding 4 millimeters, midsole shanks for torsional stability, and waterproof-breathable membranes to manage moisture exchange during prolonged exposure. The primary commercial purpose is to reduce injury risk and extend endurance for recreational and professional users traversing variable elevations and substrates. Hiking boots occupy the largest revenue pool due to replacement cycles and premium price positioning, while trail runners represent the fastest-growing product type as ultralight backpacking gains traction among younger demographics. Synthetic materials are displacing leather in volume terms as brands respond to vegan consumer preferences and supply chain traceability requirements.
REACH compliance in Europe restricts perfluorinated compounds in waterproofing treatments, compelling reformulation of durable water repellent chemistries across supply chains. The EU Green Deal's product environmental footprint criteria are pressuring manufacturers to disclose lifecycle carbon data for footwear sold in member states. ASTM F2413 in the United States establishes minimum performance benchmarks for protective toe components in work-hiking crossover styles. Stakeholders must monitor how extended producer responsibility frameworks for textile waste alter post-consumer collection obligations and circular business model economics.
Market Dynamics
Waterproof-breathable membrane technology is forcing wholesale supply chain restructuring as direct-to-consumer channels capture margin previously held by specialty retailers. Adventure tourism operators now specify recycled-content requirements in procurement contracts.
Growth Catalysts
- Adventure Tourism Procurement Standards:Commercial outfitters in the United States and Germany now mandate vegan material specifications for guide footwear. This pulls volume toward synthetic construction methods.
- REACH DWR Reformulation Mandate:ECHA restrictions on perfluorinated compounds are accelerating adoption of plant-based durable water repellent chemistries. Suppliers must recertify entire product lines.
- Ultralight Backpacking Demographics:Trail runners are displacing traditional boots among hikers under 35 who prioritize base weight reduction. This segment commands premium pricing for technical performance.
Market Restraints
- Petrochemical Input Volatility:Synthetic upper materials and rubber compounds face price instability tied to crude oil derivatives. Margins compress unpredictably across production cycles.
- East Asian Manufacturing Concentration:Over 70% of waterproof membrane lamination occurs in facilities clustered in southern China. Geopolitical friction threatens supply continuity.
- Biodegradability Performance Gap:Plant-based midsole foams currently fail to match EVA compression set standards. Durability compromises limit adoption in technical categories.
Strategic Opportunities
- Japanese Aging Hiker Segment:METI wellness initiatives promote senior outdoor recreation. Footwear optimized for joint protection and easy entry captures underpenetrated demand.
- EU Green Deal PEF Disclosure:Product environmental footprint requirements create first-mover advantage for brands with lifecycle carbon data. Premium positioning follows transparency.
- Digital Fit Technology Convergence:3D foot scanning combined with AI-generated last recommendations reduces return rates. Direct-to-consumer brands leverage this to bypass retail fitting infrastructure.
Industry Challenges
- Membrane Lamination Technician Scarcity:Skilled operators who maintain waterproof-breathable bonding equipment command wage premiums. Training pipelines remain underdeveloped.
- ASTM F2413 Cross-Category Certification:Work-hiking hybrid styles require protective toe testing timelines that extend 8-14 months. Product launch windows compress against seasonal demand.
- Post-Consumer Collection Infrastructure:Extended producer responsibility frameworks lack standardized collection density. Reverse logistics economics remain unfavorable outside urban corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hiking Footwear Market |
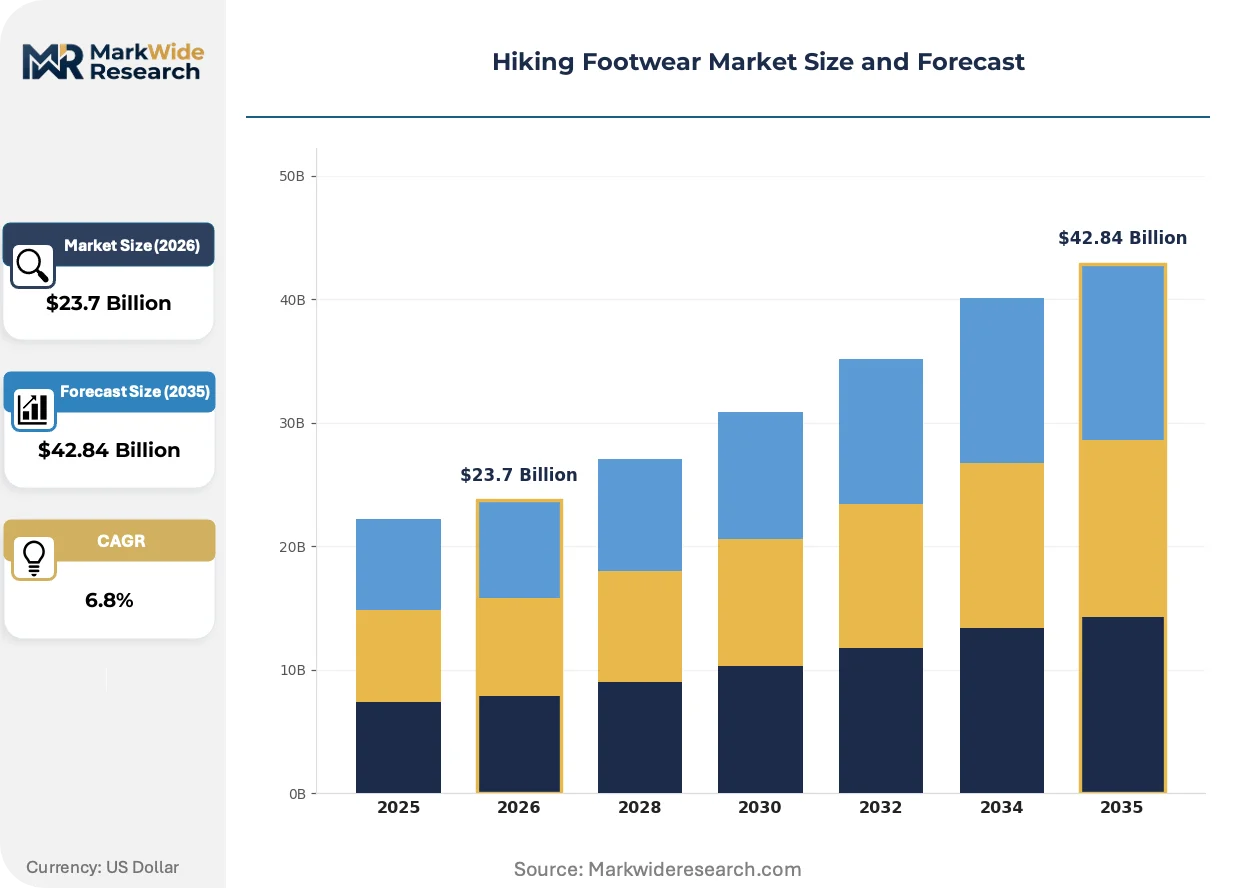
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trail Runners, Hiking Boots, Approach Shoes, Sandals Material: Leather, Synthetic, Gore-Tex, Rubber End User: Men, Women, Kids, Unisex Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | Altra, KEEN, HOKA, Oboz, Danner, Salomon, La Sportiva, Scarpa, Merrell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hiking Footwear Market Strategic Shifts
Material science breakthroughs and regulatory disclosure requirements are compressing product development cycles while fragmenting competitive positioning around sustainability verification rather than performance specifications alone.
Recycled membrane technology is digitizing quality control protocols throughout lamination facilities. Alpine specialty retailers now demand batch-level traceability data. This is digitizing supplier audit processes and compressing acceptable defect thresholds.
EU Green Deal product environmental footprint criteria are mandating lifecycle carbon disclosure for footwear sold in member states. Manufacturers must invest in primary data collection across tier-two and tier-three suppliers. Technical hiking boots face the steepest compliance burden due to multi-material construction complexity.
Specialty retail consolidation is compressing brand negotiation leverage. Independent outdoor shops in Germany and Japan are ceding floor space to direct-to-consumer showrooms and brand-owned experiential centers. Buyer concentration among surviving multi-brand chains is forcing margin concessions from heritage manufacturers.
Hiking Footwear Market Segmentation
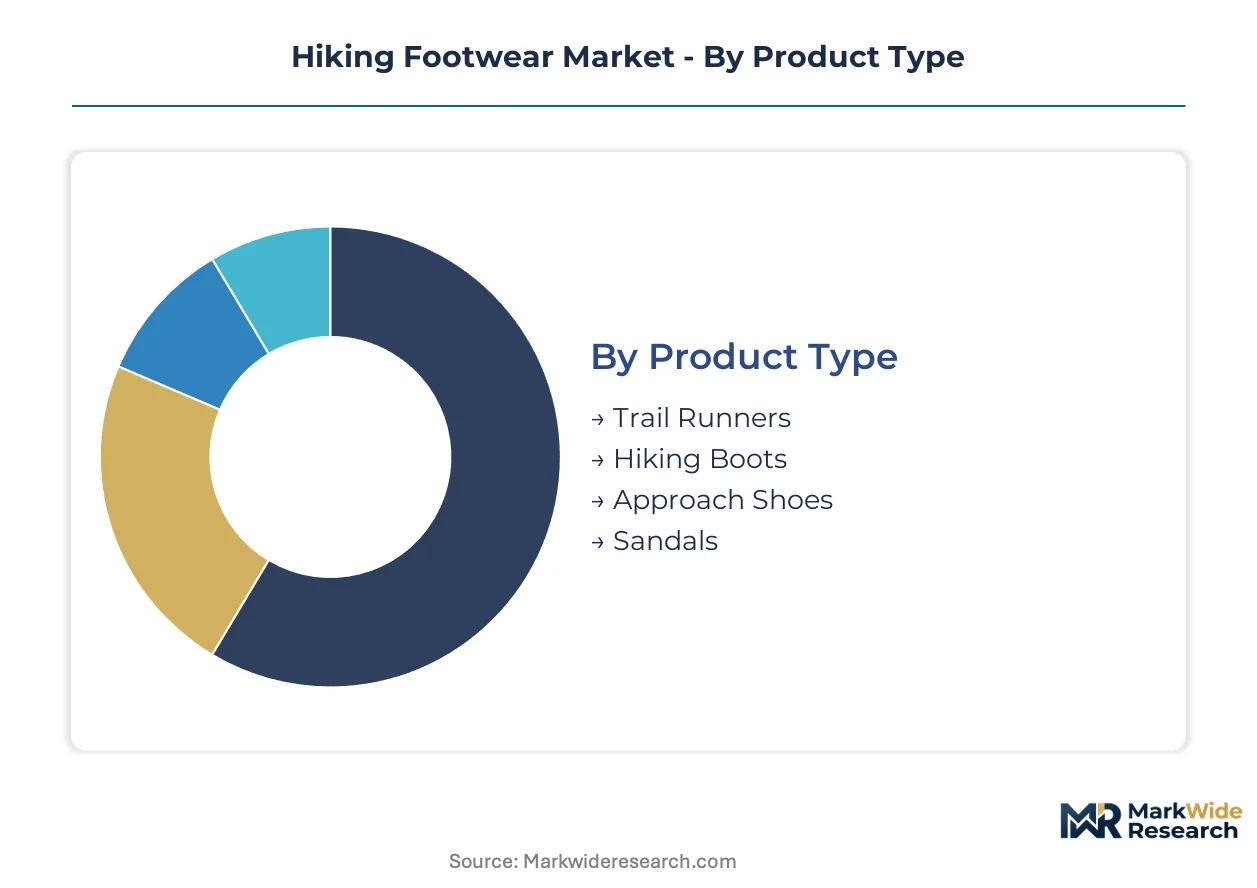
Hiking footwear segmentation reveals how technical specifications, material sourcing, and user demographics fragment commercial opportunity. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive strategy across the value chain.
Product Type:
Use-case spectrum spans ultralight speed to technical mountaineering, with construction methods and retail channels diverging sharply across the four categories.
- Hiking Boots:Full-grain leather or synthetic uppers paired with rigid shank midsoles and lug depths exceeding 5 millimeters define this category. Replacement cycles and premium price positioning concentrate revenue in alpine regions of Germany and the United States, though weight penalties now constrain adoption among younger users.
- Trail Runners:Engineered mesh uppers with aggressive 4-millimeter lugs and rock plates deliver sub-300-gram performance. Ultralight backpacking demographics in Japan and the Pacific Northwest are pulling volume fastest as base weight reduction becomes a purchasing priority.
- Approach Shoes:Sticky rubber outsoles and low-profile midsoles bridge hiking and climbing applications. European crag access regulations favor this hybrid construction.
- Sandals:Open-toe designs with adjustable strap systems and contoured footbeds serve river crossing and camp footwear needs. Warm-climate recreational use in the southern United States sustains niche demand.
Established volume favors Hiking Boots; emerging adoption favors Trail Runners.
Material:
Cost tier stratification separates heritage construction from performance-engineered alternatives, with traceability requirements now penetrating procurement decisions.
- Synthetic:Polyester and nylon woven uppers with welded overlays reduce weight 30-40% versus leather equivalents. REACH DWR reformulation mandates are accelerating plant-based coating adoption across European supply chains.
- Gore-Tex:Expanded polytetrafluoroethylene membranes laminated to textile substrates deliver waterproof-breathable performance. Lamination technician scarcity in southern China constrains capacity expansion for this premium tier.
- Leather:Full-grain and nubuck hides provide abrasion resistance and mold-to-foot customization. Vegan consumer preferences in Germany are compressing volume share.
- Rubber:Carbon-black reinforced outsole compounds with variable durometers optimize grip across substrates. Petrochemical input volatility creates margin unpredictability.
Heritage positioning sustains Leather; technical performance and regulatory compliance favor Synthetic.
End User:
Customer type fragmentation reflects fit engineering requirements and purchasing autonomy differences across age and gender lines.
- Men:Wider lasts and higher volume insteps dominate technical category development. Adventure tourism procurement standards in the United States specify this segment for guide footwear.
- Women:Narrower heel cups and higher arch support address anatomical variance. Direct-to-consumer digital channels capture disproportionate share through AI-generated last recommendations.
- Kids:Rapid outgrowth cycles and simplified closure systems define construction priorities. Price sensitivity concentrates demand in mass-market outdoor chains.
- Unisex:Adjustable lacing and medium-volume lasts accommodate diverse foot morphologies. Specialty retail consolidation is compressing shelf space for this flexible positioning.
Volume concentration sits with Men; margin expansion potential concentrates in Women.
Price Tier:
Margin structure separates certification-grade technical footwear from accessible entry points, with distribution channel control determining profitability.
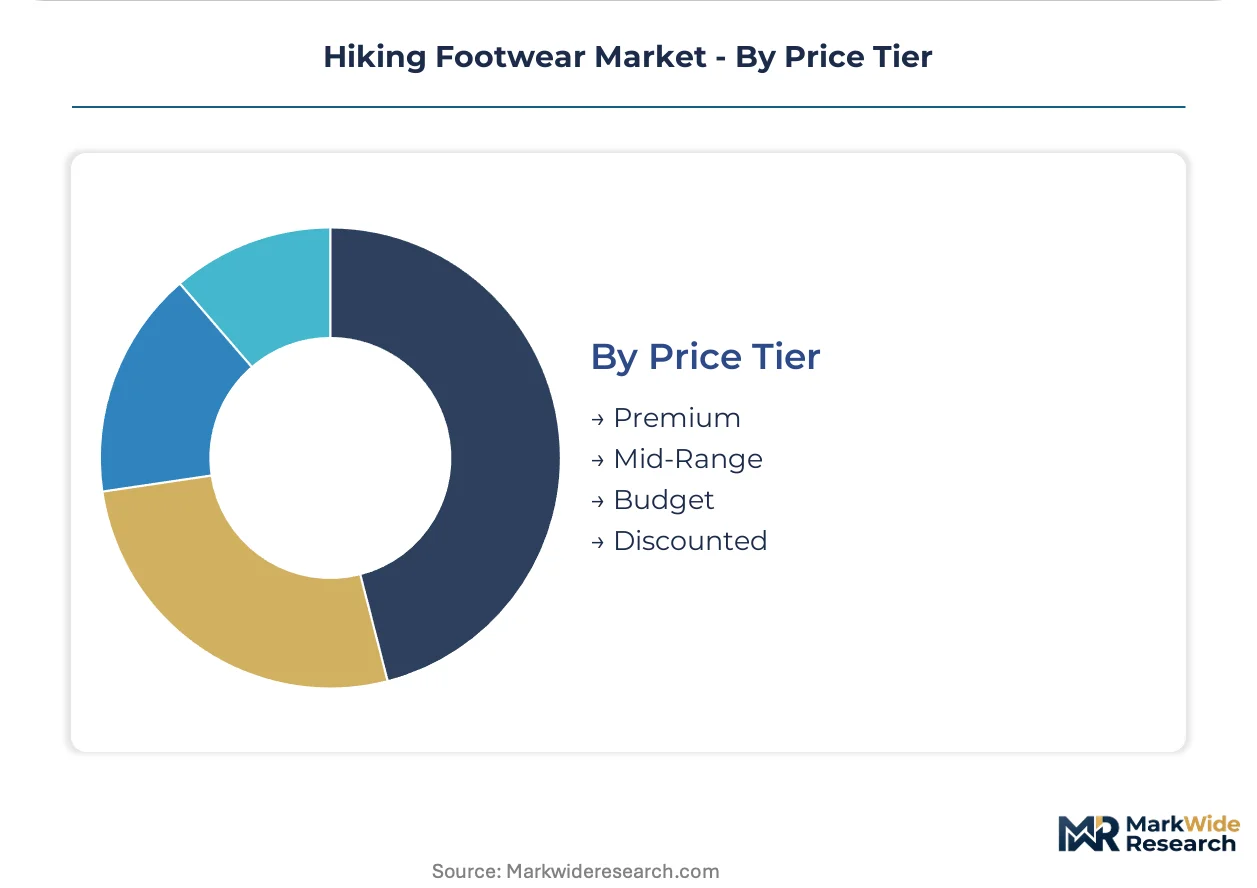
- Premium:Lifecycle carbon disclosure compliance and batch-level membrane traceability justify price positioning above $250. EU Green Deal PEF requirements create first-mover advantage for transparent brands.
- Mid-Range:Balanced performance specifications without specialized certifications capture recreational hikers in Japan and Germany. Merrell sustains broad distribution through this positioning.
- Budget:Simplified construction with basic waterproofing serves occasional users. Digital fit technology convergence is eroding retail fitting infrastructure dependency here.
- Discounted:Closeout inventory and prior-season styles clear through outlet channels. Post-consumer collection infrastructure gaps limit circular model economics.
Profitability concentrates in Premium; volume accessibility depends on Budget positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA standards in the United States anchor the dominant geography, where adventure tourism procurement and direct-to-consumer digital channels concentrate commercial activity. Germany and Japan follow with distinct regulatory and demographic drivers.
United States
Adventure tourism operators in Colorado and Utah now mandate vegan material specifications for guide footwear, pulling volume toward synthetic construction. EPA oversight of perfluorinated compound discharge influences domestic waterproofing reformulation timelines. Manufacturing clusters in Portland, Oregon and Boston, Massachusetts specialize in alpine performance design and digital fit technology development.
Germany
Bavarian and Black Forest hiking associations report surging trail runner adoption among hikers under 35 prioritizing base weight reduction. ECHA REACH restrictions on perfluorinated compounds accelerate plant-based durable water repellent chemistry adoption across supply chains. Specialty retail consolidation in Munich and Frankfurt compresses independent outdoor shop floor space while direct-to-consumer showrooms expand.
Japan
METI wellness initiatives promote senior outdoor recreation, creating underpenetrated demand for joint-protection footwear with easy entry systems. The country's national standards body coordinates with industry on biodegradable midsole foam performance benchmarking. Industrial concentration in the Kanto region around Tokyo supports precision lamination equipment manufacturing for waterproof-breathable membranes.
China
Dual carbon goals pressure manufacturers in Guangdong and Fujian provinces to disclose lifecycle carbon data for export-bound footwear. The Ministry of Ecology and Environment tightens oversight of textile chemical discharge in membrane lamination facilities. Southern China clusters maintain over 70% of waterproof membrane lamination capacity, though geopolitical friction threatens supply continuity planning.
United Kingdom
Lake District and Scottish Highland trail maintenance programs stimulate replacement cycle demand for technical hiking boots. The country's national environmental regulator enforces extended producer responsibility frameworks altering post-consumer collection economics. Manchester and Sheffield retain heritage manufacturing expertise in leather tanning and welted boot construction.
Hiking Footwear Market Competitive Environment
Alpine heritage specialists and mass-market accessibility providers split the market into distinct competitive spheres. The structure remains moderately consolidated, with five to eight brands capturing disproportionate shelf space and digital traffic. Three archetypes dominate: European alpine performance houses, American outdoor lifestyle conglomerates, and trail-running pure-plays. Competitive moves center on direct-to-consumer channel buildout and sustainability certification acquisition rather than price-based confrontation.
Within the alpine heritage tier, Salomon and La Sportiva exemplify technical performance positioning rooted in European mountain sports lineage. Scarpa occupies a position bridging Italian craftsmanship tradition with modern materials engineering. At the mass-market accessibility vector, Merrell anchors broad distribution through outdoor retail chains while competing on entry-point price positioning. KEEN represents a distinct American-built manufacturing narrative with proprietary toe-protection architecture. These five entities collectively illustrate how geographic origin, construction philosophy, and channel strategy fragment competitive identity without requiring homogeneous product overlap.
| Leading Market Players |
|---|
| Altra |
| KEEN |
| HOKA |
| Oboz |
| Danner |
| Salomon |
| La Sportiva |
| Scarpa |
| Merrell |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific container freight corridors from Guangdong and Fujian provinces to Long Beach and Rotterdam anchor cost dynamics for waterproof-breathable membrane lamination, compressing margins for synthetic-construction tiers while premium leather sourcing from Italian tanneries sustains price elevation through scarcity positioning.
Pricing Analysis
The customization-premium spread separates configured-to-order alpine boots with anatomical last modifications from standard trail runners, with three-tier pricing structure across premium, standard, and economy levels driven by membrane certification grade and batch-level traceability investment. Price differentiation hinges on REACH DWR reformulation compliance and lifecycle carbon disclosure under EU Green Deal PEF requirements. Cost compression in budget tiers is intensifying because petrochemical input volatility erodes synthetic material margins. Mass-market outdoor chains exhibit highest price sensitivity, while specialty retailers serving ultralight backpacking demographics absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Contract-manufacturing concentration rests with southern China facilities handling over 70 percent of waterproof membrane lamination, supplemented by precision equipment manufacturing clusters in Japan's Kanto region and heritage welted boot construction in Manchester and Sheffield. Raw material dependencies draw from petroleum-derived synthetic uppers, carbon-black reinforced rubber compounds, and full-grain hides from European tanneries. Single-source vulnerability concentrates in membrane lamination technician scarcity across Guangdong province. Distribution runs through direct-to-consumer digital channels compressing traditional wholesale markups, with brand-owned experiential centers displacing independent outdoor shop floor space in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hiking footwear market reads as a service-attach opportunity where digital fit technology subscriptions and AI-generated last recommendation platforms expand faster than hardware unit growth, creating recurring revenue layers with superior retention economics.
For Market Incumbents: Pre-empt synthetic construction margin erosion by securing captive supply of plant-based DWR chemistries through backward integration into coating formulation facilities in REACH-compliant European jurisdictions. Defend against trail-running pure-plays by accelerating ASTM F2413 certification timelines for work-hiking hybrid styles, compressing 8-14 month testing windows through parallel laboratory engagement.
For New Entrants and Emerging Players: Establish a beachhead in the Japanese aging hiker segment where METI wellness initiatives stimulate underpenetrated demand for joint-protection footwear with easy entry systems. Target direct-to-consumer digital channels with 3D foot scanning integration, bypassing retail fitting infrastructure that incumbents have built over decades.
For Investors and Strategic Acquirers: Carve-out targets emerge from American outdoor lifestyle conglomerates seeking to divest heritage manufacturing assets with proprietary toe-protection patents and American-built narratives. Long-term viability favors brands with transparent lifecycle carbon data infrastructure already deployed. The signal to watch is EU Green Deal PEF disclosure enforcement velocity as first-mover advantage crystallizes around verified environmental footprints.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Buildout | Bypasses wholesale markups and captures margin previously held by specialty retailers in Germany and Japan. |
| Plant-Based DWR Chemistry Investment | Addresses ECHA REACH restrictions on perfluorinated compounds across European supply chains. |
| Digital Fit Technology Integration | Reduces return rates through AI-generated last recommendations and 3D foot scanning convergence. |
| Lifecycle Carbon Disclosure Infrastructure | Creates first-mover advantage under EU Green Deal PEF requirements for premium positioning. |
| Biodegradable Midsole Foam R&D | Closes durability performance gap against EVA compression set standards in technical categories. |
Study Parameters
Initial hypotheses were tested against primary input from brand product development directors, specialty retail buyers, adventure tourism procurement officers, and membrane lamination facility engineers, and refined through secondary validation against customs records, SEC footwear sector filings, ECHA chemical registration databases, and outdoor industry association trade data. Bottom-up volume estimates from individual product lines were triangulated against top-down category spending analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, material construction, end-user demographic, and price tier dimensions. CAGRs were derived from regression analysis of historical volume patterns against adventure tourism growth indices, regulatory compliance cost trajectories, and generational purchasing preference shifts. Industry-specific forecast inputs incorporated REACH DWR reformulation timelines and ASTM F2413 certification backlog data.
Stress conditions across petrochemical price volatility, geopolitical friction in East Asian manufacturing corridors, and extended producer responsibility framework enforcement velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about membrane lamination capacity expansion and synthetic material adoption curves. Quarterly review of ECHA regulatory pronouncements and METI wellness initiative funding levels is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Men Formal Shoe Market
Footwear
Footwear Testing Services Market
Footwear
Global Recovery Footwear Market
Footwear
Refurbished Running Shoes Market
Footwear
UGG Boots Market
Footwear
Cyber-Shoes Market
Footwear
Womens Footwear Market
Footwear
Riding Boots Market
Footwear
White Sneakers Market
Footwear
Duck Boots Market
Footwear
Training Shoes Market
Footwear
Barefoot Shoes Market
Footwear
Sustainable Footwear Market
Footwear
Athletic Footwear Market
Footwear
Casual Shoes Market
Footwear
Ankle Boots Market