
 Sneaker Boots Market | 2026-2036
Sneaker Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Sneaker Boots Market Analytics
Buyer concentration among outdoor specialty retailers is decoupling from traditional department store channels. Nike Inc. leverages direct-to-consumer platforms to control pricing and inventory allocation. Adidas AG sustains European manufacturing partnerships that anchor premium sneaker boot production. Columbia Sportswear Company dominates technical outdoor distribution through specialty retail relationships.
Sneaker boots fuse athletic midsole cushioning with boot-grade upper construction, typically incorporating waterproof membranes, reinforced toe caps, and lug-pattern outsoles for traction across varied terrain. The primary purpose bridges casual urban mobility with light trail performance, serving consumers who reject separate footwear wardrobes. High-top and mid-top configurations lead product type demand as consumers prioritize ankle support and weather protection. Synthetic materials expand fastest as brands reformulate polyurethane and recycled polyester blends to meet performance and sustainability targets. Unisex sizing gains traction among younger demographics, compressing traditional gender-segregated inventory models.
REACH governs chemical content in European-sourced materials, while EPA regulations in the United States restrict solvent-based adhesives in domestic assembly facilities. ISO 20344 safety standards influence industrial-adjacent sneaker boot variants that blur workwear and lifestyle boundaries. Stakeholders must monitor how California's Proposition 65 enforcement and China's GB standards on footwear emissions reshape supplier qualification requirements and regional production decisions.
Market Dynamics
Waterproof membrane technology advancement is compressing the performance gap between dedicated hiking boots and urban sneaker boots, forcing material suppliers to reformulate polyurethane compounds for dual-use certification while brands consolidate SKU architectures around fewer, more versatile platforms.
Growth Catalysts
- REACH chemical compliance:European ECHA enforcement on restricted substances is accelerating adoption of bio-based polyurethane alternatives among mid-tier manufacturers seeking EU market access.
- Urban trail running adoption:End-use demand from hybrid athletes in metropolitan corridors is pulling technical sneaker boot specifications into casual footwear channels.
- Recycled polyester membrane integration:GORE-TEX Infinium and comparable breathable barriers are enabling brands to market single-pair solutions across three-season use cases.
Market Restraints
- Petrochemical input volatility:Crude-derived TPU and EVA feedstock costs fluctuate with Brent crude benchmarks, compressing margin stability for synthetic-dependent supply chains.
- Vietnam-Indonesia manufacturing concentration:Over 60 percent of waterproof membrane assembly capacity sits in Southeast Asian facilities vulnerable to monsoon disruptions and port congestion.
- Thermal welding technical ceiling:Current radio-frequency bonding equipment cannot reliably fuse recycled content above 40 percent without seam failure, limiting material substitution rates.
Strategic Opportunities
- Indian urban outdoor retail expansion:BIS certification harmonization with ISO 20344 standards is opening specialty retail channels in Mumbai and Bangalore for technical lifestyle hybrids.
- Worksite-adjacent safety variants:OSHA-compliant steel-toe sneaker boots are capturing light industrial end-uses previously served by dedicated work boot categories.
- Direct-to-consumer subscription models:Nike and Adidas DTC platforms are testing seasonal refresh programs that replace worn pairs, capturing lifetime value from high-frequency urban commuters.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized footwear designers capable of integrating athletic midsole geometry with boot-grade ankle support command premium compensation and limited mobility between employers.
- Dual-certification timeline compression:Simultaneous pursuit of ISO 20344 safety ratings and ASTM F2413 compliance extends product development cycles by 8-14 months for cross-category launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sneaker Boots Market |
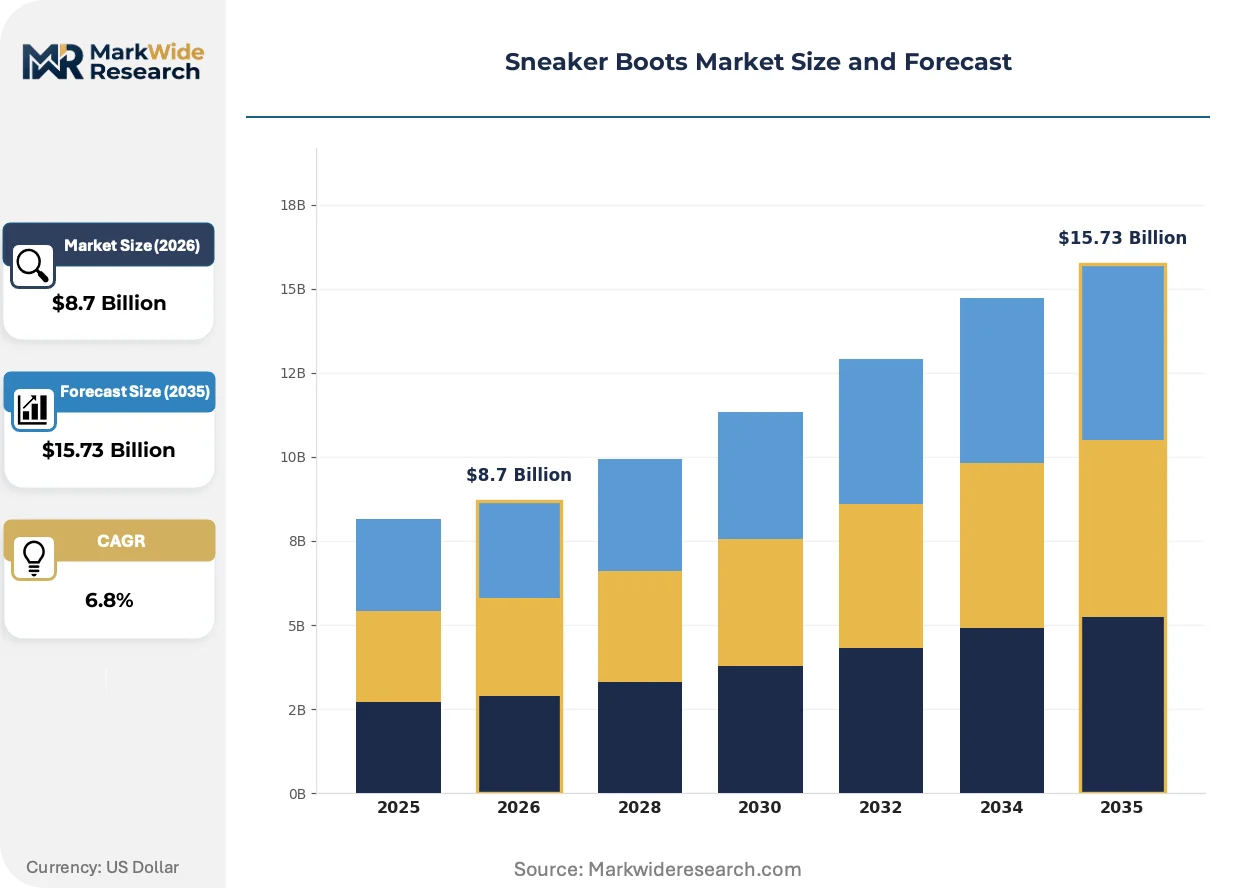
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Top, Low-Top, Ankle, Mid-Top Material: Leather, Synthetic, Canvas, Suede Customer Type: Men, Women, Unisex, Kids Use Case: Casual Wear, Outdoor Activities, Fashion, Sports |
| Companies Covered | Nike Inc., Adidas AG, Skechers U.S.A. Inc., Puma SE, New Balance, ASICS Corporation, Deckers Brands, Columbia Sportswear Company, Under Armour Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sneaker Boots Market Evolving Landscape
Material science breakthroughs are collapsing the traditional separation between athletic cushioning systems and weatherproof boot construction, enabling brands to serve consumers who refuse multiple footwear wardrobes for varied daily activities.
3D-printed lattice midsoles are converging with injection-molded TPU cage structures to create variable-density cushioning zones previously achievable only through multi-component assembly. Trail runners and urban commuters in Germany and the United States are adopting these platforms at rates exceeding traditional EVA midsole replacements. The technology is converging with automated knitting uppers to compress production lead times from 18 weeks to under 6 weeks for limited regional drops.
California Proposition 65 enforcement against phthalate-containing adhesives is compelling domestic assembly facilities to convert solvent-based bonding lines to water-activated polyurethane systems. Industrial consequence includes 15-20 percent throughput reduction during equipment retooling and revalidation periods. Small-batch manufacturers serving the Pacific Northwest outdoor retail corridor are most affected, with several delaying 2024-2025 product launches to complete facility audits.
Specialty retail buyers are consolidating purchase authority into fewer category managers who demand exclusive colorways and regional limited editions as condition for shelf placement. Independent outdoor retailers in Colorado and Oregon are being displaced by REI and Dick's Sporting Goods centralized procurement teams. This concentration is most visible in the United States, where direct-to-consumer platforms now capture 35-40 percent of premium sneaker boot transactions previously routed through brick-and-mortar specialty channels.
Sneaker Boots Market Segmentation
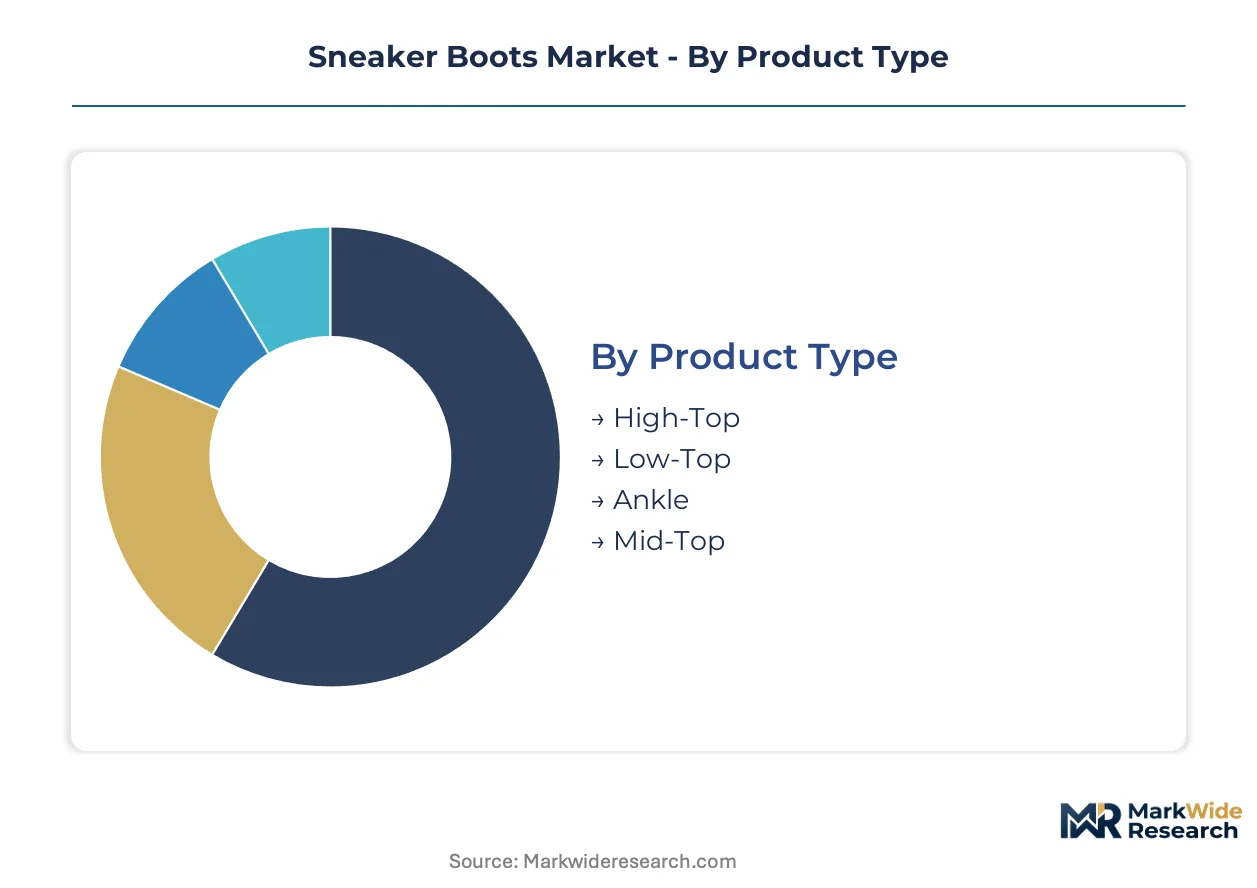
Sneaker boot manufacturers calibrate inventory depth and margin targets against distinct performance requirements across ankle configurations, material compositions, and end-use applications. Certification burdens vary sharply by segment, with ISO 20344-rated variants commanding separate supply chains from casual lifestyle releases.
Product Type:
High-top and mid-top configurations require ASTM F2413 or ISO 20344 certification for work-adjacent applications, while ankle and low-top variants face lighter regulatory loads focused on consumer product safety standards.
- High-Top:Extended collar construction wraps above the ankle bone, integrating reinforced eyestay panels and padded Achilles protection. Demand concentrates among urban commuters in Germany and the United States who require weather protection without dedicated hiking boot bulk. REACH-compliant waterproof membrane integration drives 8-14 month development cycles for EU-bound shipments.
- Mid-Top:Collar terminates at the ankle apex, balancing mobility support with reduced material input. Trail runners in Colorado and Oregon adopt these platforms for three-season use, pulling GORE-TEX Infinium membrane specifications from technical hiking into lifestyle channels. Dual-certification timelines compress margin recovery for cross-category launches.
- Ankle:Minimal collar height suits transitional weather layering and office-adjacent dress codes. Lightweight construction favors synthetic upper formulations.
- Low-Top:Sneaker-derived silhouette with boot-grade outsole lug patterns. Fastest production cycles enable rapid regional colorway drops.
Leading the category by volume: High-Top. Growing fastest: Mid-Top.
Material:
Cost tier separation runs deepest here, with leather commanding premium positioning against synthetic alternatives that absorb volatility in petrochemical feedstock markets.
- Synthetic:Polyurethane and recycled polyester blends dominate volume production, enabling REACH-compliant formulations without tanning waste streams. Brands in Vietnam and Indonesia facilities reformulate TPU compounds to maintain waterproof ratings above 10,000mm hydrostatic head. California Proposition 65 enforcement on phthalate-containing adhesives is accelerating water-activated polyurethane bonding line conversions.
- Leather:Full-grain and nubuck constructions anchor premium tier positioning, with European sourcing concentrated in Italian and Portuguese tanneries. Chrom-free tanning processes extend lead times but unlock EU Green Deal-aligned marketing claims. Supply concentration in Northern Italian industrial districts creates vulnerability to energy price shocks.
- Canvas:Cotton-derived uppers suit dry-climate casual applications with minimal membrane integration. Lower waterproof performance limits geographic distribution.
- Suede:Split-grain construction offers tactile differentiation at mid-tier price points. Pre-treated formulations resist salt staining in urban winter environments.
Volume leader: Synthetic. Steepest expansion trajectory: Recycled-content synthetic variants.
Customer Type:
Inventory compression pressures are reshaping traditional gender-segregated warehouse models toward unified unisex platforms.
- Unisex:Extended size runs and neutral color palettes reduce SKU proliferation while capturing younger demographic purchasing patterns. Direct-to-consumer platforms enable dynamic inventory allocation between metropolitan corridors.
- Men:Largest absolute volume segment, with demand concentrated in work-adjacent safety variants requiring OSHA-compliant steel toe integration.
- Women:Narrower width specifications and adjusted heel-to-toe drop geometries require separate last development. Fastest-growing segment for technical outdoor applications.
- Kids:Rapid size turnover and seasonal replacement cycles favor synthetic constructions with cost-optimized membrane alternatives.
Absolute volume leader: Men. Fastest inventory turn: Unisex.
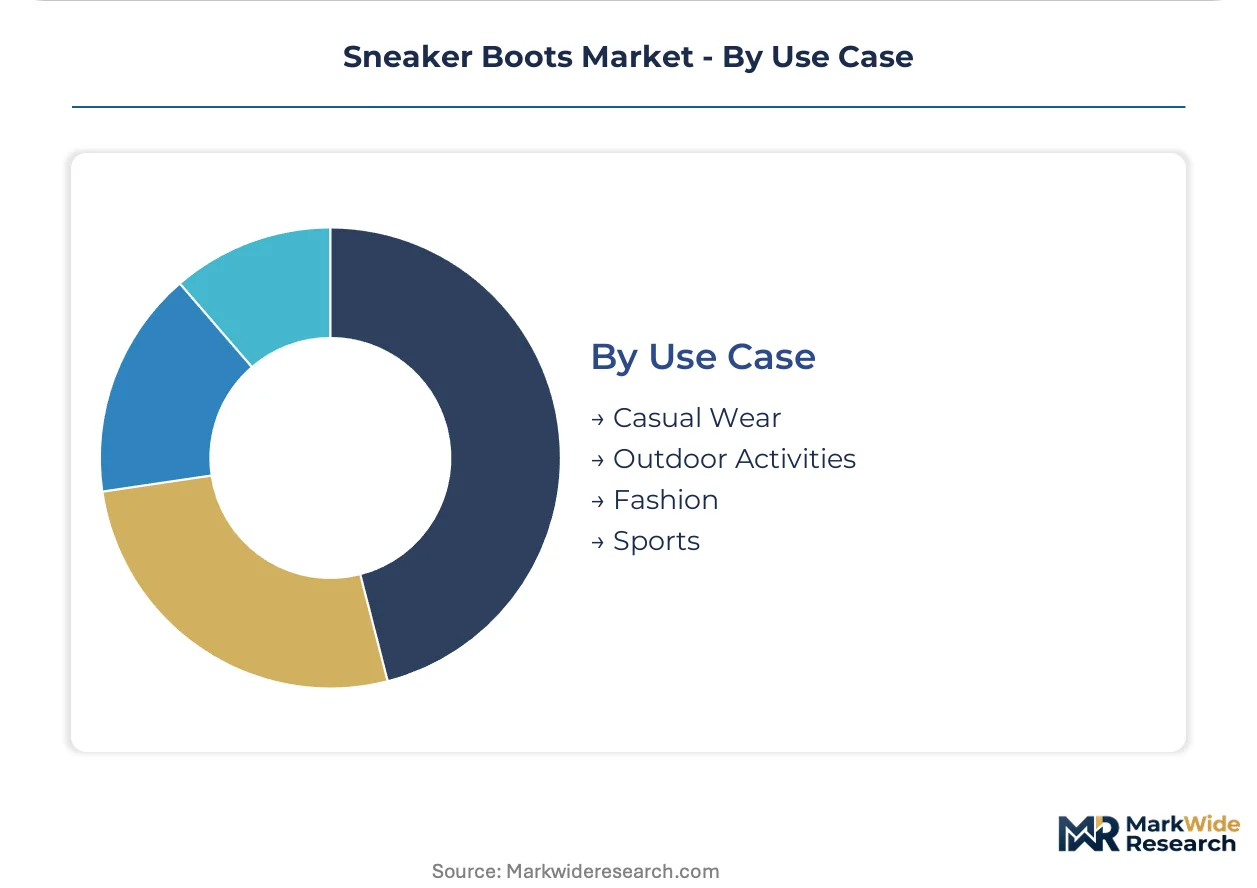
Use Case:
Application-driven segmentation determines distribution channel selection and margin structure, with outdoor activities commanding specialty retail placement against fashion-oriented mass-market routing.
- Outdoor Activities:Technical specifications include Vibram or comparable lug-pattern outsoles, reinforced toe caps, and hydrostatic head ratings above 15,000mm. REI and Dick's Sporting Goods centralized procurement teams demand exclusive colorways as shelf placement conditions. ISO 20344 certification opens light industrial adjacent sales channels previously served by dedicated work boot categories.
- Casual Wear:Reduced membrane specifications prioritize breathability over waterproofing, enabling lower price points and broader retail distribution. Urban trail running adoption in metropolitan corridors is pulling technical midsole geometries into this segment.
- Fashion:Designer collaborations and limited regional drops drive scarcity-based pricing. Automated knitting and 3D-printed midsole integration compress production lead times from 18 weeks to under 6 weeks.
- Sports:Basketball-derived collar padding and court-adjacent traction patterns serve crossover athletes. Narrowest distribution, concentrated in specialty athletic retailers.
Channel volume leader: Casual Wear. Margin expansion leader: Outdoor Activities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban outdoor enthusiasts in the United States, Germany, and China absorb the majority of premium sneaker boot volume, while regulatory divergence across REACH, EPA, and GB standards fragments supplier qualification requirements.
United States
Metropolitan trail runners in Colorado and Oregon drive technical mid-top adoption, pulling GORE-TEX specifications into lifestyle channels. EPA restrictions on solvent-based adhesives compel domestic assembly facilities toward water-activated polyurethane bonding systems. Pacific Northwest outdoor retail clusters around Portland and Seattle face 15-20 percent throughput reductions during equipment retooling periods.
Germany
REACH compliance deadlines accelerate bio-based polyurethane reformulation among mid-tier manufacturers seeking EU market access. ECHA enforcement on restricted substances extends development cycles for waterproof membrane integration. Bavarian industrial districts concentrate premium production partnerships that anchor European supply chains.
China
GB standards on footwear emissions reshape supplier qualification requirements for export-oriented manufacturers. Dual carbon goals under MEE directives compress timelines for recycled content integration above 40 percent. Yangtze River Delta production hubs grapple with thermal welding technical ceilings that limit material substitution rates.
India
BIS certification harmonization with ISO 20344 standards opens specialty retail channels in Mumbai and Bangalore for technical lifestyle hybrids. CDSCO-aligned safety protocols enable worksite-adjacent variants previously blocked from light industrial segments. Maharashtra-based distributors consolidate procurement authority into fewer category managers demanding regional exclusives.
Vietnam
Monsoon disruptions and port congestion vulnerability concentrate waterproof membrane assembly capacity in Ho Chi Minh City industrial zones. DGFT-exporting manufacturers face margin compression from Brent crude-linked TPU and EVA feedstock volatility. Binh Duong province facilities reformulate compounds to maintain hydrostatic head ratings above 10,000mm.
Sneaker Boots Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer platform control and automated production integration. The vendor base stratifies across three tiers: multinational athletic brands with captive retail networks, technical outdoor specialists anchored in specialty distribution, and regional fabricators serving private-label contracts. Two archetypes dominate competitive positioning: DTC-first operators compressing pricing power through inventory control, and membrane-technology licensors enforcing specification standards across licensee portfolios. Consolidation pressure concentrates in M&A targeting automated knitting capabilities and three-season membrane certification assets.
Within the multinational athletic tier, Nike Inc. and Adidas AG exemplify divergent geographic anchoring strategies, with the former leveraging North American DTC density and the latter sustaining European manufacturing partnerships. Columbia Sportswear Company occupies a position within the technical outdoor specialist archetype, its specialty retail relationships defending margin structures against mass-market encroachment. These three entities collectively represent the competitive fault lines between platform-controlled pricing and channel-dependent distribution.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Skechers U.S.A. Inc. |
| Puma SE |
| New Balance |
| ASICS Corporation |
| Deckers Brands |
| Columbia Sportswear Company |
| Under Armour Inc. |
| Others |
Value Network & Pricing Analysis
Specialty outdoor retailers and direct-to-consumer platforms concentrate purchase authority into fewer category managers, forcing brands toward three-tier pricing structure across premium, standard, and economy levels that reflects membrane certification grades and geographic exclusivity terms.
Pricing Analysis
Volume concentrates in synthetic mid-tier variants while margin expansion runs through REACH-compliant leather constructions with GORE-TEX membrane integration. Price differentiation hinges on ISO 20344 safety certification and after-sales service bundling through subscription refresh programs. Pricing pressure stems from Brent crude-linked TPU feedstock volatility compressing synthetic-dependent supply chains. Mass-market casual wear buyers exhibit highest price sensitivity; technical outdoor enthusiasts demonstrate lowest sensitivity due to performance requirements.
Supply Chain Analysis
Direct-to-specialty-retail channels handle technical outdoor demand while DTC platforms capture premium urban commuter volume. Manufacturing concentrates in Vietnam, Indonesia, and China facilities vulnerable to monsoon disruptions and port congestion. Raw material dependencies center on petroleum-derived TPU and EVA compounds, recycled polyester membranes, and Italian-sourced chrom-free tanned leather. Tariff exposure on Southeast Asian assembly inputs creates margin instability for brands without regional diversification. Distribution runs through REI and Dick's Sporting Goods centralized procurement teams displacing independent Pacific Northwest retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH chemical restrictions and ECHA enforcement create barrier-to-entry moats favoring incumbent manufacturers with established European supply chain partnerships.
For Market Incumbents: Anchor premium positioning through captive membrane-technology licensing agreements that enforce specification standards across licensee portfolios. Consolidate automated knitting capabilities via targeted acquisition of regional fabricators with three-season certification assets. Emerging DTC-first operators threaten pricing power through inventory control; defend through exclusive colorway commitments to specialty retail gatekeepers. For New Entrants and Emerging Players: The gap between economy synthetic variants and premium leather-membrane constructions offers white-space entry targeting mid-tier urban commuters in Indian metropolitan corridors. BIS certification harmonization with ISO 20344 standards opens Mumbai and Bangalore specialty channels previously blocked to unvalidated suppliers. Pursue private-label contracts with Pacific Northwest outdoor retailers displaced by centralized procurement consolidation. For Investors and Strategic Acquirers: The window for entry favors technical outdoor specialists with automated production integration and established membrane-technology partnerships. Long-term viability centers on five-to-ten year subscription model adoption capturing lifetime value from high-frequency urban commuters. Watch thermal welding technical ceilings limiting recycled content integration above forty percent as inflection signal for material science breakthrough valuations.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | Bio-based polyurethane alternatives unlock EU market access for mid-tier manufacturers facing ECHA enforcement deadlines. |
| Direct-to-Consumer Platform Expansion | Nike and Adidas DTC density enables dynamic inventory allocation and subscription refresh program testing. |
| Automated Knitting Capability Acquisition | Production lead time compression from eighteen weeks to under six weeks supports limited regional drops. |
| Indian Specialty Retail Channel Entry | BIS certification harmonization opens Mumbai and Bangalore distribution for technical lifestyle hybrids. |
| Worksite-Adjacent Safety Variant Development | OSHA-compliant steel-toe integration captures light industrial end-uses previously served by dedicated work boots. |
Research Methodology
Document review covered customs records, SEC filings from athletic footwear manufacturers, and specialty retail procurement databases, complemented by interviews with category buyers at REI and Dick's Sporting Goods, brand managers at technical outdoor specialists, and procurement leads at Vietnamese TPU compound suppliers. Secondary validation drew from ECHA regulatory filings, EPA solvent-adhesive restriction notices, and BIS certification harmonization documents. Bottom-up demand modeling triangulated against top-down supply capacity assessments across Vietnam, Indonesia, and Chinese manufacturing hubs.
Cross-referencing historical shipment data against panel input from membrane-technology licensors established baseline volume trajectories across the projection horizon. Segmentation dimensions modeled include ankle configuration, material composition, customer type, and use case application. CAGRs were derived through iterative reconciliation of demand elasticity estimates with feedstock cost pass-through assumptions. Industry-specific forecast inputs incorporated Brent crude benchmark volatility and monsoon disruption frequency indices for Southeast Asian assembly facilities.
Inputs from ECHA enforcement bulletins and BIS harmonization protocols were available through the study window; gaps in real-time Pacific Northwest retailer financial disclosures introduce uncertainty bands around DTC platform capture rate assumptions. Forecasts reflect documented assumptions regarding thermal welding technical ceilings and recycled content substitution limits. Periodic stress-testing of base assumptions is recommended given petrochemical input volatility and regulatory enforcement timing variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Kids Barefoot Shoes Market
Footwear
Refurbished Sneaker Market
Footwear
Europe Barefoot Shoes Market
Footwear
Formal Shoes Market
Footwear
Women's Sneakers Market
Footwear
Shoe Rental Service Market
Footwear
South America Athletic Footwear Market
Footwear
Sandals Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Men Formal Shoe Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
PVC Footwear Market
Footwear
Slip Resistant Shoes Market
Footwear
Water Shoes Market
Footwear
UK Lifestyle Sneakers Market
Footwear
Europe Footwear Market