
 PU Sole (Footwear Polyurethane) Market | 2026-2036
PU Sole (Footwear Polyurethane) Market Size, Share, and Industry Trends Forecast 2026-2036
PU Sole (Footwear Polyurethane) Market Outlook
Chinese chemical producers is consolidating regional supply of footwear-grade polyurethane systems. Covestro AG leverages its global polymer R&D network to sustain formulation leadership across performance tiers. BASF SE anchors European supply through integrated polyol production at its Ludwigshafen complex. Wanhua Chemical Group Co., Ltd. dominates Asia-Pacific feedstock supply with backward integration into MDI manufacturing.
PU Sole (Footwear Polyurethane) denotes a thermoset or thermoplastic polyurethane layer engineered for footwear ground contact, typically formulated with polyester or polyether polyols reacted with isocyanates to achieve Shore A hardness between 45 and 95, abrasion resistance below 150 mm³, and flex endurance exceeding 150,000 cycles. Injection Molding captures the largest volume share due to cycle-time efficiency in mass production of sports and casual soles. Multi-density configurations represent the fastest-growing product category as brands engineer zonal cushioning for athletic performance. Safety Footwear end-use generates premium margin pools where EN ISO 20345 compliance commands certified compound pricing.
REACH restricts aromatic amine content in PU footwear formulations across Europe, while China's SAMR enforces GB standards limiting solvent residuals in factory emissions. The US EPA and OSHA jointly regulate isocyanate exposure thresholds in domestic molding facilities, elevating capital requirements for new entrants. Stakeholders must monitor evolving biocide restrictions under ECHA review and assess captive compounding investments against third-party supply reliability.
Market Dynamics
Sports footwear brands are consolidating PU sole procurement around lightweight performance midsoles, compressing supplier margins while rewarding compounders with certified multi-density capabilities. REACH compliance timelines and China's GB standards on volatile organic compounds are simultaneously tightening formulation constraints across manufacturing corridors.
Growth Catalysts
- Multi-density midsole engineering:Athletic brands are specifying zonal cushioning configurations that combine Shore A 55 heel sections with Shore A 75 forefoot platforms in single injection cycles. This technical requirement pulls volume toward compounders with dual-hardness metering capability.
- REACH aromatic amine restrictions:The European regulation limits permissible content in finished footwear, creating certified-premium tier pricing for compliant formulations. Brands serving EU distribution channels now mandate REACH documentation upstream.
- Vietnam manufacturing corridor concentration:Footwear production gravity near Ho Chi Minh City is generating localized demand for just-in-time polyol and isocyanate supply. Regional distributors are establishing captive blending facilities to serve this cluster.
Market Restraints
- MDI feedstock volatility:Diphenylmethane diisocyanate pricing swings directly compress compounding margins. Wanhua Chemical's backward integration into MDI manufacturing in China has concentrated upstream supply among a handful of producers.
- EVA substitution in casual segments:Ethylene-vinyl acetate foams are capturing volume in non-performance applications where abrasion resistance below 200 mm³ suffices. This displacement is most pronounced in children's and fashion footwear categories.
- Capital intensity of low-VOC molding:Closed-loop emission capture systems required for GB standard compliance in China demand seven-figure equipment investments. New entrants face barrier-to-entry thresholds that favor incumbent compounders with depreciated asset bases.
Strategic Opportunities
- India PLI scheme for footwear manufacturing:Production-linked incentives are attracting sports brand contract manufacturers to Tamil Nadu and Uttar Pradesh. Local PU system supply remains underdeveloped, creating white space for regional compounders.
- EN ISO 20345 certified safety footwear:Industrial protective footwear mandates across European worksites are generating premium margin pools. Certified compound pricing commands 40-60% premiums over uncertified grades.
- Bio-based polyol convergence with performance tiers:Renewable feedstock polyols are achieving parity with petroleum-based equivalents in Shore A 65-75 ranges. Sustainability-positioned brands are specifying bio-content thresholds in technical agreements.
Industry Challenges
- Isocyanate handling certification gaps:Qualified technicians for TDI and MDI metering systems are scarce in emerging manufacturing clusters. OSHA and EPA joint enforcement in the US has elevated training requirements, creating talent pipeline bottlenecks.
- Multi-density mold flow simulation complexity:Predicting material front progression in zonal hardness configurations requires specialized CAE expertise. Tooling iterations for new athletic platforms extend development timelines by 8-14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PU Sole (Footwear Polyurethane) Market |
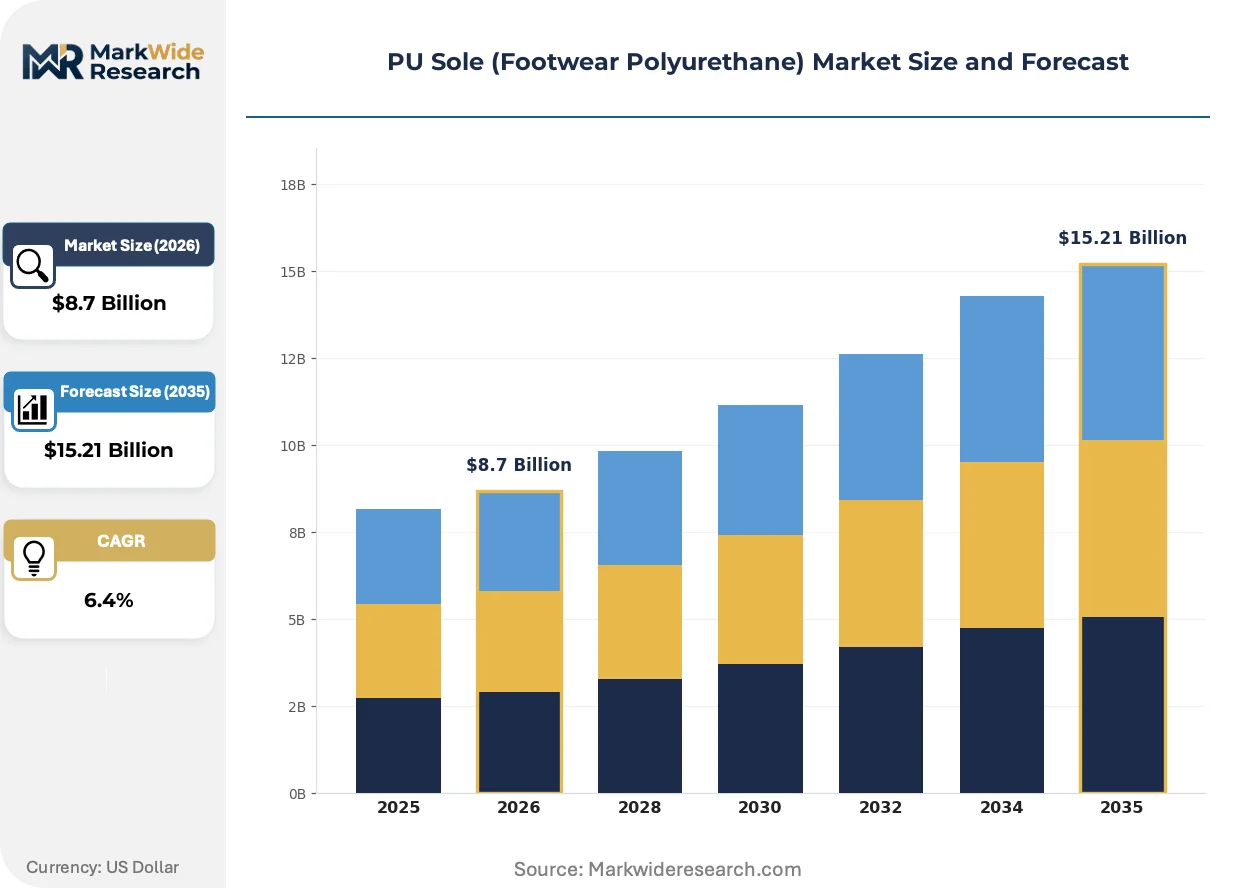
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Compression Molding, Thermoplastic, Multi-density End User: Sports Footwear, Casual Footwear, Formal Footwear, Safety Footwear Application: Footwear Manufacturing, Footbed Production, Outsole Engineering, Accessory Creation Technology: Bonding Technology, Co-extrusion, Thermoforming, Injection Technology |
| Companies Covered | Huntsman Corporation, Coim Group, BASF SE, INOAC Corporation, Lubrizol Corporation, Covestro AG, Wanhua Chemical Group Co., Ltd., Lanxess AG, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PU Sole (Footwear Polyurethane) Market Strategic Shifts
Formulation science and manufacturing process control are converging to enable thinner, lighter sole platforms without sacrificing abrasion resistance. Three developments are actively restructuring competitive capability requirements.
Water-blown microcellular polyurethane is electrifying midsole density targets previously unattainable with physical blowing agents. Running shoe platforms are adopting 0.25-0.32 g/cm³ core densities for energy return optimization. This technology is compressing the performance gap between TPU and EVA foams while maintaining PU's superior flex endurance.
China's GB standards on solvent residuals in factory emissions are forcing compounding facility upgrades across Guangdong and Fujian provinces. The SAMR enforcement timeline requires activated carbon capture or thermal oxidizer installations by specified deadlines. Export-oriented manufacturers serving European and North American brands are accelerating compliance investments ahead of domestic competitors.
Direct-to-sole bonding without primer systems is altering procurement specifications for upper attachment. Athletic footwear engineers are specifying plasma-treated PU surfaces that eliminate adhesive steps. This specification change is most visible in Vietnam-based production for premium running and basketball platforms, where cycle-time reduction justifies material cost premiums.
PU Sole (Footwear Polyurethane) Market Segmentation
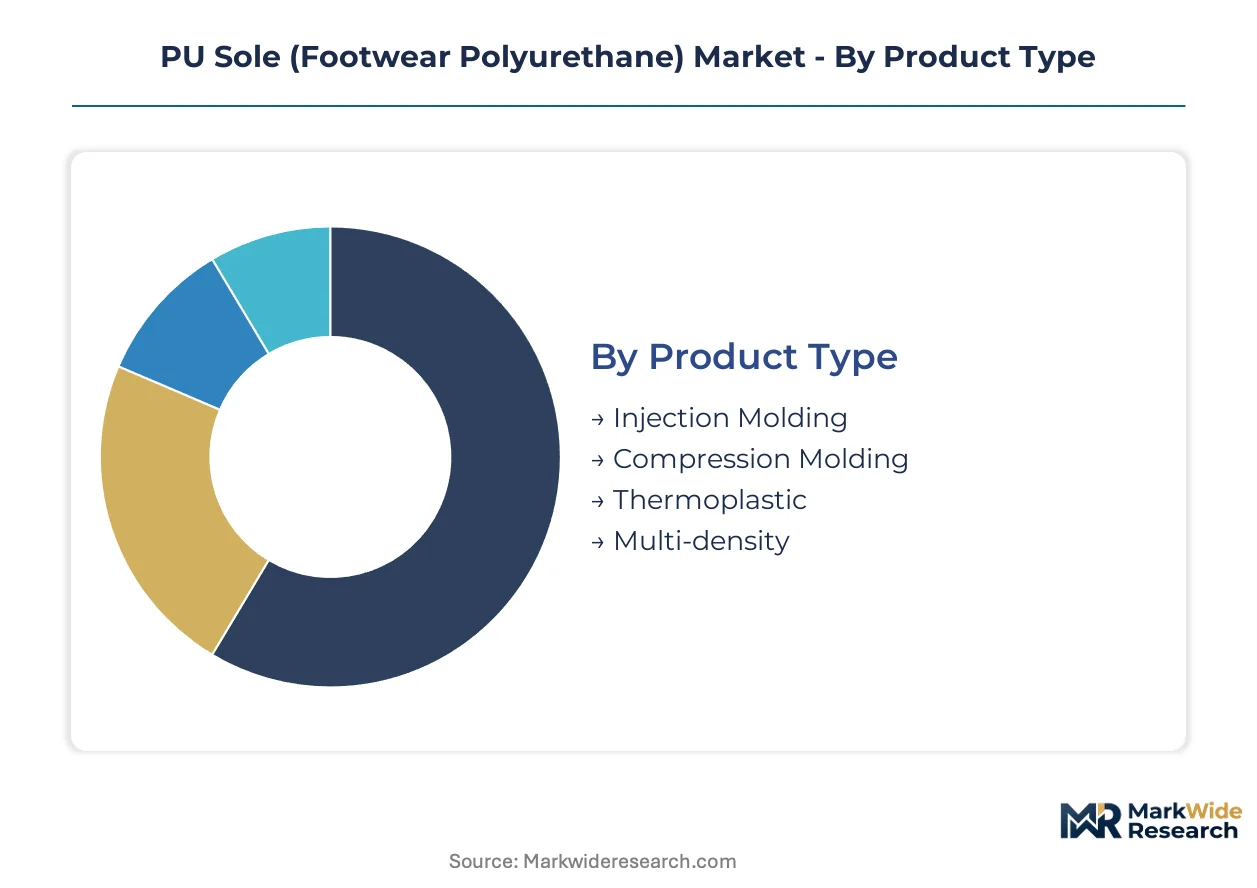
Segmentation in the PU sole market tracks how manufacturing technology, end-use performance requirements, and application specifications create distinct procurement tiers. Each dimension carries different margin structures and compliance burdens that reshape supplier relationships.
Product Type:
Manufacturing technology upgrades drive replacement cycles in molding equipment, with brands refreshing tooling to capture density and weight improvements.
- Injection Molding:Cycle-time efficiency dominates mass production of sports and casual soles through automated metering of polyol-isocyanate blends. Demand concentrates in Vietnam's manufacturing corridor near Ho Chi Minh City, where just-in-time supply chains reward rapid throughput.
- Multi-density:Zonal hardness configurations combine Shore A 55 heel sections with Shore A 75 forefoot platforms in single injection cycles. Athletic brands specify these for energy return optimization, pulling volume toward compounders with dual-hardness metering capability.
- Compression Molding:Lower capital intensity suits smaller batch production of formal and safety footwear with standardized hardness profiles.
- Thermoplastic:Recyclability appeals to sustainability-positioned brands specifying post-industrial regrind content in technical agreements.
Volume placements concentrate in Injection Molding; the faster expansion belongs to Multi-density.
End User:
Cost tier differentiation separates certified premium supply from commodity-grade procurement across footwear categories.
- Sports Footwear:Lightweight performance midsoles with 0.25-0.32 g/cm³ core densities dominate running and basketball platform engineering. Brands compress supplier margins while rewarding compounders with certified multi-density capabilities and REACH documentation.
- Safety Footwear:EN ISO 20345 compliance commands certified compound pricing with 40-60% premiums over uncertified grades. European worksite mandates generate premium margin pools where abrasion resistance below 150 mm³ is mandatory.
- Casual Footwear:EVA substitution pressure is most pronounced here where abrasion resistance below 200 mm³ suffices.
- Formal Footwear:Traditional leather-upper attachment favors compression-molded soles with primer-based bonding systems.
Revenue concentration sits with Sports Footwear; Safety Footwear delivers the steepest margin expansion.
Application:
Application scope determines whether polyurethane functions as structural component or comfort layer in finished footwear.
- Footwear Manufacturing:Complete sole platform production integrates ground contact layers with midsole cushioning in single-source supply relationships.
- Outsole Engineering:Abrasion-resistant formulations achieve Shore A hardness between 45 and 95 with flex endurance exceeding 150,000 cycles for durability-critical placements.
- Footbed Production:Open-cell microcellular structures prioritize moisture management and underfoot comfort over structural load-bearing.
- Accessory Creation:Heel counters, toe puffs, and stabilizer elements utilize thermoplastic polyurethane for shape retention.
Procurement scale favors Footwear Manufacturing; Outsole Engineering is climbing the fastest on performance specification intensity.
Technology:
Customer type segmentation separates brands specifying advanced surface treatment from those accepting conventional adhesive bonding.
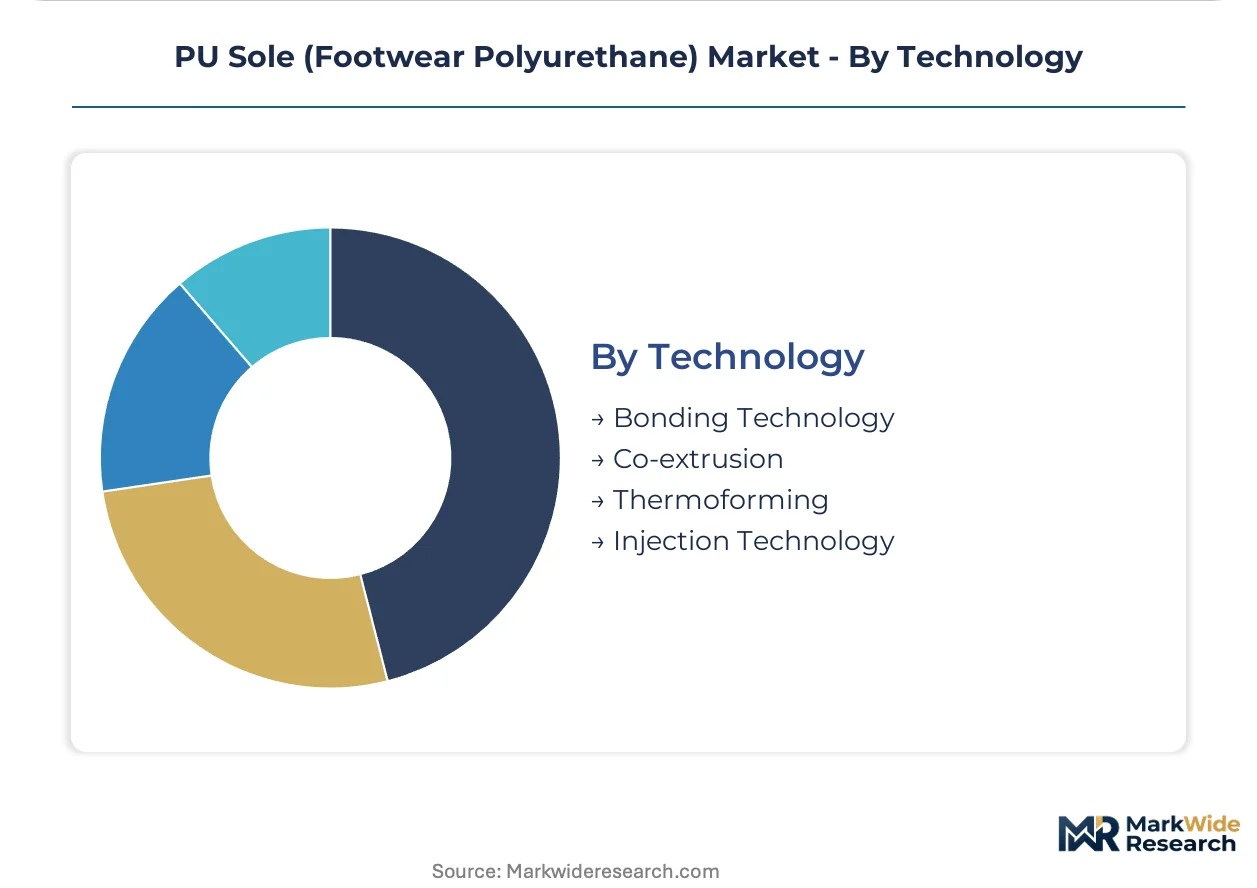
- Bonding Technology:Plasma-treated PU surfaces eliminate primer steps in direct-to-sole upper attachment. Vietnam-based production for premium running and basketball platforms justifies material cost premiums through cycle-time reduction.
- Injection Technology:Water-blown microcellular polyurethane achieves midsole density targets previously unattainable with physical blowing agents.
- Co-extrusion:Multi-material layering combines wear-resistant outsole compounds with cushioned midsole cores in continuous profiles.
- Thermoforming:Sheet-based processing supports low-volume customization and rapid prototyping for fashion footwear iterations.
Deployment scale centers on Injection Technology; Bonding Technology is gaining share fastest among premium athletic specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MDI manufacturing concentration in China's Ningbo and Yantai chemical parks anchors polyurethane feedstock supply for footwear-grade systems. Regional demand patterns track manufacturing corridor development and regulatory enforcement timelines.
China
Guangdong and Fujian provinces host compounding facility upgrades to meet SAMR's GB solvent residual standards. MEE enforcement timelines require activated carbon capture installations by specified deadlines. Export-oriented manufacturers in Dongguan and Quanzhou accelerate compliance investments ahead of domestic competitors.
Vietnam
Ho Chi Minh City's footwear manufacturing corridor generates localized demand for just-in-time polyol supply. Regional distributors establish captive blending facilities to serve this cluster. Sports brand contract manufacturers specify plasma-treated PU surfaces for direct-to-sole bonding.
Germany
REACH aromatic amine restrictions limit permissible content in finished footwear distributed through EU channels. ECHA compliance documentation now mandates upstream certification. BASF SE's Ludwigshafen complex anchors European polyol supply with integrated production.
United States
EPA and OSHA joint enforcement elevates isocyanate handling requirements in domestic molding facilities. New entrants face capital thresholds favoring incumbents with depreciated emission capture assets. Qualified technicians for TDI and MDI metering systems remain scarce.
India
Tamil Nadu and Uttar Pradesh attract sports brand contract manufacturers through PLI scheme incentives. Local PU system supply remains underdeveloped, creating white space for regional compounders. BIS standards for industrial protective footwear generate certified compound demand.
PU Sole (Footwear Polyurethane) Market Competitive Environment
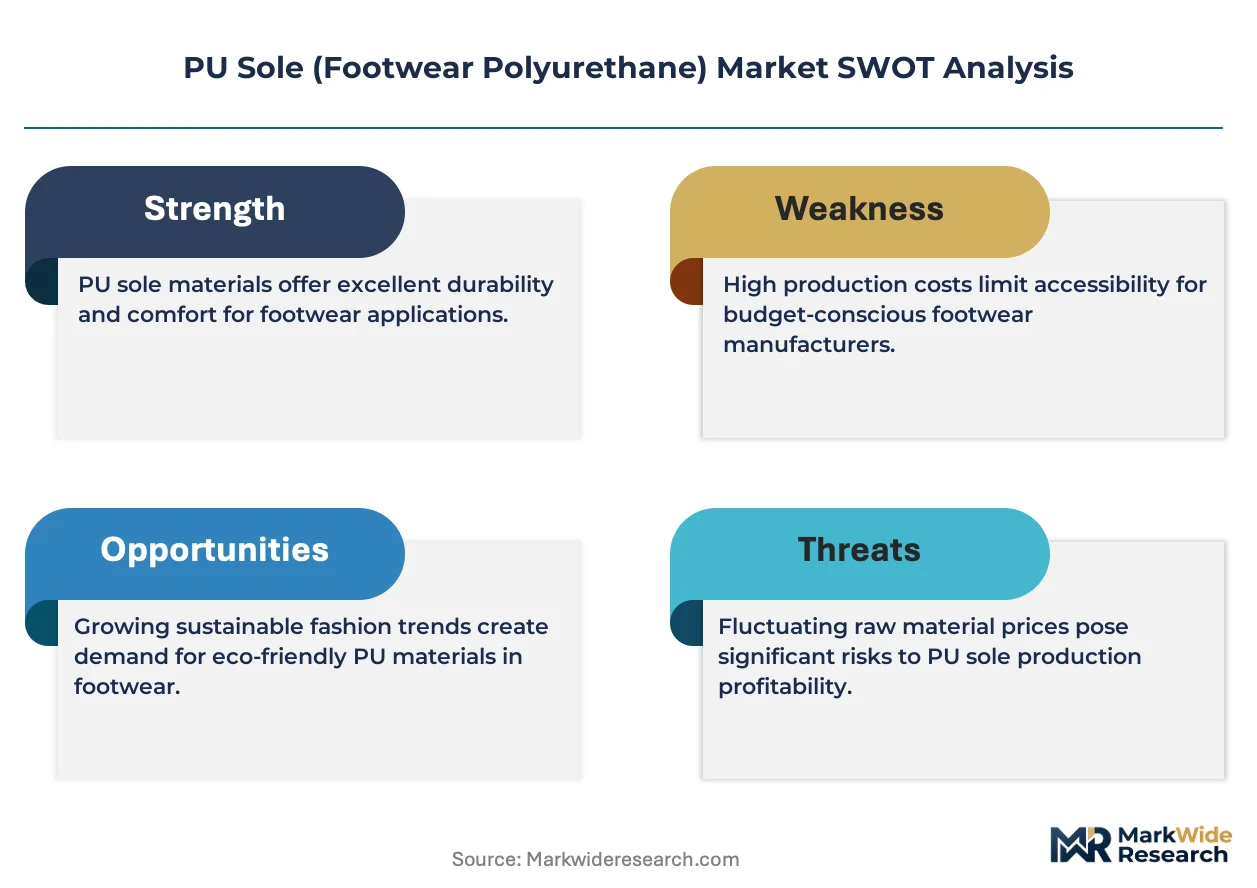
Established producers occupy the standard tier; emerging entrants pursue bio-based formulation differentiation. The supplier base concentrates around integrated chemical conglomerates with captive MDI access and regional compounders serving just-in-time manufacturing clusters. Three archetypes dominate: backward-integrated feedstock suppliers, dual-hardness metering specialists, and sustainability-positioned bio-polyol compounders. Capacity expansion and certified formulation portfolios constitute the dominant competitive moves.
Among German-based chemical conglomerates, BASF SE and Covestro AG exemplify integrated supply archetypes with polyol production anchoring regional networks. Wanhua Chemical Group Co., Ltd. represents the Asia-Pacific feedstock concentration through Ningbo-based MDI manufacturing. These three occupy positions across premium formulation tiers where REACH documentation and multi-density capability separate procurement winners.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Coim Group |
| BASF SE |
| INOAC Corporation |
| Lubrizol Corporation |
| Covestro AG |
| Wanhua Chemical Group Co., Ltd. |
| Lanxess AG |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
Sports brand procurement consolidation around REACH-certified multi-density formulations is compressing supplier margins while elevating premiums for compounders with dual-hardness metering and compliance documentation. This demand-side specification tightening forces supply response through captive blending investments near Vietnam's manufacturing corridor, reshaping pricing power toward integrated feedstock suppliers with backward integration into MDI manufacturing.
Pricing Analysis
After-sales technical support and formulation warranty coverage are increasingly unbundled from base compound pricing, creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on REACH certification status and multi-density capability, with certified compounds commanding substantial premiums over uncertified grades. Pricing pressure stems from EVA substitution in casual segments where abrasion resistance requirements relax. Volume-scale buyers in Vietnam's contract manufacturing cluster exhibit highest price sensitivity, while safety footwear OEMs serving European worksites demonstrate lowest sensitivity due to mandated EN ISO 20345 compliance.
Supply Chain Analysis
Post-industrial regrind flows and thermoplastic polyurethane recycling streams are establishing reverse-logistics infrastructure for sustainability-positioned brands specifying bio-content thresholds. Geographic supply concentration centers on China, Vietnam, and Germany, with MDI feedstock anchored in Ningbo and Yantai chemical parks. Raw material dependencies include diphenylmethane diisocyanate, polyester and polyether polyols, and specialty additives. Single-source vulnerability concentrates around Wanhua Chemical's captive MDI supply. Distribution runs through regional compounders serving just-in-time manufacturing clusters near Ho Chi Minh City and Dongguan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MDI manufacturing capacity concentration among three dominant producers is constraining feedstock availability, propping compound pricing and favoring suppliers with in-house isocyanate production.
For Market Incumbents: To counter EVA foam displacement in non-performance casual segments, BASF SE and Covestro AG should deepen backward integration into specialty polyol production while accelerating water-blown microcellular capacity expansion in Ludwigshafen and Shanghai corridors. Certification investment in EN ISO 20345 and REACH documentation serves as the critical lever for margin defense against Asian commodity compounders. For New Entrants and Emerging Players: Launch via regional blending facilities in India's Tamil Nadu and Uttar Pradesh corridors, where PLI scheme incentives are attracting sports brand contract manufacturers and local PU system supply remains underdeveloped. Target safety footwear certification as the most penetrable premium tier, with bio-based polyol formulations offering differentiation for sustainability-positioned brand procurement. For Investors and Strategic Acquirers: The window for entry favors dual-hardness metering specialists with captive Vietnam corridor access and established plasma-treatment bonding capability. Over the medium-term horizon, acquisition targets should demonstrate REACH documentation infrastructure and multi-density mold flow simulation expertise. Monitor isocyanate handling certification pipeline bottlenecks as the inflection signal for regional supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Manufacturing | Wanhua Chemical's Ningbo complex anchors Asia-Pacific feedstock supply and pricing power. |
| Multi-density Capability Expansion | Dual-hardness metering infrastructure separates premium compounders from commodity suppliers in athletic procurement. |
| REACH Certification Investment | ECHA compliance documentation enables EU distribution channel access for safety footwear compounders. |
| Regional Blending Facility Establishment | Captive compounding near Ho Chi Minh City captures just-in-time supply premiums from sports brands. |
| Bio-based Polyol Formulation Development | Renewable feedstock parity in Shore A 65-75 ranges unlocks sustainability-positioned brand procurement. |
Study Parameters
Document review covered customs and trade data, chemical industry association reports, and SEC regulatory filings, complemented by interviews with plant managers at compounding facilities, procurement leads at sports footwear OEMs, and technical R&D directors at polyol suppliers. Primary fieldwork with distribution channel partners in Vietnam and China validated secondary intelligence on manufacturing corridor development. Bottom-up volume modeling and top-down value triangulation reconciled shipment data with brand procurement specifications across the analysis window.
Segmentation-level outputs reflect modeling across manufacturing technology tiers, end-use performance requirements, and application specifications throughout the forecast period. The analytical framework incorporated density-grade differentiation, certification status premiums, and regional regulatory enforcement timelines. CAGRs were derived from production capacity expansion schedules, brand platform refresh cycles, and substitution elasticity estimates between PU and EVA foams in casual segments.
MDI feedstock price volatility, REACH enforcement timeline acceleration, and EVA substitution rate shifts in children's footwear are the dominant revision risks to modeled outputs. Practitioners should monitor ECHA biocide review proceedings and SAMR GB standard compliance deadlines for early signals of regulatory-driven demand displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Formal Shoes Market
Footwear
US Slip Resistant Shoes Market
Footwear
Football Shoes Market
Footwear
Training Shoes Market
Footwear
Orthopedic Footwear Market
Footwear
Sneaker Identification Service Market
Footwear
Flip Flops Market
Footwear
Kids Barefoot Shoes Market
Footwear
Europe Footwear Market
Footwear
Gypsy Jazz Shoes Market
Footwear
Cyber-Shoes Market
Footwear
South America Athletic Footwear Market
Footwear
Hiking Footwear Market
Footwear
Global Recovery Footwear Market
Footwear
Casual Shoes Market
Footwear
Water Shoes Market