

Sustainable EVTOL Cabin Interior Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable EVTOL Cabin Interior Systems Market Insights
The EU Green Deal's aviation decarbonization targets is realigning material specifications across electric aircraft interiors. Collins Aerospace leverages thermoplastic polymer research to reduce cabin weight fractions. Safran anchors European supply chains through bio-based composite partnerships with airframe integrators. Diehl Aviation specializes in modular seating architectures that simplify end-of-life recycling for fleet operators.
Sustainable EVTOL cabin interior systems comprise lightweight, low-emission assemblies engineered from bio-based composites, recycled aluminum, and natural fiber reinforcements, typically fabricated through resin transfer molding or automated fiber placement to achieve strength-to-weight ratios exceeding conventional aircraft interiors. These systems serve the primary purpose of minimizing energy consumption per passenger-kilometer while satisfying crashworthiness and fire-resistance protocols unique to electric vertical flight. Bio-based composites dominate material procurement due to their stiffness-to-density performance, while seating systems command concentrated margin pools as OEMs prioritize occupant safety integration with battery thermal management zones. Urban air mobility leads application demand, though emergency medical transport segments are expanding fastest as health systems contract dedicated EVTOL fleets.
FAA Part 25 equivalency determinations and EASA SC-VTOL special conditions govern structural fire, smoke, and toxicity standards for EVTOL cabin materials, forcing suppliers to certify beyond conventional transport-category thresholds. REACH restrictions on halogenated flame retardants and the EU F-Gas Regulation on insulating foams further constrain material selection, advantaging European suppliers with pre-qualified sustainable chemistries. Stakeholders must monitor how emerging battery-cell-to-cabin thermal runaway protocols reshape bulkhead and panel specifications before committing to multi-year production tooling.
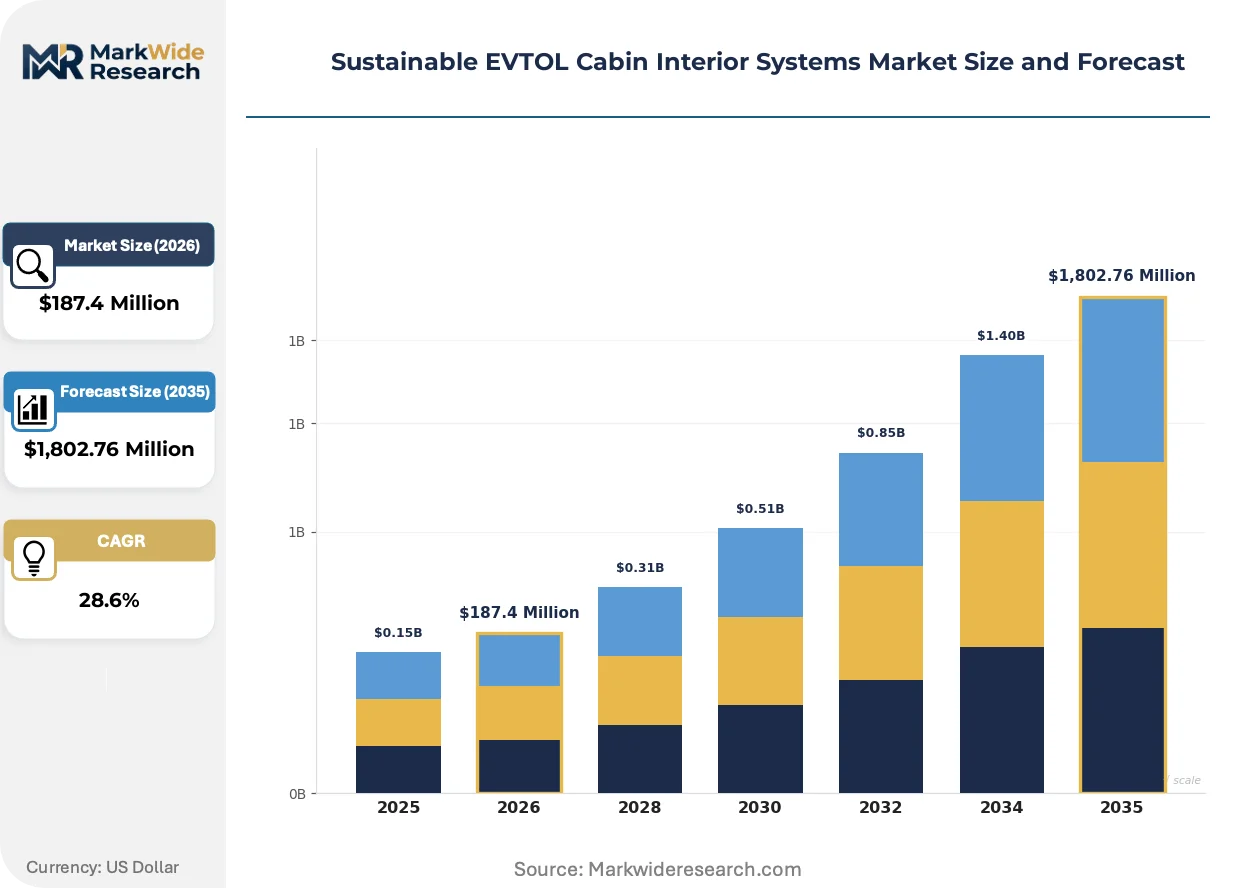
Market Dynamics
The EU Green Deal's aviation decarbonization mandates are compressing material certification timelines, forcing EVTOL cabin suppliers to pre-qualify bio-based composites before airframe integrators finalize production tooling. This regulatory acceleration is restructuring supplier-airframer contracting relationships across the value chain.
Growth Catalysts
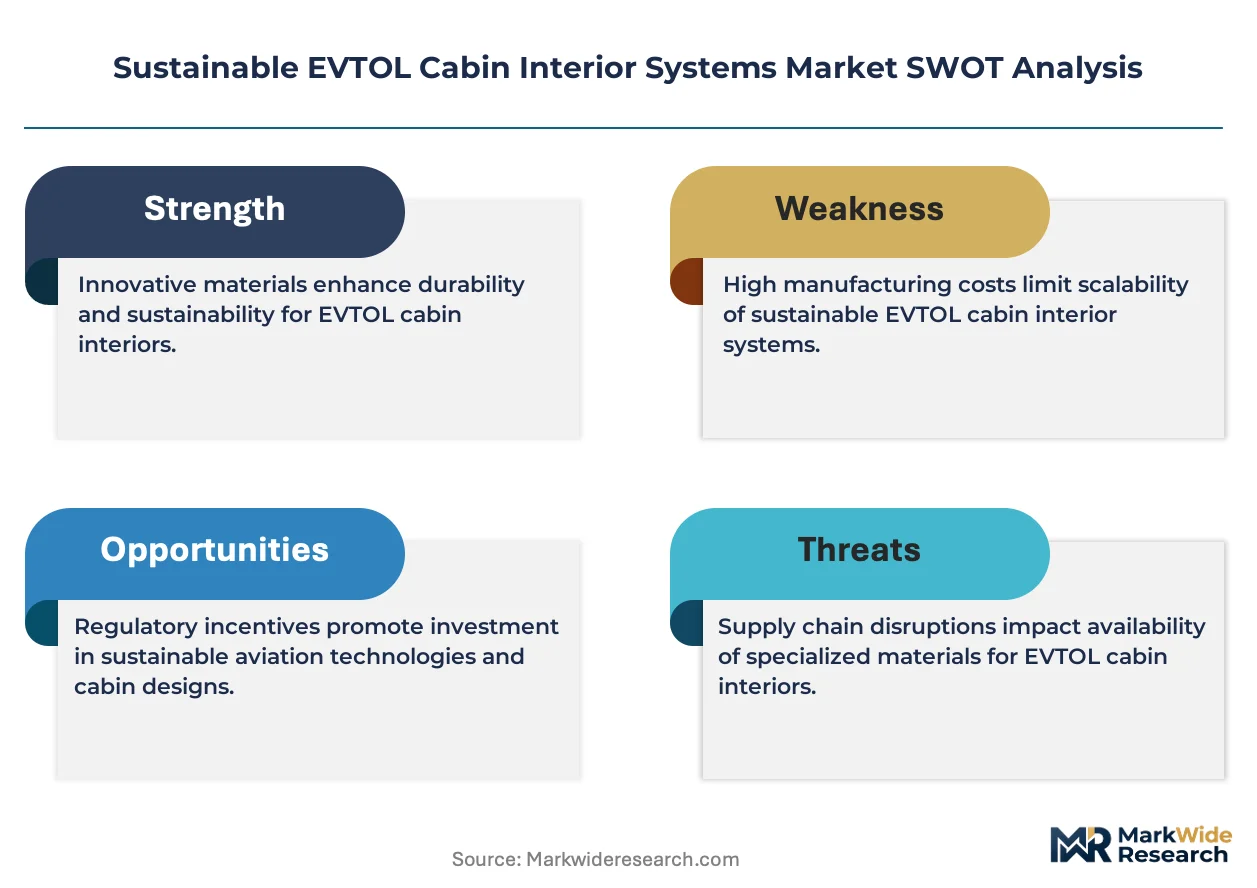
- EASA SC-VTOL Certification Pathway:Special conditions for electric vertical flight create dedicated regulatory lanes that reduce time-to-market for qualified sustainable interior systems compared to traditional Part 25 equivalence routes.
- Urban Air Mobility Fleet Procurement:Commercial operators in Germany and France are bundling cabin interior specifications with airframe purchase agreements, locking in multi-year supply commitments for lightweight seating and panel systems.
- Resin Transfer Molding Scale-Up:Automated fiber placement and out-of-autoclave processing are cutting cycle times for natural fiber-reinforced components, enabling cost parity with conventional thermoset interiors.
Market Restraints
- REACH-Compliant Flame Retardant Scarcity:Restrictions on halogenated chemistries limit qualified additive suppliers to a concentrated European base, creating input bottlenecks for fire-resistant foam and textile specifications.
- Bio-Based Feedstock Price Volatility:Flax and hemp fiber costs fluctuate with agricultural commodity cycles, compressing margin stability for composite panel manufacturers dependent on natural reinforcements.
- Single-Source Pre-Preg Concentration:Automated fiber placement systems rely on thermoplastic pre-impregnated tapes produced by a narrow German and Austrian supplier base, exposing procurement to geographic concentration risk.
Strategic Opportunities
- Emergency Medical Transport Contracts:Health systems in Italy and Spain are issuing dedicated EVTOL fleet tenders that specify crashworthy cabin interiors with integrated patient monitoring mounting points.
- EU F-Gas Regulation Exemption Pathways:Vacuum insulation panels using non-fluorinated aerogels qualify for accelerated approval, creating first-mover advantage for thermal management system suppliers.
- Modular Seating-to-Battery Integration:Converging occupant safety and thermal runaway containment specifications are opening design contracts for bulkhead-integrated seating architectures that simplify airframe assembly.
Industry Challenges
- Multi-Physics Simulation Talent Gap:Cabin suppliers struggle to recruit engineers capable of modeling simultaneous crash, fire, and electromagnetic interference scenarios unique to battery-proximate interior zones.
- Tooling Amortization Compression:Low initial production volumes for emerging EVTOL platforms extend payback periods for automated fiber placement mandrels and resin transfer molds beyond typical capital planning horizons.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable EVTOL Cabin Interior Systems Market Trends and Innovations
Thermoplastic polymer systems are displacing thermoset epoxies across load-bearing cabin structures, driven by recyclability mandates and processing speed advantages. Material qualification protocols are compressing as regulators develop EVTOL-specific test standards.
Natural fiber-reinforced composites using flax and hemp bast fibers are consolidating their position as the primary sustainable alternative to glass fiber in non-structural panels. Urban air mobility operators in Germany and the Netherlands are specifying these materials in fleet procurement guidelines. The technology is consolidating supplier bases around vertically integrated fiber processors who control cultivation through molding operations.
REACH restrictions on halogenated flame retardants are eliminating legacy chemistries from cabin textile and foam specifications. European suppliers with pre-qualified phosphorus-based and intumescent systems are capturing specification lock-in from airframe integrators. The regulation is forcing North American suppliers to reformulate product lines for European market access, creating transatlantic regulatory divergence in material portfolios.
Buyer consolidation among urban air mobility fleet operators is compressing supplier negotiation leverage and unbundling aftermarket service contracts from initial equipment sales. Direct procurement relationships between Volocopter and Lilium with tier-two cabin specialists are displacing traditional distributor channels. This concentration is most visible in German and French procurement patterns, where fleet-scale operators command custom specification development.
Sustainable EVTOL Cabin Interior Systems Market Segmentation
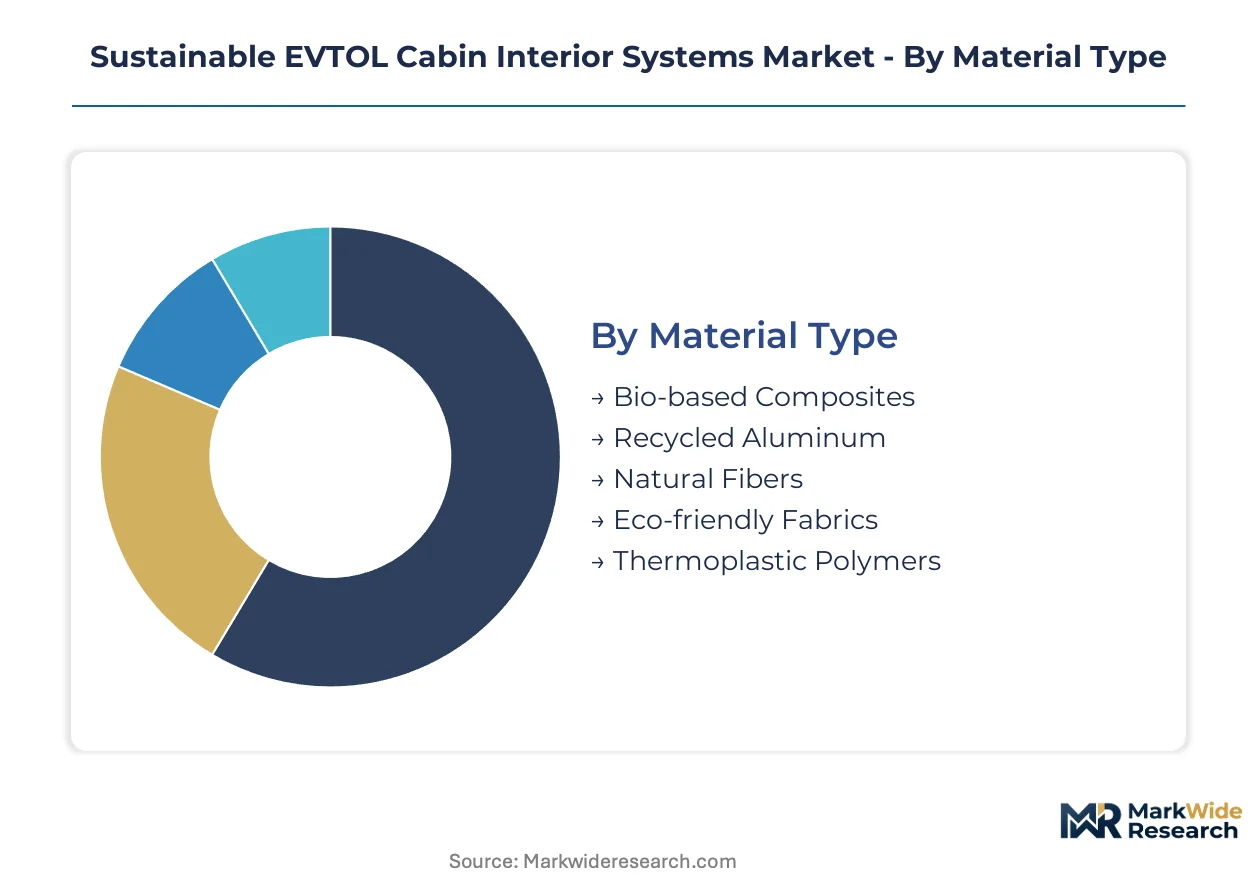
EVTOL cabin interior procurement fragments across material chemistries, component architectures, and operational use cases. Fleet operators in Germany and France are consolidating specifications around certified sustainable systems that satisfy EASA SC-VTOL special conditions.
Material Type:
Customization intensity varies sharply across this category, from commodity-recycled metals to purpose-engineered bio-resins requiring airframe-specific qualification cycles.
- Bio-based Composites:Flax and hemp bast fibers embedded in bio-epoxy matrices deliver stiffness-to-density ratios exceeding glass fiber alternatives. Urban air mobility fleet operators in the Netherlands specify these materials in procurement guidelines to satisfy EU Green Deal emissions benchmarks. REACH-compliant resin systems remain bottlenecked to pre-qualified European suppliers.
- Recycled Aluminum:Aerospace-grade 6xxx and 7xxx series alloys recovered from decommissioned commercial aircraft serve structural seat rails and floor tracks. German OEMs anchor procurement through closed-loop partnerships with specialized secondary smelters.
- Natural Fibers:Unidirectional flax tapes processed through automated fiber placement enable non-structural panel production with 40% lower embodied carbon than synthetic reinforcements.
- Eco-friendly Fabrics:Recycled PET and bio-polyester textiles treated with phosphorus-based flame retardants replace halogenated legacy specifications banned under REACH.
- Thermoplastic Polymers:PEEK and PPS formulations enable out-of-autoclave processing and end-of-life recyclability for high-load cabin components.
Leading the category by volume: Bio-based Composites. Expanding most quickly: Thermoplastic Polymers.
Component:
Margin concentration tracks integration complexity, with systems requiring simultaneous crashworthiness and thermal management commanding premium positioning.
- Seating Systems:Modular architectures integrate 16g dynamic test compliance with battery proximity thermal runaway containment. Diehl Aviation and Safran compete for specification lock-in from Volocopter and Lilium production programs.
- Cabin Panels:Natural fiber-reinforced sandwich structures with phenolic or bio-epoxy skins replace thermoset legacy systems in sidewall and ceiling applications.
- Overhead Bins:Thermoplastic composite shells with integrated mounting rails reduce part count versus metal-stamped alternatives.
- Flooring Systems:Honeycomb-core panels with recycled aluminum facesheets satisfy floor beam loading requirements at sub-conventional weights.
- Lighting Fixtures:OLED and LED assemblies housed in bio-based housings address fire-smoke-toxicity protocols without halogenated additives.
Capturing the steepest margin expansion: Seating Systems. Volume concentration: Cabin Panels.
Application:
Operational tempo and payload flexibility differentiate procurement specifications across mission profiles.
- Urban Air Mobility:High-frequency shuttle operations prioritize rapid-turn cabin durability and passenger density maximization. German fleet operators bundle interior specifications with airframe purchase agreements.
- Air Taxi Services:Premium-configured cabins with reduced seat counts emphasize passenger experience metrics over utilitarian efficiency.
- Emergency Medical Transport:Italian and Spanish health systems issue dedicated fleet tenders specifying crashworthy interiors with integrated patient monitoring mounting points and stretcher restraint systems.
- Corporate Transport:Custom-configured executive cabins require extended lead times for bespoke material finishing and connectivity integration.
- Tourism Flights:Scenic operators prioritize panoramic window integration and reduced interior weight for extended hover endurance.
Commanding current procurement volume: Urban Air Mobility. Climbing the fastest: Emergency Medical Transport.
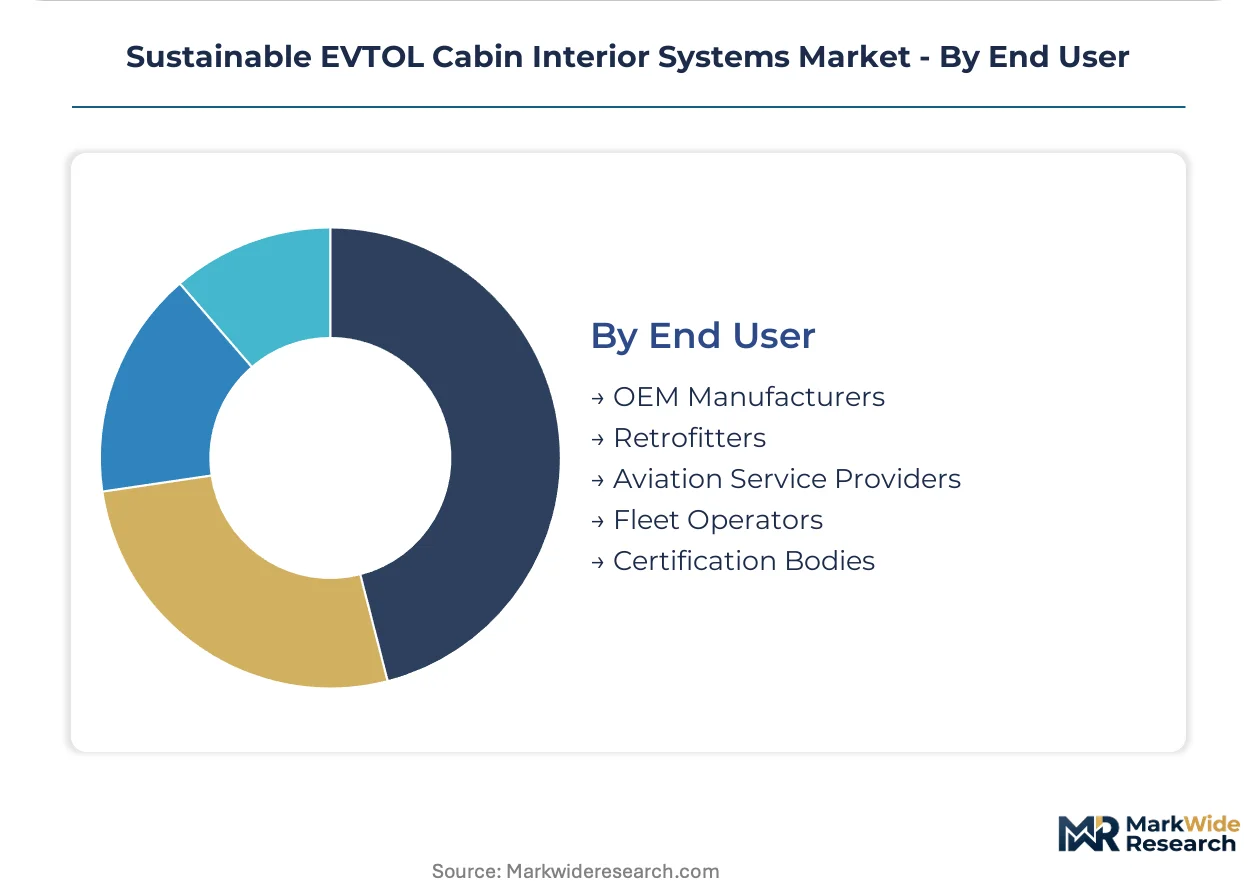
End User:
Contracting authority and certification liability distribute differently across build-phase versus operational-phase stakeholders.
- OEM Manufacturers:Airframe integrators retain specification authority for type-certified interior configurations, locking in multi-year supply commitments with tier-two specialists.
- Retrofitters:Post-delivery modification providers face compressed qualification timelines when adapting certified interiors to emerging battery thermal runaway protocols.
- Aviation Service Providers:Maintenance organizations control aftermarket parts procurement for cabin refresh cycles and damage repair.
- Fleet Operators:Urban air mobility consolidators in France and Germany unbundle service contracts from initial equipment sales to optimize lifecycle cost.
- Certification Bodies:EASA and FAA equivalency determinations govern material approval lists that constrain supplier selection for all other end-user categories.
Holding specification authority: OEM Manufacturers. Gaining procurement leverage: Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European EVTOL cabin supply chains through Diehl Aviation's composite manufacturing campus and Safran's research partnerships with Technical University of Munich. German procurement patterns cascade across neighboring jurisdictions as EASA SC-VTOL certification timelines compress material qualification windows.
Germany
Urban air mobility fleet operators in Bavaria and Baden-Württemberg bundle sustainable interior specifications with airframe purchase agreements. EU Green Deal aviation decarbonization targets tighten embodied carbon thresholds for cabin materials entering type certification. Stuttgart's aerospace cluster concentrates automated fiber placement capacity for natural fiber-reinforced thermoplastic components.
France
Air taxi operators in the Île-de-France region issue dedicated tenders for lightweight seating systems with integrated battery thermal management. REACH restrictions on halogenated flame retardants eliminate legacy chemistries from textile specifications, advantaging domestic suppliers with pre-qualified phosphorus-based alternatives. Toulouse's aeronautical ecosystem anchors bio-based composite development through partnerships between Safran and regional research institutes.
United States
FAA Part 25 equivalency determinations for electric vertical flight create parallel certification tracks that extend material approval timelines versus EASA pathways. Urban air mobility ventures in California and Texas procure cabin interiors through direct supplier relationships that bypass traditional distributor channels. Seattle's aerospace engineering base supplies multi-physics simulation talent for crash-fire-electromagnetic interference modeling.
Italy
Emergency medical transport contracts from Lombardy and Emilia-Romagna health systems specify crashworthy interiors with stretcher restraint integration and patient monitoring mounting points. National procurement frameworks align with EU F-Gas Regulation exemptions for non-fluorinated aerogel insulation in thermal management systems. Turin's automotive composite expertise migrates into EVTOL cabin panel production through supplier diversification.
Netherlands
Urban air mobility operators in the Randstad specify flax fiber-reinforced composites in fleet procurement guidelines to satisfy circular economy mandates. Agricultural cooperatives in the Northern Netherlands supply bast fiber feedstocks to vertically integrated processors controlling cultivation through molding operations. Eindhoven's high-tech systems cluster develops out-of-autoclave processing equipment for natural fiber thermoplastic components.
Sustainable EVTOL Cabin Interior Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and thermal management integration depth. The supplier base organizes into three tiers: airframe-integrated system architects, component specialists with EASA pre-qualification, and commodity panel fabricators. Dominant competitive moves include strategic partnerships for resin transfer molding scale-up and geographic expansion into Italian and Spanish emergency medical transport markets.
Within the system architect tier, Collins Aerospace and Safran occupy positions defined by thermoplastic polymer research depth and bio-based composite partnerships with European airframe integrators. Diehl Aviation anchors the modular seating specialization vector through Bavaria-based engineering capacity. Among natural fiber composite specialists, Bcomp exemplifies vertical integration from agricultural feedstock through automated fiber placement processing.
| Leading Market Players |
|---|
| Collins Aerospace |
| Diehl Aviation |
| Safran |
| RECARO Aircraft Seating |
| FACC AG |
| JAMCO Corporation |
| Panasonic Avionics Corporation |
| Thales |
| Bcomp |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal aviation decarbonization benchmarks gate qualified supply access and premium-tier pricing power for sustainable EVTOL cabin interior systems. Airframe integrators in Germany and France pay material certification premiums to suppliers with pre-qualified bio-based composite portfolios, while REACH-compliant flame retardant scarcity compresses margin pools for second-tier panel fabricators lacking chemistry partnerships.
Pricing Analysis
Certification-attached pricing anchors value capture in this market, with EASA SC-VTOL pre-qualified systems commanding substantial premiums over uncertified alternatives. Price differentiation tracks REACH-compliant chemistry access and automated fiber placement capability, with German and Austrian suppliers capturing margin expansion. Cost compression in natural fiber-reinforced panels intensifies as flax and hemp feedstock volatility feeds through to composite manufacturers. Fleet operators exhibit highest price sensitivity for commodity cabin panels, while emergency medical transport buyers prioritize crashworthiness integration over unit economics.
Supply Chain Analysis
EU F-Gas Regulation domestic-content requirements reshape sourcing patterns for thermal management system suppliers seeking exemption pathways. Feedstock concentration centers on Germany, France, and the Netherlands for bast fiber cultivation and automated fiber placement capacity. Raw material dependencies include flax and hemp agricultural supply, thermoplastic pre-impregnated tapes, and phosphorus-based flame retardant chemistries. Single-source pre-preg concentration in southern Germany exposes procurement to geographic concentration risk. Distribution runs through direct contracting relationships between airframe integrators and tier-two cabin specialists, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a materials-transition phase as thermoplastic polymers displace thermoset epoxies across load-bearing cabin structures. Bio-based composite qualification cycles and out-of-autoclave processing scale-up define competitive positioning across the forecast horizon.
For Market Incumbents: Cement specification lock-in through multi-year resin transfer molding capacity commitments with Bavarian and Baden-Württemberg airframe integrators. Deepen backward integration into flax fiber cultivation partnerships with Dutch agricultural cooperatives to buffer feedstock volatility. Threats from emerging thermoplastic specialists with out-of-autoclave processing advantages require accelerated R&D in natural fiber-reinforced PEEK formulations. For New Entrants and Emerging Players: Enter via Italian and Spanish emergency medical transport fleet tenders, where crashworthy interior specifications with integrated patient monitoring mounting points remain underpenetrated by incumbent seating specialists. White-space exists in non-fluorinated aerogel vacuum insulation panels qualifying for EU F-Gas Regulation exemptions. Go-to-market leverage centers on Turin automotive composite expertise migrating into EVTOL cabin panel production. For Investors and Strategic Acquirers: EASA SC-VTOL special condition publication timelines are the leading indicator that certification-pre-qualified supplier bases will consolidate ahead of production ramp decisions. Long-term viability favors vertically integrated natural fiber processors controlling cultivation through molding operations. Acquisition targets include mid-cap specialists with automated fiber placement capacity and pre-qualified phosphorus-based flame retardant portfolios. Watch battery-cell-to-cabin thermal runaway protocol finalization as the inflection signal reshaping bulkhead and seating architecture specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Transfer Molding Scale-Up | Automated fiber placement investments by Diehl Aviation and Safran compress cycle times for natural fiber-reinforced components. |
| Bio-Based Composite Partnership | Airframe integrators lock multi-year supply commitments with Bcomp and European fiber processors for EU Green Deal compliance. |
| Emergency Medical Transport Specification | Italian and Spanish health system tenders create dedicated revenue streams for crashworthy interior specialists. |
| REACH-Compliant Chemistry Investment | Phosphorus-based flame retardant qualification secures textile and foam specification lock-in from EASA-aligned integrators. |
| Modular Seating-to-Battery Integration | Converging safety and thermal management specifications open design contracts simplifying airframe assembly for Volocopter and Lilium. |
Research Methodology
Independent corroboration across EASA certification documentation, EU F-Gas Regulation exemption filings, and REACH-compliant chemical supplier registries underwrites the qualitative findings in this analysis. Primary interviews with EVTOL airframe procurement directors, cabin system engineering leads, composite manufacturing plant managers, and fleet operator sustainability officers combined with secondary validation from EASA SC-VTOL special condition drafts, EU Green Deal aviation decarbonization impact assessments, and bast fiber agricultural cooperative production data. Bottom-up segment sizing and top-down market triangulation cross-checked against automated fiber placement capacity announcements and resin transfer molding investment disclosures.
Comparable-period anchoring to historical aviation interior certification timelines and electric aircraft program development cycles structured the forecast window across the analysis window. Segmentation modeling incorporated material chemistry tiers, component integration complexity, operational application mission profiles, and end-user contracting authority dimensions. CAGRs derived from production volume build-up curves tied to airframe integrator delivery schedules and fleet operator procurement commitments. Industry-specific inputs included EASA SC-VTOL special condition implementation timelines and EU F-Gas Regulation exemption pathway qualification rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under battery thermal runaway protocol revisions or REACH flame retardant restriction expansions. Forecasts reflect assumptions around certification timeline compression and natural fiber feedstock supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.