
 Commercial Aircraft Floor Panels Market | 2026-2036
Commercial Aircraft Floor Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Floor Panels Market Outlook
EASA CS-25 Appendix F flammability qualification is unwinding the competitive landscape for interior panel suppliers. Collins Aerospace leverages its vertical integration across thermoplastic composites and metallic substructures to sustain program awards on Airbus and Boeing platforms. Hexcel Corporation anchors the prepreg supply chain for honeycomb-core sandwich panels, while Safran competes through its specialization in integrated cabin systems that bundle flooring with sidewalls and stowage.
Commercial aircraft floor panels are structural-interior components, typically fabricated as sandwich assemblies with aluminum or aramid-fiber honeycomb cores bonded to glass-phenolic or epoxy-glass face sheets, engineered to withstand 9g forward inertia loads while minimizing mass per unit area. Their primary purpose is to provide a stable, fire-resistant walking and cargo-bearing surface that integrates with seat tracks, monuments, and emergency egress paths. Composite material types command the dominant share of new-build demand due to weight advantages over legacy aluminum constructions, while the passenger application segment generates the deepest margin pools as custom interiors and premium cabin reconfigurations multiply. The OEM end-user channel leads volume, though maintenance providers represent the fastest-growing category as aging-fleet retrofit cycles compress.
FAA Part 25.853 flammability standards, EASA CS-25 certification requirements, and ISO 2685 fire-containment test protocols collectively dictate material selection, testing cadence, and supplier qualification timelines for floor panel manufacturers. These frameworks elevate barriers for uncertified entrants while creating recurring revenue streams for incumbents as airworthiness directives mandate periodic material upgrades. Stakeholders must monitor evolving sustainable-aviation regulations that will likely extend to cabin interiors, forcing early decisions on recyclable core materials and bio-based resin systems.
Market Dynamics
Lightweight sandwich-construction panels are displacing legacy aluminum flooring across narrow-body retrofits and OEM line-fit programs, driven by FAA flame-resistance mandates and EASA CS-25 certification thresholds that reward mass reduction without compromising 9g load integrity.
Growth Catalysts
- FAA Part 25.853 flammability mandates:Airworthiness directives force aging-fleet operators toward thermoset composite replacements, expanding addressable demand for certified panel suppliers.
- Aramid-fiber honeycomb cores:These materials deliver specific strength advantages that OEMs prioritize for new-build single-aisle platforms, accelerating specification wins against metallic alternatives.
- Germany's aerospace manufacturing cluster:Concentrated tier-1 supplier ecosystems around Hamburg and Munich compress logistics costs and qualification timelines for European airframer programs.
Market Restraints
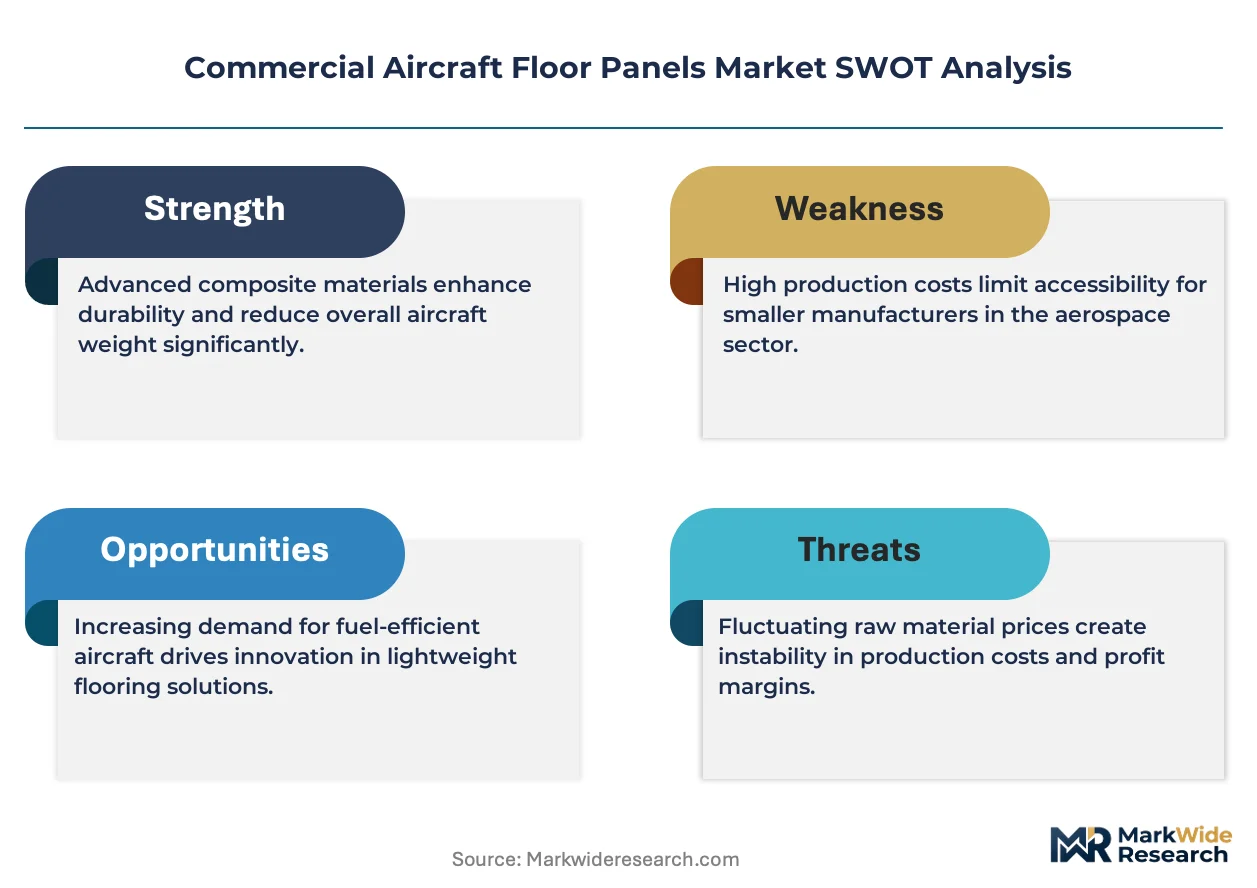
- Epoxy resin price volatility:Petrochemical feedstock fluctuations compress margins for prepreg manufacturers locked into long-term airframe supply agreements.
- Single-source honeycomb dependency:North American aramid-core production concentrates among limited qualified vendors, creating supply vulnerability for sandwich-panel fabricators.
- ISO 2685 fire-containment testing:Extended certification cycles delay new material introductions, freezing out innovative core technologies from near-term program awards.
Strategic Opportunities
- India's MRO expansion:Maintenance providers in Bengaluru and Hyderabad are retrofitting legacy narrow-body fleets, creating aftermarket demand for lightweight replacement panels.
- Bio-based phenolic resins:Sustainable-aviation regulatory pressure is forcing early qualification of recyclable face-sheet chemistries that differentiate suppliers on environmental metrics.
- Direct airframer contracting:Tier-1 suppliers are bypassing distributors to capture program-level engineering relationships and multi-year volume commitments.
Industry Challenges
- Composite technician scarcity:Qualified bonding and autoclave operators are concentrated at legacy aerospace hubs, constraining capacity expansion for new market entrants.
- Dual-certification burden:Simultaneous FAA and EASA qualification demands duplicate testing expenditure and extend time-to-revenue for modified panel designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Floor Panels Market |
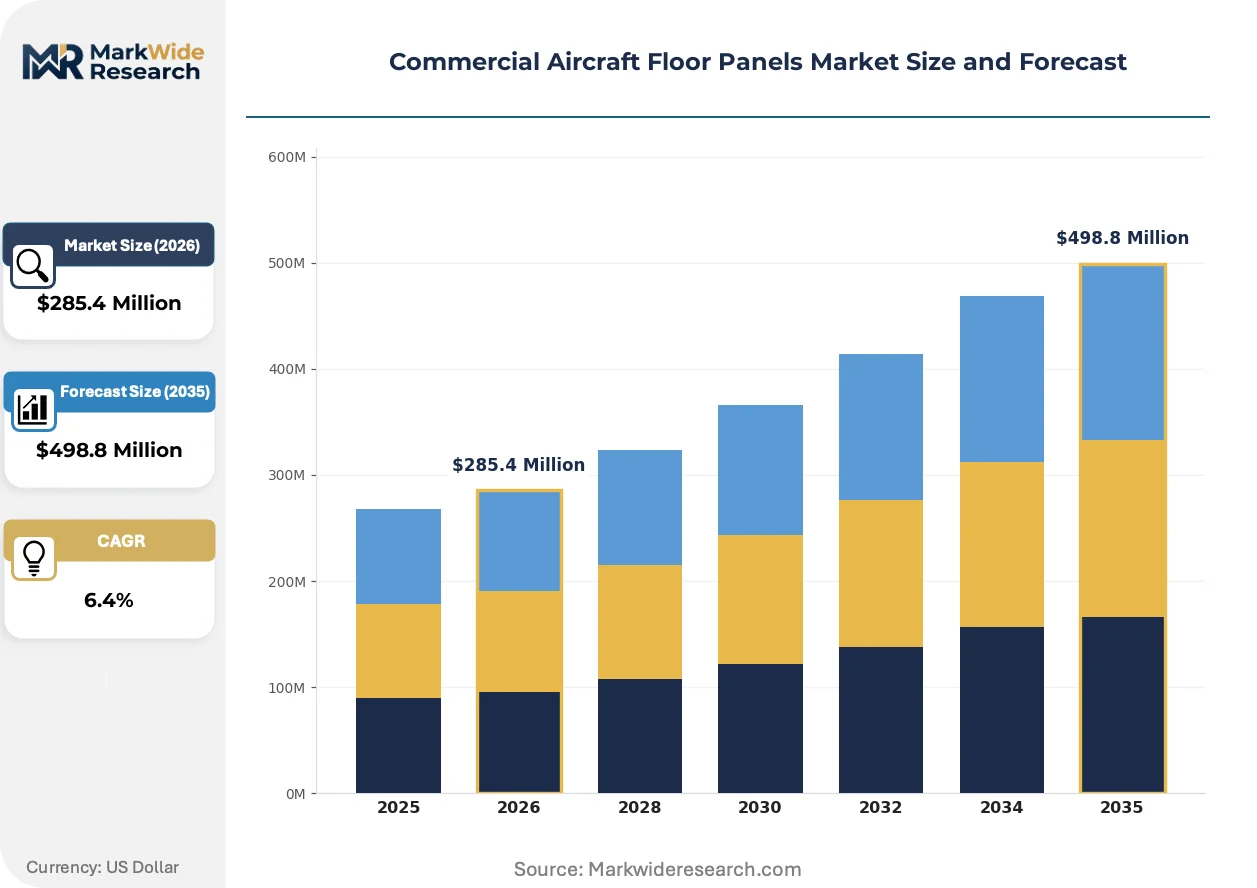
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $498.8 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Composite, Steel, Titanium Application: Cargo, Passenger, Military, Business Jet Manufacturing Process: Machining, Molding, Assembly, Welding End User: OEMs, Airlines, Maintenance Providers, Contractors |
| Companies Covered | The Gill Corporation, Collins Aerospace, Triumph Group, Safran, Hexcel Corporation, Singapore Technologies Engineering, Latecoere, EFW GmbH, Lufthansa Technik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Floor Panels Market Strategic Shifts
Thermoplastic composite processing and automated fiber placement are compressing fabrication cycle times while regulatory pressure on cabin fire safety intensifies material-performance requirements.
Thermoplastic resin systems for floor panel face sheets are miniaturizing the gap between metallic and composite structural performance. Airbus and Boeing procurement teams are specifying these materials for next-generation single-aisle programs at accelerating volume. The technology is miniaturizing the weight-penalty differential that previously favored aluminum in high-load cargo applications.
EASA CS-25 Appendix F flammability amendments are tightening smoke-density and heat-release thresholds for interior materials. European airframers are requalifying entire supply chains to meet revised certification baselines. Narrow-body OEM programs face the steepest compliance cost escalation as they balance retrofit timelines against new-build specifications.
Airline procurement departments are consolidating vendor relationships around full-cabin system integrators rather than discrete component suppliers. Maintenance providers and retrofit specialists are losing direct specification influence to airframer engineering teams. This concentration is most visible in the United States, where American Airlines and Delta Air Lines have centralized interior configuration authority with Boeing and Airbus program offices.
Commercial Aircraft Floor Panels Market Segmentation
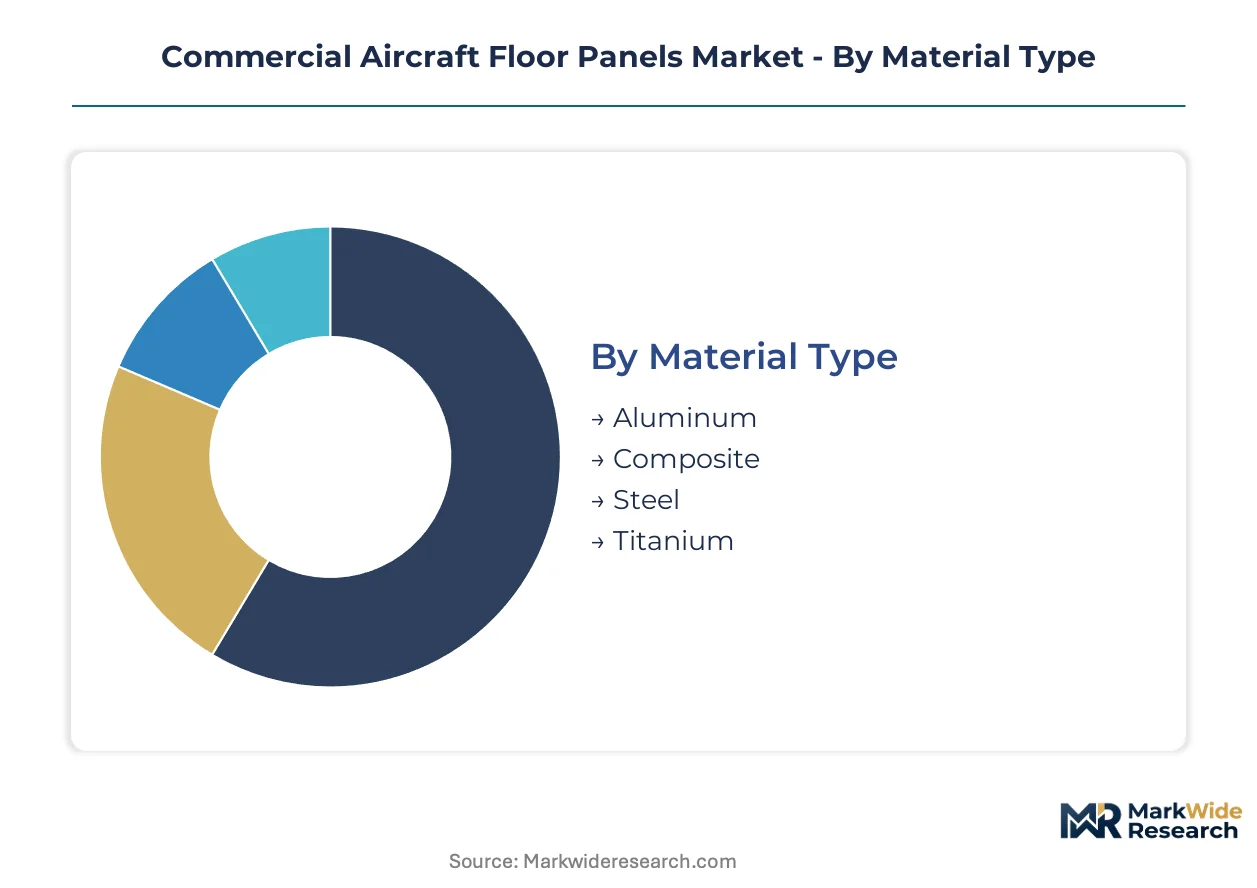
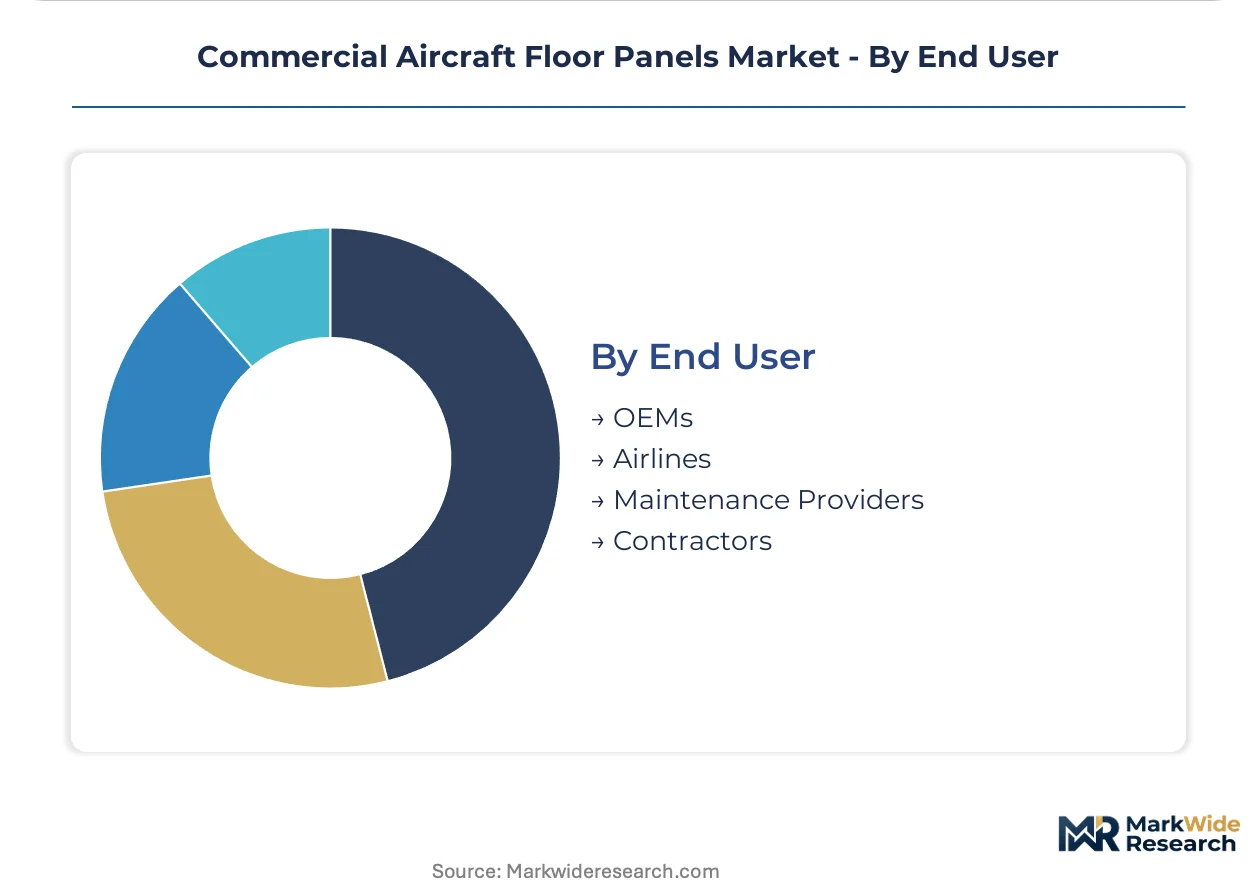
Floor panel procurement splits sharply across material certification grades, application load requirements, and end-user technical capabilities. Each segmentation axis carries distinct regulatory burdens and margin structures that reshape supplier positioning.
Material Type:
FAA Part 25.853 and EASA CS-25 Appendix F create divergent qualification timelines across metallic and non-metallic constructions.
- Composite:Sandwich constructions with aramid-fiber honeycomb cores and glass-phenolic face sheets dominate new-build narrow-body programs. Boeing and Airbus procurement teams specify these materials for single-aisle line-fit installations where 9g load integrity must pair with mass reduction targets.
- Aluminum:Legacy honeycomb-core panels with aluminum face sheets persist in cargo applications and aging-fleet retrofits where fire-resistance mandates permit grandfathered constructions. Maintenance providers in Germany and the United States stock these for replacement cycles on older narrow-body fleets.
- Steel:High-strength alloy panels serve specialized military transport applications requiring ballistic tolerance and extreme load-bearing capacity beyond commercial 9g standards.
- Titanium:Premium-grade panels address business jet and VIP conversion markets where specific strength ratios justify material cost premiums for ultra-long-range platforms.
Established volume favors aluminum; emerging adoption favors composite.
Application:
Load-case severity and passenger exposure duration determine certification stringency and replacement frequency across installation zones.
- Passenger:Floor panels in the cabin zone must integrate with seat tracks, monuments, and emergency egress paths while meeting the strictest smoke-density thresholds. Airlines in France and Germany drive specification for premium cabin reconfigurations that multiply custom interior demand.
- Cargo:Lower-deck and freighter applications prioritize concentrated load distribution over walking-surface comfort, permitting heavier constructions. EASA fire-containment protocols for Class C cargo compartments are tightening material selection for converted narrow-body freighters.
- Military:Tactical transport platforms demand panels with enhanced puncture resistance and rapid-field-replaceability features absent from commercial specifications.
- Business Jet:Ultra-lightweight sandwich panels with thermoplastic face sheets are gaining specification in long-range business aircraft where every kilogram translates to range extension.
Passenger applications concentrate margin pools; cargo installations expand most quickly through e-commerce-driven freighter conversions.
Manufacturing Process:
Process selection locks suppliers into distinct capital intensity tiers and airframer relationship structures.
- Assembly:Bonding and fastening of honeycomb-core sandwich panels represents the dominant production mode for tier-1 suppliers serving Airbus and Boeing. Autoclave curing cycles and adhesive qualification protocols create steep barriers for new entrants.
- Molding:Compression and resin-transfer molding of thermoplastic composite face sheets is compressing fabrication times for next-generation single-aisle programs. Automated fiber placement systems are displacing manual layup in high-volume panel production.
- Machining:Precision milling of metallic core structures and edge profiles serves legacy aluminum panel refurbishment and military platform sustainment.
- Welding:Fusion joining of titanium and steel subcomponents addresses niche high-performance applications where adhesive bonding fails thermal or load requirements.
Assembly commands program-level relationships; molding is climbing the fastest as thermoplastic adoption accelerates.
End User:
Technical authority over specification varies dramatically between airframer engineering teams and aftermarket decision-makers.
- OEMs:Boeing and Airbus program offices wield direct specification authority for line-fit installations, consolidating vendor relationships around full-cabin system integrators rather than discrete component suppliers.
- Maintenance Providers:MRO facilities in India and the United States are retrofitting legacy narrow-body fleets, creating aftermarket demand for lightweight replacement panels as airworthiness directives force material upgrades.
- Airlines:Major carriers have centralized interior configuration authority with airframer engineering teams, losing direct specification influence to OEM program offices.
- Contractors:VIP completion centers and specialty modification shops retain fragmented procurement autonomy for business jet and head-of-state conversions.
OEMs anchor volume concentration; maintenance providers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Everett final assembly line and adjacent aerospace corridor anchor Washington State's role in floor panel specification authority. Hamburg's A320 family production complex drives European demand concentration.
United States
Boeing's Renton and Everett facilities specify sandwich-construction panels for 737 and 777 programs. FAA Part 25.853 mandates accelerate thermoset composite adoption across aging narrow-body retrofits. The Wichita, Kansas aerostructure cluster hosts tier-1 bonding operations serving both OEM and aftermarket channels.
Germany
Airbus Hamburg final assembly lines consume aramid-core panels for A320neo family output. EASA CS-25 Appendix F amendments force supply chain requalification toward reduced smoke-density materials. The Bavarian aerospace corridor around Munich concentrates autoclave curing capacity for sandwich-panel fabrication.
France
Toulouse headquarters operations coordinate global panel procurement for A350 and A330 programs. ANSM oversight of aerospace material imports maintains strict qualification protocols for honeycomb core suppliers. The Nantes composite manufacturing cluster specializes in thermoplastic face sheet processing for next-generation cabin systems.
India
Bengaluru and Hyderabad MRO facilities retrofit legacy narrow-body fleets with lightweight replacement panels. DGFT import licensing for aerospace-grade prepregs creates compliance complexity for tier-2 fabricators. The Maharashtra aerospace cluster near Pune is developing bonding capacity to serve domestic airline refurbishment demand.
United Kingdom
Gatwick and Heathrow maintenance bases drive aftermarket panel consumption for British Airways and Virgin Atlantic fleets. CAA flame-resistance standards align with EASA baselines but retain distinct approval pathways. The Midlands aerospace corridor around Birmingham hosts machining operations for metallic core refurbishment.
Commercial Aircraft Floor Panels Market Competitive Environment
Listed leaders compete with private specialists across certification-tier positioning. The vendor base stratifies between full-cabin system integrators and discrete component fabricators. Three archetypes dominate: vertically integrated airframer subsidiaries, honeycomb-core material suppliers, and regional MRO service providers. Consolidation pressure favors backward integration into prepreg manufacturing, while geographic expansion targets India's maintenance growth corridor.
Among US-based conglomerates, Collins Aerospace and Triumph Group exemplify the integrated-systems archetype, anchoring program-level relationships through bundled cabin offerings. Hexcel Corporation represents the materials-tier specialist position, occupying a central role in aramid-fiber honeycomb supply. Safran anchors the European full-service vector, sitting within the tier-1 supplier tier that captures multi-year OEM volume commitments.
| Leading Market Players |
|---|
| The Gill Corporation |
| Collins Aerospace |
| Triumph Group |
| Safran |
| Hexcel Corporation |
| Singapore Technologies Engineering |
| Latecoere |
| EFW GmbH |
| Lufthansa Technik |
| Others |
Value Chain & Pricing Dynamics
Ninety-day honeycomb-core qualification timelines compress supplier switching flexibility and concentrate pricing leverage among incumbent aramid-fiber producers serving Boeing and Airbus programs. This lead-time rigidity locks sandwich-panel fabricators into long-term offtake agreements that dampen spot-market competition.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FAA-EASA dual-certified panels from single-jurisdiction alternatives and uncertified commodity replacements. Certification grade and volume scale drive differentiation, with OEM line-fit contracts commanding substantial premiums over aftermarket retrofits. Cost compression in standard-tier panels is intensifying because epoxy resin feedstock volatility squeezes prepreg manufacturer margins. Maintenance providers exhibit highest price sensitivity as airworthiness directive compliance deadlines force expedited procurement.
Supply Chain Analysis
France and Germany anchor aramid-fiber honeycomb core production for European airframer programs, while the United States concentrates thermoset prepreg manufacturing around aerospace corridors in Washington and Kansas. Sandwich-panel fabrication draws from petrochemical-derived epoxy resins, glass-fiber reinforcements, and phenolic face-sheet substrates. Single-source vulnerability concentrates in qualified aramid-core vendors, creating supply disruption exposure for tier-1 fabricators. Distribution runs through airframer-directed tier-1 supplier networks that bypass independent distributors for program-level volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as airline procurement centralization with OEM engineering teams fragments specification authority away from legacy maintenance relationships. This demand-side shift creates niche openings for specialized integrators and regional MRO service providers.
For Market Incumbents: Fortify backward integration into prepreg manufacturing to capture margin pools currently flowing to Hexcel and specialized resin suppliers. Expand autoclave curing capacity in Germany's Bavarian aerospace corridor to compress qualification timelines for EASA Appendix F requalification cycles. Threats from thermoplastic composite substitutes demand accelerated R&D investment in recyclable face-sheet chemistries. For New Entrants and Emerging Players: Anchor in India's Bengaluru-Hyderabad MRO corridor where DGFT import licensing complexity creates service gaps for domestic retrofit demand. Target aftermarket narrow-body replacement panels as the most penetrable segment, exploiting compressed lead-time requirements that favor regional fabrication over transatlantic supply. Pursue direct contracting with Indian low-cost carriers bypassing OEM specification chokepoints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive aerospace subsidiaries lacking standalone scale. Long-term viability hinges on certification asset durability rather than manufacturing capacity alone. Watch EASA sustainable-aviation regulatory extensions to cabin interiors as the inflection signal forcing early-mover advantage in bio-based material qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prepreg Manufacturing | Captures margin pools from aramid-core suppliers serving Airbus and Boeing programs. |
| Thermoplastic Composite Qualification | Accelerates fabrication cycles for next-generation single-aisle platform specifications. |
| India MRO Corridor Expansion | Positions suppliers for DGFT-licensed domestic retrofit demand from narrow-body fleets. |
| Bio-Based Phenolic Resin Development | Differentiates suppliers as EASA extends sustainable-aviation regulations to cabin interiors. |
| Dual-Certification Fast-Track Program | Compresses time-to-revenue for modified panel designs across FAA and EASA jurisdictions. |
Study Parameters
Operator-level perspectives from airframer procurement directors, tier-1 supplier program managers, MRO facility engineering leads, and composite fabrication technicians anchored the qualitative base. Primary interview findings triangulated against FAA airworthiness directive databases, EASA certification filings, customs trade records for aerospace-grade prepregs, and SEC disclosures from listed aerostructure suppliers. Bottom-up volume estimates from individual program specifications reconciled with top-down market sizing from production forecasts across the analysis window.
Sensitivity analysis tested forecast robustness across alternative scenarios for narrow-body delivery rates, retrofit cycle compression, and regulatory amendment timing. Segmentation dimensions modeled include material certification grade, application load requirement, manufacturing process capital intensity, and end-user technical authority. CAGRs derived from compound growth trajectory analysis of historical program awards and projected fleet expansion. Industry-specific inputs incorporated epoxy resin price indices, honeycomb-core capacity utilization rates, and airworthiness directive issuance cadence.
Material uncertainties — regulatory amendment acceleration, feedstock supply disruption, and airframer insourcing decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline stability and OEM procurement consolidation continuity. Recalibration cycles align with material shifts in EASA Appendix F implementation schedules and sustainable-aviation regulatory scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market